
 Dietary Supplement Cultures Market | 2026-2036
Dietary Supplement Cultures Market Size, Share, and Industry Trends Forecast 2026-2036
Dietary Supplement Cultures Market Outlook
The functional food sector is repositioning culture procurement toward clinically validated strains. DuPont leverages its microbial strain library to anchor supply relationships with North American nutraceutical brands. DSM sustains R&D intensity across human milk oligosaccharide-compatible cultures. Hansen Holding A/S dominates fermentation-derived culture supply for dairy-alternative applications.
Dietary supplement cultures comprise live microorganisms, fermented substrates, or botanical-derived matrices standardized for colony-forming units or bioactive metabolite content, produced via controlled fermentation, lyophilization, or encapsulation processes to preserve viability through shelf life and gastric transit. Probiotics command the largest current volume share, though fermented foods as a culture delivery format is expanding fastest among clean-label formulators. Nutraceuticals application channels capture premium margin pools due to strain-specific health claim substantiation costs.
EFSA QPS lists, FDA GRAS notifications, and FSSAI licensing requirements collectively determine strain approval timelines and cross-border market access for culture suppliers. WHO guidelines on probiotic strain documentation influence national adoptions across multiple jurisdictions. Stakeholders must monitor evolving strain-level transparency mandates and preemptively build clinical evidence dossiers ahead of regulatory harmonization shifts.
Market Dynamics
Strain-level regulatory substantiation requirements under EFSA and FDA frameworks are compressing supplier margins while elevating barriers to entry, forcing culture manufacturers to reallocate R&D budgets toward clinical validation infrastructure.
Growth Catalysts
- EFSA QPS List Expansion:The European Food Safety Authority's qualified presumption of safety updates accelerate novel strain approvals, reducing time-to-market for European culture developers.
- Fermented Foods Category:Clean-label formulators in Germany and the United States are driving demand for live culture matrices as functional delivery vehicles beyond traditional capsule formats.
- Human Milk Oligosaccharide Research:Infant nutrition manufacturers are procuring HMO-compatible cultures, opening premium application channels with substantiated gut-brain axis claims.
Market Restraints
- Fermentation Input Volatility:Yeast extract and peptone prices fluctuate with agricultural commodity cycles, squeezing gross margins for bulk culture producers.
- Lyophilization Energy Costs:European natural gas price instability elevates freeze-drying operational expenses, disadvantaging continental suppliers versus North American competitors.
- Strain Patent Thickets:Dense intellectual property landscapes around Lactobacillus and Bifidobacterium species restrict freedom-to-operate for mid-tier entrants.
Strategic Opportunities
- Chinese Functional Food Market:SAMR's streamlined health food registration pathways enable faster strain-specific claim approvals for compliant foreign suppliers.
- Precision Fermentation Convergence:Integration of synthetic biology tools with traditional culture banking accelerates novel metabolite production for next-generation synbiotics.
- Direct-to-Consumer Microbiome Testing:Personalized nutrition platforms create captive demand for subscription-based culture formulations matched to individual gut profiles.
Industry Challenges
- Clinical Trialist Scarcity:Qualified investigators capable of executing GI endpoint studies for probiotic claims command premium fees, extending dossier development timelines.
- Legacy ERP Integration:Batch record systems designed for chemical manufacturing require costly reconfiguration to accommodate live culture viability tracking and cold chain documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dietary Supplement Cultures Market |
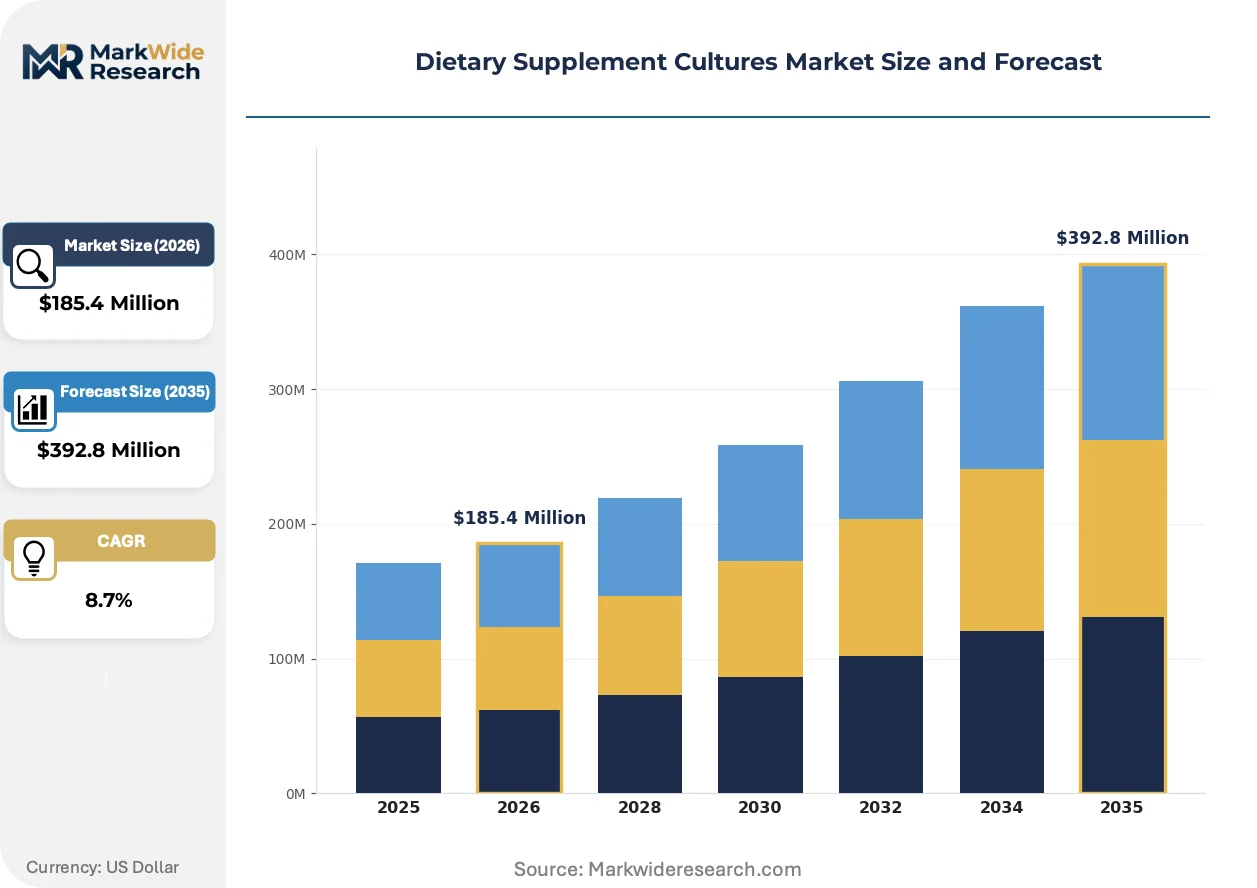
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $392.8 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Fermented Foods, Botanical Extracts Application: Health Supplement, Functional Food, Nutraceuticals, Beverages End User: Individual Consumers, Healthcare Providers, Fitness Industry, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | DuPont, DSM, BioGaia AB, Hansen Holding A/S, Danone, Nestlé, Abbott Laboratories, Synlogic, Bioprox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dietary Supplement Cultures Market Strategic Shifts
Controlled-release encapsulation technologies are displacing standard enteric coatings as the primary mechanism for gastric transit protection, while regulatory transparency mandates force open-access publication of strain genomic data.
Algal-derived prebiotic fibers are expanding into synbiotic formulations as dual-function matrices that simultaneously nourish administered cultures and resident microbiota. Functional beverage manufacturers in Germany and California are adopting these hybrid ingredients at scale. The technology is expanding into dairy-alternative applications where traditional prebiotic fibers compromise mouthfeel and stability.
EFSA's 2023 guidance on post-market surveillance for live cultures mandates systematic adverse event reporting across all member states, elevating pharmacovigilance costs for suppliers. The framework requires strain-specific traceability from fermentation through finished product. Small and mid-sized culture houses are consolidating to amortize compliance infrastructure across larger revenue bases.
Formulators now specify colony-forming unit guarantees at end-of-shelf-life rather than manufacture date, compressing supplier pricing power and forcing process redesign toward enhanced stability engineering. Contract manufacturers in the United States are rejecting batch releases without accelerated aging validation data. This specification tightening is most visible in pediatric and geriatric nutrition segments where efficacy claims carry heightened liability exposure.
Dietary Supplement Cultures Market Segmentation
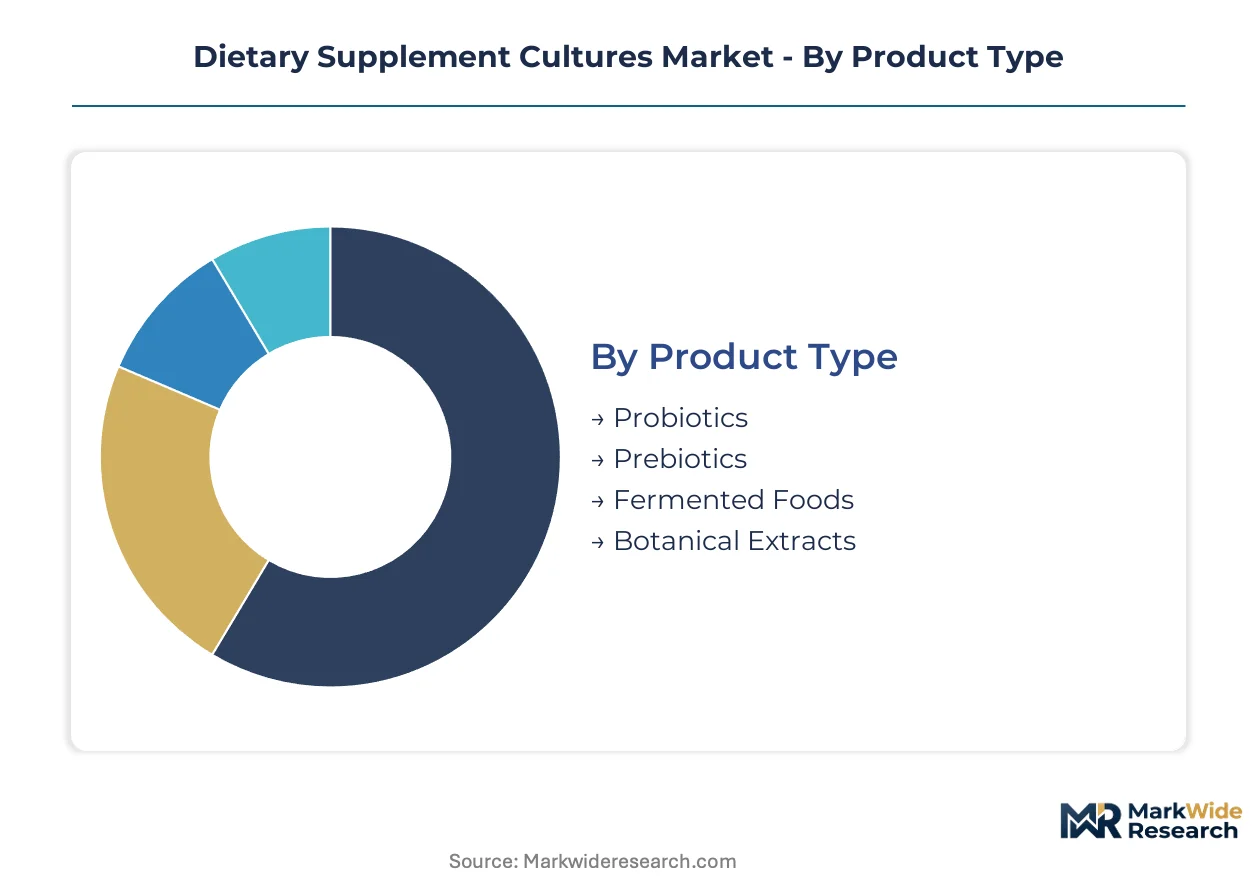
Strain-level substantiation costs and shelf-life stability requirements fragment supplier capabilities across product categories. Application channels diverge sharply between clinical-grade formulations and mass-market functional foods. Distribution infrastructure determines viable market entry points for live culture products requiring cold chain integrity.
Product Type:
Supply concentration clusters around fermentation-derived formats where clinical validation investments amortize across larger production runs.
- Probiotics:Live microbial strains standardized to colony-forming unit counts at end-of-shelf-life, demanding lyophilization expertise and gastric transit protection engineering. Demand concentrates in nutraceuticals channels across Germany and the United States, where EFSA QPS-listed and FDA GRAS-notified strains command formulation preference. Strain patent thickets around Lactobacillus and Bifidobacterium species constrain mid-tier supplier entry.
- Fermented Foods:Live culture matrices delivered through kimchi, kefir, and kombucha formats, prioritizing clean-label positioning over precise CFU quantification. Clean-label formulators in Germany and California are adopting these hybrid ingredients at scale, with dairy-alternative applications expanding fastest as traditional prebiotic fibers compromise mouthfeel in plant-based bases.
- Prebiotics:Non-digestible substrates that selectively nourish beneficial gut microbiota, including inulin, FOS, and GOS compounds.
- Botanical Extracts:Plant-derived matrices standardized for polyphenol or alkaloid content, often combined with live cultures in synbiotic formulations.
Today's leader: Probiotics. Tomorrow's challenger: Fermented Foods.
Application:
Margin structures vary threefold between clinical-grade substantiation requirements and commodity functional food positioning.
- Nutraceuticals:Strain-specific health claim formulations requiring dossier-level clinical evidence for regulatory approval. Premium margin pools reflect EFSA and FDA substantiation costs, with pediatric and geriatric segments carrying heightened liability exposure that forces accelerated aging validation data.
- Functional Food:Culture integration into yogurts, cheeses, and plant-based alternatives where fermentation-derived bioactives replace synthetic additives. German manufacturers lead procurement of HMO-compatible cultures for infant nutrition gut-brain axis claims.
- Health Supplement:Capsule, tablet, and powder formats emphasizing convenience and precise dosing for individual consumers.
- Beverages:Shelf-stable liquid delivery vehicles requiring advanced encapsulation for culture viability through pasteurization and ambient distribution.
Nutraceuticals command premium positioning; Functional Food is climbing the fastest.
End User:
Procurement authority separates institutional specification from discretionary retail purchase patterns.
- Food Manufacturers:Industrial-scale culture procurement for fermented product lines and dairy-alternative formulations, specifying batch consistency and strain traceability from fermentation through finished goods.
- Healthcare Providers:Clinical recommendation of strain-specific formulations for gastrointestinal, immunological, and metabolic endpoints, requiring published trial data and adverse event surveillance compliance.
- Individual Consumers:Direct purchase driven by microbiome testing results, subscription personalization, and influencer-endorsed wellness positioning.
- Fitness Industry:Performance-oriented formulations targeting recovery, protein synthesis, and body composition optimization.
Food Manufacturers dominate volume; Healthcare Providers are gaining share fastest.
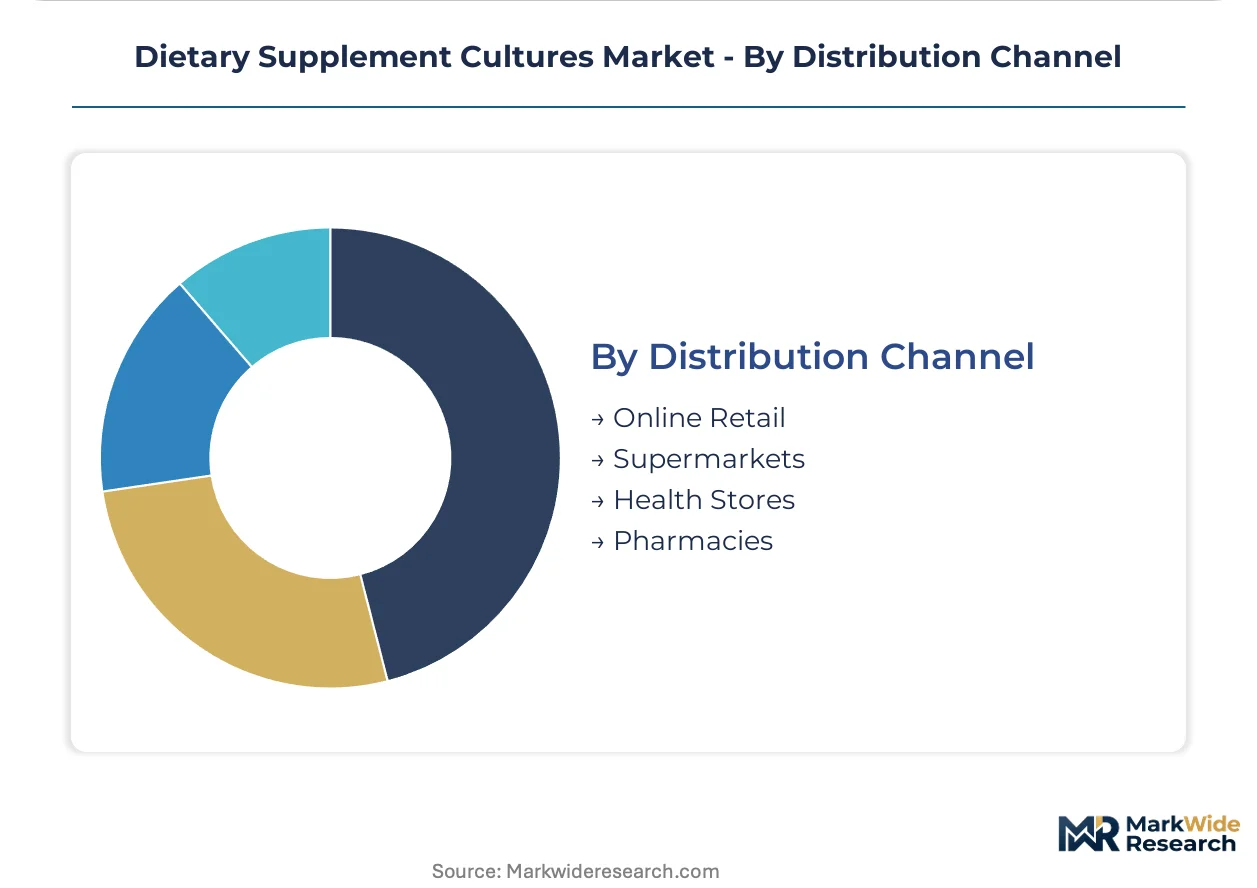
Distribution Channel:
Cold chain capabilities and regulatory licensing requirements stratify channel access for live culture products.
- Pharmacies:Licensed retail requiring strain-specific health claim approvals and pharmacovigilance infrastructure, advantaging suppliers with EFSA QPS-listed or FDA GRAS-notified portfolios.
- Online Retail:Direct-to-consumer platforms enabling subscription-based personalized formulations matched to individual gut profiles, with accelerated growth in precision fermentation-derived synbiotics.
- Health Stores:Specialty retail emphasizing organic certification, non-GMO verification, and practitioner-grade potency claims.
- Supermarkets:Mass-market distribution of fermented foods and functional beverages with shorter shelf-life requirements and price-sensitive positioning.
Pharmacies anchor premium positioning; Online Retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as suppliers migrate toward jurisdictions with streamlined strain-approval pathways and lower compliance-cost structures. Manufacturers now site fermentation capacity where EFSA QPS alignment or FDA GRAS notification timelines compress time-to-revenue.
United States
FDA GRAS notification pathways attract culture developers seeking rapid market access for novel strains. The agency's 2023 updated guidance on live microbial ingredients clarifies substantiation requirements for infant nutrition applications. Greater Boston hosts precision fermentation clusters where synthetic biology tools integrate with traditional culture banking for next-generation synbiotics.
Germany
EFSA QPS-listed strains command formulation preference among domestic nutraceutical brands targeting pharmacy distribution. The country's Federal Office of Consumer Protection and Food Safety enforces strain-level traceability mandates that exceed baseline EU requirements. Bavaria's dairy-alternative manufacturing corridor procures HMO-compatible cultures for gut-brain axis positioning in infant formula.
China
SAMR's streamlined health food registration enables faster strain-specific claim approvals for compliant foreign suppliers. The regulator's 2024 draft guidelines on probiotic labeling intensify documentation requirements for CFU guarantees at end-of-shelf-life. Yangtze River Delta formulators scale fermented food production for domestic clean-label demand and export markets.
India
FSSAI licensing requirements for live culture imports create captive demand for domestic fermentation capacity expansion. The regulator's 2023 harmonization with Codex Alimentarius standards accelerates approval timelines for QPS-aligned strains. Maharashtra's nutraceutical manufacturing belt attracts contract culture production for regional functional food brands.
Switzerland
Swissmedic's pharmaceutical-grade manufacturing standards position the jurisdiction for clinical-grade culture exports. The regulator's alignment with EMA quality guidelines enables seamless EU market access for certified suppliers. Basel's life sciences cluster houses fermentation infrastructure serving both nutraceutical and prescription probiotic developers.
Dietary Supplement Cultures Market Competitive Environment
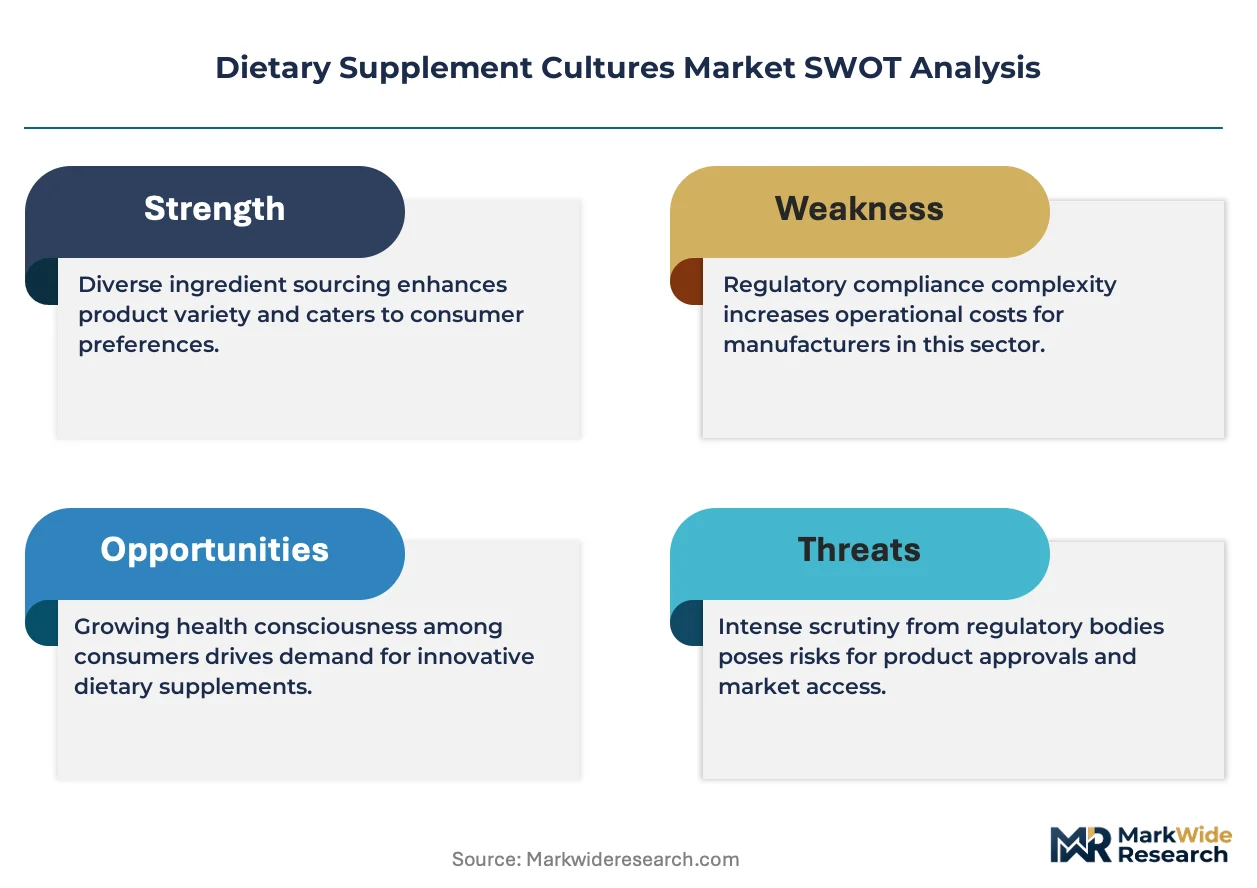
Branded specialists and contract manufacturers split share differently across segments, with strain-ownership advantages concentrating in premium nutraceutical channels while toll-manufacturing capacity dominates fermented food supply. The supplier base exhibits tiered structure: multinational culture libraries with clinical-validation infrastructure occupy top tier; mid-tier regional fermenters compete on cost and speed; boutique strain developers target personalized nutrition niches. Two strategic archetypes predominate: integrated fermentation-to-finished-goods operators and pure-play culture banks licensing strain IP. Competitive moves center on M&A to acquire genomic strain assets and capacity expansion into precision fermentation platforms.
Within the integrated fermentation tier, DuPont and DSM occupy positions exemplifying multinational scale advantages in clinical validation infrastructure. Hansen Holding A/S anchors the specialized culture bank archetype, representing suppliers focused on fermentation-derived matrices for dairy-alternative applications. These three entities collectively illustrate how R&D intensity and regulatory dossier depth stratify competitive positioning across EFSA-aligned and FDA-notified market access pathways.
| Leading Market Players |
|---|
| DuPont |
| DSM |
| BioGaia AB |
| Hansen Holding A/S |
| Danone |
| Nestlé |
| Abbott Laboratories |
| Synlogic |
| Bioprox |
| Others |
Value Chain & Pricing Dynamics
Captive fermentation infrastructure in Germany and the United States anchors supplier pricing power by internalizing lyophilization capacity and strain-banking capabilities, insulating integrated operators from European energy cost volatility while forcing toll-dependent competitors into margin compression.
Pricing Analysis
Distributor margin layering separates pharmacy-grade strain formulations from mass-market fermented food channels, with EFSA QPS-listed and FDA GRAS-notified strains commanding premium-mid-economy pricing differentiation based on dossier depth and clinical validation tier. Price differentiation hinges on certification level and volume scale, with pediatric and geriatric segments showing least price sensitivity due to liability exposure. Pricing pressure stems from end-of-shelf-life CFU guarantee specifications forcing accelerated aging investments. Direct-to-consumer platforms exhibit highest price sensitivity as subscription models compete on per-dose accessibility.
Supply Chain Analysis
Workforce availability for qualified fermentation technicians concentrates in Bavaria, Greater Boston, and the Yangtze River Delta, where technical training pipelines and precision biology clusters sustain operational scale. Geographic supply concentration clusters in Germany, China, and the United States as formulation hubs expand. Raw material dependencies center on yeast extract, peptone substrates, and algal-derived prebiotic fibers. Single-source vulnerability around proprietary strain libraries threatens mid-tier suppliers. Distribution runs through cold-chain logistics networks requiring validated thermal packaging for live culture viability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where SAMR's streamlined health food registration in China offers faster strain-specific claim approvals than EFSA's extended QPS timelines, compressing time-to-revenue for compliant foreign suppliers.
For Market Incumbents: Anchor market position by acquiring genomic strain assets from boutique developers facing patent thicket barriers, and expand precision fermentation capacity in North America to exploit European natural gas cost disadvantages. Consolidation amortizes pharmacovigilance infrastructure across larger revenue bases as EFSA post-market surveillance mandates intensify. For New Entrants and Emerging Players: Enter via the fermented foods category where clean-label positioning tolerates lower clinical substantiation burdens than nutraceutical channels, targeting German and California formulators scaling dairy-alternative applications. Precision fermentation convergence offers white-space entry for synthetic biology-enabled metabolite production. For Investors and Strategic Acquirers: Consolidation pressure builds where clinical trialist scarcity extends dossier development timelines and small culture houses lack compliance infrastructure. Long-term viability favors targets with EFSA-aligned or FDA-notified strain portfolios and captive lyophilization capacity. Watch SAMR's final probiotic labeling guidelines as inflection signal for Chinese market access windows.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Patent Acquisition | Genomic asset purchases from boutique developers unlock freedom-to-operate in Lactobacillus and Bifidobacterium species. |
| Precision Fermentation Scale-Up | Synthetic biology integration in Greater Boston clusters accelerates novel metabolite production for next-generation synbiotics. |
| EFSA QPS Alignment Investment | Clinical validation infrastructure compresses approval timelines for European pharmacy distribution access. |
| Cold Chain Partnership | Validated thermal packaging agreements secure live culture viability through ambient distribution channels. |
| HMO-Compatible Culture Development | Infant nutrition positioning in Bavaria's dairy-alternative corridor captures gut-brain axis premium segments. |
Study Parameters
Coverage spans Germany, China, the United States, India, and Switzerland, with primary inputs from each jurisdiction combining interviews with fermentation operations directors, regulatory affairs specialists at culture houses, pharmacy procurement managers, and functional food formulators. Secondary validation draws from EFSA QPS list updates, FDA GRAS notifications, SAMR health food registration databases, and FSSAI licensing records. Bottom-up strain-level production estimates triangulate against top-down application channel demand assessments.
Granularity-level modeling disaggregates volume and value across product type, application, end user, and distribution channel dimensions, with regional regulatory cluster and strain certification tier as cross-cutting variables. CAGRs derive from segment-level growth rate reconciliation against macro drivers including clean-label adoption curves and precision fermentation technology maturation. Forecast inputs incorporate lyophilization energy cost trajectories and clinical trialist availability indices.
Inputs from EFSA, FDA, and SAMR regulatory filings were available through the study window; gaps in real-time strain-specific adverse event surveillance data introduce uncertainty bands around pharmacovigilance cost projections. Forecasts reflect assumptions regarding regulatory harmonization pace and fermentation input price stability. Material deviation in European natural gas pricing or SAMR guideline finalization timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Red Ginseng Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
North America Omega-3 Products Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Brain Health Supplement Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Complete Nutrition Products Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Omega-3 Products Market
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
South Africa Collagen Peptides Market
Nutritional Supplements
Microalgae DHA Market