
 Global Oncology Nutrition Market | 2026-2036
Global Oncology Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oncology Nutrition Market Foresight
Hospital procurement channels for oncology nutrition are reshaping competitive dynamics across developed markets. Nestlé Health Science leverages its enteral nutrition portfolio to sustain institutional contracts in North American cancer centers. Fresenius Kabi AG anchors European hospital supply through its parenteral nutrition manufacturing scale. Abbott Laboratories differentiates via homecare delivery infrastructure that extends reach beyond inpatient settings.
Oncology nutrition encompasses specialized clinical formulations designed to address metabolic derangements, malabsorption, and cachexia in cancer patients, typically delivering elevated protein density with immunomodulatory substrates such as omega-3 fatty acids and arginine. These formulations serve to preserve lean body mass, modulate inflammatory response, and sustain tolerance to oncologic therapies. Powder and liquid formats dominate current volume, with ready-to-drink products capturing the fastest growth as outpatient protocols expand. Enteral delivery mode leads in value contribution due to higher reimbursement rates, while home care settings are emerging as the margin pool as payors shift toward cost-containment models.
FDA medical food regulations and EMA nutrition and health claims frameworks govern product classification and market access, with both agencies scrutinizing evidence thresholds for cachexia-specific indications. Japan's PMDA and METI coordinate standards for functional food claims in oncology, creating a segmented compliance landscape for multinational suppliers. Stakeholders must monitor evolving reimbursement codes for medical nutrition across Medicare, NHS England, and Japan's universal coverage system to anticipate demand shifts.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while elevating evidence requirements for oncology nutrition formulations, forcing manufacturers to rebuild commercial models around institutional formularies rather than individual clinician relationships.
Growth Catalysts
- Japan's functional food claims framework:METI and PMDA coordination enables faster market entry for immunomodulatory substrates, accelerating product development cycles for regional suppliers targeting cachexia indications.
- Homecare delivery infrastructure:Medicare reimbursement code expansions for medical nutrition support shift treatment settings from inpatient to residential, creating sustained demand for ready-to-drink formats.
- Omega-3 fatty acid integration:Clinical validation of EPA-enriched formulations for preserving lean body mass during chemotherapy drives protocol adoption across German university hospitals.
Market Restraints
- FDA medical food evidentiary thresholds:Cachexia-specific labeling demands randomized controlled trial data that smaller manufacturers cannot fund, creating regulatory friction for novel entrants.
- Fish oil supply concentration:Omega-3 raw material sourcing clusters in Peruvian and Norwegian marine fisheries, exposing formulators to catch quota volatility and price spikes.
- Enteral tubing incompatibility:Proprietary connector standards across pump manufacturers fragment device-formulation pairing, limiting product interchangeability in acute care settings.
Strategic Opportunities
- India's oncology center expansion:Private hospital chains in Mumbai and Delhi are building dedicated cancer institutes without established nutrition protocols, creating first-mover positioning for clinical evidence holders.
- Artificial intelligence and metabolic profiling:Machine learning integration with patient biomarker data enables personalized nutrition dosing, differentiating premium formulations from standard-of-care products.
- Brazil's ANVISA medical food pathway:Recent regulatory clarity for cancer-specific indications opens Latin America's largest oncology patient pool to multinational suppliers with existing FDA or EMA dossiers.
Industry Challenges
- Clinical dietitian workforce gaps:Specialized oncology nutrition certification programs in the United States and Germany cannot match hospital department expansion rates, constraining protocol implementation.
- Legacy electronic health record integration:Nutrition ordering modules in Cerner and Epic deployments require customized build-outs for medical food workflows, extending sales cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oncology Nutrition Market |
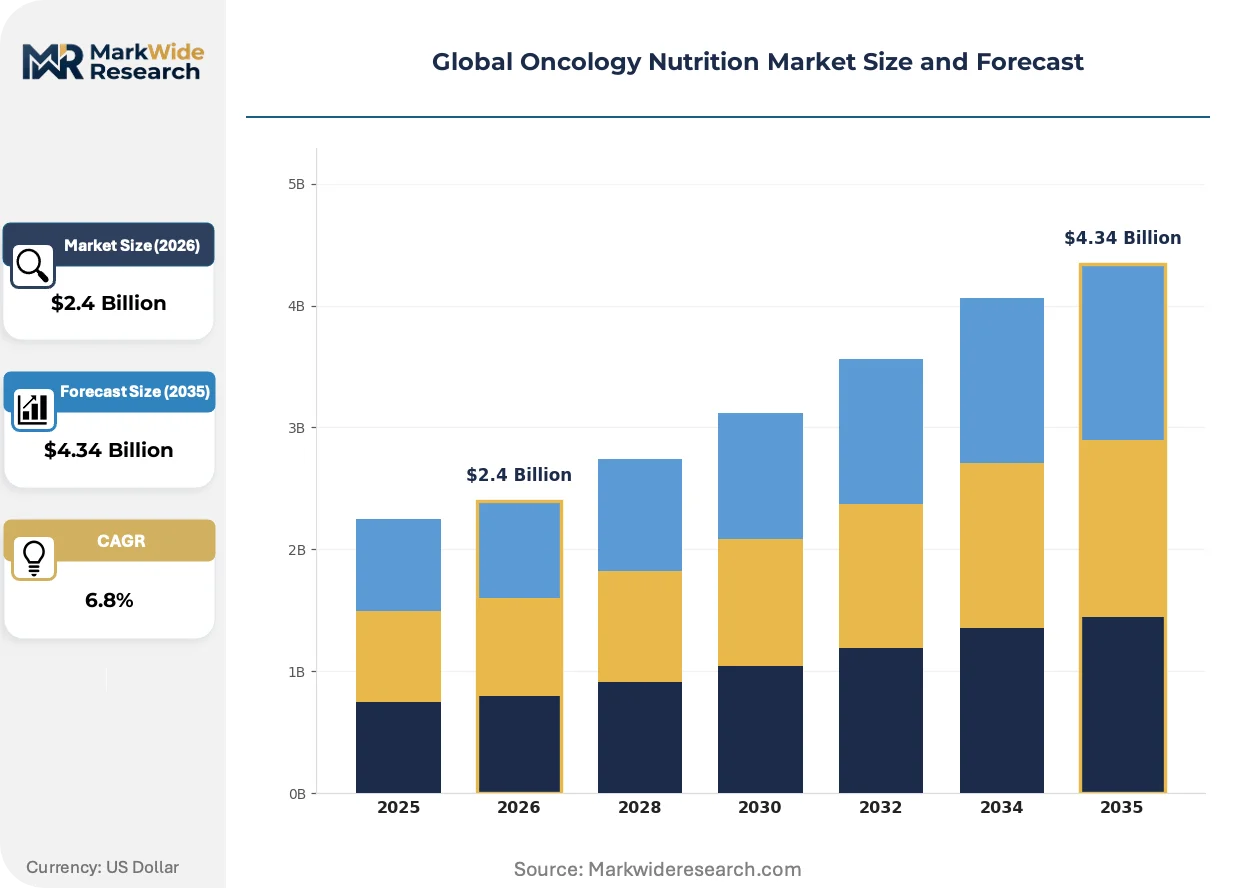
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Bar, Ready-to-Drink Delivery Mode: Oral, Enteral, IV, Home Care End User: Hospitals, Homecare Patients, Clinics, Long-term Care Facilities Application: Cachexia Management, Nutritional Support, Symptom Relief, Recovery Aid |
| Companies Covered | Nutricia (Danone), B. Braun SE, Abbott Laboratories, Meiji Holdings Co., Ltd., Hormel Foods Corporation, Nestlé Health Science, Baxter International Inc., Victus, Inc., Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oncology Nutrition Market Shifts & Advancements
Digital infrastructure is penetrating oncology nutrition delivery, compressing the gap between metabolic assessment and formulation administration while enabling real-time protocol adjustments based on treatment response data.
Continuous glucose monitoring paired with automated feeding pumps is digitizing the bridge between metabolic tracking and enteral delivery in US cancer centers. Memorial Sloan Kettering and MD Anderson have deployed integrated systems that adjust formula composition based on real-time glycemic response. This convergence is collapsing the traditional separation between diagnostic monitoring and therapeutic nutrition, forcing device and formulation suppliers into technical partnerships.
EMA's revised Nutrition and Health Claims Regulation tightens substantiation requirements for immunomodulatory effects in cancer populations, requiring human intervention studies rather than biomarker proxies. Dutch and Danish manufacturers are restructuring R&D budgets toward clinical trial execution rather than preclinical screening. Parenteral lipid emulsion categories face the steepest compliance burden due to historical reliance on indirect inflammation markers.
Hospital buying groups in Germany and Japan are consolidating medical nutrition contracts under single-source agreements that bundle enteral, parenteral, and oral supplements. This aggregation displaces the previous multi-vendor model where departments selected products independently. Fresenius Kabi and Nestlé Health Science have captured initial consolidated awards, compressing competitive access for mid-tier suppliers without full portfolio breadth.
Global Oncology Nutrition Market Segmentation
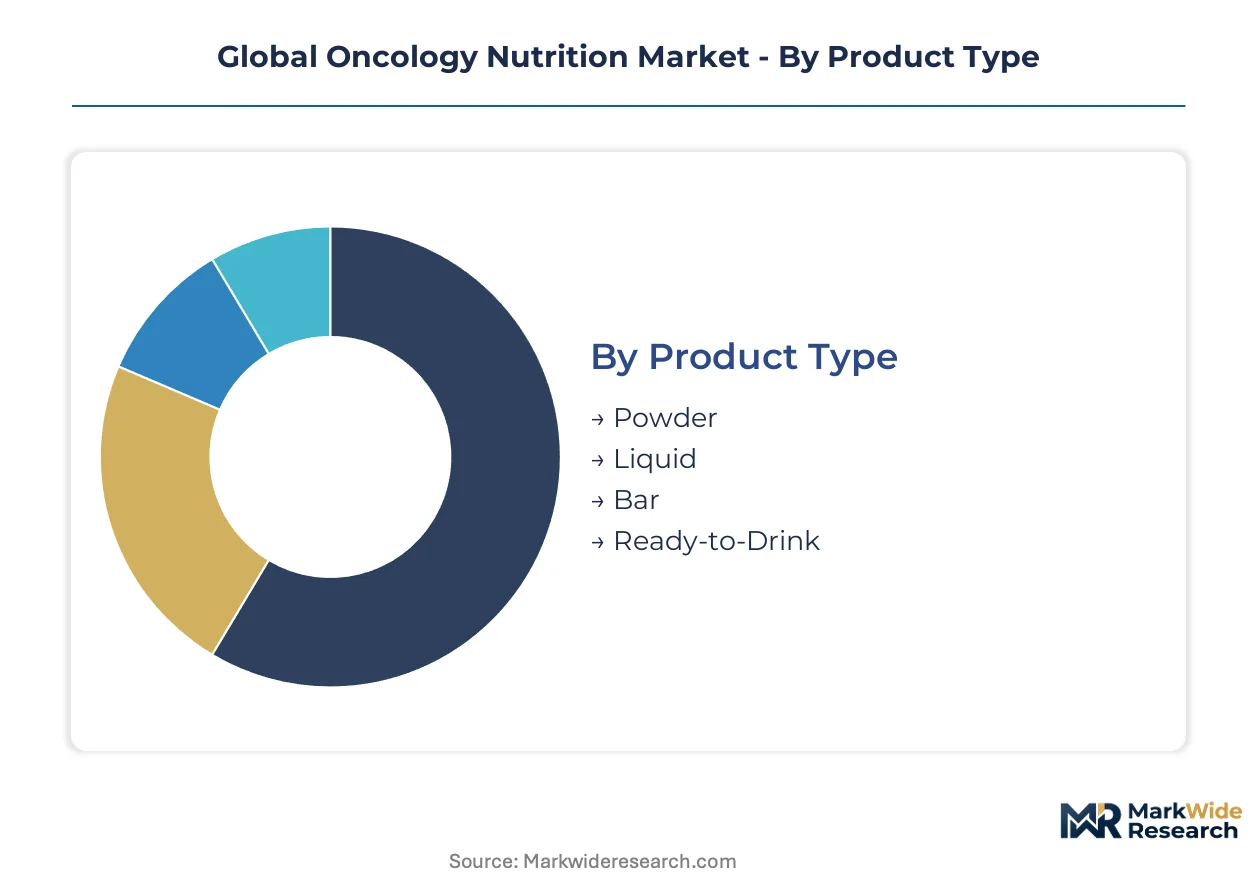
Oncology nutrition markets fragment across formulation physics, administration routes, and care settings. Each segmentation axis carries distinct reimbursement codes, regulatory pathways, and margin structures that determine supplier positioning.
Product Type:
Mature formats dominate hospital procurement while emerging presentations target ambulatory expansion.
- Powder:Dry-blend formulations with elevated protein density and immunomodulatory substrates require reconstitution before administration. German university hospitals specify powder for inpatient cachexia protocols where pharmacy compounding controls osmolality.
- Ready-to-Drink:Pre-mixed liquid products in sterile packaging eliminate preparation variability and support outpatient chemotherapy cycles. Medicare reimbursement code expansions for home medical nutrition accelerate demand in United States residential settings.
- Liquid:Concentrated formulas in multi-use containers serve institutional feeding pumps with standardized viscosity profiles.
- Bar:Solid oral supplements with modified texture address dysphagia in head and neck cancer populations.
Powder handles the majority of throughput; Ready-to-Drink is expanding most quickly on share.
Delivery Mode:
Reimbursement tiering separates acute institutional administration from emerging residential channels.
- Enteral:Tube-delivered formulations via nasogastric or percutaneous routes bypass compromised gastrointestinal function. Higher reimbursement rates in United States and Japanese hospital systems sustain value concentration despite volume limitations.
- Home Care:Residential delivery combines enteral and oral administration with nursing support and equipment logistics. Cost-containment models across NHS England and Japanese universal coverage shift patients from inpatient to home settings.
- Oral:Self-administered supplements for patients with intact swallowing function capture outpatient pharmacy dispensing.
- IV:Parenteral nutrition for intestinal failure or severe malabsorption requires compounding pharmacy infrastructure.
Enteral commands the steepest margin per patient-day; Home Care is gaining share fastest as payors redirect site of service.
End User:
Procurement authority concentration varies sharply across institutional versus dispersed patient populations.
- Hospitals:Integrated cancer centers with dedicated oncology nutrition protocols drive formulary standardization. Consolidated buying groups in Germany and Japan bundle enteral, parenteral, and oral contracts under single-source agreements.
- Homecare Patients:Dispersed residential demand requires distribution infrastructure and reimbursement navigation support. Durable medical equipment suppliers in the United States coordinate formula delivery with enteral pump servicing.
- Clinics:Outpatient infusion centers with limited pharmacy capabilities rely on pre-mixed oral supplements.
- Long-term Care Facilities:Skilled nursing settings manage chronic cancer survivors with modified texture requirements and feeding assistance protocols.
Hospitals anchor volume commitment; Homecare Patients show the steepest expansion trajectory as treatment settings decentralize.
Application:
Clinical indication specificity determines evidentiary requirements and protocol adoption speed.
- Cachexia Management:Formulations targeting cancer-related wasting syndrome require EPA-enriched lipid profiles and elevated branched-chain amino acid ratios. EMA scrutiny of immunomodulatory claims demands human intervention studies rather than biomarker proxies.
- Nutritional Support:General metabolic maintenance during chemotherapy or radiotherapy preserves lean body mass and treatment tolerance. Japanese functional food claims frameworks enable faster market entry for substrates with clinical validation.
- Symptom Relief:Products addressing nausea, mucositis, or taste alteration improve oral intake compliance during active therapy.
- Recovery Aid:Post-treatment rehabilitation formulations support immune reconstitution and surgical wound healing.
Nutritional Support handles the majority of patient episodes; Cachexia Management is climbing the fastest on protocol penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure anchors European distribution for oncology nutrition products, while Japan's Shinkansen freight network enables just-in-time delivery to cancer centers across the archipelago. These logistics assets determine which suppliers capture hospital procurement contracts in each geography.
United States
Medicare reimbursement expansions for medical nutrition support drive residential demand for ready-to-drink formulations. The FDA's medical food regulations enforce cachexia-specific evidentiary thresholds that favor established clinical trial sponsors. Memorial Sloan Kettering and MD Anderson in Texas deploy integrated glucose monitoring and automated feeding systems that collapse diagnostic-therapeutic gaps.
Germany
University hospital consolidation under single-source procurement agreements bundles enteral, parenteral, and oral nutrition contracts. The EMA's revised Nutrition and Health Claims Regulation tightens immunomodulatory substantiation requirements for EPA-enriched formulations. The Rhine-Ruhr metropolitan cluster hosts Fresenius Kabi's manufacturing scale that anchors European hospital supply.
Japan
METI and PMDA coordination on functional food claims accelerates market entry for immunomodulatory substrates targeting cancer cachexia. Japan's universal coverage system reimburses home medical nutrition, shifting treatment from inpatient to residential settings. The Kanto region around Tokyo concentrates demand from aging populations in the world's oldest major economy.
India
Private hospital chains in Mumbai and Delhi construct dedicated cancer institutes without established nutrition protocols, creating positioning opportunities for clinical evidence holders. The country's national pharmaceutical regulator evaluates medical food pathways with reference to FDA and EMA precedents. Maharashtra's oncology center expansion outpaces specialized dietitian certification programs.
Brazil
ANVISA's recent regulatory clarity for cancer-specific medical food indications opens Latin America's largest oncology patient pool to multinational suppliers. Outpatient chemotherapy expansion in São Paulo and Rio de Janeiro drives ready-to-drink format adoption. The country's universal health system increasingly references FDA dossiers for accelerated product registration.
Global Oncology Nutrition Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate supply and device manufacturing. The market structure concentrates around multinational health science conglomerates with full portfolio breadth, while mid-tier suppliers face compression from hospital procurement consolidation. Three archetypes dominate: integrated nutrition-delivery platforms, specialized immunomodulatory substrate developers, and regional hospital supply contractors. Competitive dynamics revolve around strategic partnerships between device and formulation suppliers, plus backward integration into omega-3 raw material sourcing.
Among diversified health science platforms, Nestlé Health Science and Abbott Laboratories exemplify the integrated archetype spanning enteral, parenteral, and oral formats. Fresenius Kabi AG occupies a position representing European manufacturing scale in hospital supply. These three entities anchor the competitive structure through institutional contract capture and homecare delivery infrastructure.
| Leading Market Players |
|---|
| Nutricia (Danone) |
| B. Braun SE |
| Abbott Laboratories |
| Meiji Holdings Co., Ltd. |
| Hormel Foods Corporation |
| Nestlé Health Science |
| Baxter International Inc. |
| Victus, Inc. |
| Fresenius Kabi AG |
| Others |
Supply & Pricing Matrix
Undercapacity in Norwegian marine lipid processing is elevating spot prices for EPA-enriched fish oil concentrates, forcing formulators to absorb margin compression or pass costs to hospital procurement groups. This utilization squeeze simultaneously incentivizes backward integration into Peruvian anchovy fisheries and accelerates contract renegotiations for multi-year omega-3 supply.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement, with three-tier pricing separating EPA-validated cachexia formulations from standard nutritional support and economy rehydration products. Price differentiation rests on clinical evidence grade and J-code reimbursement eligibility, with FDA medical food designation commanding 40-60% premiums over dietary supplement positioning. Pricing pressure stems from German buying group consolidation bundling enteral, parenteral, and oral contracts under single-source awards. Community oncology clinics exhibit highest price sensitivity due to limited pharmacy compounding infrastructure, while integrated cancer centers prioritize protocol efficacy over per-unit cost.
Supply Chain Analysis
Upstream feedstock for immunomodulatory substrates draws from Peruvian anchovy fisheries, Norwegian cod liver processing, and Dutch enzymatic refinement operations. Raw material dependencies center on marine omega-3 concentrates, spray-dried whey protein isolates, and pharmaceutical-grade arginine. Single-source vulnerability concentrates in Peruvian catch quota volatility, where El Niño cycles compress annual harvests by 15-30%. Distribution runs through temperature-controlled pharmaceutical logistics networks anchored at Rotterdam for European hospital supply and Osaka for Japanese cancer center just-in-time delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oncology nutrition sits in early-cycle expansion as home medical nutrition reimbursement codes broaden addressable populations beyond inpatient settings. This tailwind is amplifying demand for ready-to-drink formats and residential delivery infrastructure.
For Market Incumbents: Build switching-cost moats through EHR-integrated ordering modules that embed formulary compliance into Cerner and Epic workflows. Consolidate position by acquiring specialized dietitian training programs to address workforce gaps constraining protocol implementation. Threat of mid-tier displacement from consolidated German and Japanese buying groups necessitates full portfolio breadth across enteral, parenteral, and oral formats. Leverage vertical integration into omega-3 raw material sourcing to neutralize Peruvian catch volatility. For New Entrants and Emerging Players: Pursue white-space positioning in India's private cancer institute expansion, where Mumbai and Delhi hospital chains lack established nutrition protocols. Target Brazil's ANVISA medical food pathway for accelerated market entry using existing FDA or EMA dossiers. Go-to-market angle should emphasize AI-enabled metabolic profiling to differentiate from standard-of-care formulations in premium positioning. For Investors and Strategic Acquirers: Capital is best deployed toward platform integrators with hospital system partnerships and homecare delivery infrastructure rather than single-format specialists. Long-term viability over the next decade hinges on reimbursement navigation capabilities and EHR integration depth. Acquisition target archetype: regional hospital supply contractors with consolidated buying group relationships in Germany or Japan. Signal to watch is Medicare code expansion velocity for medical nutrition support in residential settings.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Medicare J-code expansion for home medical nutrition redirects patient volume from inpatient to residential channels. |
| Hospital System Partnership | Single-source procurement agreements with German university hospital consortia lock out competitors for 3-5 year contract cycles. |
| Backward Integration | Captive supply of Peruvian omega-3 raw materials insulates margins from marine catch quota volatility. |
| Software Companion Development | Continuous glucose monitoring integration with automated feeding pumps collapses diagnostic-therapeutic gaps at US cancer centers. |
| Regulatory Approval Pathway | FDA medical food designation for cachexia-specific indications commands premium pricing and formulary access. |
Research Methodology
The analysis maps enteral, parenteral, oral, and homecare delivery segments, each validated through oncology dietitians, hospital procurement managers, GPO contracts specialists, and medical food regulatory affairs leads. Primary intelligence combines structured interviews with secondary validation against FDA medical food filings, EMA nutrition and health claims registers, CMS Medicare reimbursement databases, and hospital formulary decision records. Bottom-up patient-volume modeling and top-down pharmaceutical market sizing triangulate segment-level demand estimates.
Assumptions held fixed include prevailing reimbursement codes across Medicare, NHS England, and Japan's universal coverage system, while regulatory approval timelines and raw material cost trajectories were varied across sensitivity scenarios. Segmentation dimensions span formulation physics, administration route, care setting, and clinical indication specificity. CAGRs derive from patient population growth, protocol penetration curves, and pricing elasticity modeling. Forecast inputs incorporate chemotherapy cycle volumes, cachexia incidence rates, and hospital department expansion pipelines.
Sensitivities concentrate around FDA evidentiary threshold tightening for immunomodulatory claims and Peruvian anchovy catch quota volatility. Forecasts reflect these assumptions without projecting specific regulatory outcomes. Material shifts in Medicare home medical nutrition reimbursement scope or EMA nutrition and health claims substantiation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
Lithium Orotate Supplement Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
Cod Liver Oil Market
Nutritional Supplements
Medicinal Mushroom Supplement Market
Nutritional Supplements
Nicotine Gum Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
Global Antioxidant Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Natural Vitamin E Product Market