
 Global Soluble Dietary Fibers Market | 2026-2036
Global Soluble Dietary Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soluble Dietary Fibers Market Intelligence
Subscription-based formulation support and ongoing technical advisory services are rebalancing how soluble dietary fiber suppliers capture long-term value beyond commodity ingredient sales. Cargill, Incorporated leverages its integrated agricultural supply chain to secure cost-advantaged raw material positions across multiple fiber categories. Tate & Lyle PLC anchors its competitive stance through deep specialization in specialty starches and fibers for beverage applications. Roquette Frères differentiates via leadership in pea-derived and plant-based fiber solutions aligned with European formulation trends.
Soluble dietary fibers encompass non-starch polysaccharides and oligosaccharides that dissolve in water to form viscous gels or fermentable substrates, typically comprising glucose, fructose, or galactose units linked by beta-bonds resistant to human digestive enzymes. These compounds function primarily as bulking agents, prebiotics, and viscosity modifiers in processed foods, beverages, and nutraceutical matrices. Inulin commands the largest volume position among product types due to its established use in dairy alternatives and baked goods, though beta-glucan from oat and barley sources is gaining fastest traction among cardiovascular health-positioned applications. Functional foods and dietary supplements represent the most margin-attractive application channels, while animal nutrition constitutes an emerging demand pocket with distinct formulation requirements.
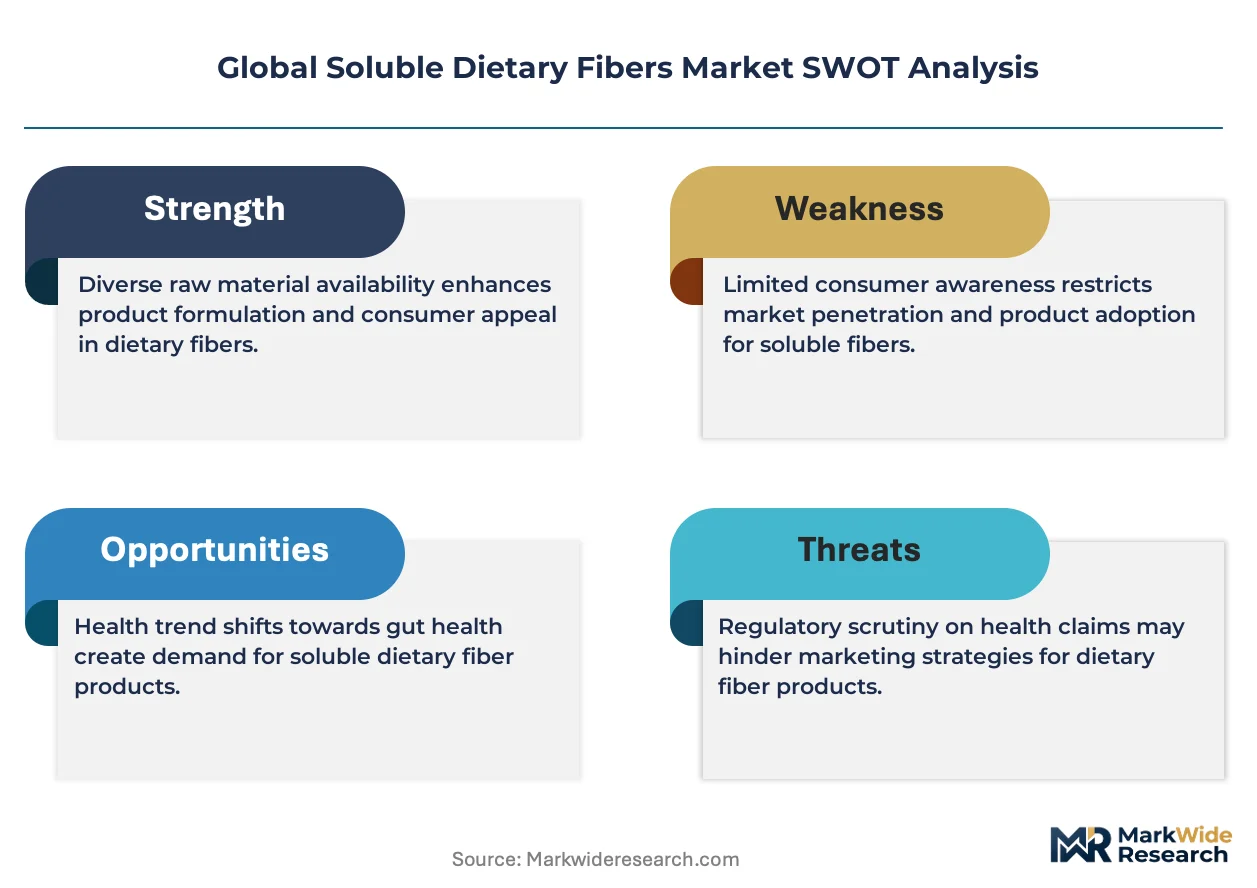
The FDA fiber definition framework and corresponding Nutrition Facts label requirements in the United States dictate which isolated or synthetic fibers qualify for declared fiber content, directly influencing R&D prioritization and product qualification timelines. EFSA health claim authorization pathways in Europe impose additional substantiation burdens for digestive and glycemic response positioning, favoring suppliers with established clinical dossiers. Manufacturers must monitor evolving regulator positions on novel fiber sources and fermentable carbohydrate classifications to anticipate reformulation mandates and preemptive portfolio adjustments.
Market Dynamics
The FDA's evolving fiber definition framework is compressing qualification timelines and forcing suppliers to rebuild clinical dossiers around isolated and synthetic fiber categories. This regulatory recalibration is redistributing competitive advantage toward integrated agricultural processors with captive R&D infrastructure.
Growth Catalysts
- Clean-label reformulation mandates:Processed food manufacturers in the United States are accelerating soluble fiber incorporation to replace modified starches and synthetic hydrocolloids in dairy alternatives and baked goods.
- EFSA digestive health claim pathways:European suppliers with established clinical substantiation dossiers are capturing premium positioning in glycemic response and prebiotic applications.
- Pea protein co-product valorization:Roquette Frères and European processors are extracting soluble fiber from starch processing sidestreams, reducing unit costs for plant-based fiber solutions.
Market Restraints
- Chicory root supply concentration:Inulin production depends on Belgian and Dutch agricultural zones, exposing processors to weather-induced raw material volatility and contract pricing spikes.
- FDA fiber definition exclusion risk:Novel isolated fibers from algae or fungal sources face uncertain qualification under evolving Nutrition Facts label rules, delaying commercialization timelines.
- Beta-glucan extraction yield ceilings:Oat and barley processing technologies max out at 60-70% beta-glucan recovery, constraining volume economics for cardiovascular health-positioned applications.
Strategic Opportunities
- Brazilian functional food underpenetration:ANVISA regulatory harmonization with Codex standards is opening formulation pathways for prebiotic fibers in fortified beverages and infant nutrition.
- Precision fermentation fiber synthesis:Microbial production of rare oligosaccharides is converging with enzymatic modification platforms to create novel prebiotic structures beyond conventional plant sources.
- Subscription technical advisory services:Ingredient suppliers are capturing recurring revenue through ongoing formulation support contracts that extend beyond commodity ingredient transactions.
Industry Challenges
- Clinical trial capacity constraints:EFSA health claim substantiation requires human intervention studies that strain European CRO availability and extend dossier preparation to 24-36 months.
- Legacy equipment retrofit requirements:Soluble fiber incorporation demands viscosity-controlled mixing and heat-stable processing lines that conflict with existing hydrocolloid infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soluble Dietary Fibers Market |
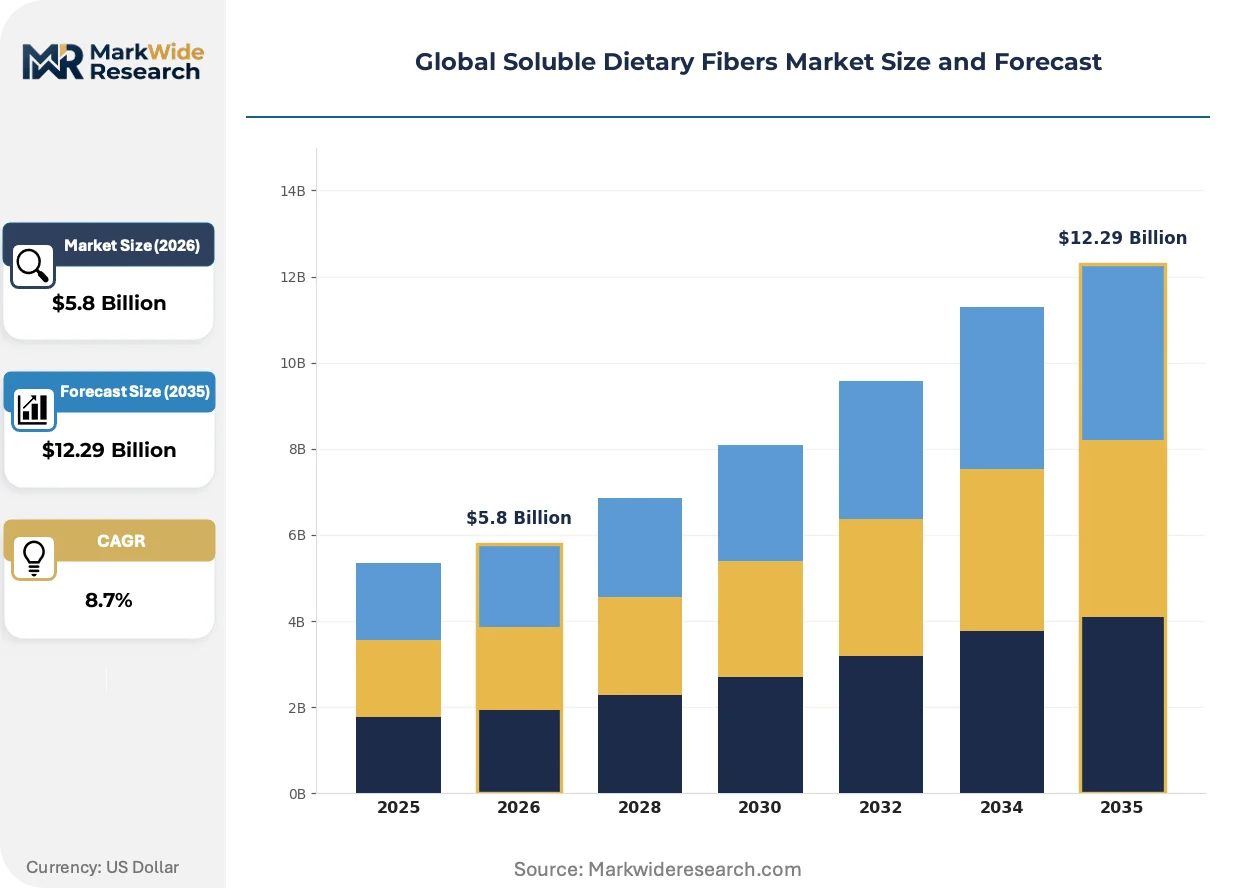
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Pectin, Guar Gum, Beta-Glucan, Psyllium, Gums Application: Functional Foods, Beverages, Dietary Supplements, Bakery Products, Pharmaceuticals, Animal Nutrition End User Industry: Food & Beverage Manufacturers, Supplement Producers, Pharmaceutical Companies, Animal Feed Manufacturers Form: Powder, Granules, Liquid, Flakes |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, DuPont de Nemours, Inc., BENEO GmbH, Kerry Group plc, Nexira, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soluble Dietary Fibers Market Strategic Shifts & Innovations
Processing technology convergence and regulatory classification battles are fragmenting competitive advantage away from commodity volume toward specialized clinical substantiation capabilities. The market is bifurcating between agricultural-integrated suppliers and biotechnology-enabled novel fiber developers.
Enzymatic modification of resistant starches is overtaking conventional extraction methods as the dominant production pathway for soluble dietary fibers. Beverage manufacturers in Japan and South Korea are adopting these modified starches for transparent, low-viscosity fiber fortification. This technology is overtaking traditional inulin and guar gum solutions in clear liquid applications where haze formation previously blocked fiber incorporation.
EFSA's updated guidance on beneficial physiological effect substantiation is tightening clinical evidence requirements for digestive health claims. European suppliers must now demonstrate fiber-specific effects rather than generic prebiotic outcomes. Dietary supplement manufacturers targeting EU markets are accelerating dossier investments or pivoting to non-claim positioning to avoid authorization delays.
Direct procurement relationships between food manufacturers and agricultural processors are compressing traditional ingredient distributor margins. Large CPG buyers in the United States are contracting directly with chicory root cooperatives and oat millers for multi-year supply security. This channel disintermediation is most visible in the functional beverage segment where clean-label positioning demands traceable origin documentation.
Global Soluble Dietary Fibers Market Segmentation
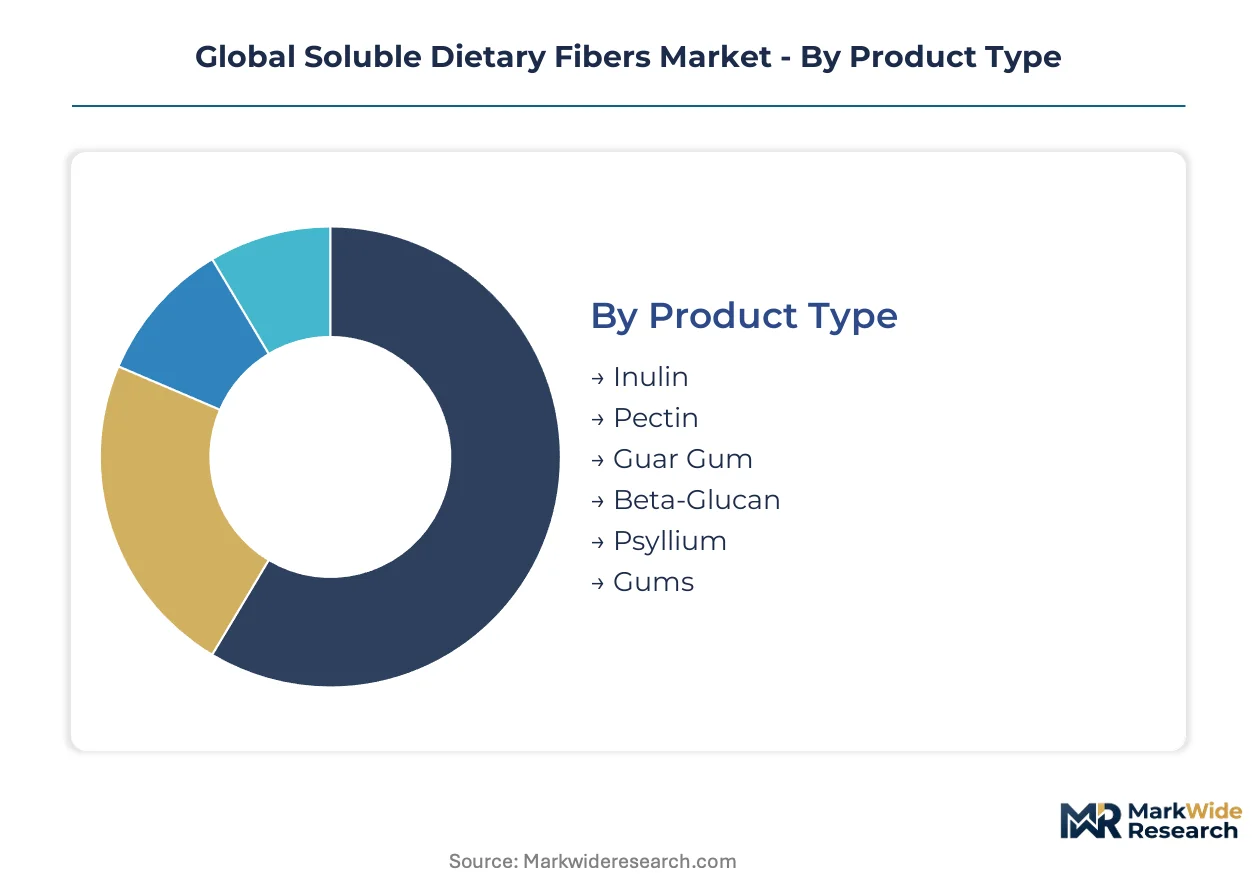
Segmentation in soluble dietary fibers determines formulation feasibility, regulatory qualification pathways, and margin capture. Product chemistry dictates processing compatibility while application channels shape clinical substantiation investments and customer relationships.
Product Type:
Standardization dominates commodity polysaccharides while enzymatic modification and rare oligosaccharide synthesis enable premium customization tiers.
- Inulin:A fructan polymer extracted primarily from chicory root, comprising beta-2,1 linked fructose units with terminal glucose. Dairy alternatives and baked goods in the United States absorb the largest volumes as manufacturers replace modified starches for clean-label positioning. Leading the category by volume: Inulin. Growing fastest: Beta-Glucan.
- Beta-Glucan:Linear glucose polymers linked by beta-1,3 and beta-1,4 bonds concentrated in oat and barley endosperm cell walls. Cardiovascular health-positioned applications in the United States and Scandinavian markets are expanding fastest as FDA-qualified health claims drive finished product differentiation.
- Pectin:Galacturonic acid-based heteropolysaccharide with variable methyl esterification degrees controlling gelation behavior.
- Guar Gum:Galactomannan from Cyamopsis tetragonoloba seeds with mannose-to-galactose ratios near 2:1 enabling high-viscosity solutions at low concentrations.
- Psyllium:Mucilaginous arabinoxylan from Plantago ovata seed husks with exceptional water-binding capacity for digestive health applications.
- Gums:Xanthan, gellan, and other microbial exopolysaccharides produced via fermentation platforms with tunable rheological properties.
Extraction yield ceilings constrain beta-glucan economics while inulin benefits from mature agricultural supply infrastructure.
Application:
Functional positioning requirements separate premium health-claim channels from cost-driven bulk incorporation segments.
- Functional Foods:Processed products with substantiated physiological benefits beyond basic nutrition, requiring fiber incorporation without sensory degradation. United States reformulation mandates for clean-label dairy alternatives and baked goods are concentrating demand as FDA fiber definition compliance becomes mandatory.
- Dietary Supplements:Capsule, tablet, and powder formats delivering concentrated fiber doses with specific health positioning. EFSA digestive health claim pathways in Europe favor suppliers with established clinical dossiers, creating qualification barriers for novel entrants.
- Beverages:Clear liquid applications demanding low-viscosity, non-hazing fiber solutions.
- Bakery Products:Fiber enrichment in bread, pastries, and snack items requiring moisture management and texture preservation.
- Pharmaceuticals:Excipient and active ingredient applications with stringent purity and documentation requirements.
- Animal Nutrition:Emerging prebiotic applications in pet food and livestock feed with distinct formulation specifications.
Highest margin capture occurs in supplements with authorized claims; fastest volume expansion is in functional food reformulation.
End User Industry:
Scale requirements and technical capabilities fragment procurement approaches across customer types.
- Food & Beverage Manufacturers:Large-scale processors reformulating legacy product lines for clean-label compliance. Direct contracting with agricultural processors in the United States is compressing traditional distributor margins as traceability documentation becomes mandatory.
- Supplement Producers:Formulators requiring certified prebiotic content and clinical substantiation packages. EFSA health claim dossier investments are extending supplier qualification timelines to 24-36 months for European market access.
- Pharmaceutical Companies:Buyers demanding GMP compliance, batch documentation, and excipient-grade purity certifications.
- Animal Feed Manufacturers:Emerging customers seeking cost-optimized fiber sources with documented fermentability profiles.
Food and beverage manufacturers command volume leadership; supplement producers deliver premium pricing power.
Form:
Processing equipment compatibility and dissolution kinetics drive form selection across application channels.
- Powder:Dominant format for dry blending operations, offering longest shelf stability and lowest transport costs. Functional food manufacturers in the United States prefer agglomerated powders for dust-controlled handling during high-speed production lines.
- Liquid:Pre-hydrated solutions eliminating dispersion challenges in beverage applications. Japanese and South Korean clear beverage producers are adopting liquid resistant starch concentrates for transparent fiber fortification.
- Granules:Intermediate particle size for controlled release and reduced hygroscopicity in supplement tablets.
- Flakes:Specialized format for specific cereal and snack applications requiring visual fiber presence.
Powder maintains volume dominance; liquid formats are climbing fastest in beverage channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Belgian and Dutch agricultural zones for chicory-derived inulin, while consumption tilts toward United States functional food reformulation and Japanese beverage fortification channels.
United States
Processed food manufacturers accelerate soluble fiber incorporation to replace modified starches in dairy alternatives and baked goods. FDA fiber definition adjustments under evolving Nutrition Facts label rules compress supplier qualification timelines. Chicago and Minneapolis anchor North American procurement, where direct contracting between CPG buyers and agricultural processors is compressing traditional distributor margins.
Belgium
Chicory root cultivation and inulin extraction infrastructure supply the majority of European and export volumes. EFSA digestive health claim authorization pathways impose clinical substantiation burdens that favor established suppliers with dossier capabilities. Flanders agricultural cooperatives dominate raw material sourcing, though weather-induced harvest volatility exposes processors to contract pricing spikes.
Japan
Beverage manufacturers adopt enzymatically modified resistant starches for transparent, low-viscosity fiber fortification in clear liquid applications. METI standards alignment with Codex frameworks facilitates novel fiber incorporation. Osaka and Tokyo metropolitan areas concentrate formulation R&D, where local processors pioneer processing technologies that displace conventional inulin and guar gum solutions.
Germany
Specialty starch and fiber processors leverage technical advisory services to capture recurring revenue beyond commodity transactions. EFSA's tightened guidance on beneficial physiological effect substantiation extends dossier preparation timelines to 24-36 months. Bavaria and Baden-Württemberg host integrated agricultural processors with captive R&D infrastructure qualified for European health claim pathways.
Brazil
Functional food underpenetration creates formulation opportunities as ANVISA regulatory harmonization with Codex standards opens prebiotic fiber pathways in fortified beverages. Domestic processors extract value from tropical agricultural sidestreams. São Paulo state anchors South American demand, where local manufacturers reformulate legacy product lines for emerging clean-label expectations.
Global Soluble Dietary Fibers Market Key Industry Players
Top-tier vendors anchor integrated agricultural processing, while mid-tier specialists compete through enzymatic modification capabilities and clinical dossier services. The vendor base stratifies across three archetypes: captive raw material controllers, biotechnology-enabled novel fiber developers, and formulation service integrators. Dominant competitive moves include direct procurement relationship cultivation with large CPG buyers and precision fermentation platform investments for rare oligosaccharide synthesis.
Within the integrated processing tier, Cargill, Incorporated and Tate & Lyle PLC exemplify agricultural supply chain capturers with multi-fiber category positions. Roquette Frères occupies a specialist position aligned with European plant-based formulation trends. These three entities represent contrasting geographic and technological anchoring strategies without implying specific market share or revenue claims.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Frères |
| DuPont de Nemours, Inc. |
| BENEO GmbH |
| Kerry Group plc |
| Nexira |
| Others |
Cost & Logistics Intelligence
Chicory root contract prices cascade through three downstream tiers as Belgian and Dutch agricultural cooperatives negotiate multi-year supply agreements with North American CPG buyers seeking FDA-compliant fiber sources. This raw material concentration enables processors to enforce volume-commitment pricing while exposing finished product margins to weather-induced harvest volatility.
Pricing Analysis
Margin tightening in standard-grade inulin reflects direct procurement relationships between United States dairy alternative manufacturers and chicory root cooperatives eliminating distributor markups. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-authorized clinical dossier holders from commodity polysaccharide suppliers. Price differentiation hinges on certification grade and volume scale, with cardiovascular health-positioned beta-glucan commanding premium positioning. Cost-down pressure on economy-tier guar gum accelerates because Indian seed processors face competing industrial demand from oilfield applications. Animal nutrition formulators exhibit highest price sensitivity, while pharmaceutical excipient buyers demonstrate least sensitivity due to GMP compliance requirements.
Supply Chain Analysis
Ocean freight rates from Antwerp to Chicago and Minneapolis determine landed cost competitiveness for European inulin processors serving North American functional food manufacturers. Supply concentrates in Belgium, the Netherlands, and France for chicory-derived fructans, while oat beta-glucan extraction centers on Scandinavian and North American millers. Raw material dependencies encompass chicory root cultivation cycles, oat and barley varietal selection, and pea starch sidestream availability from protein isolation facilities. Single-source vulnerability characterizes Belgian inulin infrastructure exposed to fungal root rot outbreaks. Distribution runs through direct processor-to-manufacturer contracts in the United States, bypassing traditional ingredient distributors for traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in soluble dietary fibers is consolidating around captive chicory root supply and in-house clinical trial infrastructure as qualification timelines extend under EFSA and FDA pressure.
For Market Incumbents: To counter precision fermentation startups synthesizing rare oligosaccharides, established processors should deepen backward integration into Belgian and Dutch agricultural cooperatives while expanding captive R&D capacity for 24-36 month EFSA dossier preparation. Direct contracting relationships with United States CPG buyers provide channel control against biotechnology-enabled entrants. For New Entrants and Emerging Players: E-commerce-enabled technical advisory subscriptions offer the lowest-friction entry path for microbiome-focused startups seeking recurring revenue beyond commodity fiber sales. Brazilian functional beverage reformulation under ANVISA harmonization represents the most penetrable geography, with enzymatically modified resistant starches for clear liquid applications offering differentiation against incumbent inulin suppliers. For Investors and Strategic Acquirers: FDA fiber definition expansion to include novel isolated categories is the leading indicator that clinical substantiation capabilities will command acquisition premiums. Long-term viability favors targets with integrated agricultural processing and established European health claim dossiers. Watch for ANVISA regulatory finalization triggering Brazilian formulation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chicory Cultivation | Captive Belgian and Dutch root supply secures multi-year contract pricing against harvest volatility. |
| EFSA Health Claim Dossier Investment | Clinical substantiation packages enable premium positioning in European glycemic response applications. |
| Precision Fermentation Platform Buildout | Microbial oligosaccharide synthesis creates novel prebiotic structures beyond conventional plant extraction. |
| Direct-to-CPG Procurement Relationships | Chicago and Minneapolis-based buyers demand traceable origin documentation compressing distributor margins. |
| Enzymatic Modification Technology Licensing | Japanese beverage processors adopt transparent resistant starch solutions displacing conventional inulin. |
Research Approach
Independent corroboration across ingredient procurement directors at North American CPG manufacturers, EFSA regulatory affairs consultants, and Belgian agricultural cooperative managers underwrites the qualitative findings in this study. Primary interviews with functional food formulators, dietary supplement brand managers, and clinical research organization executives combined with secondary validation from FDA guidance documents, EFSA opinion publications, and ANVISA regulatory harmonization notices. Bottom-up volume modeling across product chemistry tiers triangulates with top-down value estimates from trade flow analysis.
Rate-of-change decomposition separates volume drivers from price-mix effects across the analysis window. Segmentation dimensions encompass product chemistry, application channel, end-user industry, and geographic regulatory cluster. CAGRs derive from normalized historical trajectories adjusted for FDA fiber definition recalibration impacts and EFSA substantiation timeline extensions. Forecast inputs incorporate chicory root harvest yield variability and enzymatic modification technology adoption curves in Japanese and South Korean beverage markets.
The model holds under stable regulatory classification frameworks; deviation in FDA novel fiber qualification criteria or EFSA beneficial physiological effect guidance would shift supplier R&D prioritization and commercialization timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Medicinal Mushroom Supplement Market
Nutritional Supplements
L-Leucine Market
Nutritional Supplements
Dysphagia Supplements Market
Nutritional Supplements
Vietnam Collagen Supplements Market
Nutritional Supplements
Europe Nutraceutical Excipients Market
Nutritional Supplements
Choline Supplement Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
Hair Growth Supplements Market
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
Global Beta Glucan Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Diet Market
Nutritional Supplements
Asia-Pacific Beta-Glucan Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
Global Vitamin Supplements Market
Nutritional Supplements
US Ketones Market