
 Dal Mill Machine Market | 2026-2036
Dal Mill Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Dal Mill Machine Market Outlook
Food processing cooperatives is realigning dal milling demand toward higher-throughput equipment. Mill Master Machinery Private Limited leverages its engineering footprint across western India to serve this shift. Pavan Group sustains dominance in pneumatic handling systems for large-scale installations. Buhler AG competes through its grain processing technology leadership, extending solutions from wheat into pulse-specific applications.
Dal mill machines mechanically dehusk, split, and polish pulses using abrasive rollers, graders, and aspiration systems operating at throughput rates from 50 kg/hr to 500 kg/hr. The equipment integrates destoning, pre-conditioning, and color-sorting stages to deliver edible-grade split lentils for commercial packers and retail brands. Automatic machine type commands the widest installed base, though solar-powered units represent the fastest-growing configuration as rural electrification gaps persist. Small scale producers anchor volume demand, while agricultural cooperatives concentrate margin pools through collective procurement of 200 kg/hr and 500 kg/hr lines.
India's BIS standards for food processing equipment, combined with FSSAI hygiene mandates and state-level food safety officer inspections, elevate stainless steel construction and clean-in-place design from optional to mandatory. ISO 22000 certification requirements from export buyers further filter supplier eligibility. Stakeholders must monitor how India's PLI scheme for food processing machinery reshapes domestic manufacturing economics against established European and East Asian import channels.
Market Dynamics
India's BIS certification requirements for food-contact machinery are forcing manufacturers toward stainless steel construction and hazard analysis compliance, compressing supplier margins while elevating equipment durability standards across the pulse processing sector.
Growth Catalysts
- Cooperative procurement aggregation:Farmer-producer organizations in Gujarat's Anand-Surat belt are pooling capital for shared 200-500 kg/hr milling lines, concentrating demand for higher-throughput automated systems.
- FSSAI hygiene mandates:State-level food safety officer inspections are mandating clean-in-place design and stainless steel contact surfaces, eliminating non-compliant domestic fabricators from eligibility pools.
- Solar electrification gaps:Rural Maharashtra and Madhya Pradesh are driving fastest-growing demand for solar-powered dal mill configurations where grid connectivity remains unreliable.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 stainless steel price swings directly compress fabrication margins for domestic equipment manufacturers serving price-sensitive small-scale producers.
- Import channel concentration:Established European and East Asian machinery suppliers control premium pneumatic handling and color-sorting technology segments, limiting domestic manufacturer pricing power.
- Technical limitation in pulse-specific sorting:Discrimination accuracy for split versus whole lentils remains below wheat processing standards, constraining yield recovery rates for high-value exports.
Strategic Opportunities
- Export certification arbitrage:ISO 22000 certification requirements from Middle Eastern and Southeast Asian buyers are filtering supplier eligibility, creating first-mover advantage for compliant Indian manufacturers.
- PLI scheme manufacturing incentives:India's production-linked incentive scheme for food processing machinery is reshaping domestic fabrication economics against import dependency.
- Pre-conditioning technology convergence:Integration of microwave hydration with traditional abrasive dehusking is opening yield recovery improvements for pigeon pea and mung bean processing.
Industry Challenges
- Certification timeline compression:BIS testing protocols and FSSAI facility approvals now require 8-14 months, delaying commercialization for new equipment entrants.
- Legacy equipment integration friction:Retrofitting automated graders and aspiration systems onto existing 50 kg/hr village-level installations demands custom engineering that erodes project economics.
- Skilled technician scarcity:Pneumatic system calibration and color-sorter maintenance expertise concentrates in Anand and Nagpur, constraining service response times for remote cooperative installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dal Mill Machine Market |
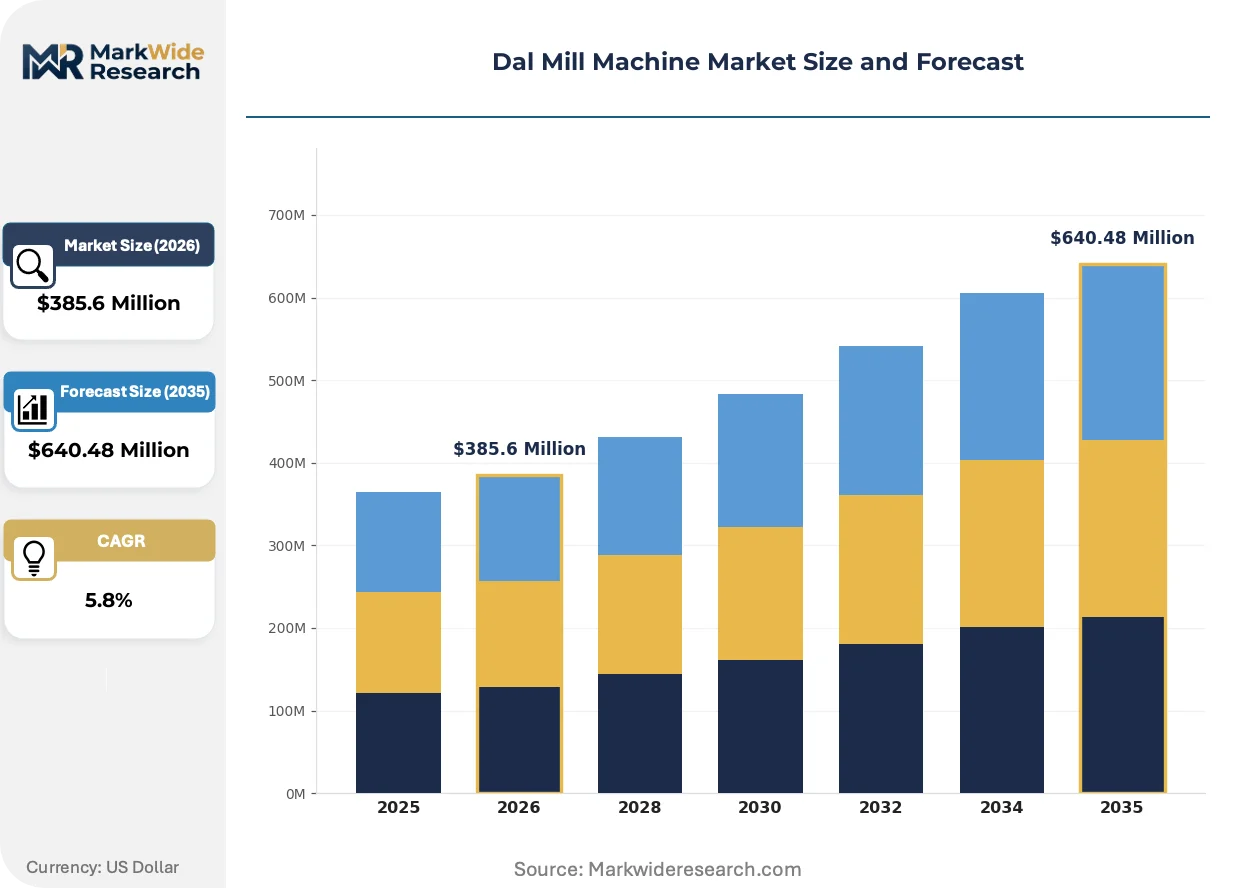
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Automatic, Semi-Automatic, Manual, Customized End User: Small Scale Producers, Large Scale Manufacturers, Retailers, Agricultural Cooperatives Processing Capacity: 50 kg/hr, 100 kg/hr, 200 kg/hr, 500 kg/hr Power Source: Electric, Diesel, Solar, Hybrid |
| Companies Covered | Mill Master Machinery Private Limited, Pavan Group, Zhengzhou Taizy Machinery Co., Ltd, Alvan Blanch Development Company, Rudra Industries, SATAKE, Shri Viratra Engineering Industries, Veerba Agro, Buhler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dal Mill Machine Market Strategic Shifts
Automation architectures are fragmenting from monolithic lines toward configurable sub-systems, while regulatory compliance layers deepen and buyer procurement models consolidate through cooperative structures.
Integrated destoning-pre-conditioning units are modularizing across Gujarat's cooperative installations, allowing farmer-producer organizations to stage capital deployment by adding color-sorting and automated packaging modules as procurement volumes justify expansion, compressing the traditional single-purchase capex model into phased investment cycles.
FSSAI's escalating hygiene inspection protocols are mandating welded seams over bolted joints and 316-grade stainless steel over 304 in all food-contact surfaces, pushing domestic fabricators toward European welding certification standards and eliminating lower-cost fabrication shops from government tender eligibility pools.
Collective tendering through Maharashtra and Madhya Pradesh cooperatives is displacing individual smallholder purchases, with shared infrastructure models now accounting for the majority of 200 kg/hr and above installations, channeling demand toward vendors offering multi-year service contracts and spare parts availability guarantees rather than equipment-only transactions.
Dal Mill Machine Market Segmentation
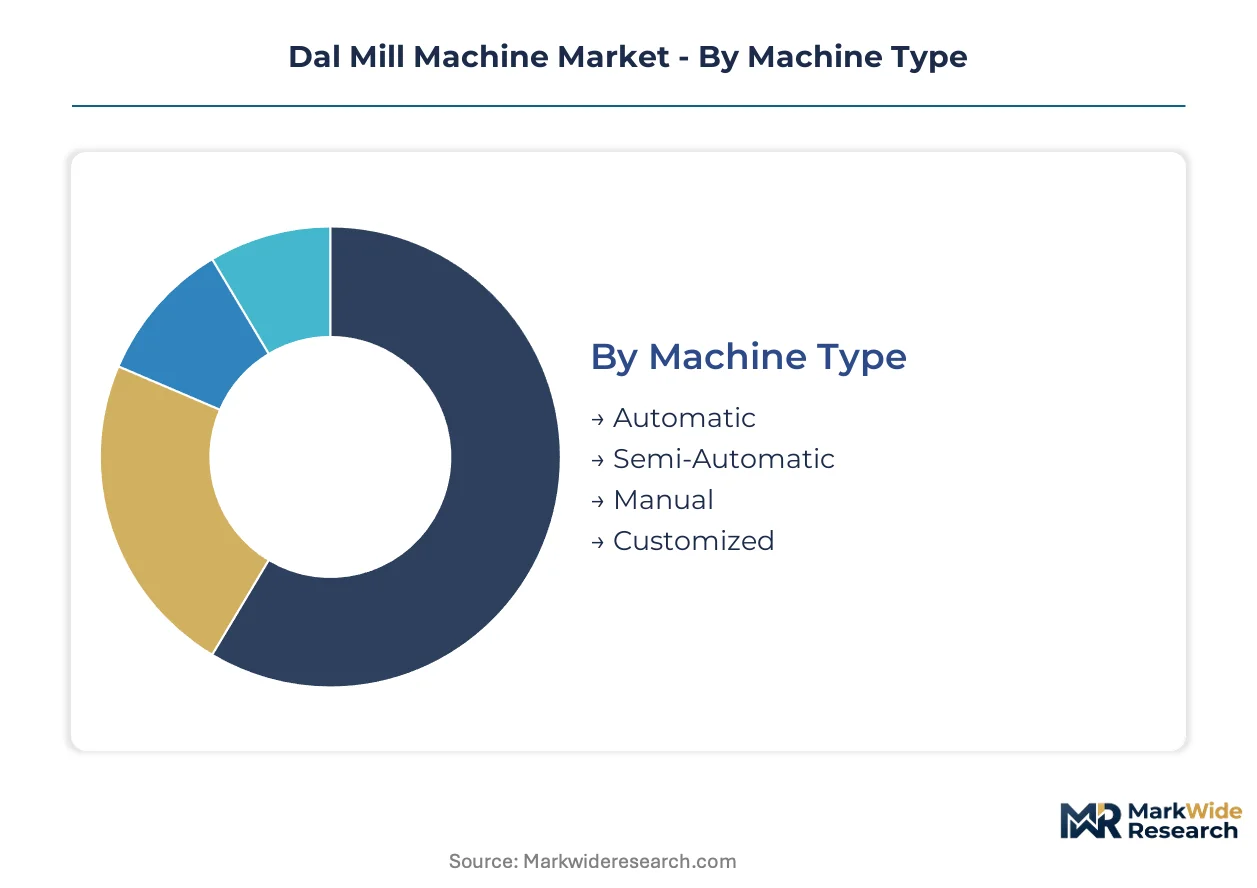
Dal mill machine procurement decisions hinge on electrification reliability, capital access, and cooperative governance structures. Equipment specifications diverge sharply between individual smallholders and collective farmer-producer organizations pooling resources for shared infrastructure.
Machine Type:
Buyers weigh labor substitution against maintenance complexity and grid dependency when selecting automation tiers.
- Automatic:Fully integrated systems with PLC-controlled abrasive dehusking, pneumatic aspiration, and color-sorting modules command the widest installed base. Gujarat's Anand-Surat processing belt concentrates procurement for 200-500 kg/hr lines where FSSAI hygiene mandates require clean-in-place design and welded 316-grade stainless steel contact surfaces.
- Semi-Automatic:Hybrid configurations blending motorized dehusking with manual grading and bagging dominate price-sensitive smallholder budgets. Maharashtra's pulse processing cooperatives are staging capital deployment through semi-automatic intermediates before upgrading to full automation as procurement volumes justify expansion.
- Manual:Hand-cranked abrasive rollers and single-stage graders persist in remote tribal belts with unreliable grid connectivity and limited formal credit access.
- Customized:Retrofit packages integrating automated color-sorters onto legacy 50 kg/hr village installations demand site-specific engineering for destoning-pre-conditioning convergence.
Automatic leads on scale; Customized leads on momentum.
End User:
Procurement authority is consolidating toward collective structures with multi-year service contract negotiating power.
- Small Scale Producers:Individual farmers and village-level processors anchor volume demand for 50-100 kg/hr units. Madhya Pradesh's tribal districts sustain manual and semi-automatic purchases where BIS certification awareness remains limited and stainless steel price volatility compresses fabrication margins.
- Agricultural Cooperatives:Farmer-producer organizations in Maharashtra and Madhya Pradesh are pooling capital for shared 200-500 kg/hr milling infrastructure. Collective tendering now channels demand toward vendors offering spare parts availability guarantees and multi-year maintenance contracts rather than equipment-only transactions.
- Large Scale Manufacturers:Commercial packers and retail brands operate integrated lines with ISO 22000 certification for export-grade split lentil recovery.
- Retailers:Trading intermediaries and regional distributors maintain small-scale polishing and re-bagging operations for local market supply.
Agricultural Cooperatives concentrate margin pools; Small Scale Producers sustain absolute unit volumes.
Processing Capacity:
Throughput selection tracks electrification quality and procurement aggregation scale across rural infrastructure gradients.
- 500 kg/hr:High-throughput lines with integrated destoning, microwave pre-conditioning, and automated packaging serve Gujarat's cooperative installations. These configurations demand three-phase grid stability and concentrated raw material supply that only collective procurement models can secure.
- 200 kg/hr:Mid-scale systems represent the cooperative sweet spot, allowing Maharashtra farmer-producer organizations to amortize capital across 40-60 member farms while meeting FSSAI facility approval timelines.
- 100 kg/hr:Compact units suit electrified village clusters with moderate pigeon pea and mung bean throughput.
- 50 kg/hr:Entry-level lines persist in off-grid talukas where diesel or solar hybridization extends operational reach.
500 kg/hr commands premium positioning; 200 kg/hr captures cooperative expansion.
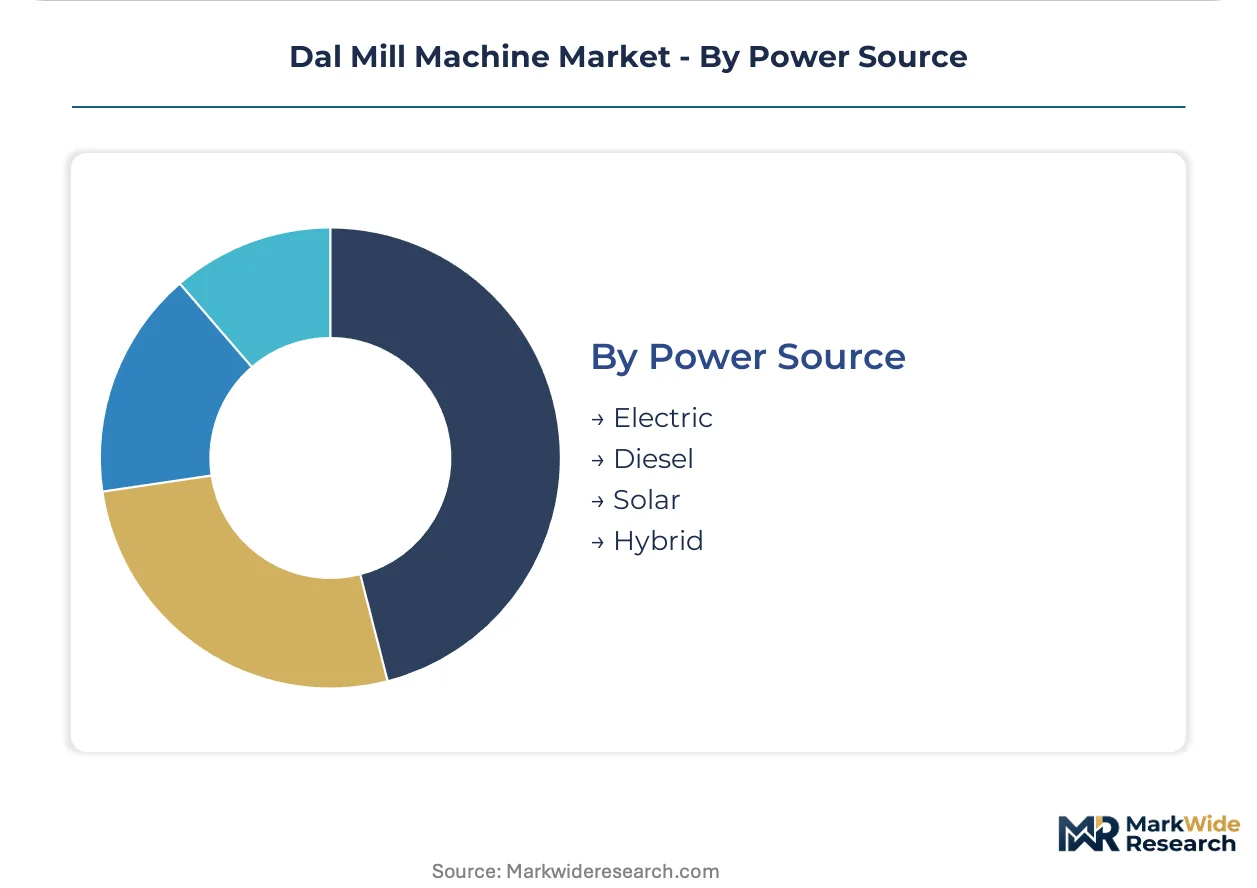
Power Source:
Energy access gaps and input cost volatility reshape equipment configuration preferences across rural electrification frontiers.
- Solar:Photovoltaic-powered units with battery storage and DC motor drives are climbing fastest where Maharashtra and Madhya Pradesh grid connectivity remains unreliable. PLI scheme incentives for food processing machinery are improving domestic fabrication economics against imported solar-hybrid alternatives.
- Electric:Grid-tied three-phase systems dominate Gujarat's Anand-Surat belt with stable rural electrification and cooperative load aggregation justifying higher-throughput investments.
- Diesel:Generator-dependent configurations persist as backup for grid-intermittent locations and primary power for remote tribal processing clusters.
- Hybrid:Dual-mode electric-diesel or solar-diesel systems offer operational flexibility where grid reliability fluctuates seasonally.
Electric anchors installed base; Solar gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where BIS certification costs and stainless steel fabrication economics create compliance arbitrage. India's domestic manufacturers exploit this gap against European import channels.
India
Maharashtra's farmer-producer organizations and Gujarat's Anand-Surat processing belt concentrate cooperative procurement for 200-500 kg/hr lines. FSSAI hygiene mandates and BIS food-contact machinery standards eliminate non-compliant fabricators from government tender pools. Nagpur and Anand host the densest clusters of pneumatic system calibration expertise.
China
Zhengzhou-based machinery fabricators serve price-sensitive small-scale producers across Southeast Asian export markets. GB standards for agricultural equipment and MIIT industrial policy support domestic manufacturing scale. The Yangtze River Delta concentrates color-sorting component supply chains for regional equipment integrators.
Italy
Pneumatic handling specialists in Emilia-Romagna leverage legacy grain processing engineering into pulse-specific applications. CE marking requirements and EU machinery directives shape stainless steel construction standards for Middle Eastern export destinations. Bologna anchors European color-sorting technology development.
Switzerland
Precision engineering hubs around Zurich and Basel supply premium optical sorting modules to Indian mill retrofit projects. Swissmedic-adjacent quality protocols and ISO 22000 certification frameworks filter supplier eligibility for GCC export buyers. The Lake Geneva corridor concentrates grain processing R&D infrastructure.
Turkey
Anatolian fabricators compete on diesel-hybrid configurations for Central Asian markets with unreliable grid infrastructure. The country's national food safety regulator enforces hazard analysis compliance for equipment serving domestic lentil processing cooperatives. Konya hosts the primary cluster of mid-scale abrasive roller manufacturing.
Dal Mill Machine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments. The market exhibits tiered concentration with European precision engineering houses commanding premium pneumatic and optical sorting segments while Asian fabricators capture volume-driven small-scale producer demand. Three archetypes dominate: stainless steel construction specialists, solar-hybrid configuration integrators, and legacy grain processing technology extenders. Competitive moves center on multi-year service contract bundling and phased cooperative procurement financing structures.
Among Indian stainless steel construction specialists, Mill Master Machinery Private Limited occupies a position exemplifying western India engineering footprint concentration, while Pavan Group represents pneumatic handling system dominance for large-scale installations. Buhler AG anchors the European technology extension archetype, leveraging grain processing leadership into pulse-specific applications without direct competitive confrontation with domestic fabricators on price-sensitive segments.
| Leading Market Players |
|---|
| Mill Master Machinery Private Limited |
| Pavan Group |
| Zhengzhou Taizy Machinery Co., Ltd |
| Alvan Blanch Development Company |
| Rudra Industries |
| SATAKE |
| Shri Viratra Engineering Industries |
| Veerba Agro |
| Buhler AG |
| Others |
Value Chain & Pricing Dynamics
FSSAI hygiene mandates and BIS certification requirements for food-contact machinery gate both qualified supply and premium-tier pricing access, compressing margins for non-compliant fabricators while elevating equipment durability standards across India's pulse processing sector.
Pricing Analysis
Distributor margins of 12-18% layer onto factory gate prices before cooperative procurement aggregations in Gujarat and Maharashtra negotiate volume discounts. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified stainless steel configurations from basic 304-grade semi-automatic units. Cost compression in economy-tier manual equipment is intensifying because Grade 304 and 316 stainless steel price volatility directly squeezes domestic fabrication margins. Small-scale individual producers in Madhya Pradesh's tribal districts exhibit highest price sensitivity, while agricultural cooperatives pooling 200-500 kg/hr investments demonstrate lowest sensitivity due to amortized capital structures.
Supply Chain Analysis
Stainless steel feedstock rests on Indian domestic mills, Chinese specialty alloy producers, and European precision suppliers for 316-grade food-contact specifications. Abrasive roller compounds, pneumatic aspiration components, and optical sorting modules anchor fabrication dependencies. Single-source vulnerability concentrates in color-sorter sensor arrays sourced from Swiss and Italian precision engineering houses. Distribution runs through Anand and Nagpur-based equipment integrators serving western India's cooperative belt, with spare parts logistics extending through regional service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dal mill machine margins are expanding through cooperative procurement aggregation that concentrates buyer power and extends service contract durations, while stainless steel input volatility compresses economy-tier fabricators.
For Market Incumbents: Extend multi-year maintenance contract bundling to capture recurring revenue streams as cooperative procurement displaces equipment-only transactions. Invest in 316-grade stainless steel welding certification to defend eligibility against FSSAI facility approval timelines. Backward integration into precision-machined abrasive roller production reduces dependency on Nagpur component suppliers. For New Entrants and Emerging Players: Solar-hybrid configuration buyers in rural Maharashtra and Madhya Pradesh represent an underserved archetype with fastest-growing demand and limited incumbent service coverage. Penetrate through diesel-to-solar retrofit packages for existing 50 kg/hr village installations. Partner with farmer-producer organizations for phased capital deployment financing rather than competing on upfront equipment pricing. For Investors and Strategic Acquirers: Roll-up economics work for regional stainless steel fabrication specialists because BIS certification timelines and FSSAI compliance costs create barriers that favor scaled players with regulatory navigation expertise. Target mid-cap Indian manufacturers with established western India service footprints. Watch PLI scheme disbursement velocity for food processing machinery as inflection indicator for domestic manufacturing competitiveness against European import channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Abrasive Roller Manufacturing | Captive production of wear components reduces Nagpur supply dependency and compresses maintenance contract costs. |
| 316-Grade Stainless Steel Welding Certification Investment | FSSAI facility approvals now mandate European-standard welded seams over bolted joints in food-contact surfaces. |
| Solar-Hybrid Configuration Product Line Expansion | Maharashtra and Madhya Pradesh grid electrification gaps drive fastest-growing demand for photovoltaic-powered units. |
| Multi-Year Service Contract Bundling | Cooperative procurement aggregation shifts buyer preference from equipment-only transactions to availability guarantees. |
| Cooperative Procurement Financing Partnerships | Phased capital deployment structures align vendor economics with farmer-producer organization cash flow constraints. |
Study Parameters
Multiple input streams — equipment manufacturer production data, cooperative procurement tender records, and stainless steel trade flow documentation — were reconciled through bottom-up and top-down triangulation. Primary interviews with plant engineers at Maharashtra and Madhya Pradesh farmer-producer organizations, procurement leads at Gujarat processing cooperatives, and aftermarket service heads at Anand-based integrators were validated against secondary sources including BIS certification registries, FSSAI facility approval databases, and customs machinery import records.
Historical capacity installation patterns were cross-referenced against panel input from cooperative governance structures to model adoption trajectories across the projection horizon. Segmentation dimensions included machine type automation tier, end-user procurement authority structure, processing capacity throughput, and power source configuration. CAGRs were derived from reconciling top-down market sizing with bottom-up equipment shipment aggregation, incorporating PLI scheme incentive assumptions and rural electrification gap persistence as industry-specific forecast inputs.
Underlying measurement precision varies by segment; automatic machine type and agricultural cooperative end-user categories carry tighter precision than manual configurations and small-scale producer segments due to data availability through formal tender processes. Forecasts reflect documented assumptions regarding BIS certification timeline compression and stainless steel price volatility. Regulatory enforcement intensity, cooperative formation velocity, and solar-hybrid technology cost curves constitute the small set of triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Global Nut Processing Equipment Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
North America Feed Pelletizing Agent Market
Agricultural Processing Equipment
Grain Processing Equipment Market
Agricultural Processing Equipment
Global Threshers Market
Agricultural Processing Equipment
Harvesting Machinery Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Global Square Straw Baler Market
Agricultural Processing Equipment
Global Grain and Seed Cleaning Equipment Market
Agricultural Processing Equipment
Feed Screw Barrel Market
Agricultural Processing Equipment
Asia-Pacific Agricultural Shredder Machine Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Japan Agricultural Shredder Machine Market
Agricultural Processing Equipment
Color Sorter Market
Agricultural Processing Equipment
Cashew Processing Machine Market
Agricultural Processing Equipment
China Agricultural Shredder Machine Market