
 Global Nut Processing Equipment Market | 2026-2036
Global Nut Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nut Processing Equipment Market Intelligence
Equipment leasing and project finance is tilting competitive access toward mid-tier processors that previously faced capital barriers. Bühler AG leverages its integrated technology platforms across thermal and optical sorting systems to sustain premium positioning in high-throughput installations. JBT Corporation anchors its presence through extensive service networks and aftermarket parts dominance in North American snack production facilities. TOMRA Systems ASA differentiates via sensor-based sorting intelligence that extends machine uptime and reduces manual intervention for processors.
Nut processing equipment encompasses machinery engineered for shell removal, thermal treatment, size classification, foreign material detection, and bulk material handling of tree nuts and groundnuts, typically operating at throughputs from 500 kg to 50 metric tons per hour with stainless steel contact surfaces meeting food-grade sanitation protocols. The equipment serves commercial processors seeking yield maximization, allergen control, and finished product uniformity for downstream food manufacturing. Optical sorting technology captures expanding investment as processors prioritize defect detection and mycotoxin mitigation; thermal processing retains mature margin pools but faces energy-efficiency retrofit pressure. Snack production application demand outpaces oil extraction as consumer packaged goods brands reformulate portfolios toward value-added nut-based products.
FDA food safety modernization rules and EU Green Deal energy-efficiency frameworks shape equipment design requirements, compelling manufacturers to validate sanitation protocols and document carbon footprint reductions across thermal processing lines. ISO 22000 and HACCP certification standards govern market access for European and North American equipment suppliers, while China's NMPA and GB standards regulate imported machinery compliance for domestic nut processing facilities. Stakeholders must monitor regulatory divergence between energy-efficiency mandates and food safety protocols when configuring product development roadmaps and geographic deployment priorities.
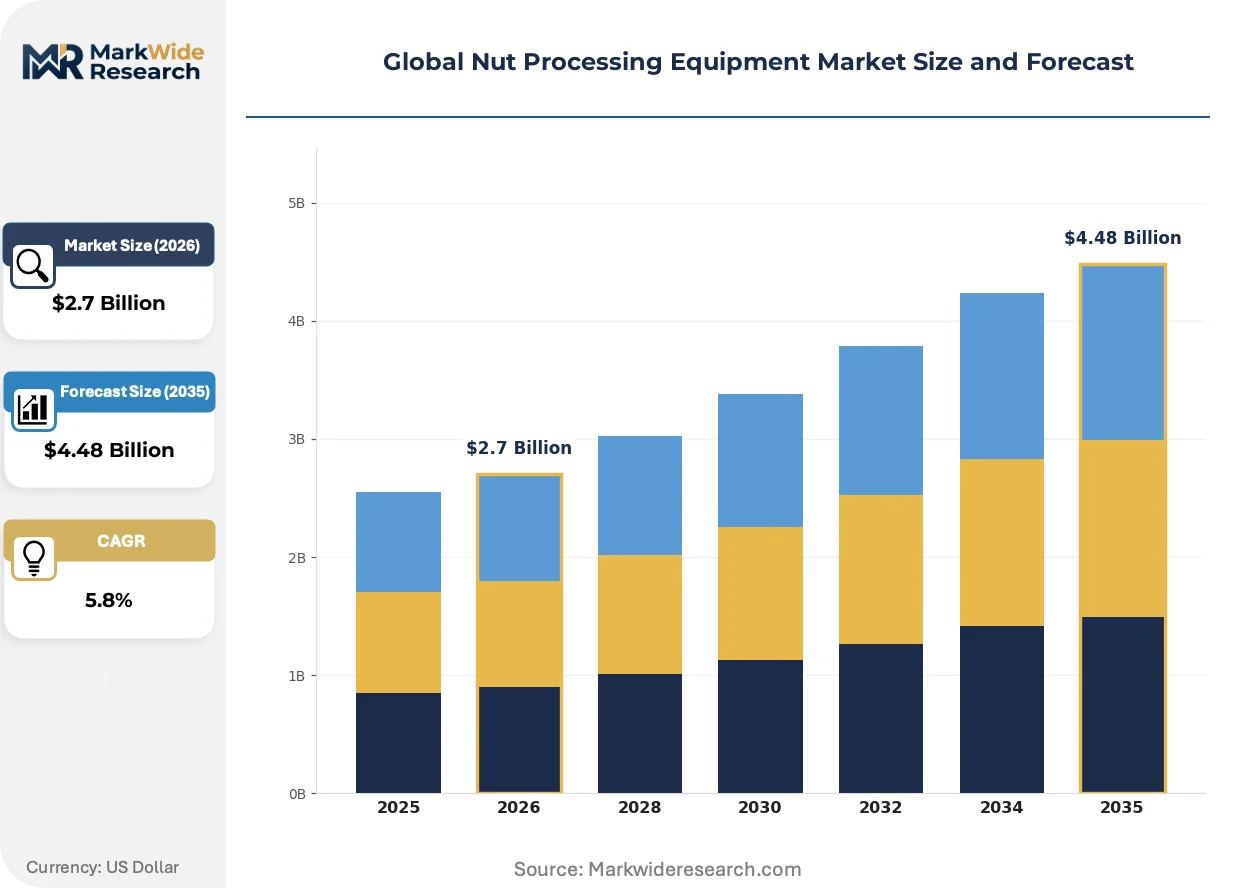
Market Dynamics
Optical sorting systems are compressing defect-detection timelines while EU Green Deal mandates force thermal equipment retrofits, creating bifurcated investment priorities across processor tiers.
Growth Catalysts
- India PLI scheme incentives:Domestic food manufacturing scale-up subsidizes capital equipment acquisition for groundnut and cashew processors establishing integrated shelling-to-packaging lines.
- Snack production line expansion:Consumer packaged goods brands reformulate portfolios toward value-added nut-based products, prioritizing optical sorting and thermal roasting capacity.
- EU Green Deal energy-efficiency mandates:Thermal processing equipment faces compulsory retrofit standards, generating replacement demand for heat-recovery and low-emission roasting systems.
Market Restraints
- Stainless steel input volatility:Food-grade 304 and 316L contact surface requirements expose equipment manufacturers to nickel and chromium price swings, compressing margin predictability on long-delivery contracts.
- Optical sensor supply concentration:High-resolution near-infrared and hyperspectral imaging modules concentrate among Japanese and German component suppliers, creating procurement bottlenecks for mid-tier equipment builders.
- Allergen cross-contamination protocols:FDA food safety modernization rules mandate validated sanitation sequences between peanut and tree nut processing campaigns, extending changeover downtime.
Strategic Opportunities
- Vietnam and Indonesia processing hubs:Underpenetrated cashew and macadamia sectors lack integrated shelling-sorting-packaging infrastructure, opening greenfield deployment for turnkey system providers.
- Equipment-as-a-service models:Leasing structures with embedded maintenance and upgrade pathways reduce capital barriers for mid-tier processors previously excluded from premium technology access.
- Hyperspectral-magnetic sorting convergence:Combined foreign material and mycotoxin detection platforms enable single-pass quality assurance, commanding premium positioning in almond and pistachio segments.
Industry Challenges
- Control systems integration:Legacy mechanical sorting lines require PLC and HMI retrofit compatibility with new optical modules, extending commissioning timelines and demanding scarce automation engineering talent.
- ISO 22000 and HACCP certification timelines:European and North American market access requires documented sanitation protocol validation, creating 12-18 month compliance gaps for emerging market equipment entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nut Processing Equipment Market |
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.48 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Shellers, Roasters, Graders, Sorters, Conveyors Technology: Thermal, Optical Sorting, Pneumatic, Mechanical, Vibratory Application: Snack Production, Ingredient Processing, Oil Extraction, Bakery Ingredients, Confectionery End User: Food Processing Plants, Ingredient Manufacturers, Packagers, OEMs |
| Companies Covered | Key Technology, Lewis M. Carter Manufacturing, LLC, JBT Corporation, Savage Equipment, Modern Process Equipment Corporation, Bühler AG, The Middleby Corporation, Kadıoglu LTD, TOMRA Systems ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nut Processing Equipment Market Strategic Shifts & Innovations
Digital twin architectures are compressing commissioning cycles while regulatory carbon-accounting frameworks reshape thermal equipment specifications across processor procurement criteria.
Hyperspectral imaging systems detect aflatoxin contamination and shell fragment residue through spectral signature analysis rather than mechanical sieving. Large-scale almond and pistachio processors in California and Spain deploy these platforms at 10-15 metric ton per hour throughputs. This technology is virtualizing quality-control labor, reducing manual inspection headcount while compressing defect escape rates below 50 parts per million.
The EU Green Deal's F-Gas Regulation and embedded carbon border adjustment mechanisms impose documented lifecycle emissions thresholds on imported thermal processing equipment. Manufacturers must validate heat-recovery efficiencies and refrigerant alternatives in roasting and drying lines. European snack production facilities face the steepest compliance curves, with German and Italian processors accelerating equipment replacement cycles to avoid carbon tariff exposure.
Service contract unbundling allows processors to separate equipment purchase from aftermarket parts and remote monitoring subscriptions. Mid-tier operators in India and Vietnam increasingly procure core machinery through project finance while purchasing predictive maintenance and spare parts on consumption-based terms. This preference shift concentrates recurring revenue with OEMs possessing dense regional service networks, disadvantaging pure equipment vendors lacking localized technical presence.
Global Nut Processing Equipment Market Segmentation
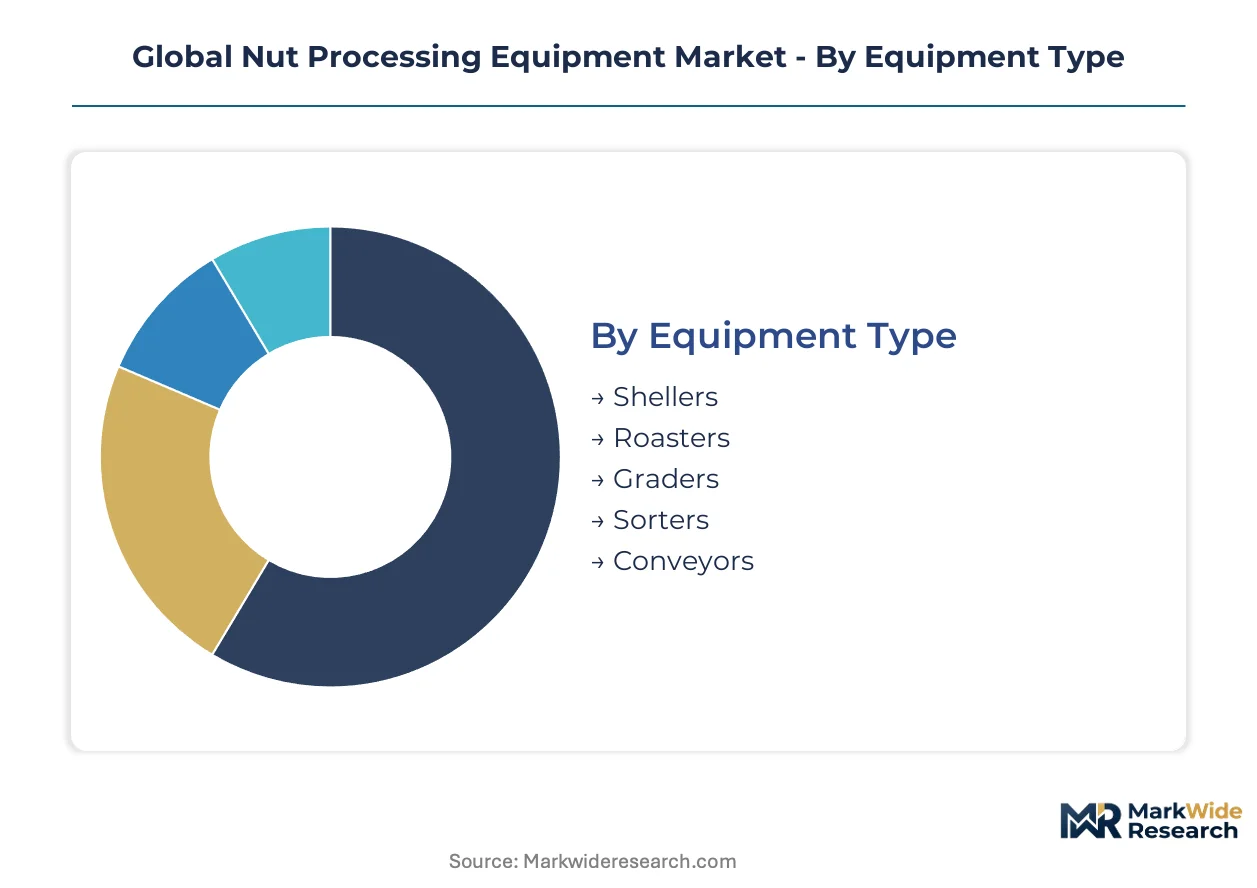
Nut processing equipment segments diverge sharply by capital intensity and regulatory exposure. Equipment type and technology choices determine energy compliance burdens, while application focus shapes throughput requirements and sanitation protocols.
Equipment Type:
Shelling through packaging lines span manual-feed village operations to fully automated 50-ton-per-hour installations serving multinational snack brands.
- Shellers:Mechanical cracking systems for almonds, walnuts, and cashews employ adjustable gap rollers and pneumatic kernel separation. Indian groundnut processors under the PLI scheme dominate acquisition volumes as domestic capacity scales.
- Roasters:Continuous rotary and fluidized-bed thermal systems apply precise temperature curves for flavor development and pathogen reduction. EU Green Deal mandates are forcing replacement cycles in Germany and Italy as carbon border adjustments bite.
- Graders:Size-classification machinery sorts kernels by dimensional and density characteristics for uniform downstream processing.
- Sorters:Optical and mechanical platforms remove defects, foreign material, and shell fragments prior to packaging.
- Conveyors:Stainless steel belt and bucket systems handle bulk transfer between process stages with washdown-compatible designs.
The dominant share belongs to Shellers, while Sorters are closing the gap fastest on hyperspectral technology adoption.
Technology:
Technology selection hinges on defect detection precision versus energy consumption trade-offs, with optical systems commanding premium positioning.
- Thermal:Roasting, drying, and pasteurization equipment applies controlled heat for microbial reduction and shelf-life extension. California almond processors face steep retrofit pressure from EPA emissions tracking and EU carbon border exposure on exported equipment.
- Optical Sorting:Near-infrared and hyperspectral imaging platforms detect aflatoxin, shell fragments, and color defects at throughputs exceeding 15 metric tons per hour. Spanish pistachio installations drive European demand for single-pass quality assurance.
- Pneumatic:Air-classification systems separate kernels by density and aerodynamic properties for preliminary cleaning stages.
- Mechanical:Sieving, cracking, and conveying equipment employs physical force and gravity separation for robust, low-maintenance operation.
- Vibratory:Oscillating feeders and conveyors meter bulk flow and stratify material for downstream processing stages.
Thermal retains the largest installed base, though Optical Sorting is expanding most quickly on food safety modernization requirements.
Application:
Application focus determines equipment configuration complexity, with snack production demanding the most integrated shelling-to-packaging lines.
- Snack Production:Dry-roasted and flavored nut products require thermal processing, seasoning application, and retail packaging integration. Consumer packaged goods brands in Vietnam and Indonesia are reformulating portfolios toward value-added nut-based offerings.
- Ingredient Processing:Diced, sliced, and milled nut components supply bakery and confectionery manufacturers with specified particle sizes and moisture content. Food processing plants in India scale groundnut and cashew ingredient supply for domestic and export markets.
- Oil Extraction:Pre-press and solvent extraction equipment processes high-oil-content groundnuts and tree nuts for culinary and industrial oil production.
- Bakery Ingredients:Roasted nut pieces and meals integrate into dough, filling, and topping applications with specified texture and flavor profiles.
- Confectionery:Caramelized, praline, and chocolate-enrobed nut products demand precise moisture control and coating compatibility.
Snack Production commands the dominant revenue position, while Ingredient Processing is gaining share fastest on bakery and confectionery reformulation trends.
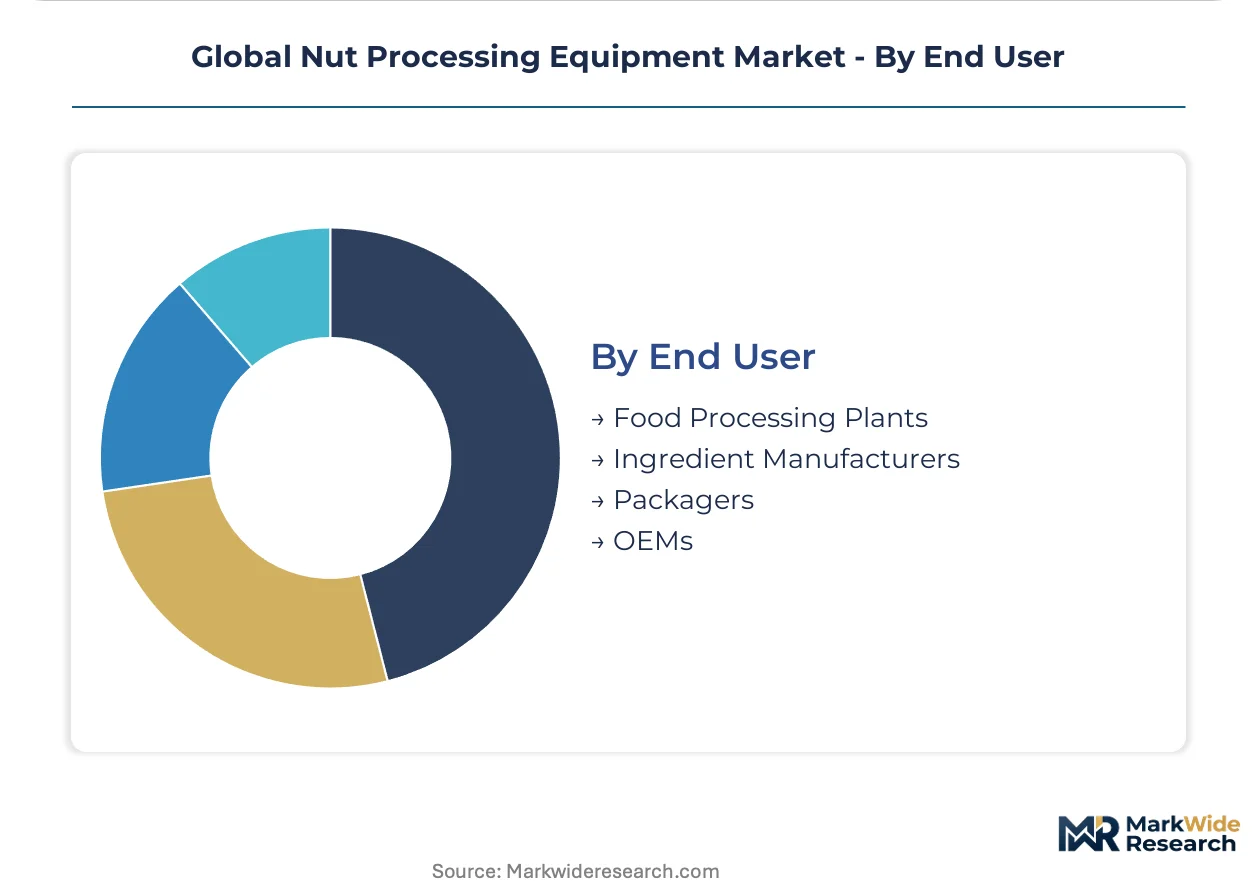
End User:
End-user categories separate integrated processors from component suppliers, with capital access determining technology tier.
- Food Processing Plants:Integrated facilities manage shelling through finished product packaging with comprehensive HACCP and ISO 22000 protocols. Indian processors leverage PLI incentives to establish captive shelling-sorting-packaging infrastructure.
- Ingredient Manufacturers:Specialized suppliers produce diced, milled, and pasteurized nut components for downstream food manufacturers. California and Spain host concentrated almond and pistachio ingredient capacity serving European and North American markets.
- Packagers:Contract packaging operations receive bulk-processed nuts for retail portioning, nitrogen flushing, and shelf-ready formatting.
- OEMs:Equipment manufacturers and system integrators procure sub-assemblies and components for incorporation into turnkey processing lines.
Food Processing Plants hold the dominant share, with Ingredient Manufacturers climbing fastest on outsourcing trends among consumer brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme subsidies are redirecting processing equipment procurement toward domestic groundnut and cashew shelling-sorting-packaging lines. Germany and Italy face EU Green Deal retrofit deadlines for thermal roasting systems. California almond processors confront EPA emissions tracking alongside EU carbon border exposure on exported equipment.
United States
California's Central Valley hosts concentrated almond and pistachio processing capacity serving export markets to Europe and Asia. EPA emissions tracking requirements and FDA food safety modernization rules compel thermal equipment retrofits in Modesto and Fresno county facilities. Sacramento Valley processors are deploying hyperspectral sorting platforms to meet aflatoxin detection standards for EU-bound shipments.
Germany
Snack production lines in Bavaria and North Rhine-Westphalia drive demand for integrated roasting and optical sorting systems. EU Green Deal F-Gas Regulation mandates heat-recovery validation in thermal processing equipment, accelerating replacement cycles. Stuttgart-area engineering clusters supply automation components for PLC retrofit compatibility in legacy mechanical sorting lines.
India
Gujarat and Maharashtra groundnut processors leverage PLI scheme capital subsidies to establish captive shelling-to-packaging infrastructure. FSSAI sanitation protocols and BIS equipment standards regulate imported machinery compliance for domestic facilities. Saurashtra region processing hubs are scaling capacity to serve ingredient supply contracts for bakery and confectionery manufacturers.
Spain
Valencia and Murcia pistachio installations deploy single-pass optical sorting platforms for quality assurance at throughputs exceeding 15 metric tons per hour. EU embedded carbon border adjustment mechanisms impose documented lifecycle emissions thresholds on thermal equipment imports. Albacete province snack production facilities are reformulating portfolios toward value-added nut-based products.
Vietnam
Underpenetrated cashew sectors in Binh Phuoc and Dong Nai provinces lack integrated shelling-sorting-packaging infrastructure. The country's national food safety regulator enforces HACCP alignment for export-oriented processing facilities. Ho Chi Minh City-based project finance structures are reducing capital barriers for mid-tier processors accessing premium technology tiers.
Global Nut Processing Equipment Market Key Industry Players
On the supply side, the industry is tiered between integrated technology platforms and specialized component suppliers. Swiss and German engineering groups anchor premium positioning through thermal and optical system integration. North American service-network operators dominate aftermarket parts and predictive maintenance subscriptions. Chinese and Turkish fabricators occupy mid-tier segments through cost-optimized mechanical equipment. Strategic moves concentrate on equipment-as-a-service model expansion and sensor technology licensing partnerships.
Within the integrated technology tier, Bühler AG and JBT Corporation exemplify divergent competitive vectors. Bühler AG represents European engineering consolidation across thermal treatment and optical sorting domains. JBT Corporation anchors North American presence through dense regional service networks. TOMRA Systems ASA occupies sensor-based sorting specialization, with Norwegian-listed structure signaling hyperspectral imaging focus. Kadıoglu LTD exemplifies Turkish mechanical equipment fabrication for emerging market price sensitivity.
| Leading Market Players |
|---|
| Key Technology |
| Lewis M. Carter Manufacturing, LLC |
| JBT Corporation |
| Savage Equipment |
| Modern Process Equipment Corporation |
| Bühler AG |
| The Middleby Corporation |
| Kadıoglu LTD |
| TOMRA Systems ASA |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese mechanical equipment fabrication compresses margin structures for mid-tier shellers and graders, while undercapacity in Japanese and German optical sensor modules concentrates pricing power among hyperspectral imaging suppliers serving premium sorter installations.
Pricing Analysis
Certification level creates the primary spread across equipment tiers, with FDA-validated and CE-marked thermal systems commanding substantial premia over BIS-compliant machinery for Indian domestic processors. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 22000 documentation depth and HACCP protocol integration rather than throughput scale alone. Cost compression in economy-tier mechanical equipment intensifies because Chinese and Turkish fabricators compete on stainless steel input costs. Mid-tier processors in Vietnam and Indonesia exhibit highest price sensitivity, while multinational snack brands in California and Bavaria prioritize total cost of ownership over capital expenditure minimization.
Supply Chain Analysis
Extended payment terms from 90 to 180 days characterize procurement relationships between European OEMs and emerging market processors, with supply-chain finance facilities bridging working capital gaps for Indian PLI scheme beneficiaries. Component sourcing concentrates in Germany for precision optical modules, Japan for near-infrared sensors, and China for stainless steel fabrication and mechanical sub-assemblies. Raw material dependencies encompass nickel and chromium for food-grade 304 and 316L contact surfaces, high-purity silicon for imaging arrays, and specialized refrigerants for thermal equipment compliance. Single-source vulnerability in Japanese hyperspectral sensor supply creates procurement bottlenecks. Distribution runs through regional service networks rather than direct OEM relationships, with aftermarket parts and predictive maintenance subscriptions capturing recurring revenue concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as optical sorting intelligence converges with thermal processing control architectures, with interoperability between sensor modules and legacy PLC systems determining processor upgrade pathways.
For Market Incumbents: Harden defensive moats through backward integration into optical sensor calibration and hyperspectral algorithm development, countering emerging entrant threats from Asian automation specialists. Anchor premium positioning by embedding predictive maintenance subscriptions within equipment-as-a-service contracts, leveraging dense regional service networks to capture recurring revenue concentration. Prioritize certification investment in EU Green Deal heat-recovery validation and FDA sanitation protocol documentation to extend compliance gaps for emerging market competitors.
For New Entrants and Emerging Players: Vietnam's underpenetrated cashew processing infrastructure offers white-space deployment for turnkey shelling-sorting-packaging systems, with Binh Phuoc and Dong Nai provinces lacking integrated optical sorting capacity. Indonesia's macadamia sector presents comparable greenfield opportunity for hyperspectral-magnetic sorting convergence platforms. Project finance structures with embedded maintenance pathways provide the most penetrable go-to-market angle, reducing capital barriers for mid-tier processors previously excluded from premium technology tiers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across equipment-as-a-service models, shifting value capture from hardware margins toward recurring software and maintenance revenue streams. Long-term viability favors OEMs possessing dense regional service networks and sensor technology licensing partnerships over pure equipment vendors lacking localized technical presence. Acquisition target archetype: mid-tier automation specialists with PLC retrofit compatibility and established aftermarket parts distribution. Signal to watch: unbundling rates of service contracts from equipment purchase as indicator of preference shift toward consumption-based terms.
| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Expansion | Leasing structures with embedded maintenance reduce capital barriers for Vietnamese and Indonesian mid-tier processors. |
| Hyperspectral Technology Licensing | Sensor module partnerships enable mid-tier builders to bypass Japanese and German component supply bottlenecks. |
| EU Green Deal Compliance Certification | Heat-recovery validation documentation protects German and Italian installed base from carbon tariff exposure. |
| Regional Service Network Density | Localized technical presence captures predictive maintenance subscriptions and aftermarket parts revenue concentration. |
| PLC Retrofit Compatibility Development | Legacy mechanical line integration extends addressable market for optical sorting module upgrades. |
Research Approach
Initial hypotheses were tested against primary input from plant engineers at integrated processing facilities, procurement leads at snack manufacturing OEMs, aftermarket service heads at equipment distributors, and regulatory compliance officers, then refined through secondary validation. Primary interviews encompassed maintenance directors evaluating thermal equipment retrofit timelines and automation specialists assessing PLC integration complexity. Secondary sources included FDA food safety modernization rule filings, EU Green Deal technical documentation, BIS equipment standard registrations, and SEC disclosures from listed OEMs. Bottom-up capacity assessments across Gujarat, California, and Valencia processing clusters were triangulated against top-down equipment procurement forecasts.
Demand-supply balance modeling across the analysis window incorporated equipment type segmentation by capital intensity, technology selection by energy compliance exposure, and application focus by sanitation protocol requirements. Segmentation dimensions encompassed shelling-through-packaging equipment categories, thermal-optical-mechanical technology tiers, and snack production versus ingredient processing end-use configurations. CAGRs were derived from installed base replacement cycles, greenfield capacity announcements, and regulatory mandate compliance deadlines. Industry-specific inputs included PLI scheme subsidy disbursement rates and EU carbon border adjustment mechanism phase-in schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese automation specialists or Turkish fabricators into premium optical sorting would shift outcomes. Forecasts assume continued regulatory divergence between FDA sanitation protocols and EU energy-efficiency mandates without harmonization. Macroeconomic volatility in nickel and chromium prices, regulatory acceleration of carbon border adjustments, or breakthroughs in AI-driven defect detection would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
China Agricultural Shredder Machine Market
Agricultural Processing Equipment
Solar Herbs Dryer Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Meat Cutting Machine Market
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Meat Dicing Machine Market
Agricultural Processing Equipment
Rice Polishers Market
Agricultural Processing Equipment
Global Feed Processing Market
Agricultural Processing Equipment
Rice Milling Machines Market
Agricultural Processing Equipment
Harvesting Machinery Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Seed Processing Equipment Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Grain Processing Equipment Market
Agricultural Processing Equipment
Japan Agricultural Shredder Machine Market