
 Harvesting Machinery Market | 2026-2036
Harvesting Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Harvesting Machinery Market Intelligence
A demand rotation from individual farm ownership towards large-scale agricultural cooperatives and contract farmers is bifurcating the market for harvesting equipment. This shift favors machinery with higher capacity, advanced telematics, and fleet management capabilities. Deere & Company leverages its extensive dealer network and technology stack to serve these large-scale buyers. CNH Industrial N.V. competes through its multi-brand strategy, offering a diverse portfolio tailored to different regional and operational scales.
Harvesting machinery encompasses a range of self-propelled or tractor-pulled equipment designed to gather mature crops from fields. These machines integrate complex mechanical, hydraulic, and electronic systems to perform functions like cutting, threshing, separating, and cleaning grains or other produce. Their primary purpose is to automate and accelerate the harvesting process, maximizing yield and minimizing crop loss. Combine harvesters continue to constitute the largest product segment by value. The fastest-growing technology segment is autonomous operation, which commands a significant price premium over conventional GPS-enabled systems.
Regulatory frameworks globally shape equipment design and market access. In the United States, the EPA enforces strict engine emission standards, such as Tier 4 Final, impacting powertrain development. In Europe, machinery must comply with CE marking requirements for safety and operational standards. For equipment exported to India, adherence to standards set by the Bureau of Indian Standards (BIS) is often necessary. Stakeholder success now depends on navigating these divergent regional standards while investing in modular platforms that can be adapted for local needs.
Market Dynamics
The central force shaping the harvesting machinery market is the economic bifurcation between large-scale agribusiness and smaller farms. This divide accelerates demand for high-capacity, telematics-enabled equipment for commercial growers while creating distinct needs for modular, affordable solutions elsewhere.
Growth Catalysts
- Precision Agriculture Adoption:The integration of GPS, yield monitors, and telematics allows growers to optimize inputs and maximize harvest efficiency, directly supporting frameworks like the EU Green Deal that prioritize sustainable farming practices.
- Fleet Modernization in Brazil:Large agricultural economies, particularly Brazil, are undergoing significant fleet renewal cycles, replacing older equipment with modern, higher-capacity machines to improve productivity in soybean and corn harvesting.
- Focus on Yield Maximization:A persistent need to increase crop output per hectare to meet food demand drives investment in advanced harvesting technologies that minimize grain loss and damage during collection.
Market Restraints
- High Capital Costs:The substantial upfront investment required for modern combine harvesters and specialized equipment acts as a significant barrier for individual farmers and smaller agricultural enterprises, limiting market access.
- Divergent Emission Standards:Manufacturers face increased R&D and compliance costs navigating varied engine emission regulations, such as EPA Tier 4 Final in the US and separate standards in other regions.
- Maintenance Complexity:The growing sophistication of electronic and hydraulic systems requires specialized technicians and diagnostic tools, posing a maintenance challenge in remote agricultural areas with limited service infrastructure.
Strategic Opportunities
- Autonomous Systems Development:Fully autonomous harvesting equipment represents a major growth vector, commanding a price premium by addressing labor shortages and enabling 24/7 field operations for large-scale producers.
- Equipment-as-a-Service (EaaS) Models:Subscription and leasing models offer an alternative to outright purchase, providing access to advanced machinery for cooperatives and farmers who cannot justify the capital expenditure.
- Expansion in Mechanizing Regions:Emerging agricultural markets in parts of Africa and Southeast Asia present long-term opportunities as they transition from manual labor to mechanized harvesting to improve food security and efficiency.
Industry Challenges
- Skilled Labor Scarcity:A critical shortage of operators and technicians skilled in managing data-driven precision agriculture platforms and servicing complex mechatronic systems constrains the effective use of advanced machinery.
- Data Interoperability:A lack of standardization across different brands of equipment and farm management software creates data silos, hindering the development of a seamless, connected farm ecosystem for users.
- Navigating Regional Compliance:Global manufacturers must invest significant resources to ensure products meet a patchwork of safety and import standards, including CE marking in Europe and BIS certification in India.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Harvesting Machinery Market |
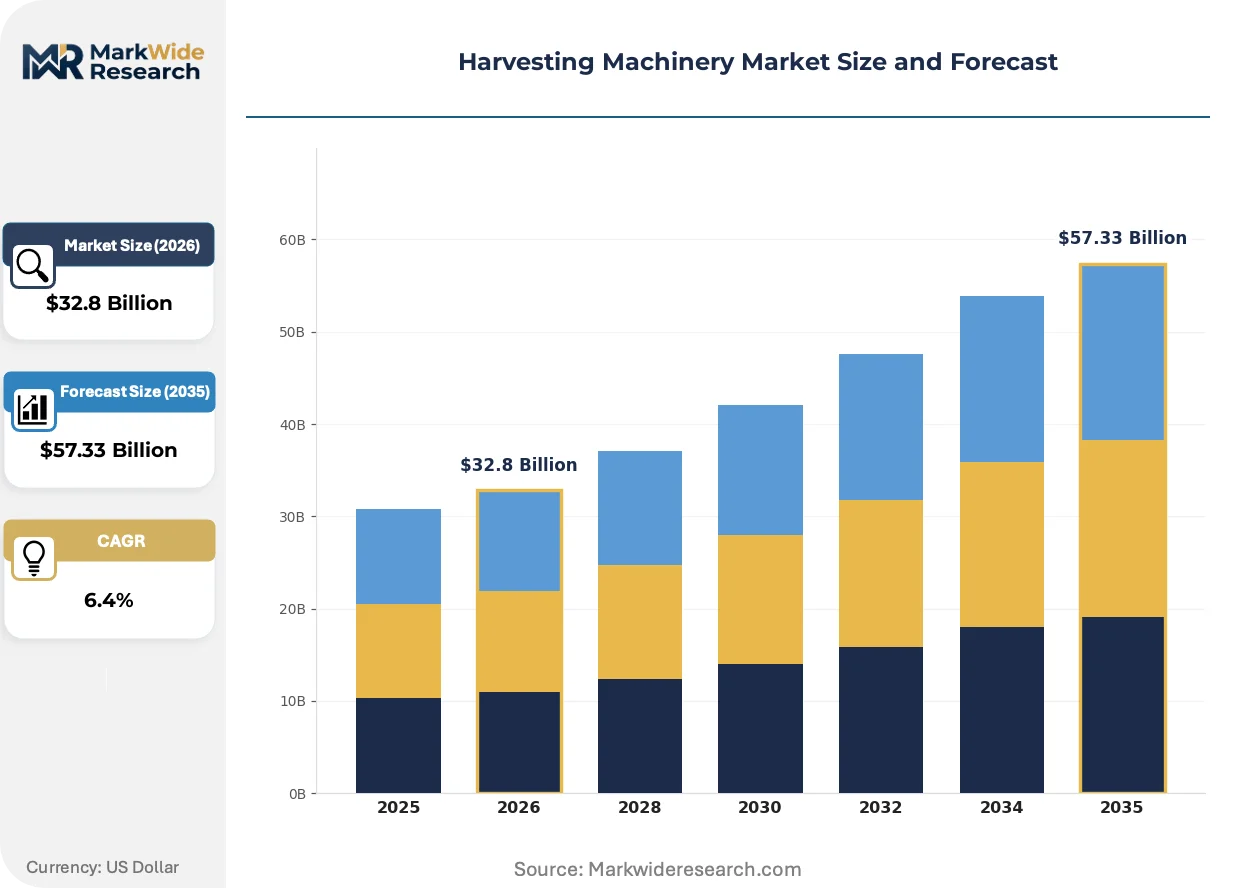
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combine Harvesters, Forage Harvesters, Reapers, Potato Harvesters, Sugarcane Harvesters Technology: GPS-Enabled Systems, Precision Agriculture, Autonomous Operation, Sensor-Based Monitoring, Telemetry Technology Application: Grain Collection, Root Crop Gathering, Fiber Crop Harvesting, Green Fodder Collection, Seed Crop Harvesting End User: Contract Farmers, Agricultural Cooperatives, Machinery Rental Firms, Commercial Growers, Farm Equipment Dealers |
| Companies Covered | Deere & Company, CNH Industrial N.V, AGCO Corporation, CLAAS KGaA mbH, Kubota Corporation, Mahindra & Mahindra Ltd., Yanmar Co., Ltd., SDF Group, Tractors & Farm Equipment Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Harvesting Machinery Market Strategic Shifts & Innovations
Data-centric capabilities are transforming harvesting equipment from purely mechanical assets into mobile information hubs. The evolution is toward machines that not only gather crops but also generate actionable agronomic data, driving operational decisions and fleet management strategies.
Autonomous Harvesting Systems
Autonomous operation technology combines LiDAR, advanced sensors, and AI-driven path planning to enable hands-free harvesting. Large-scale commercial growers and contract farming operations are adopting this technology to mitigate labor shortages and optimize field logistics. This automation is displacing the traditional one-operator-per-machine model, allowing for centralized fleet management and more efficient labor deployment across vast acreages.
Powertrain Electrification and Alternative Fuels
Regulations like the EU's F-Gas Regulation and broader decarbonization goals are pushing powertrain innovation beyond diesel. This shift compels development of electric-drive components and research into alternative fuels like hydrogen and biomethane for high-horsepower applications. The self-propelled forage harvester and specialty crop segments are early adopters for these technologies due to their specific power-cycle requirements.
Service and Data Monetization
A fundamental shift from one-time equipment sales to recurring revenue models is underway. This change is driven by telematics data, which enables predictive maintenance, remote diagnostics, and performance benchmarking services offered on a subscription basis. This trend is most visible in North America and Europe, where dealers and manufacturers bundle service packages with new machinery sales to large farming corporations.
Harvesting Machinery Market Segmentation
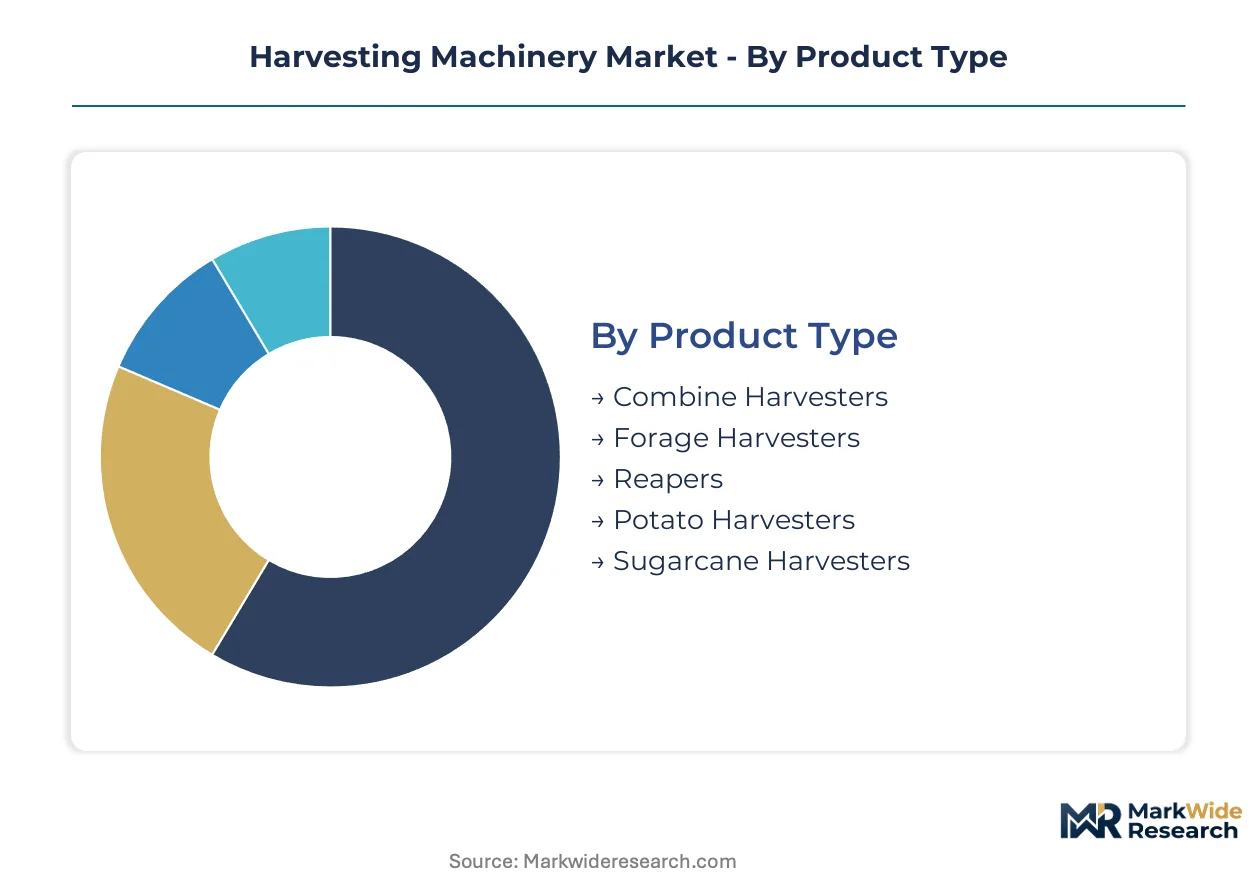
The harvesting machinery market segments reflect distinct technological capabilities, crop-specific applications, and diverse end-user requirements. Understanding these differentiations is critical for manufacturers to tailor product offerings and for stakeholders to identify growth pockets within the agricultural sector.
Product Type:
Regulatory distinctions often influence the design and market availability of different product types within harvesting machinery.
- Combine Harvesters:These self-propelled machines integrate cutting, threshing, separating, and cleaning functions for grain crops like wheat, corn, and soybeans. Demand concentrates in large agricultural economies such as Brazil, which are modernizing their farming fleets.
- Forage Harvesters:Designed to cut and chop green crops such as corn or grass into silage for livestock feed, these machines require high power output and often feature specialized attachments. The dairy and livestock sectors drive demand, with early electrification adoption observed in this segment.
- Reapers:Basic machines primarily used for cutting crops close to the ground, often for smaller farms or specific regional practices.
- Potato Harvesters:Specialized equipment designed to efficiently dig, separate, and collect potatoes from the soil, minimizing damage during the process.
- Sugarcane Harvesters:Robust machines engineered for cutting, chopping, and cleaning sugarcane stalks, crucial for large-scale sugar production in tropical regions.
Established volume favors Combine Harvesters; emerging adoption favors Sugarcane Harvesters due to regional modernization.
Technology:
The maturity curve for harvesting machinery technology reveals distinct levels of adoption and market penetration.
- Autonomous Operation:This technology leverages LiDAR, advanced sensors, and AI for hands-free harvesting, enabling 24/7 field operations. Large-scale commercial growers adopt these systems to mitigate labor shortages and optimize field logistics.
- Precision Agriculture:Integrating GPS, yield monitors, and telematics, this technology allows growers to optimize inputs and maximize harvest efficiency. It directly supports sustainable farming practices, aligning with frameworks like the EU Green Deal.
- GPS-Enabled Systems:These foundational technologies provide basic guidance and mapping capabilities for machinery, improving field coverage and reducing overlap.
- Sensor-Based Monitoring:Sensors collect real-time data on crop conditions, machine performance, and environmental factors, enabling immediate adjustments for efficiency.
- Telemetry Technology:This system transmits machine operational data remotely, facilitating predictive maintenance, remote diagnostics, and fleet management for large farming corporations.
While GPS-Enabled Systems provide foundational capabilities, Autonomous Operation technology demonstrates the steepest expansion trajectory.
Application:
Harvesting machinery applications span diverse crop types, reflecting specialized requirements across agricultural sectors.
- Grain Collection:This application involves harvesting staple crops such as wheat, corn, rice, and soybeans, primarily utilizing combine harvesters. Global food demand and the need for high-volume output drive continuous investment in this segment.
- Green Fodder Collection:Focused on gathering crops like silage corn and alfalfa for animal feed, this application heavily relies on forage harvesters. The livestock and dairy industries are the primary consumers, demanding efficient and high-quality feed processing.
- Root Crop Gathering:This segment includes harvesting potatoes, sugar beets, and carrots, requiring specialized diggers and separators designed to handle subterranean produce delicately.
- Fiber Crop Harvesting:Machinery for fiber crops like cotton and hemp must efficiently separate the valuable fibers from the plant material, minimizing contamination.
- Seed Crop Harvesting:This application demands equipment that can gently harvest seeds while maintaining their viability and purity for future planting.
Grain Collection continues to drive the largest equipment volumes, while Seed Crop Harvesting requires highly specialized machinery.
End User:
End-user segments for harvesting machinery reflect varying operational scales and investment capacities.
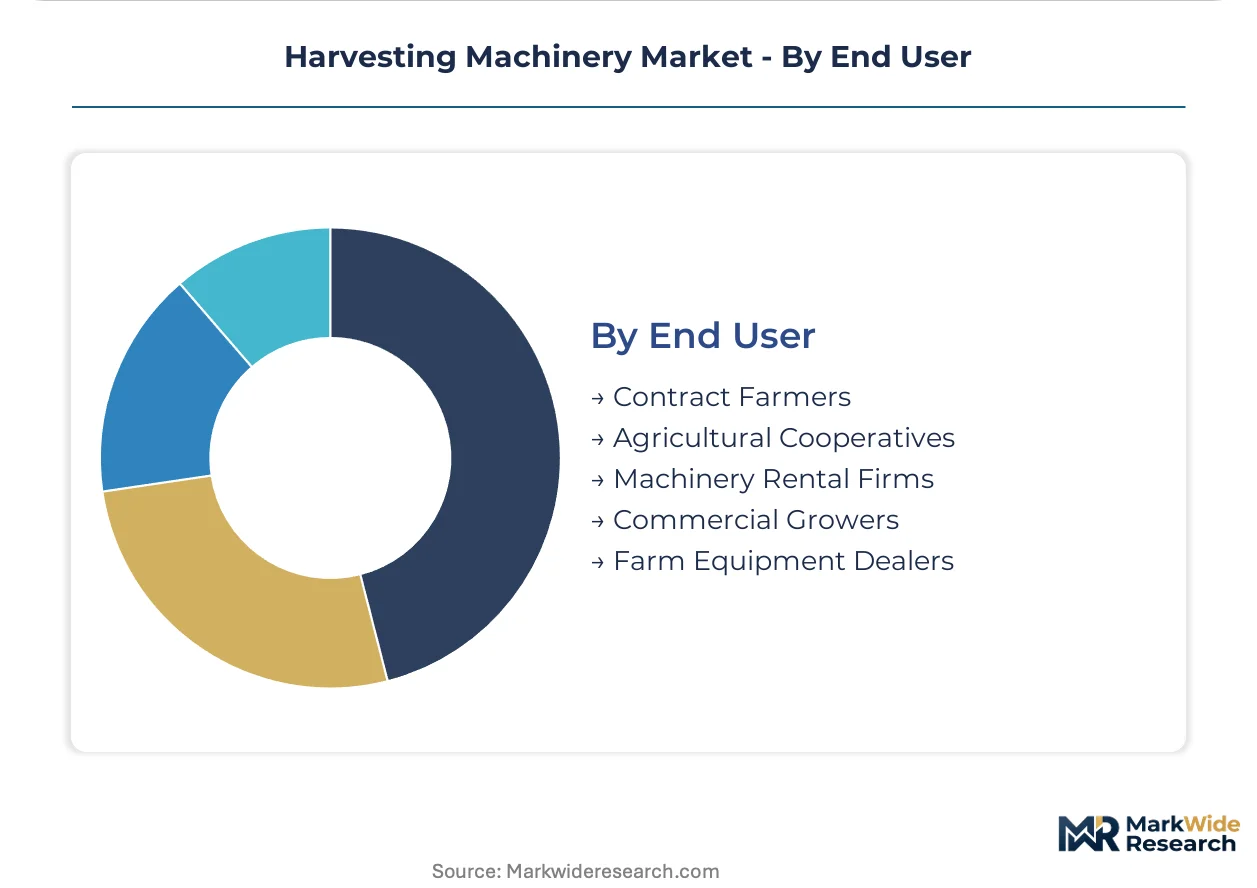
- Commercial Growers:These large-scale agricultural enterprises operate extensive acreages, requiring high-capacity equipment with advanced telematics and fleet management capabilities. Their focus is on maximizing yield and operational efficiency across vast fields.
- Agricultural Cooperatives:Organizations where farmers pool resources to collectively purchase and share expensive machinery, enabling access to advanced technology without individual capital burden. They often leverage equipment-as-a-service models.
- Contract Farmers:Individuals or companies providing harvesting services to other farmers, often owning a fleet of specialized machinery. They operate across multiple farms, prioritizing machine reliability and uptime.
- Machinery Rental Firms:These businesses lease harvesting equipment to farmers, offering flexible access to machinery for seasonal needs without the commitment of ownership.
- Farm Equipment Dealers:Entities that sell, service, and support harvesting machinery, acting as crucial intermediaries between manufacturers and end-users.
Commercial Growers represent a core market for advanced machinery, with Agricultural Cooperatives increasingly influencing procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's robust agricultural exports to global markets drive significant demand for modern harvesting machinery. This necessity for efficient crop gathering influences procurement patterns across major farming economies. Such trends underscore the global interconnectedness of agricultural supply chains.
Brazil
Brazil's fleet modernization cycle drives substantial demand for high-capacity harvesting equipment, particularly for soybean and corn. The country's national agricultural policies support investment in advanced farming technologies to boost productivity. Production facilities in states like Rio Grande do Sul are expanding to meet domestic and regional Latin American demand.
United States
The United States market prioritizes advanced harvesting systems with precision agriculture capabilities to optimize large-scale operations. The USDA provides programs and incentives for farmers to adopt sustainable practices and modern equipment. The Midwest region, particularly states like Iowa and Illinois, serves as a hub for both demand and manufacturing innovation.
Germany
Germany's agricultural sector focuses on high-efficiency and environmentally compliant harvesting machinery, aligning with EU Green Deal objectives. Machinery must comply with CE marking requirements for safety and operational standards. Manufacturers in regions such as Baden-Württemberg lead in developing specialized and autonomous farming solutions.
India
India exhibits growing demand for mechanized harvesting solutions as it transitions from manual labor to improve agricultural efficiency. Adherence to standards set by the Bureau of Indian Standards (BIS) is often necessary for imported and domestically manufactured equipment. States like Punjab and Haryana are witnessing increased adoption of combine harvesters for staple crops.
Australia
Australia's broadacre farming operations require durable and high-capacity harvesting equipment adapted to diverse climatic conditions. The Australian government supports agricultural innovation through research and development grants for advanced farming technologies. Western Australia and New South Wales represent key demand centers for grain harvesting machinery.
Harvesting Machinery Market Key Industry Players
Player mix skews toward established global manufacturers with extensive product portfolios and dealer networks. The market structure exhibits a tiered consolidation, with a few dominant players alongside numerous regional specialists. Strategic archetypes include full-line agricultural equipment providers and niche players focusing on specific crop types or technology segments. Dominant competitive moves involve continuous investment in R&D for autonomous systems and strategic partnerships to expand market reach.
On the premium-tier vector, Deere & Company leverages its extensive dealer network and technology stack to serve large-scale buyers. CNH Industrial N.V. competes through its multi-brand strategy, offering a diverse portfolio tailored to different regional and operational scales. Kubota Corporation, a Japan-based global manufacturer, occupies a position focused on compact and mid-sized agricultural machinery, exemplifying diversification across operational scales.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial N.V |
| AGCO Corporation |
| CLAAS KGaA mbH |
| Kubota Corporation |
| Mahindra & Mahindra Ltd. |
| Yanmar Co., Ltd. |
| SDF Group |
| Tractors & Farm Equipment Ltd. |
Cost & Logistics Intelligence
Harvesting machinery scale economies, particularly in combine harvester production, establish high barriers to entry. This scale necessitates concentrated manufacturing and influences price floors for high-capacity equipment.
Pricing Analysis
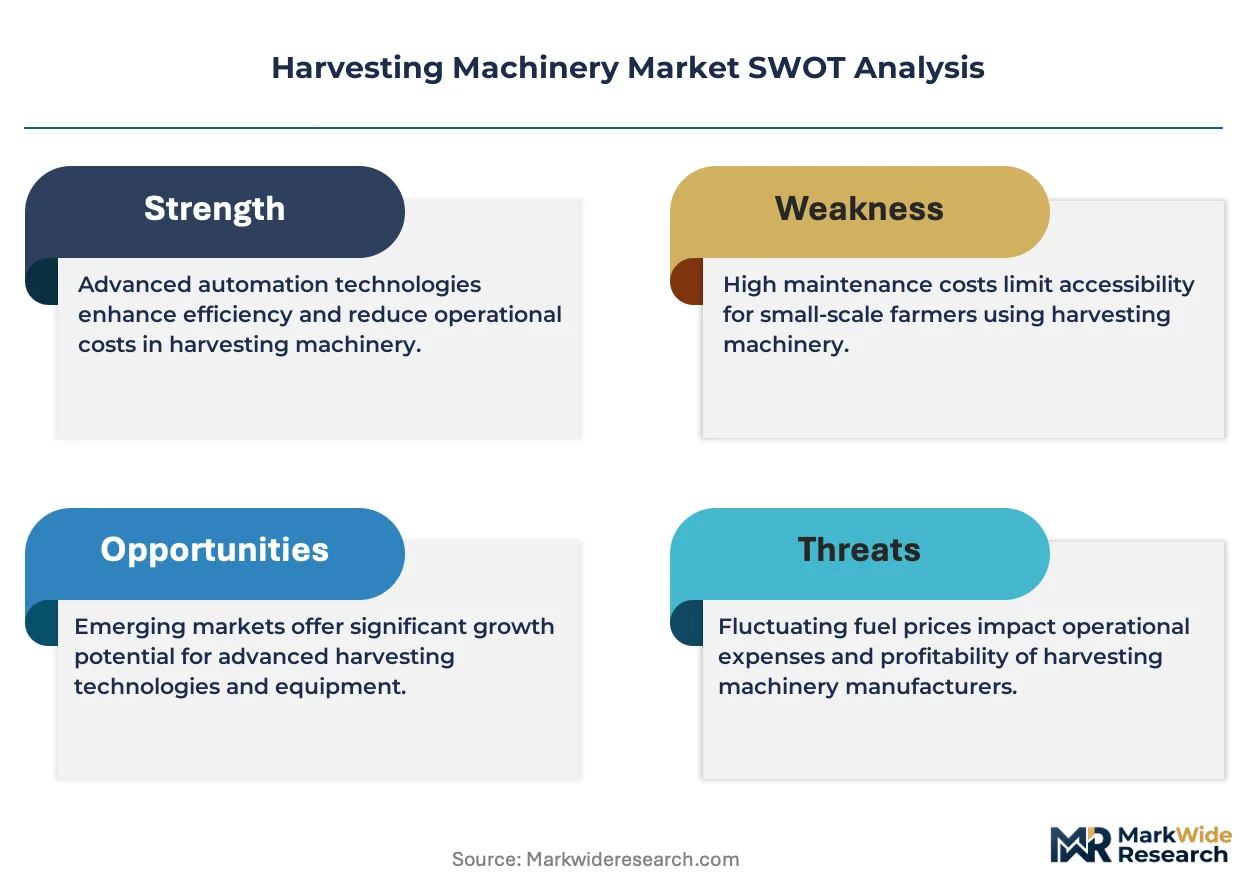
The pricing gap between conventional GPS-enabled systems and next-generation autonomous operation technology is significant. Pricing stratifies across premium, standard, and economy tiers, driven by advanced features like telematics and after-sales service bundles. High capital costs for modern combine harvesters create pricing pressure for smaller agricultural enterprises. Commercial Growers are least price-sensitive, valuing efficiency gains over upfront investment.
Supply Chain Analysis
Germany and the United States anchor high-precision component manufacturing for harvesting machinery. The supply chain draws from critical raw materials like specialized steels and advanced electronic components. Single-source vulnerability for specific mechatronic systems poses a structural risk. Distribution runs through extensive dealer networks and regional service centers, particularly in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The harvesting machinery market experiences a platform-economics inflection, driven by the emergence of integrated farm management software ecosystems. Interoperability across different equipment brands and data platforms is reshaping competitive positioning.
For Market Incumbents:Fortify existing dealer networks by investing in specialized technician training for autonomous systems. Deepen vertical integration into advanced sensor and AI development to counter emerging technology entrants. The persistent skilled labor scarcity and data interoperability challenges represent a named threat. Channel control through service bundling and financing options strengthens market position.
For New Entrants and Emerging Players:BIS certification fast-track for specialized equipment provides a market entry point into India's mechanizing regions. Target modular, affordable solutions for agricultural cooperatives and contract farmers in underpenetrated markets. Equipment-as-a-Service models offer a compelling go-to-market angle, reducing upfront capital expenditure for buyers. Focus on niche crop harvesting, such as sugarcane or potato, with tailored autonomous solutions.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors software-centric specialized equipment providers with strong IP in AI and robotics. Long-term viability over the next decade hinges on firms addressing labor shortages through automation. Seek acquisition targets demonstrating proven scalable autonomous platforms or robust telematics integration capabilities. The signal to watch is the widespread adoption of EaaS models by commercial growers.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Systems R&D | Accelerates labor displacement and optimizes 24/7 field operations for commercial growers. |
| EaaS Model Expansion | Reduces capital expenditure barriers for agricultural cooperatives, expanding market access. |
| Dealer Network Modernization | Enhances service capabilities for complex mechatronic systems across regional hubs. |
| Data Interoperability Standards | Fosters a connected farm ecosystem by integrating diverse equipment and software. |
| Electrification Component Sourcing | Addresses EPA Tier 4 Final and EU F-Gas regulations for powertrain development. |
Research Approach
A standing panel of OEM R&D directors, large-scale farm managers, dealer network heads, and agricultural economists provided ongoing calibration. This involved combining primary interviews with industry stakeholders and validating findings through extensive secondary data. Secondary sources included USDA reports, EU Green Deal policy documents, and BIS standards. Bottom-up and top-down triangulation ensured data consistency.
Forecast outputs were validated against external benchmarks, ensuring consistency across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, and end-user. CAGRs were derived through regression analysis of historical data and projected drivers. Key forecast inputs included crop yield projections and regional fleet modernization rates.
Decision-makers should treat outputs as directional under base assumptions regarding regulatory stability and agricultural commodity prices; material deviation would warrant model refresh. Forecasts reflect these assumptions. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
India Rice Milling Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Maize Milling Machine Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Meat Dicing Machine Market
Agricultural Processing Equipment
Meat and Poultry Processing Equipment Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Corn Thresher Market
Agricultural Processing Equipment
Japan Agricultural Shredder Machine Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Color Sorter Market
Agricultural Processing Equipment
Harvesting Equipment Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Global Dry Milling Market
Agricultural Processing Equipment
Harvesters Market