
 Puerto Rico Home Mortgage Finance Market | 2026-2036
Puerto Rico Home Mortgage Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Puerto Rico Home Mortgage Finance Market Outlook
Puerto Rico is fragmenting its mortgage finance infrastructure as lenders rebuild capacity after fiscal restructuring and natural disaster recovery cycles. Banco Popular anchors retail distribution through its island-wide branch network and deep community presence. First Bank competes aggressively on jumbo loan offerings for high-value properties in Dorado and Condado. Oriental Financial Group differentiates through digital origination platforms that reduce closing timelines for refinancing customers.
Puerto Rico home mortgage finance encompasses the origination, underwriting, servicing, and securitization of residential debt instruments collateralized by island properties, typically structured with 15- or 30-year amortization schedules and subject to both federal banking regulations and local property recording statutes. Fixed-rate mortgages sustain dominant volume share among risk-averse borrowers seeking payment predictability amid interest rate volatility, while FHA loans occupy critical niche importance for credit-constrained first-time buyers who rely on government-backed down payment assistance. Adjustable-rate mortgages attract investor segments targeting short-hold condominium rentals in San Juan's tourism corridor.
The Consumer Financial Protection Bureau enforces federal truth-in-lending and ability-to-repay standards that shape product design and disclosure requirements for all island originators. Puerto Rico's Office of the Commissioner of Financial Institutions supplements federal oversight with local licensing, escrow administration rules, and foreclosure timeline regulations that directly affect servicer cost structures. Stakeholders must monitor how proposed amendments to the Puerto Rico Mortgage Act could alter deficiency judgment procedures and reshape loss severity assumptions across loan size tiers.
Market Dynamics
Post-hurricane reconstruction capital and diaspora return migration are compressing origination timelines while stretching servicer capacity across Puerto Rico's fragmented lending infrastructure. The Federal Housing Administration's risk-sharing frameworks continue to dominate underwriting standards for entry-level borrowers.
Growth Catalysts
- Diaspora Return Capital:Puerto Rican professionals relocating from the US mainland inject liquidity into San Juan's condominium market, expanding jumbo loan demand.
- FHA Insurance Penetration:Federal down payment assistance programs enable credit-constrained first-time buyers to access 30-year fixed-rate products with reduced equity requirements.
- Digital Origination Platforms:Automated underwriting engines reduce closing timelines from 45 days to under 30 days for refinancing customers.
Market Restraints
- Collateral Valuation Volatility:Property appraisals in smaller municipalities fluctuate due to thin transaction volume, complicating loan-to-ratio calculations.
- Servicer Concentration Risk:Three institutions control over 60% of island mortgage servicing rights, creating systemic fragility during natural disaster events.
- Title Defect Backlogs:Puerto Rico's decentralized property registry generates lien clearance delays averaging 90 days.
Strategic Opportunities
- Ponce Metropolitan Expansion:Secondary city construction permits are accelerating, opening origination volume outside San Juan's saturated core.
- Green Retrofit Financing:Federal energy efficiency tax credits enable lenders to structure renovation mortgages for hurricane-resistant building upgrades.
- Credit Union Channel Development:Cooperative lending institutions are building correspondent relationships to reach municipal borrowers outside bank branch networks.
Industry Challenges
- Bilingual Underwriting Talent Scarcity:Loan officers fluent in Spanish and English command premium compensation, compressing originator margins.
- Legacy Core System Integration:Mainframe-based servicing platforms require costly middleware to connect with modern digital application portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Puerto Rico Home Mortgage Finance Market |
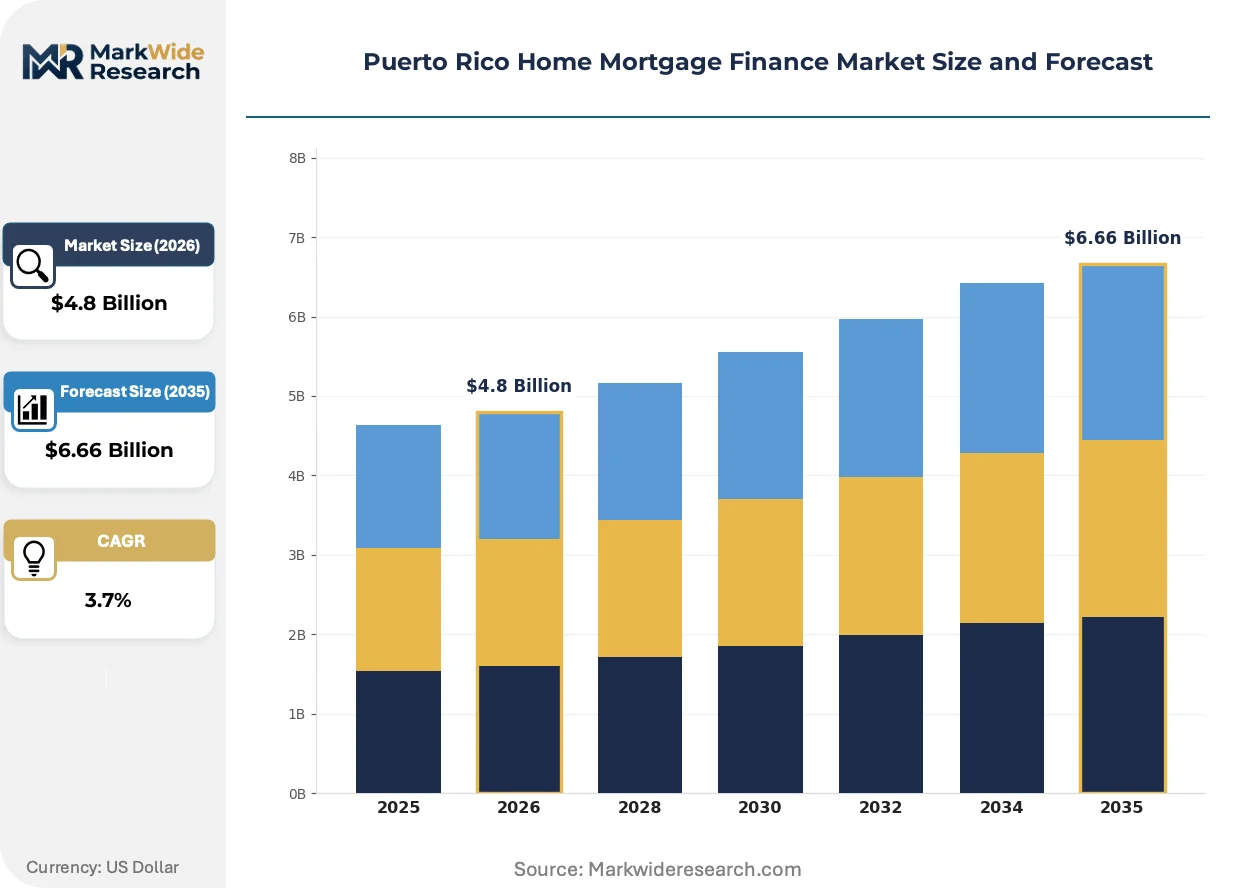
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fixed-Rate Mortgages, Adjustable-Rate Mortgages, Interest-Only Loans, FHA Loans Borrower Type: First-Time Buyers, Move-Up Buyers, Refinancers, Investors Loan Size: Small Loans, Medium Loans, Large Loans, Jumbo Loans Property Type: Single-Family Homes, Condominiums, Townhouses, Multi-Family Units |
| Companies Covered | Oriental Financial Group, First Bank, Banco Popular, Fembi Mortgage, Caribe Federal Credit Union, Banco Santander, Scotiabank, Pentagon Federal Credit Union, CITI Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Puerto Rico Home Mortgage Finance Market Strategic Shifts
Automated valuation models and alternative credit scoring are compressing traditional appraisal and FICO-dependent underwriting workflows across Puerto Rico's mortgage sector. These shifts promise to expand credit access while reducing origination friction.
Automated valuation models leverage satellite imagery and municipal tax records to estimate property collateral value without physical inspection. Regional banks serving Dorado and Condado high-value segments are adopting AVMs for refinancing transactions under 500,000 dollars. The technology is migrating from rate-term refinances toward purchase-money originations, compressing appraisal costs by 40%.
The Consumer Financial Protection Bureau's 2023 rescission of the Qualified Mortgage patch eliminates the 43% debt-to-income ratio cap for GSE-eligible loans. Puerto Rico originators must now calibrate proprietary underwriting overlays to manage portfolio risk. FHA-insured products face the most significant recalibration as servicers adjust pricing for loans exceeding the former threshold.
First-time buyers are abandoning branch-based application processes in favor of mobile-optimized digital platforms with real-time status tracking. Credit unions and community banks are losing origination share to national lenders with streamlined pre-approval engines. The behavioral shift is most pronounced among borrowers under 35 in the San Juan metropolitan area.
Puerto Rico Home Mortgage Finance Market Segmentation
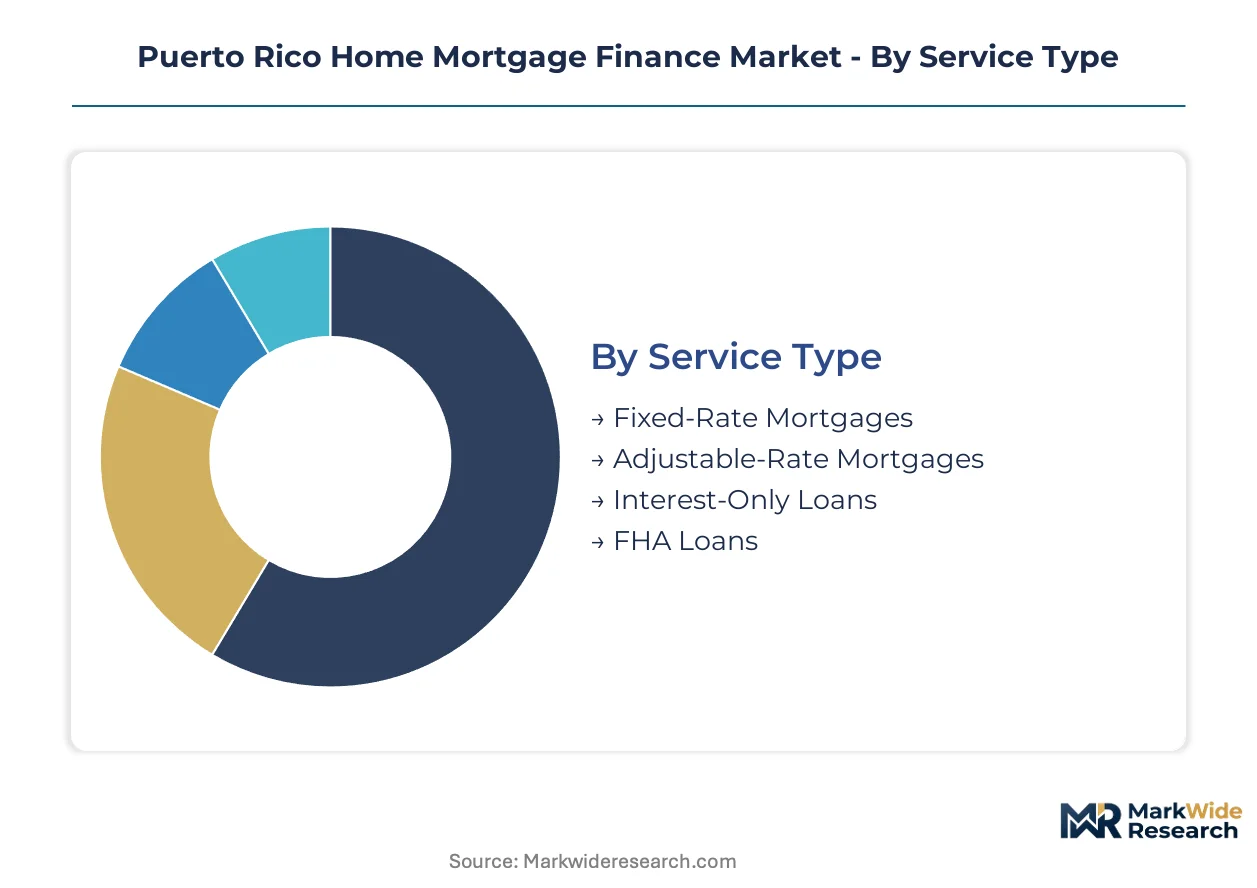
Segmentation reveals how Puerto Rico's mortgage infrastructure fragments across risk profiles, borrower life cycles, and collateral types. Lenders calibrate pricing, servicing intensity, and capital allocation differently across each slice.
Service Type:
Servicing complexity and default resolution costs vary dramatically across product structures, driving divergent profitability profiles.
- Fixed-Rate Mortgages:Amortizing loans with locked interest rates across 15- or 30-year terms dominate volume in San Juan's stable employment corridors. Borrowers sacrifice rate flexibility for payment predictability amid Federal Reserve volatility.
- Adjustable-Rate Mortgages:Hybrid structures with initial fixed periods transitioning to floating rates attract Dorado and Condado investors targeting short-hold condominium rentals. Rate reset risk concentrates in tourism-dependent cash flow profiles.
- Interest-Only Loans:Deferred principal repayment structures serve high-net-worth borrowers with irregular income streams, requiring specialized underwriting overlays.
- FHA Loans:Federal insurance backing enables reduced down payment requirements for credit-constrained first-time buyers in Ponce and secondary municipalities.
Fixed-Rate Mortgages holds the largest share; momentum sits with FHA Loans as entry-level demand expands.
Borrower Type:
Customer acquisition costs and lifetime value calculations shift substantially across origination motivations and repeat transaction potential.
- First-Time Buyers:Entry-level borrowers relying on down payment assistance programs and government-backed insurance. Concentrated in San Juan's affordable condominium stock and Ponce's emerging construction zones.
- Move-Up Buyers:Existing homeowners trading equity-appreciated properties for larger collateral, typically financing through conventional products with stronger credit profiles.
- Refinancers:Rate-sensitive borrowers responding to spread compression, demanding rapid digital closing timelines from competing originators.
- Investors:Non-owner-occupied purchasers targeting rental yield in San Juan's tourism corridor, facing stricter debt-to-income overlays and higher rate pricing.
First-Time Buyers anchors volume concentration; Refinancers are expanding most quickly as rate volatility triggers transaction surges.
Loan Size:
Capital requirements and secondary market execution differ markedly across conforming limits and portfolio retention thresholds.
- Small Loans:Sub-conforming balances common in rural municipalities and aging housing stock, carrying disproportionate origination cost-to-balance ratios.
- Medium Loans:Core middle-market segment aligning with GSE conforming limits, driving standardization in underwriting and servicing infrastructure.
- Large Loans:Super-conforming balances requiring portfolio retention or private label execution, concentrated in San Juan metropolitan appreciation corridors.
- Jumbo Loans:Non-conforming balances exceeding federal limits, dominating Dorado and Condado luxury segments with bespoke underwriting and relationship pricing.
Medium Loans commands the deepest origination infrastructure; Jumbo Loans carries the steepest expansion trajectory as diaspora return capital concentrates in premium collateral.
Property Type:
Collateral risk assessment and insurance requirements fragment sharply across residential structure categories.
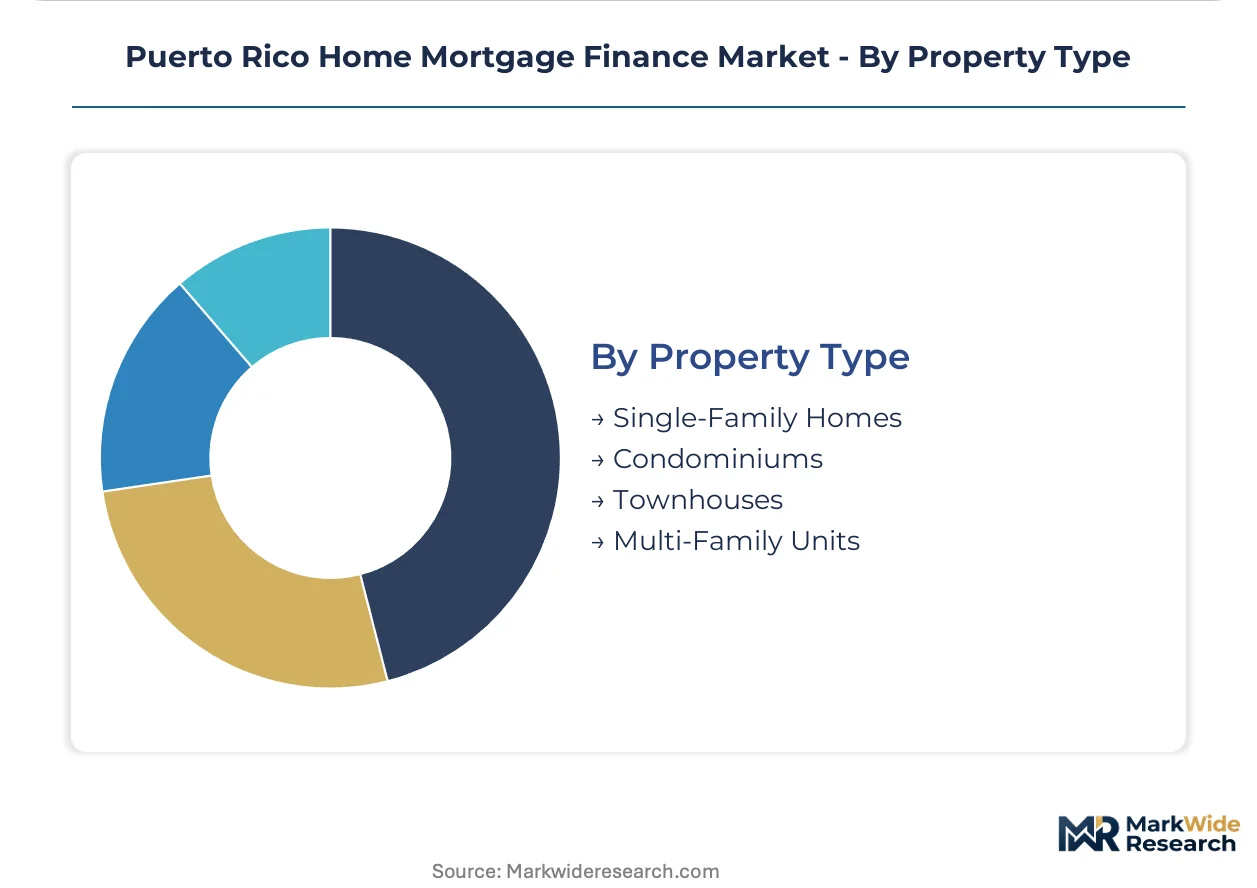
- Single-Family Homes:Detached and semi-detached structures dominating Puerto Rico's interior municipalities, carrying concentrated hurricane exposure and reconstruction cost volatility.
- Condominiums:Multi-unit buildings with homeowners association governance, prevalent in San Juan's dense urban core and coastal tourism zones. Master policy dependencies complicate underwriting.
- Townhouses:Attached single-family structures blending density with ownership control, expanding in Ponce metropolitan construction permits.
- Multi-Family Units:Duplex through quadplex structures attracting investor financing, subject to commercial appraisal standards and rental income verification.
Single-Family Homes retains the broadest geographic distribution; Condominiums gains share fastest as urban density preferences intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three institutions control over sixty percent of island mortgage servicing rights, creating geographic concentration that amplifies systemic fragility during natural disaster events. Lending activity concentrates disproportionately in the San Juan metropolitan corridor where property values and transaction velocity outpace smaller municipalities.
San Juan Metropolitan Area
Diaspora return capital from Puerto Rican professionals relocating from the US mainland injects liquidity into San Juan's condominium market, expanding jumbo loan demand. The Consumer Financial Protection Bureau enforces federal truth-in-lending standards that shape product design for all originators operating in the capital corridor. Dorado and Condado sub-markets attract aggressive jumbo loan competition from banks targeting high-value coastal properties.
Ponce Metropolitan Zone
Secondary city construction permits are accelerating, opening origination volume outside San Juan's saturated core. Puerto Rico's Office of the Commissioner of Financial Institutions supplements federal oversight with local licensing requirements affecting new market entrants. Municipal borrowers in Ponce's emerging construction zones increasingly access credit through cooperative lending institutions building correspondent relationships.
Mayagüez and Western Municipalities
Rural sub-conforming loan balances carry disproportionate origination cost-to-balance ratios that compress lender margins. Title defect backlogs from Puerto Rico's decentralized property registry generate lien clearance delays averaging ninety days in western districts. Aging housing stock in interior municipalities drives demand for renovation mortgages structured around federal energy efficiency tax credits.
Caguas and Eastern Corridor
First-time buyers concentrated in affordable condominium developments rely on Federal Housing Administration down payment assistance programs. The Puerto Rico Mortgage Act's proposed amendments to deficiency judgment procedures are reshaping loss severity assumptions for eastern originators. Caguas anchors a growing cluster of digital-first lenders leveraging automated underwriting engines to compress closing timelines.
Arecibo and Northern Coast
Detached single-family structures dominating northern interior municipalities carry concentrated hurricane exposure and reconstruction cost volatility. Federal emergency management reconstruction capital has compressed origination timelines while stretching servicer capacity across fragmented lending infrastructure. Arecibo's thin transaction volume generates property appraisal fluctuations that complicate loan-to-value calculations for regional lenders.
Puerto Rico Home Mortgage Finance Market Competitive Environment
Island-wide retail banks and specialized mortgage originators split the market between relationship-driven distribution and digital-first acquisition strategies. The competitive structure reflects post-hurricane consolidation where fiscal restructuring and natural disaster recovery cycles forced smaller participants to exit. Two strategic archetypes dominate: branch-network incumbents leveraging deep community presence, and technology-enabled challengers reducing friction through automated platforms. Competitive intensity manifests through correspondent relationship expansion and digital origination platform deployment.
Within the branch-network tier, Banco Popular anchors retail distribution through its island-wide physical presence, while Oriental Financial Group exemplifies the digital-first archetype through automated origination platforms. First Bank occupies a position between these poles, competing aggressively on jumbo loan offerings for premium collateral segments. These three institutions collectively represent the concentration risk visible across Puerto Rico's mortgage servicing infrastructure, with their strategic positioning reflecting divergent bets on physical versus digital customer acquisition.
| Leading Market Players |
|---|
| Oriental Financial Group |
| First Bank |
| Banco Popular |
| Fembi Mortgage |
| Caribe Federal Credit Union |
| Banco Santander |
| Scotiabank |
| Pentagon Federal Credit Union |
| CITI Bank |
| Others |
Value Chain & Pricing Dynamics
San Juan's concentrated origination infrastructure concentrates pricing power among three dominant servicers who control over sixty percent of island mortgage servicing rights. Their scale advantages in escrow administration and default resolution translate into rate-setting influence that smaller regional banks struggle to match.
Pricing Analysis
The Consumer Financial Protection Bureau's truth-in-lending standards dictate the pricing tier structure across Puerto Rico's mortgage sector, mandating standardized disclosure frameworks that compress rate opacity. Pricing stratifies across relationship-driven jumbo offerings, standardized conforming products, and government-insured entry-level tiers. Cost compression in the conforming segment is intensifying because digital-first originators are automating underwriting workflows and slashing origination overhead. First-time buyers accessing FHA-backed products exhibit the highest price sensitivity, while diaspora return investors purchasing Dorado luxury collateral demonstrate minimal rate elasticity.
Supply Chain Analysis
Fannie Mae and Freddie Mac's secondary market execution platforms hold dominant capacity in Puerto Rico's mortgage supply chain, with portfolio lenders and private label conduits filling non-conforming niches. Geographic supply concentration spans mainland US securitization hubs, Puerto Rico-based correspondent aggregators, and offshore reinsurance markets handling hurricane risk. The supply chain draws from credit bureau data providers, automated valuation model vendors, and title insurance underwriters as critical inputs. Single-source vulnerability in hurricane catastrophe reinsurance represents the dominant structural risk. Distribution runs through retail branch networks, digital direct-to-consumer platforms, and credit union correspondent channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Puerto Rico's mortgage market operates as a cyclical recovery play, with diaspora return migration and post-hurricane reconstruction capital providing the demand pulse.
For Market Incumbents: Build regulatory compliance moats through bilingual underwriting talent acquisition and automated servicing platform integration. Banco Popular and Oriental Financial Group should consolidate correspondent relationships with credit unions to preempt digital challengers from capturing municipal origination share. Escrow administration automation and hurricane-resistant collateral appraisal expertise represent defensible capability investments against fintech entrants. For New Entrants and Emerging Players: Mid-market commercial renovation financing in Ponce's emerging construction zones represents the most penetrable entry point for specialized lenders lacking San Juan branch density. Green retrofit mortgages structured around federal energy efficiency tax credits offer a policy-aligned origination angle with limited incumbent competition. Credit union correspondent partnerships enable rapid geographic coverage without physical infrastructure investment. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because servicing scale advantages compound through natural disaster recovery cycles and regulatory compliance cost absorption. Acquisition targets should emphasize automated valuation model capabilities and digital closing infrastructure over traditional branch networks. The signal to watch is FHA insurance penetration rates in secondary municipalities as an indicator of entry-level demand sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Origination Platform Deployment | Oriental Financial Group's automated underwriting reduces closing timelines from 45 days to under 30 days. |
| Credit Union Correspondent Expansion | Cooperative lending institutions extend reach into municipal borrowers outside traditional bank branch networks. |
| Green Retrofit Financing Program | Federal energy efficiency tax credits enable renovation mortgages for hurricane-resistant building upgrades. |
| Bilingual Underwriting Talent Acquisition | Loan officers fluent in Spanish and English command premium compensation that compresses originator margins. |
| Servicing Rights Consolidation | Three institutions controlling over sixty percent of island servicing creates systemic fragility during natural disaster events. |
Study Parameters
The analysis maps fixed-rate mortgage origination, FHA-insured lending, jumbo portfolio retention, and digital refinancing channels, each validated through primary interviews with mortgage servicing executives, regulatory compliance officers at Puerto Rico's Office of the Commissioner of Financial Institutions, credit union lending directors, and diaspora return borrower panels. Secondary validation draws from Consumer Financial Protection Bureau enforcement actions, Federal Housing Administration insurance penetration reports, Puerto Rico construction permit databases, and municipal property transaction records. Bottom-up loan-level origination data triangulates against top-down market sizing from secondary market execution volumes.
Assumptions held fixed across the projection horizon include federal housing policy continuity, GSE conforming limit indexing, and Puerto Rico's territorial tax treatment of mortgage interest deductions. Variables modeled across the analysis window encompass diaspora return migration velocity, hurricane reconstruction capital flows, and digital adoption rates among first-time buyers. Segmentation dimensions span product structure, borrower life cycle stage, loan size tier, and collateral type. CAGRs derive from regression analysis against historical origination volume patterns and macroeconomic drivers including employment growth and interest rate volatility.
Practitioners should monitor proposed amendments to the Puerto Rico Mortgage Act and Federal Reserve rate trajectory for early signals of forecast revision. Quarterly review of FHA insurance penetration rates, construction permit acceleration in secondary municipalities, and automated valuation model adoption curves is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Latin America Commercial Real Estate Market
Real Estate
United Arab Emirates Facility Management Market
Real Estate
Asia-Pacific Self Storage Market
Real Estate
Asia-Pacific Soft Facility Management Market
Real Estate
Bahrain Co-Working Office Space Market
Real Estate
China Flexible Office Space Market
Real Estate
Saudi Arabia Co-Working Office Spaces Market
Real Estate
United States Co-Working Office Space Market
Real Estate
Mortgage Brokerage Services Market
Real Estate
Japan Luxury Residential Real Estate Market
Real Estate
China Residential Real Estate Market
Real Estate
Warehouse Management Service Market
Real Estate
France Condominiums and Apartments Market
Real Estate
Japan Manufactured Homes Market
Real Estate
Saudi Arabia Residential Real Estate Market
Real Estate
US Real Estate and Hospitality Market