
 Mortgage Brokerage Services Market | 2026-2036
Mortgage Brokerage Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mortgage Brokerage Services Market Analysis
Wholesale lending capacity in the United States is recalibrating as interest rate volatility compresses origination volumes and forces broker networks to diversify funding sources. United Wholesale Mortgage leverages its pure wholesale model to sustain broker loyalty through technology investment and pricing consistency. Rocket Mortgage competes by controlling direct-to-consumer digital channels while maintaining selective broker partnerships. CrossCountry Mortgage specializes in purchase-money originations, anchoring its position in markets where refinancing activity has declined sharply.
Mortgage brokerage services encompass intermediary functions that match borrowers with lenders, coordinate documentation collection, manage underwriting communication, and facilitate loan closing through compliance-managed workflows. The service operates across loan origination software platforms that integrate credit scoring APIs, automated valuation models, and regulatory disclosure engines to compress cycle times from application to funding. Online brokerage platforms represent the fastest-growing service type as consumer preference shifts toward self-service rate comparison and digital document submission. Hybrid brokerage models capture margin pools by combining automated pre-approval engines with licensed loan officer consultation for complex credit profiles. Traditional brokerage retains structural importance in purchase transactions where local market knowledge and realtor relationships determine referral flow.
The Consumer Financial Protection Bureau enforces Loan Originator Compensation rules that reshape broker revenue structures and restrict yield-spread premium arrangements. FHA and VA loan programs administered through the Department of Housing and Urban Development and the Department of Veterans Affairs establish product standards that brokers must navigate to serve first-time and military borrower segments. State-level licensing regimes through the Nationwide Multistate Licensing System create compliance barriers that favor scaled brokerages with dedicated compliance infrastructure. Stakeholders must monitor regulatory proposals around broker compensation transparency and GSE fee structure adjustments that could redistribute volume between retail and wholesale origination channels.
Market Dynamics
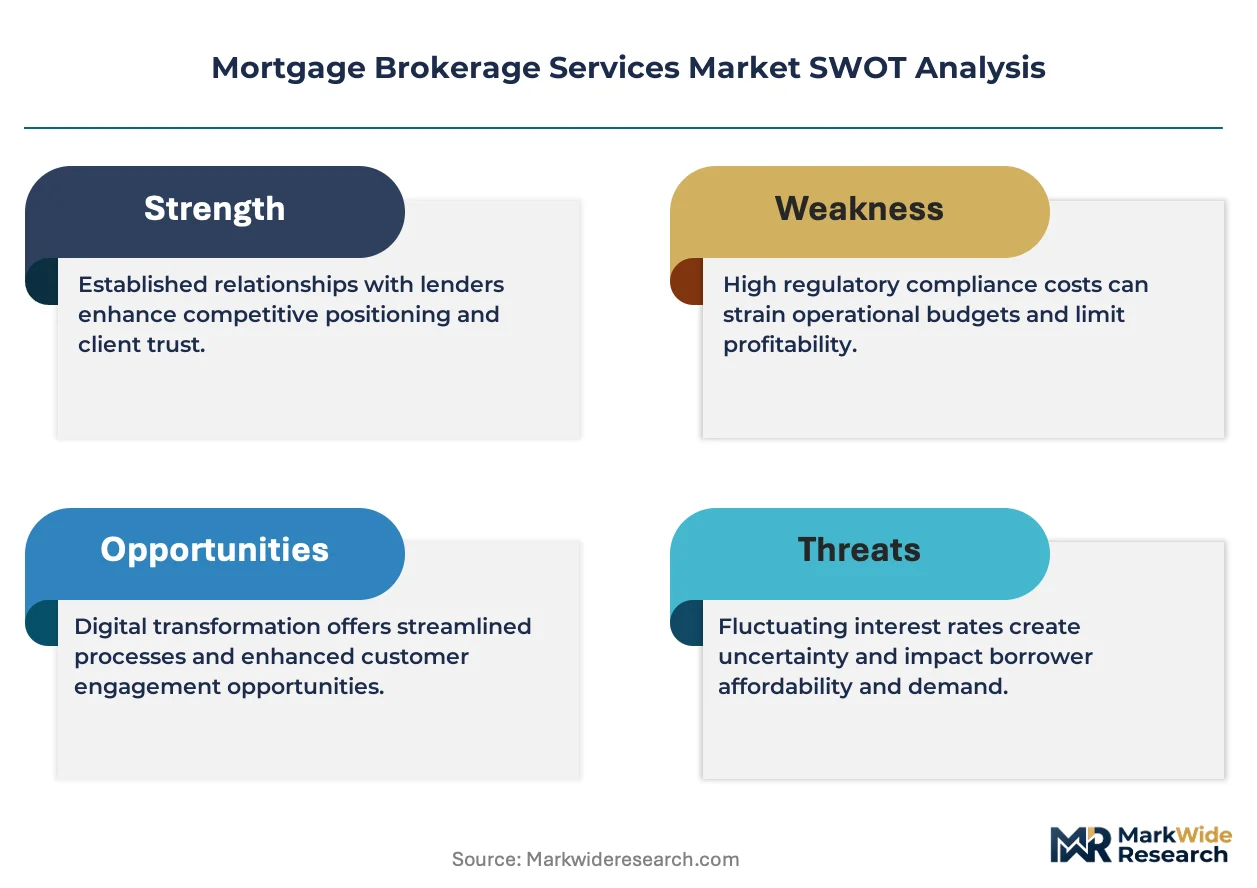
Interest rate volatility is compressing origination margins and forcing broker networks to rebuild technology stacks around API-first loan origination platforms. Wholesale lending relationships now hinge on pricing consistency and automated underwriting speed rather than traditional commission structures.
Growth Catalysts
- FHA and VA loan program expansion:Federal housing agencies are broadening eligibility criteria for first-time and military borrowers, channeling volume through broker networks certified for government-backed products.
- Automated valuation models:AVM integration into loan origination software is collapsing appraisal turnaround times from weeks to days, accelerating broker throughput in purchase-heavy markets.
- Independent broker network consolidation:United States wholesale channels are capturing share from retail bank origination as rate shopping behavior favors multi-lender comparison platforms.
Market Restraints
- Yield-spread premium restrictions:Consumer Financial Protection Bureau compensation rules cap broker revenue flexibility and compress fee structures on conventional products.
- Interest rate volatility:Federal Reserve policy uncertainty is destroying refinancing pipelines and forcing brokers to rebuild purchase-money specialization.
- State licensing fragmentation:Nationwide Multistate Licensing System compliance costs favor scaled brokerages and squeeze independent operators in high-barrier states.
Strategic Opportunities
- Digital-first borrower segments:Self-service rate comparison platforms are capturing millennials and Gen Z applicants who bypass traditional referral channels entirely.
- Non-QM product specialization:Non-qualified mortgage programs for self-employed and investment-property borrowers offer premium pricing outside agency constraints.
- API ecosystem convergence:Open banking data feeds and alternative credit scoring APIs enable broker pre-approval engines for thin-file borrowers.
Industry Challenges
- Loan officer licensing pipeline:State-specific education requirements and testing backlogs constrain broker capacity expansion in high-volume markets.
- Legacy LOS integration:Mortgage origination software from the 2000s requires costly middleware to connect modern pricing engines and document management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mortgage Brokerage Services Market |
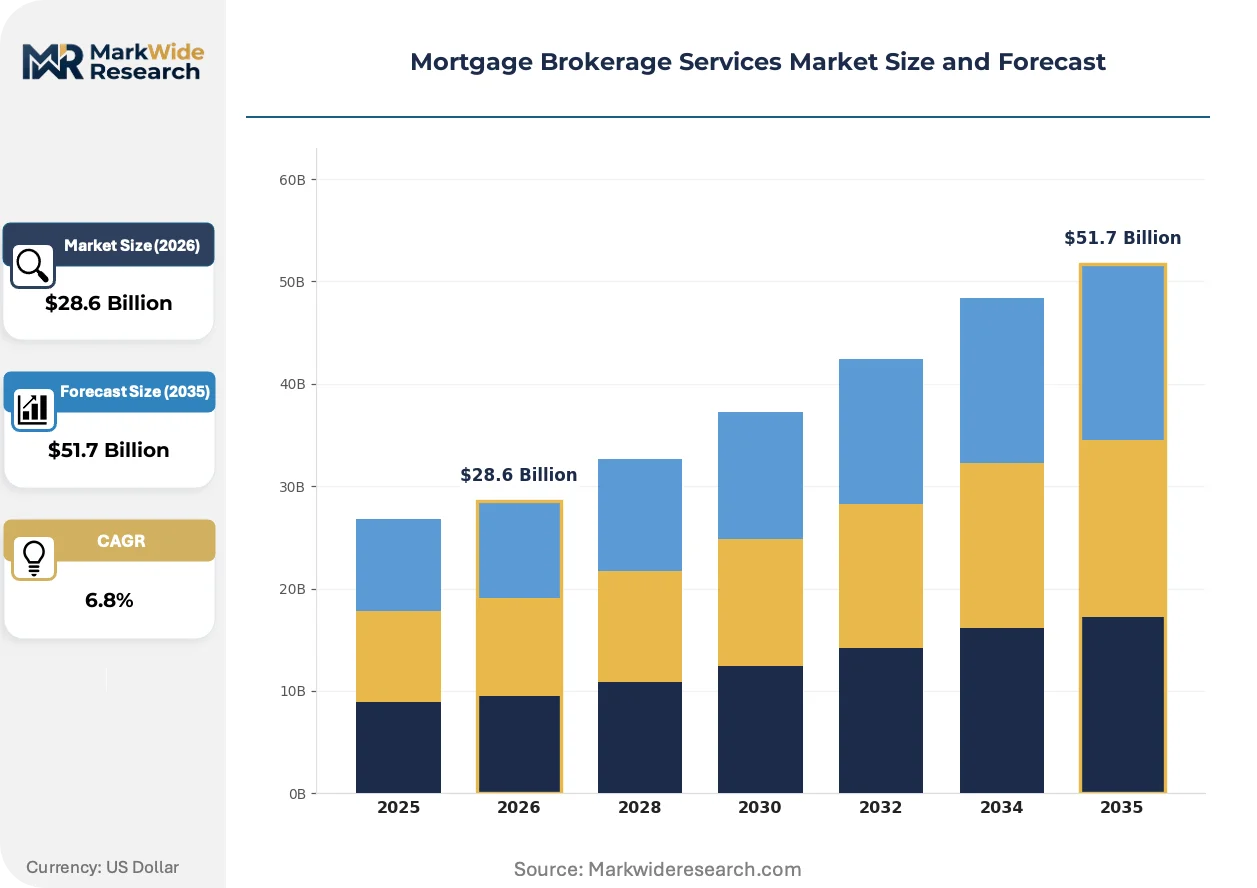
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Traditional Brokerage, Online Brokerage, Hybrid Brokerage, Consulting Services Customer Type: First-time Buyers, Real Estate Investors, Refinancers, Commercial Clients Loan Type: Fixed-rate Mortgages, Adjustable-rate Mortgages, FHA Loans, VA Loans Brokerage Model: Independent Brokers, Franchise Brokers, Mortgage Banks, Credit Unions |
| Companies Covered | United Wholesale Mortgage, Rocket Mortgage, CrossCountry Mortgage, Fairway Independent Mortgage, Guaranteed Rate, LoanDepot, Caliber Home Loans, NEXA Mortgage, C2 Financial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mortgage Brokerage Services Market Emerging Trajectories
Digital mortgage platforms are collapsing the traditional broker workflow into seamless, mobile-first experiences. Technology investment now separates surviving brokerages from those losing share to direct-to-consumer lenders.
Artificial intelligence-powered document extraction is rewriting how brokers process income verification and asset statements. Purchase-heavy brokerages are deploying these tools to compress cycle times from application to clear-to-close. The technology is rewriting competitive positioning by enabling smaller broker networks to match the throughput of scaled retail operations.
Consumer Financial Protection Bureau disclosure rule updates are mandating granular fee transparency in loan estimates. Brokers must restructure compensation agreements and upgrade point-of-sale systems to display real-time pricing comparisons. Purchase transactions in high-cost states face the steepest compliance adaptation costs.
Self-service rate locks and digital document submission are displacing phone-based application intake. First-time buyer segments favor platforms offering instant pre-qualification without loan officer interaction. This pattern is most visible in Sun Belt metropolitan markets where tech-forward brokerages are capturing referral relationships from traditional realtor networks.
Mortgage Brokerage Services Market Segmentation
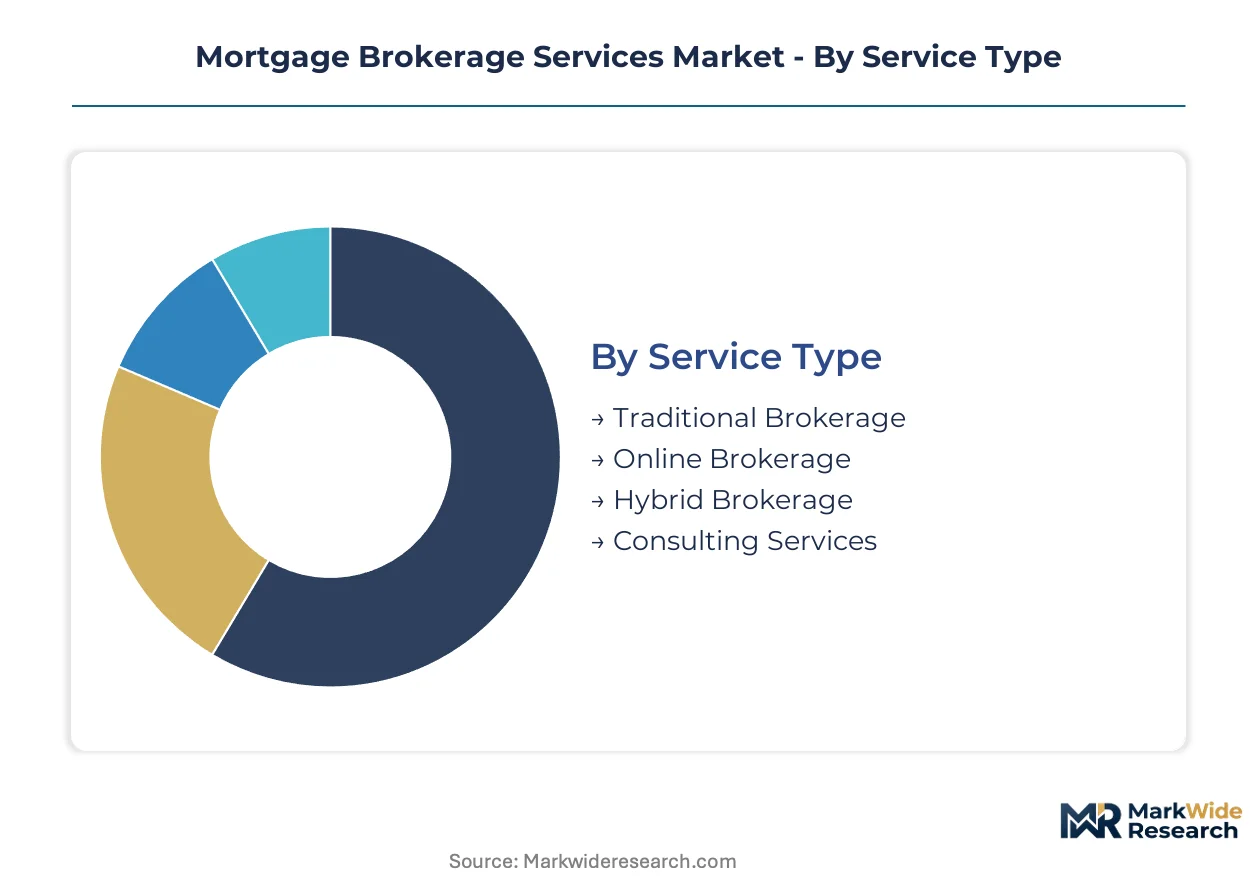
Segmentation in mortgage brokerage services reveals how technology adoption, borrower demographics, and regulatory frameworks reshape competitive positioning across distinct service delivery models. Understanding these divides exposes where capital allocation and compliance investment generate sustainable margin protection.
Service Type:
Technology integration depth separates service architectures and determines operational scalability across broker networks.
- Traditional Brokerage:Licensed loan officers manage end-to-end borrower relationships through face-to-face consultation and manual document collection. Purchase transactions in high-cost metropolitan markets sustain this model where realtor referral networks and local market expertise command premium placement fees.
- Online Brokerage:Self-service platforms automate rate comparison, pre-qualification, and document submission through mobile-optimized interfaces. Sun Belt metropolitan areas concentrate adoption among millennial and Gen Z first-time buyers who bypass traditional referral channels entirely.
- Hybrid Brokerage:Automated pre-approval engines route complex credit profiles to licensed consultants, capturing margin pools from both efficiency and advisory fees. This architecture expands most quickly in markets with heterogeneous borrower credit distributions.
- Consulting Services:Fee-based advisory for self-employed borrowers and investment property specialists navigating non-agency product structures. Demand clusters in high-cost states where jumbo and non-QM volume exceeds conventional conforming limits.
Traditional brokerage leads on scale; online brokerage leads on momentum.
Customer Type:
Borrower lifecycle position dictates product mix, referral channel preferences, and sensitivity to interest rate movements.
- First-time Buyers:FHA and VA program eligibility drives origination volume through broker networks certified for government-backed products. Federal housing agency expansion of down payment assistance programs channels this segment toward wholesale lending channels with dedicated compliance infrastructure.
- Real Estate Investors:Non-qualified mortgage products for debt-service-coverage-ratio and bank-statement qualification attract premium pricing. This category climbs the fastest as rental property acquisition accelerates in Sun Belt growth corridors.
- Refinancers:Rate-sensitive borrowers with existing equity seeking term reduction or cash-out extraction. Federal Reserve policy uncertainty has collapsed this pipeline and forced brokers to rebuild purchase-money specialization.
- Commercial Clients:Multi-property portfolios and small-balance commercial real estate requiring specialized underwriting and escrow coordination. Volume concentrates through franchise broker networks with dedicated commercial lending divisions.
First-time buyers anchor volume stability; real estate investors drive margin expansion.
Loan Type:
Interest rate structure and federal guarantee status determine capital source access and broker compensation mechanics.
- Fixed-rate Mortgages:Thirty-year and fifteen-year amortization schedules with rate locks protecting borrowers from Federal Reserve policy shifts. This product category maintains dominant share in purchase-heavy markets where payment certainty outweighs initial rate savings.
- Adjustable-rate Mortgages:Hybrid structures with fixed introductory periods transitioning to indexed floating rates. Demand revives in high-rate environments where initial affordability gaps determine transaction feasibility.
- FHA Loans:Federal Housing Administration insurance enabling low down payment access for credit-constrained borrowers. Brokers must maintain specific certifications and navigate Department of Housing and Urban Development appraisal requirements.
- VA Loans:Department of Veterans Affairs guarantee eliminating down payment requirements for eligible military borrowers. Volume concentrates near military installations and through broker networks with dedicated veteran outreach programs.
Fixed-rate mortgages dominate origination volume; adjustable-rate mortgages gain share fastest in rate-volatile cycles.
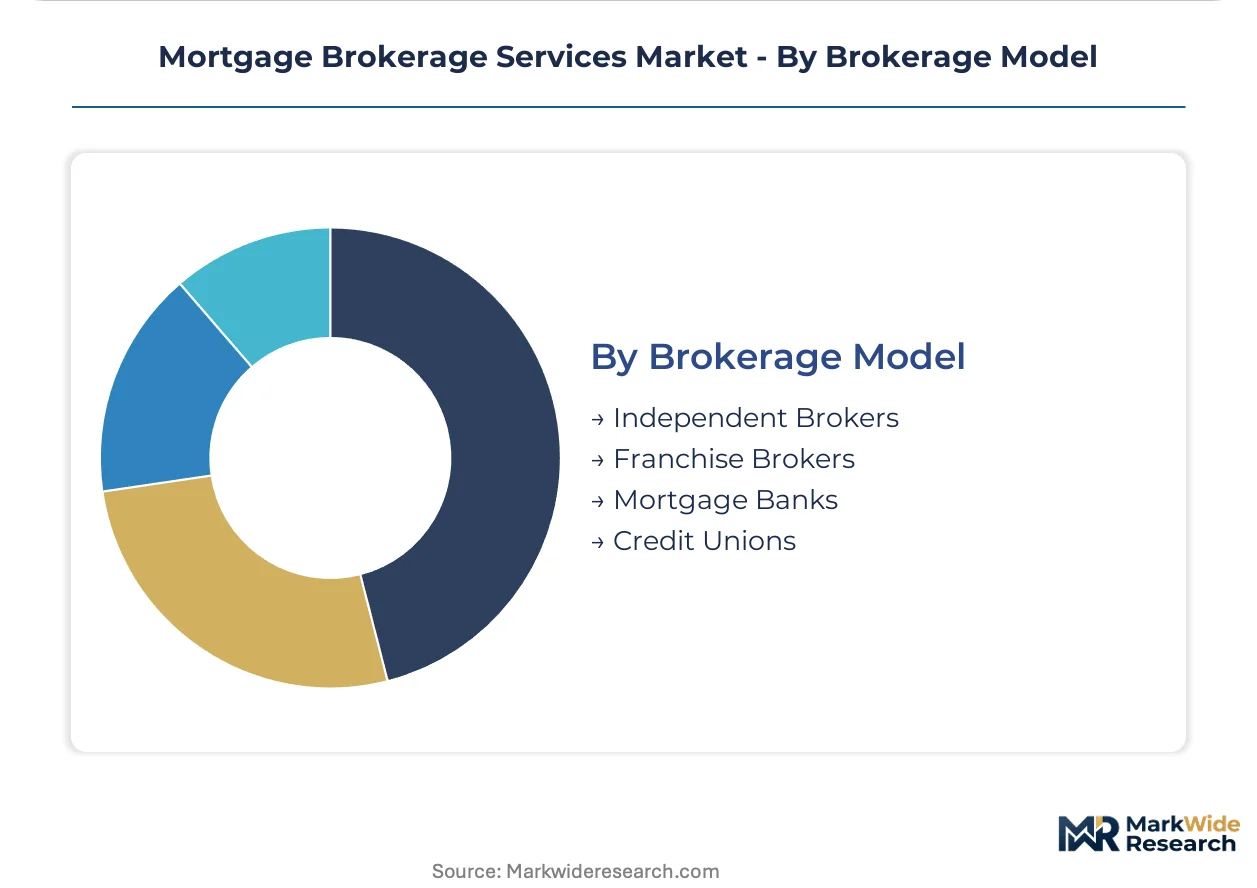
Brokerage Model:
Capital structure and funding source control separate organizational architectures and determine regulatory burden distribution.
- Independent Brokers:Non-depository originators accessing multiple wholesale lenders through correspondent relationships. Consumer Financial Protection Bureau compensation rules and state licensing fragmentation favor scaled operators with dedicated compliance infrastructure.
- Franchise Brokers:National brand networks providing technology platforms, marketing support, and centralized compliance management. This model captures share from retail bank origination as rate shopping behavior favors multi-lender comparison.
- Mortgage Banks:Balance-sheet lenders with captive origination capacity and direct secondary market access. Wholesale lending capacity recalibration has compressed margins and forced selective broker partnership strategies.
- Credit Unions:Member-owned depository institutions with portfolio lending capacity and relationship-driven origination. Purchase transactions in community-focused markets sustain this channel despite technology investment gaps.
Franchise brokers lead on network expansion velocity; independent brokers lead on pricing flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping mortgage brokerage distribution as compliance cost differentials between jurisdictions drive network consolidation and technology platform migration. Broker networks concentrate where licensing reciprocity agreements reduce operational friction and wholesale lending capacity remains accessible.
United States
Independent broker networks capture volume from retail bank contraction as rate shopping behavior intensifies. The Consumer Financial Protection Bureau enforces Loan Originator Compensation rules that reshape revenue structures across wholesale channels. Sun Belt metropolitan markets including Phoenix, Dallas-Fort Worth, and Atlanta anchor expansion as first-time buyer programs broaden access through FHA-certified broker networks.
Canada
Mortgage stress test requirements administered by the Office of the Superintendent of Financial Institutions channel borrowers toward broker-led rate comparison platforms. Provincial licensing fragmentation through the Mortgage Brokers Regulators Council of Canada creates compliance barriers favoring scaled operators with national technology infrastructure. The Greater Toronto Area and Vancouver metropolitan corridors concentrate brokerage activity where housing affordability stress sustains refinancing and purchase-money specialization.
United Kingdom
Financial Conduct Authority mortgage conduct rules mandate advised sales processes that sustain intermediary channel relevance. The Financial Services Compensation Scheme coverage limits reinforce consumer trust in broker-mediated transactions. London and Southeast England anchor network density where complex income profiles and high-value transactions demand advisory specialization beyond direct-to-lender channels.
Australia
Australian Securities and Investments Commission best interest duty obligations reshape broker remuneration transparency and consumer disclosure requirements. The National Consumer Credit Protection Act licensing framework favors aggregator-backed networks with centralized compliance management. Sydney and Melbourne metropolitan markets concentrate brokerage activity where mortgage broker market share exceeds direct bank origination.
Germany
Federal Financial Supervisory Authority intermediation rules govern broker fee disclosure and consumer protection standards. The Mortgage Credit Directive implementation creates pan-European licensing considerations for cross-border service provision. Frankfurt and Munich financial centers anchor commercial mortgage brokerage specialization serving corporate real estate and institutional investor segments.
Mortgage Brokerage Services Market Vendor Landscape
United States producers anchor the wholesale lending tier; Canadian and Australian specialists hold advisory-dominated positions in markets with stronger intermediary regulatory protection. Market structure fragments across three operational archetypes: pure wholesale lenders with technology-first broker support, hybrid direct-to-consumer platforms maintaining selective broker partnerships, and independent broker networks aggregating multi-lender access. Dominant competitive moves include API ecosystem convergence for loan origination automation and strategic consolidation of independent broker networks under franchise brands.
Within the pure wholesale tier, United Wholesale Mortgage exemplifies technology investment and pricing consistency as competitive anchors. Rocket Mortgage occupies a position spanning direct-to-consumer digital channels with selective broker partnership retention. CrossCountry Mortgage represents purchase-money specialization archetype, anchoring positioning in markets where refinancing activity has compressed. These three entities collectively illustrate how funding source control, technology platform depth, and product segment focus separate sustainable positioning from share erosion.
| Leading Market Players |
|---|
| United Wholesale Mortgage |
| Rocket Mortgage |
| CrossCountry Mortgage |
| Fairway Independent Mortgage |
| Guaranteed Rate |
| LoanDepot |
| Caliber Home Loans |
| NEXA Mortgage |
| C2 Financial |
| Others |
Supply Flow & Price Mechanics
Wholesale lender rate sheets and broker compensation splits cascade through three distinct pricing tiers, with technology-enabled platforms commanding premium placement fees while traditional referral-dependent brokers absorb margin compression from yield-spread restrictions.
Pricing Analysis
Broker network compensation splits separate wholesale pricing tiers, with independent operators retaining larger per-loan margins against franchise networks trading margin for technology platform access. Price differentiation rests on automated underwriting speed and multi-lender comparison capability rather than manual advisory depth. Cost compression in conventional conforming products is intensifying because Consumer Financial Protection Bureau compensation rules cap yield-spread arrangements. First-time buyers accessing FHA and VA programs demonstrate highest price sensitivity, while self-employed borrowers navigating non-QM structures accept premium pricing for specialized qualification pathways.
Supply Chain Analysis
Capital market funding rests on Wall Street investment banks, government-sponsored enterprise securitization channels, and private label conduits for non-agency product placement. Wholesale lending capacity draws from United States warehouse line providers, correspondent banking relationships, and balance-sheet lenders with direct secondary market access. Single-source vulnerability concentrates in GSE fee structure dependencies that redistribute volume between retail and wholesale origination channels. Distribution runs through multi-lender pricing engines, loan origination software platforms, and direct broker-lender correspondent agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mortgage brokerage services function as a stable compounder anchored by persistent housing transaction velocity and recurring refinancing cycles driven by Federal Reserve policy shifts.
For Market Incumbents: Lock in broker loyalty through API-first loan origination platform investments that compress cycle times from application to clear-to-close. Secure exclusive correspondent relationships with wholesale lenders offering pricing consistency during rate volatility periods. Yield-spread premium restrictions and direct-to-consumer digital lender encroachment threaten traditional referral channel dominance. For New Entrants and Emerging Players: Capture self-employed borrower segments underserved by automated qualification engines through non-QM product specialization and bank-statement income verification expertise. Sun Belt metropolitan markets with heterogeneous credit profiles offer lowest competitive density for hybrid brokerage models combining digital pre-approval with licensed consultant access. For Investors and Strategic Acquirers: Consolidation pressure builds where state licensing fragmentation and compliance infrastructure costs squeeze independent operators without dedicated technology platforms. Long-term viability favors scaled franchise networks with centralized compliance management and multi-state licensing reciprocity. Watch wholesale lending capacity recalibration as the dominant inflection signal for broker network valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Convergence | Open banking data feeds enable pre-approval engines for thin-file borrowers outside traditional credit scoring. |
| Automated Valuation Model Integration | AVM deployment collapses appraisal turnaround times from weeks to days in purchase-heavy markets. |
| Non-QM Product Specialization | Debt-service-coverage-ratio and bank-statement programs capture premium pricing from self-employed segments. |
| Franchise Network Consolidation | National brand aggregation of independent brokers centralizes compliance management and technology platform access. |
| Direct-to-Consumer Channel Investment | Self-service rate comparison platforms capture millennial and Gen Z applicants bypassing traditional referral networks. |
Methodological Framework
Bottom-up loan origination volume modeling reconciled against top-down wholesale lending capacity tracking forms the analytical core of this study. Primary interviews with mortgage broker network executives, wholesale lender correspondent relationship managers, loan origination software platform engineers, and Consumer Financial Protection Bureau policy specialists combined with secondary validation from SEC 10-K filings, Home Mortgage Disclosure Act data, Federal Housing Administration endorsement reports, and Nationwide Multistate Licensing System registry records. Triangulation across bottom-up and top-down approaches ensures coverage consistency.
Input-output matrices map borrower segment demand against wholesale lender supply capacity across service type, customer lifecycle position, loan structure, and brokerage model dimensions. CAGRs derive from segmented volume trajectory modeling incorporating interest rate scenario sensitivity and housing affordability program expansion assumptions. Forecast inputs include Federal Reserve policy trajectory, GSE fee structure adjustments, and automated underwriting technology penetration curves.
Interest rate volatility beyond modeled scenarios, wholesale lender capacity contraction, and regulatory proposals around broker compensation transparency are the dominant revision risks. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Turkey Residential Real Estate Market
Real Estate
Australia Flexible Office Space Market
Real Estate
Qatar Co-Working Office Spaces Market
Real Estate
US Landscaping Services Market
Real Estate
Philippines Facility Management Market
Real Estate
United States Office Real Estate Market
Real Estate
United Kingdom Office Real Estate Market
Real Estate
Spain Commercial Real Estate Market
Real Estate
Europe Commercial Real Estate Market
Real Estate
China Smart Building Market
Real Estate
United Arab Emirates Real Estate Services Market
Real Estate
Spain Office Real Estate Market
Real Estate
Singapore Real Estate Market
Real Estate
South Korea Residential Real Estate Market
Real Estate
Netherlands Luxury Residential Real Estate Market
Real Estate
Block Former Market