
 India Home Mortgage Finance Market | 2026-2036
India Home Mortgage Finance Market Size, Share, and Industry Trends Forecast 2026-2036
India Home Mortgage Finance Market Foresight
The gap between premium and commodity mortgage offerings is broadening. HDFC Bank leverages its branch density in semi-urban markets to sustain volume leadership in standardized home loan products. ICICI Bank differentiates through technology leadership in digital underwriting and instant sanction workflows.
Home mortgage finance encompasses secured lending instruments collateralized by residential real property, typically structured with loan-to-value ratios capped by prudential norms and repayment tenures extending up to thirty years. Adjustable rate products now dominate origination mix as borrowers seek insulation from rate cycle volatility. First-time buyers represent the fastest-growing end-user segment, while conventional loans anchor the loan type category due to their flexibility across property grades and borrower profiles.
RBI prudential norms, SEBI regulations on mortgage-backed securities, and the Insolvency and Bankruptcy Code collectively shape lender risk appetite and capital market access for housing finance companies. The central bank's dynamic provisioning requirements and priority sector lending mandates directly influence product pricing and geographic targeting strategies. Stakeholders must monitor how digital public infrastructure layers—account aggregators and credit bureaus—reshape borrower scoring accuracy and fraud detection thresholds.
Market Dynamics
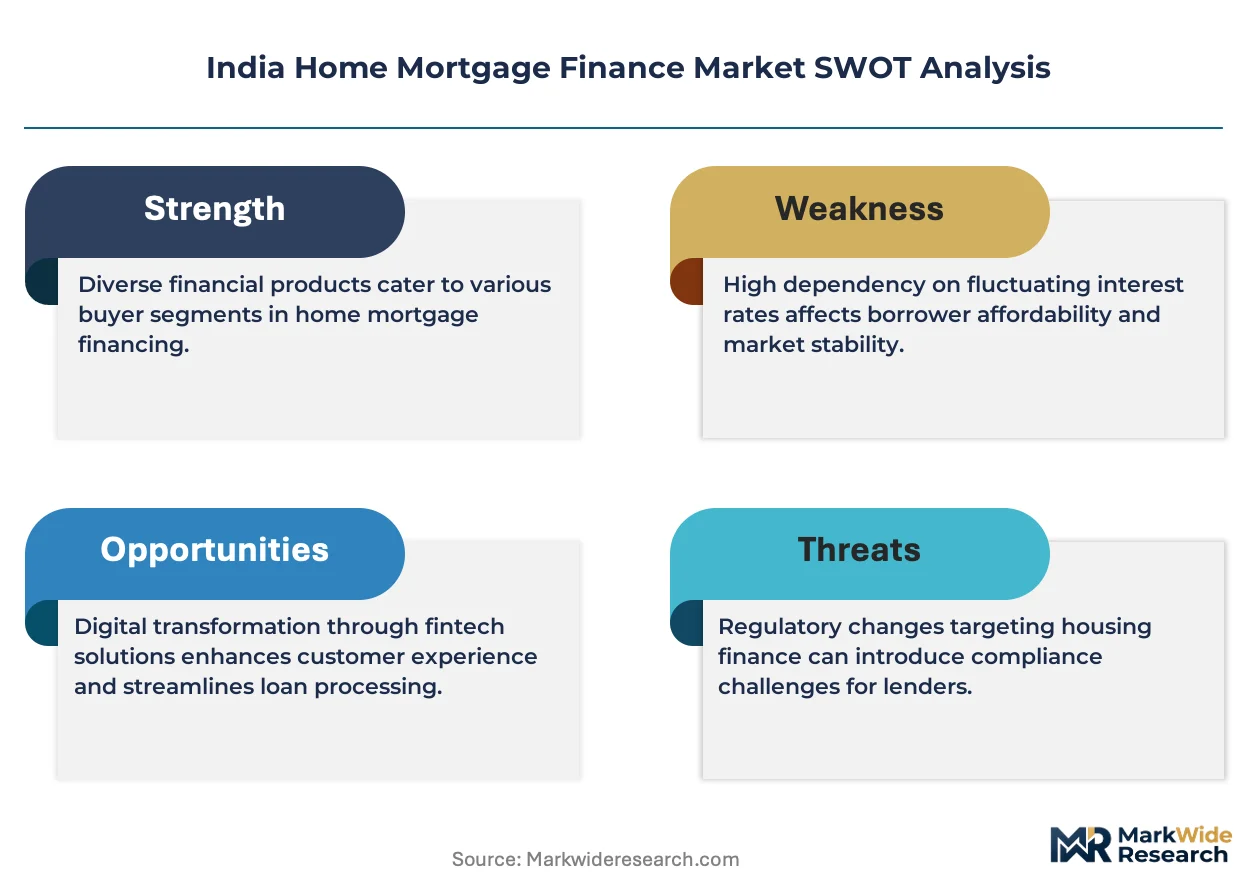
The Reserve Bank of India's risk-weight recalibration on housing loans is compressing lender capital efficiency while redirecting origination capacity toward lower-ticket borrowers in semi-urban clusters.
Growth Catalysts
- Priority Sector Lending Mandates:RBI's directed credit requirements force commercial banks to maintain housing loan portfolios, sustaining origination flow even through rate cycles.
- Digital Public Infrastructure:Account aggregators and Aadhaar-linked eKYC are collapsing verification timelines from weeks to hours, expanding addressable borrower pools.
- Tier-2 Urbanization:Formal employment expansion in cities like Pune, Kochi, and Coimbatore is generating first-time buyer pipelines previously concentrated in Mumbai and Bangalore.
Market Restraints
- Concentrated Funding Dependence:Housing finance companies rely heavily on bank borrowings and mortgage-backed securities, exposing liquidity to RBI monetary policy transmission.
- Collateral Valuation Opacity:Absence of standardized property price indices in secondary markets creates loan-to-value uncertainty and provisioning volatility.
- Construction Finance Linkages:Developer liquidity stress in delayed projects contaminates retail mortgage asset quality through pre-EMI accumulation.
Strategic Opportunities
- Green Housing Certification:RBI's inclusion of energy-efficient homes under priority sector lending creates rate arbitrage for certified properties.
- Co-lending with Regional Banks:Partnerships between large HFCs and district cooperative banks unlock origination in underpenetrated Maharashtra and Tamil Nadu hinterlands.
- Embedded Finance Channels:Integration with property listing platforms and real estate developer CRM systems captures borrowers at search-to-purchase conversion moments.
Industry Challenges
- Legacy Core System Constraints:Mid-tier housing finance companies operate on decade-old loan management platforms that fragment data across origination, underwriting, and collections modules.
- Document Forgery Detection:Property title verification and income document authentication require manual intervention that digital workflows have not yet eliminated.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Home Mortgage Finance Market |
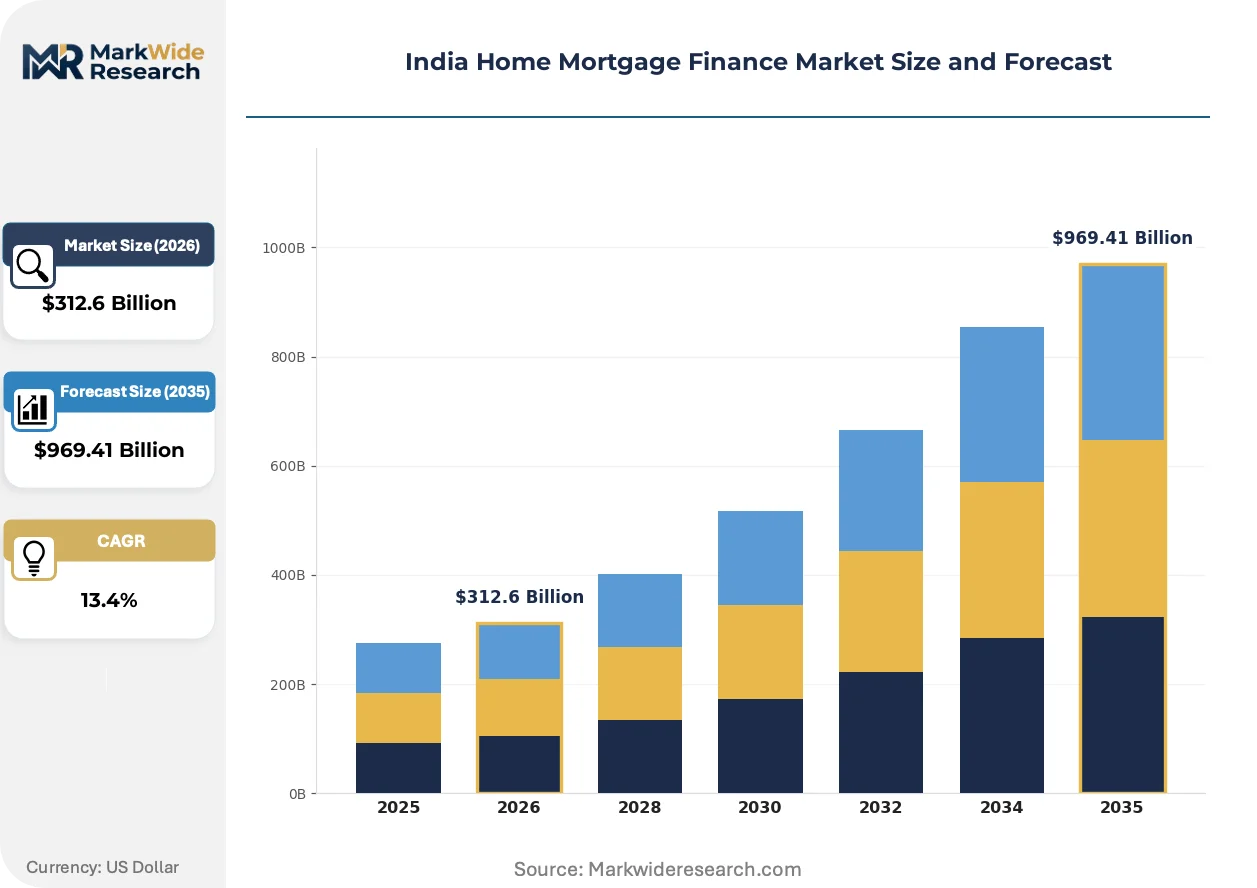
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $969.41 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Rate, Adjustable Rate, Interest-Only, Reverse Mortgage End User: First-Time Buyers, Investors, Refinancers, Retirees Distribution Channel: Online Platforms, Banks, Credit Unions, Mortgage Brokers Loan Type: Conventional Loans, FHA Loans, VA Loans, Jumbo Loans |
| Companies Covered | ICICI Bank, Axis Bank, HDFC Bank, Bajaj Housing Finance, Kotak Mahindra Bank, State Bank of India, PNB Housing Finance, Tata Capital Housing Finance, LIC Housing Finance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Home Mortgage Finance Market Shifts & Advancements
Technology adoption across the mortgage value chain is compressing decision timelines while regulatory digitization mandates are forcing infrastructure upgrades at smaller lenders.
API-based credit underwriting stacks are electrifying the traditional assessment model. Fintechs and progressive HFCs now pull real-time cash flow data through account aggregators, replacing static salary slips with dynamic transaction analysis. First-time buyers in tier-2 cities are adopting these instant sanction workflows fastest, collapsing the gap between property selection and loan commitment.
RBI's regulatory sandbox for digital lending has accelerated approval for alternative data scoring models. The framework permits supervised experimentation with telecom and utility payment histories as credit inputs, expanding formal mortgage access to thin-file borrowers. Housing finance companies with existing rural microfinance footprints are leveraging this to cross-sell home loans to established customers.
Builder tie-up models are fragmenting as direct-to-borrower digital channels gain traction. Property aggregators now embed loan comparison tools and pre-qualification engines, disintermediating the developer-recommended lender relationship. This shift is most pronounced in Bangalore and Hyderabad, where tech-savvy buyer segments prioritize rate transparency over convenience bundling.
India Home Mortgage Finance Market Segmentation
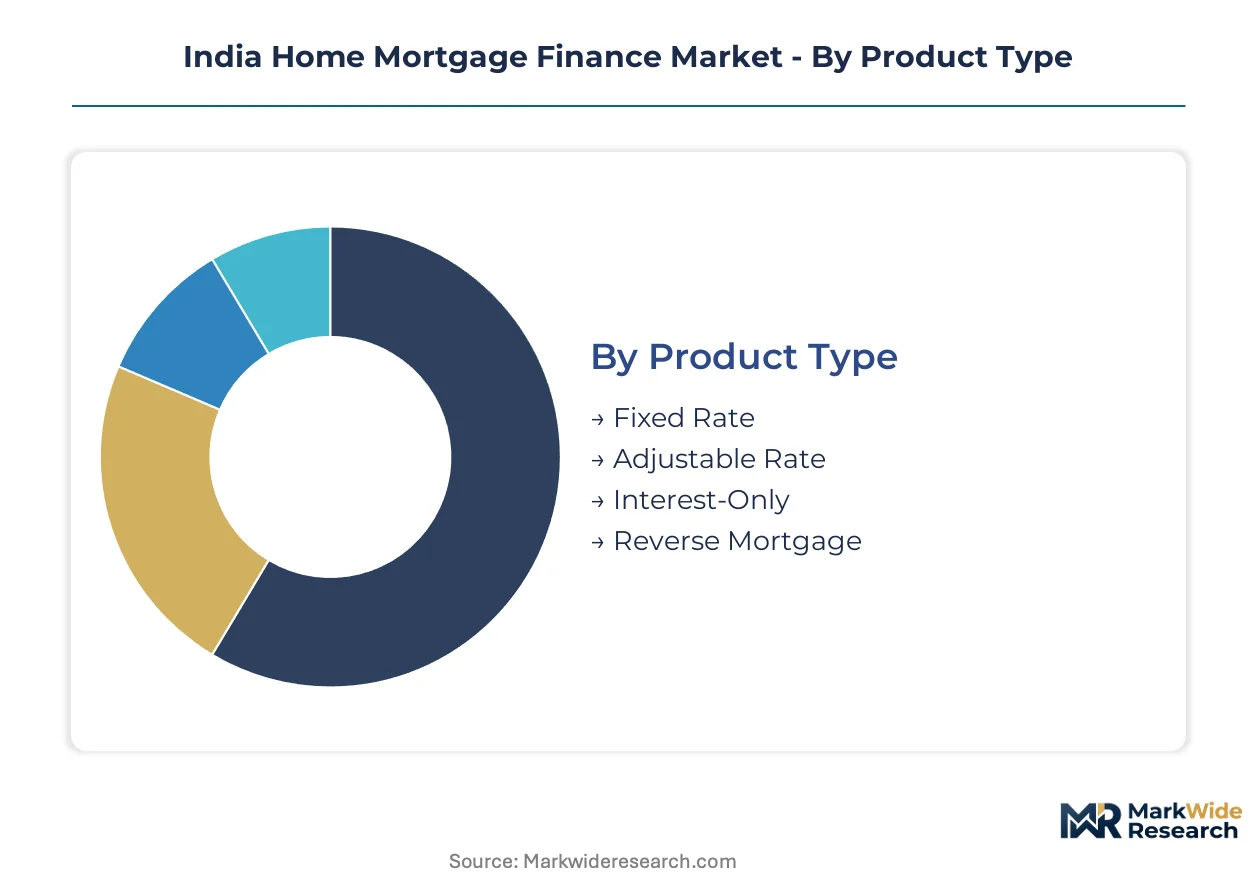
Segmentation in Indian home mortgage finance reveals how product design, borrower profiles, and channel economics split market opportunity across distinct profit pools. Lenders optimize capital allocation by matching product structures to regional income patterns and property market liquidity.
Product Type:
Customization spans from rigid payment schedules to flexible amortization structures that accommodate volatile income streams common in tier-2 employment markets.
- Fixed Rate:Locks interest costs for the full tenure, shielding borrowers from RBI policy rate cycles. Demand concentrates in Maharashtra and Karnataka where salaried professionals in IT and financial services prioritize payment certainty over potential savings from rate declines.
- Adjustable Rate:Links pricing to external benchmarks with periodic reset clauses, transferring rate risk to borrowers. Now dominating origination mix as first-time buyers in Pune and Kochi seek lower initial EMIs and accept future volatility exposure.
- Interest-Only:Defers principal repayment for an initial period, reducing early-stage cash outflow for property investors expecting rental yield appreciation.
- Reverse Mortgage:Converts home equity into periodic income streams for retirees, with RBI-mandated safeguards on tenure and loan-to-value limits protecting lender collateral recovery.
Leading the category by volume: Adjustable Rate. Growing fastest: Reverse Mortgage as urban senior populations expand and pension adequacy gaps widen.
End User:
Customer economics vary sharply across lifecycle stages, with acquisition costs and cross-sell potential dictating lender targeting priorities.
- First-Time Buyers:Salaried employees entering formal credit systems for the first time, typically seeking 20-30 year tenures on affordable housing units. Account aggregators and Aadhaar-linked eKYC are collapsing their onboarding timelines from weeks to hours.
- Investors:Multiple-property owners optimizing rental yields against interest costs, demanding flexible prepayment terms and top-up facilities for portfolio expansion.
- Refinancers:Existing borrowers switching lenders to capture rate arbitrage or release equity, concentrated in Bangalore and Hyderabad where property appreciation creates meaningful collateral value gains.
- Retirees:Asset-rich, income-constrained homeowners accessing liquidity without property disposal, with SEBI-regulated mortgage-backed securities providing funding channel depth for this lengthening-tenure segment.
First-Time Buyers anchor origination volumes. Refinancers are gaining share fastest as rate transmission accelerates and digital comparison tools proliferate.
Distribution Channel:
Channel economics reflect a trade-off between acquisition cost efficiency and relationship depth for subsequent cross-selling.
- Online Platforms:API-integrated aggregators and direct lender portals capturing search-to-purchase conversion moments, with instant sanction workflows winning tech-savvy segments in Bangalore and Hyderabad.
- Banks:Branch networks and existing liability relationships providing lowest-cost funding advantages and deposit-linked rate discounts, dominant in semi-urban Maharashtra and Tamil Nadu clusters.
- Credit Unions:Member-owned cooperatives with community-based underwriting flexibility, penetrating district-level markets in Kerala and Karnataka where formal employment documentation remains sparse.
- Mortgage Brokers:Independent intermediaries comparing across lender products, sustaining relevance in complex cases involving multiple income sources or non-standard property types.
Banks retain volume leadership through priority sector lending mandates. Online Platforms are expanding most quickly as property aggregators embed pre-qualification engines.
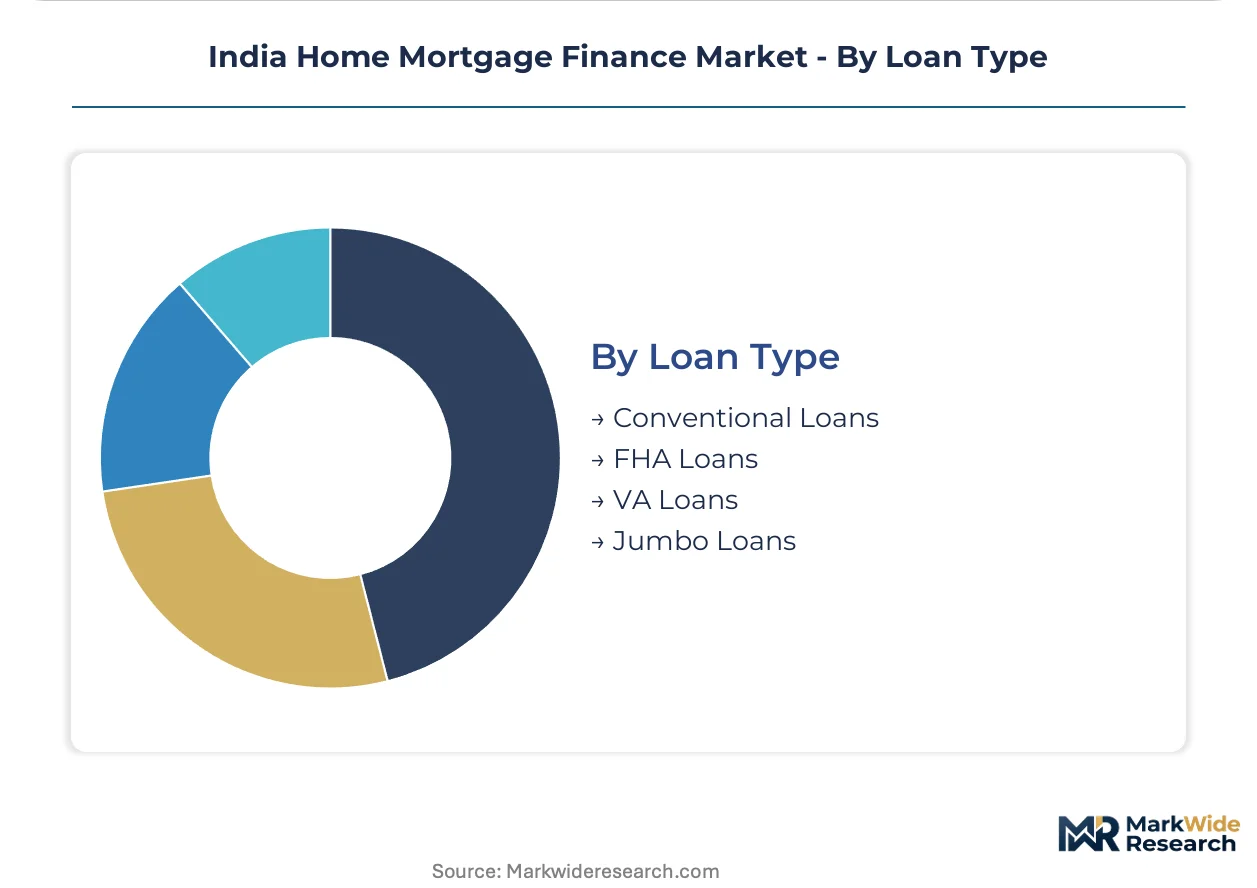
Loan Type:
Regulatory classification determines capital requirements, funding access, and borrower eligibility constraints that shape lender portfolio construction.
- Conventional Loans:Standard prime lending without government guarantee, offering maximum flexibility on property grades and borrower profiles. RBI risk-weight adjustments directly impact pricing and availability for this category.
- FHA Loans:Government-supported instruments with relaxed credit thresholds and higher loan-to-value ceilings, channeling priority sector credit to underserved segments in tier-2 urbanization corridors.
- VA Loans:Specialized products for defense personnel and veterans, leveraging salary assignment mechanisms and employer guarantees to reduce default risk.
- Jumbo Loans:Super-prime lending above conforming limits, collateralized by premium properties in Mumbai and Delhi-NCR where valuation opacity creates underwriting complexity.
Conventional Loans dominate portfolio composition. Jumbo Loans show steepest expansion trajectory as high-net-worth individuals diversify into residential real estate amid equity market volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors origination volumes in the India Home Mortgage Finance Market, with the Mumbai Metropolitan Region processing disproportionate high-ticket lending against premium residential inventory. Tier-2 urbanization corridors in Maharashtra, Karnataka, and Tamil Nadu are redirecting capital allocation toward Pune, Kochi, and Coimbatore clusters.
Maharashtra
IT and financial services employment in Mumbai and Pune generates salaried borrower pipelines seeking long-tenure products. RBI priority sector lending mandates direct bank branch networks toward semi-urban Thane and Nashik districts. The Mumbai-Pune industrial corridor concentrates developer tie-up volumes and instant sanction workflow adoption.
Karnataka
Bangalore's technology workforce drives demand for adjustable-rate products and digital-first onboarding experiences. SEBI regulations on mortgage-backed securities enable housing finance companies to access capital market funding for portfolio expansion. The Bangalore-Mysore corridor witnesses fastest growth in first-time buyer origination through API-integrated aggregator channels.
Tamil Nadu
Manufacturing formal employment in Chennai and Coimbatore creates stable income documentation for conventional loan underwriting. RBI risk-weight adjustments on housing loans compress capital efficiency for lenders with concentrated exposure to Chennai's premium property market. The Coimbatore-Tiruppur belt emerges as a testing ground for co-lending partnerships between large HFCs and district cooperative banks.
Telangana
Hyderabad's pharmaceutical and IT services expansion attracts investor-class borrowers seeking flexible prepayment terms and top-up facilities. The central bank's dynamic provisioning requirements influence lender geographic targeting toward lower-ticket borrowers in Warangal and Karimnagar. The Hyderabad metropolitan ring road corridor concentrates green housing certification uptake eligible for priority sector rate arbitrage.
Kerala
Gulf remittance-dependent household income patterns in Kochi and Thiruvananthapuram create non-standard documentation requirements addressed through account aggregator-based cash flow verification. Credit unions and member-owned cooperatives penetrate district-level markets where formal employment documentation remains sparse. The Kochi urban agglomeration leads adoption of reverse mortgage products among urban senior populations.
India Home Mortgage Finance Market Competitive Landscape
Capital-heavy banks with extensive branch networks compete with asset-light housing finance companies dependent on wholesale funding and securitization. The market structures around three tiers: universal banks with liability franchises, specialized housing finance companies with developer relationships, and fintech-enabled digital lenders with aggregator integrations. Dominant competitive moves include co-lending partnerships to penetrate underbanked geographies and API-based embedded finance integrations with property listing platforms.
Among private sector banks, ICICI Bank and Axis Bank exemplify technology-led differentiation through instant sanction workflows and digital underwriting stacks. HDFC Bank anchors the universal bank tier with branch density advantages in semi-urban markets. Specialized housing finance companies including Bajaj Housing Finance and PNB Housing Finance occupy positions dependent on mortgage-backed securities market access and builder tie-up networks. State Bank of India represents the public sector archetype with priority sector lending mandate compliance and government employee salary assignment mechanisms.
| Leading Market Players |
|---|
| ICICI Bank |
| Axis Bank |
| HDFC Bank |
| Bajaj Housing Finance |
| Kotak Mahindra Bank |
| State Bank of India |
| PNB Housing Finance |
| Tata Capital Housing Finance |
| LIC Housing Finance |
| Others |
Supply & Pricing Matrix
Credit underwriting talent concentration in Mumbai and Bangalore feeds pricing-tier spreads across the India Home Mortgage Finance Market, with fintech-enabled lenders commanding rate premiums in instant-sanction workflows while semi-urban branch networks compete on cost efficiency. Labor-cost differentials between metropolitan technology hubs and tier-2 operational centers translate directly into spread compression on standardized products versus digital-first offerings.
Pricing Analysis
Outcome-based pricing tied to loan-sanction speed anchors lender differentiation, with instant-approval workflows from ICICI Bank and Axis Bank extracting 15-30 basis point premiums over branch-mediated origination. Price differentiation separates API-integrated digital channels from relationship-heavy bank branches, with certification under RBI's regulatory sandbox adding further tiering. Cost compression in conventional loan processing is intensifying because account aggregator adoption collapses verification overhead. First-time buyers in Pune and Kochi show highest price sensitivity, while Mumbai-based investors prioritize flexibility over rate minimization.
Supply Chain Analysis
Reverse-logistics flows for document verification and income re-authentication create friction in mortgage servicing, particularly for adjustable-rate products requiring periodic reset documentation. Funding supply concentrates in domestic bank borrowings, mortgage-backed securities placement through SEBI-regulated channels, and priority sector lending certificate trading. Raw material dependencies include retail deposit bases, wholesale money market access, and securitization pipeline depth. Single-source vulnerability to RBI monetary policy transmission creates systemic liquidity risk. Distribution runs through branch networks, developer tie-ups, and embedded finance integrations with property aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Home Mortgage Finance Market is becoming a vertical-integration race, with lenders pursuing backward integration into account aggregator infrastructure and developer CRM systems to capture origination before competitor touchpoints.
For Market Incumbents: Deepen API-based underwriting capabilities to defend against fintech-enabled disintermediation in Bangalore and Hyderabad. Prioritize co-lending partnerships with district cooperative banks to lock in tier-2 origination capacity before regional specialists consolidate. RBI risk-weight recalibration on housing loans threatens capital efficiency for conventional loan-heavy portfolios. For New Entrants and Emerging Players: Gulf remittance-dependent households in Kerala present an underserved buyer archetype with non-standard documentation requirements addressable through cash-flow-based scoring. The Kochi-Thiruvananthapuram corridor offers lowest competitive density for digital-first onboarding. A go-to-market angle anchored in account aggregator verification bypasses incumbent branch infrastructure advantages. For Investors and Strategic Acquirers: Re-rating potential sits with housing finance companies possessing rural microfinance footprints given RBI regulatory sandbox approval for alternative data scoring models. Long-term viability hinges on securitization market access depth and developer relationship durability. The signal to watch is SEBI mortgage-backed securities issuance velocity as liquidity indicator.| Strategic Initiative | Industry Significance |
|---|---|
| API-Based Underwriting Stack Deployment | Account aggregator integration collapses verification timelines from weeks to hours for first-time buyers. |
| Co-Lending Partnership Formation | Collaboration between large HFCs and district cooperative banks unlocks Maharashtra and Tamil Nadu hinterlands. |
| Green Housing Certification Program | RBI priority sector inclusion creates rate arbitrage for energy-efficient home financing. |
| Embedded Finance Channel Integration | Property aggregator CRM integration captures borrowers at search-to-purchase conversion moments. |
| Legacy Core System Modernization | Mid-tier HFC infrastructure upgrades eliminate data fragmentation across origination and collections modules. |
Research Methodology
Document review covered RBI circulars on housing loan risk-weights, SEBI regulations on mortgage-backed securities, and Insolvency and Bankruptcy Code provisions, complemented by interviews with housing finance company chief risk officers, digital lending product heads, and priority sector lending compliance officers at universal banks. Secondary validation drew from RBI monetary policy reports, SEBI disclosure filings, and account aggregator framework documentation. Bottom-up origination volume modeling and top-down credit penetration benchmarking provided triangulation.
Market size outputs and growth trajectories across the projection horizon reflect segment-level modeling of product type, end user, distribution channel, and loan type dimensions. CAGRs were derived from regression analysis against macroeconomic drivers including formal employment growth, urbanization rates, and policy rate transmission. Industry-specific forecast inputs incorporated RBI priority sector lending mandate compliance thresholds and digital public infrastructure adoption curves.
Revisions become necessary when RBI risk-weight recalibrations, SEBI securitization rule changes, or developer liquidity stress events materialize beyond baseline assumptions. Forecasts reflect documented expectations regarding tier-2 urbanization velocity and account aggregator penetration. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Germany Self-Storage Market
Real Estate
United Kingdom Co-Working Office Spaces Market
Real Estate
South Africa Residential Real Estate Market
Real Estate
Austria Facility Management Market
Real Estate
Real Estate Management Software Market
Real Estate
E House Market
Real Estate
Israel Commercial Real Estate Market
Real Estate
North America Tiny Homes Market
Real Estate
Latin America Coworking Spaces Market
Real Estate
US Real Estate and Hospitality Market
Real Estate
India Flexible Office Space Market
Real Estate
North America Luxury Residential Real Estate Market
Real Estate
Japan Condominiums and Apartments Market
Real Estate
Asia Pacific Office Real Estate Market
Real Estate
Brazil Commercial Real Estate Market
Real Estate
Refrigerated Warehousing Market