
 Online Movie Market | 2026-2036
Online Movie Market Size, Share, and Industry Trends Forecast 2026-2036
Online Movie Market Outlook
The capital-intensity divergence between original content spend and licensed catalog aggregation is unwinding competitive dynamics across streaming platforms. Netflix Inc. leverages its global production infrastructure to sustain localized content pipelines across multiple continents. Amazon.com Inc. (Prime Video) anchors its streaming proposition within a broader e-commerce and logistics ecosystem. Apple Inc. (Apple TV+) differentiates through premium original productions with theatrical-quality production values.
Online movie distribution encompasses digital streaming, download-to-own, and cloud-based rental systems delivering audiovisual content via internet protocol networks with adaptive bitrate streaming, DRM encryption, and CDN edge caching for latency reduction below 200 milliseconds. The primary commercial purpose centers on monetizing film and episodic content through recurring subscription fees, transactional purchases, or advertising-supported viewership. Subscription services capture the dominant revenue pool with recurring revenue predictability, while ad-supported tiers attract price-sensitive segments with lower average revenue per user. Mobile devices represent the fastest-growing consumption endpoint as 5G penetration expands and short-form content habits migrate toward longer-form viewing.
The Federal Communications Commission shapes net neutrality frameworks affecting streaming quality-of-service guarantees, while the European Union's Digital Services Act imposes content moderation and algorithmic transparency obligations on platforms operating across member states. India's Ministry of Information and Broadcasting enforces content certification requirements that platforms must navigate for theatrical and direct-to-digital releases. Stakeholders must monitor evolving data localization mandates and cross-border content licensing friction as regulatory fragmentation intensifies platform compliance costs.
Market Dynamics
The capital-intensity divergence between original content production and licensed catalog aggregation is compressing platform margins while accelerating subscriber churn across competing services. This structural tension forces operators to choose between volume-driven acquisition and retention-focused investment in exclusive intellectual property.
Growth Catalysts
- 5G Infrastructure Deployment:Mobile network operators in South Korea and Japan are rolling out millimeter-wave spectrum that enables 4K streaming without buffering. Urban subscribers in Seoul and Tokyo are migrating from Wi-Fi-dependent viewing to seamless cellular consumption.
- India's Content Localization Mandates:The Ministry of Information and Broadcasting requires 30% domestic content quotas for foreign platforms. This regulatory pressure is spawning regional-language production hubs in Mumbai, Chennai, and Hyderabad.
- Cloud Gaming Convergence:Interactive streaming technologies are merging film narratives with gamified viewer participation. Young adult demographics in Brazil and Mexico are driving adoption of choose-your-own-adventure formats.
Market Restraints
- Bandwidth Cost Volatility:Content delivery network pricing fluctuates with energy markets, squeezing margin structures for ad-supported tiers. Southeast Asian platforms face particular pressure from diesel-dependent edge server operations.
- Licensing Concentration Risk:Major studio catalogs concentrate among three dominant rights holders in Los Angeles. Independent platforms face exclusion or punitive minimum guarantees.
- DRM Fragmentation:Incompatible encryption standards across Apple FairPlay, Google Widevine, and Microsoft PlayReady force redundant encoding pipelines. Technical overhead inflates per-title delivery costs.
Strategic Opportunities
- Indonesian Archipelago Expansion:Underpenetrated rural markets across 17,000 islands lack fixed broadband but possess 4G saturation. Satellite-backhauled mobile streaming represents untapped addressable demand.
- EU Digital Services Act Alignment:Algorithmic transparency requirements create first-mover advantage for platforms investing in explainable recommendation engines. German and French regulators are prioritizing audit-ready systems.
- AI-Driven Personalization:Machine learning models trained on viewing telemetry enable dynamic thumbnail optimization and predictive content prefetching. Convergence of computer vision and natural language processing is lowering creative asset production costs.
Industry Challenges
- Localization Talent Scarcity:Qualified subtitling and dubbing professionals are concentrated in Madrid, Mexico City, and Mumbai. Platforms expanding into Vietnamese, Thai, and Bahasa Indonesia face 6-12 month recruitment cycles.
- Cross-Border IP Arbitration:Territorial licensing disputes between co-production partners delay release windows. French and Canadian rights holders frequently clash over simultaneous streaming rights.
- Legacy Payment Integration:Emerging market subscribers prefer carrier billing and digital wallets over credit cards. Technical debt from decade-old subscription management systems impedes rapid payment method expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Movie Market |
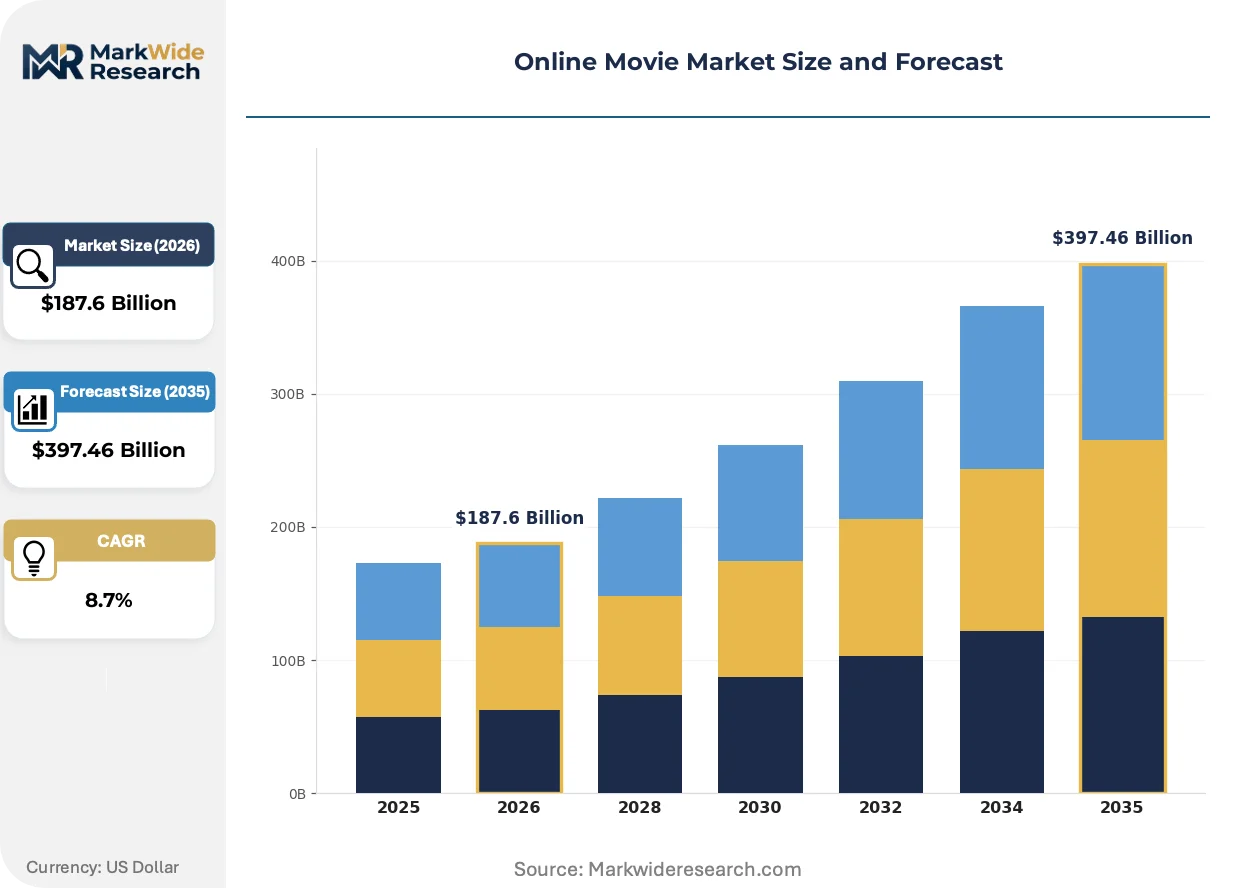
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $397.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription, Transactional, Ad-Supported, Rental Content Type: Feature Films, Documentaries, Short Films, Series Device Type: Smart TVs, Mobile Devices, Laptops, Streaming Devices Audience Segment: Families, Young Adults, Seniors, Students |
| Companies Covered | Netflix Inc., Amazon.com Inc. (Prime Video), The Walt Disney Company (Disney+), Google LLC (YouTube), Tencent Holdings Ltd (Tencent Video), Hulu LLC, Apple Inc. (Apple TV+), iQIYI Inc., Warner Bros. Discovery (Max), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Movie Market Strategic Shifts
Streaming technology stacks are fragmenting into two distinct architectural paths. One optimizes for latency-sensitive interactive experiences while the other prioritizes bandwidth-efficient passive consumption.
Edge computing infrastructure is bifurcating platform strategies between centralized cloud rendering and distributed node processing. Live sports broadcasters in the United Kingdom and Germany are adopting sub-50-millisecond latency protocols for real-time wagering integration. Passive film distributors are compressing bitrates to serve price-sensitive mobile-only subscribers in emerging markets. This technological divergence is forcing CDN providers to maintain dual hardware configurations.
The European Union's Digital Services Act imposes algorithmic audit obligations on platforms exceeding 45 million monthly active users. French regulator CNIL and German BfDI are coordinating enforcement timelines for transparency disclosures. Mid-tier services are restructuring recommendation engines to preempt regulatory scrutiny. Nordic platforms are voluntarily adopting stricter standards to differentiate in privacy-conscious markets.
Subscriber acquisition patterns are rotating from annual prepaid commitments toward flexible weekly passes. Young adult viewers in Nigeria, Kenya, and South Africa prefer mobile money-activated short-duration access over traditional monthly billing. Telco bundles in Lagos and Nairobi are displacing direct platform relationships. This behavioral shift compresses lifetime value calculations while expanding total addressable user bases.
Online Movie Market Segmentation
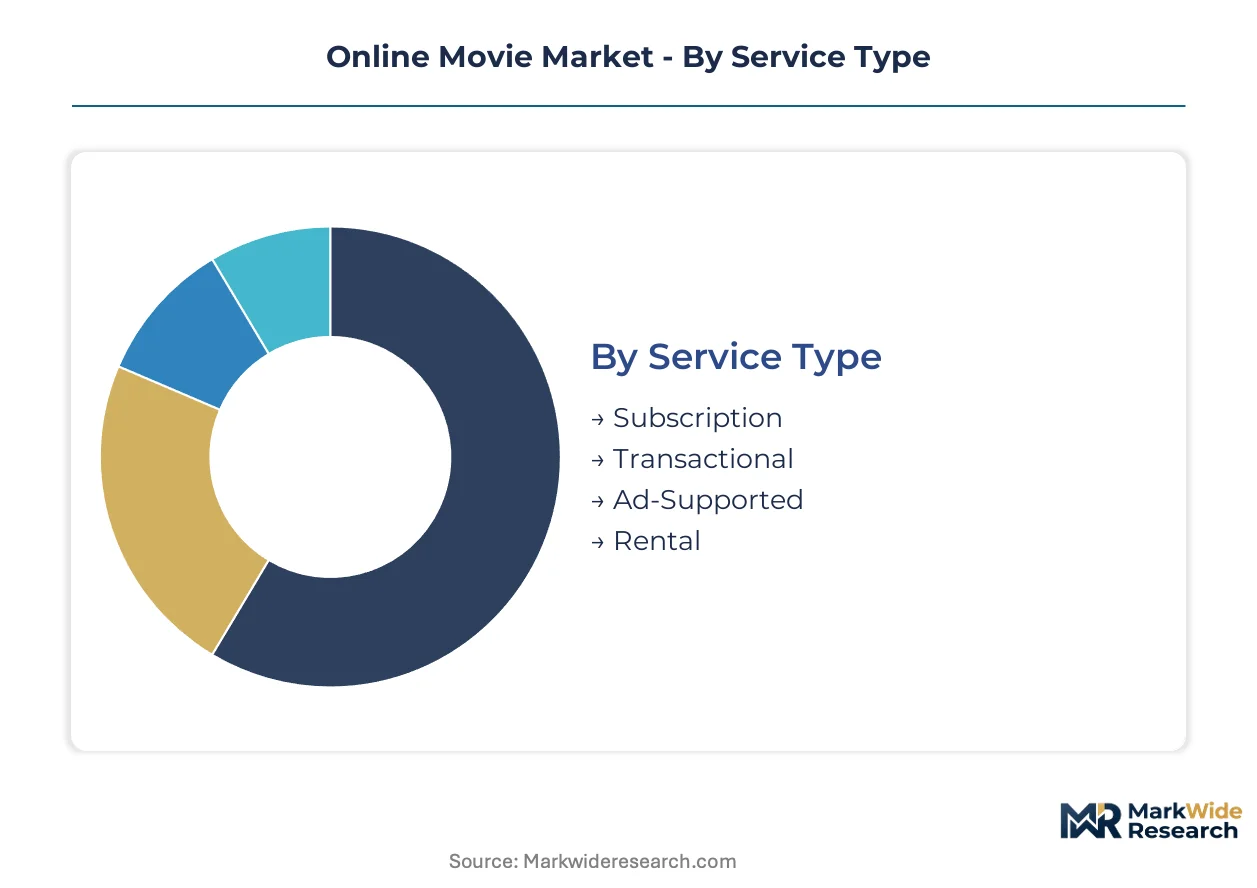
Streaming platforms calibrate monetization strategies across distinct consumption patterns. Segmentation reveals where subscriber lifetime value concentrates versus where acquisition costs balloon.
Service Type:
Subscription models dominate in bandwidth-rich urban corridors from Seoul to São Paulo, while transactional and ad-supported tiers penetrate price-sensitive emerging markets.
- Subscription:Recurring revenue models lock in predictable cash flows through annual prepaid commitments. Demand clusters in Southeast Asian metropolitan zones where disposable income supports multiple platform memberships.
- Transactional:Pay-per-view systems monetize event-driven releases and premium windowing. New release theatrical bypasses in India and Nigeria drive peak transaction volumes during festival periods.
- Ad-Supported:Lower entry price points expand total addressable audiences through sponsor-funded access. Indonesian and Filipino platforms leverage this tier to capture mobile-first viewers outside major cities.
- Rental:Time-limited access windows serve occasional viewers seeking specific titles without commitment. European markets retain residual rental demand for catalog depth and niche documentary content.
Subscription holds the largest share; momentum sits with ad-supported tiers expanding fastest in emerging economies.
Content Type:
Production economics vary dramatically by format length and amortization potential across theatrical, episodic, and short-form categories.
- Feature Films:Theatrical-quality productions command premium licensing fees and anchor platform marketing campaigns. Korean and Indian studios dominate regional feature output with localized star vehicles.
- Documentaries:Lower production costs and awards prestige attract niche subscriber segments. True crime and nature documentaries drive sustained engagement in German and British markets.
- Short Films:Festival-circuit content and creator experiments fill algorithmic gaps between major releases. Brazilian and Mexican platforms use shorts to test emerging director talent.
- Series:Episodic formats maximize watch time and reduce churn through cliffhanger retention mechanics. Turkish and Thai drama series export across Middle Eastern and Southeast Asian territories.
Series commands dominant viewing hours; feature films retain the highest per-title production investment.
Device Type:
Screen size and connectivity constraints fragment technical delivery requirements and content formatting standards.
- Smart TVs:Large-format displays drive premium 4K HDR consumption in living room environments. Japanese and South Korean households lead smart TV penetration with integrated streaming app ecosystems.
- Mobile Devices:Smartphone screens dominate emerging market consumption where fixed broadband remains scarce. Nigerian and Kenyan subscribers rely exclusively on cellular data for streaming access.
- Laptops:Portable computing maintains relevance for shared viewing and travel contexts. Student demographics in Vietnam and Indonesia prefer laptop interfaces for multitasking flexibility.
- Streaming Devices:Dedicated hardware bridges legacy televisions to internet protocol delivery. Amazon Fire and Roku sticks penetrate cost-conscious US and Mexican households.
Smart TVs generate peak revenue per user; mobile devices are climbing the fastest as 5G infrastructure spreads.
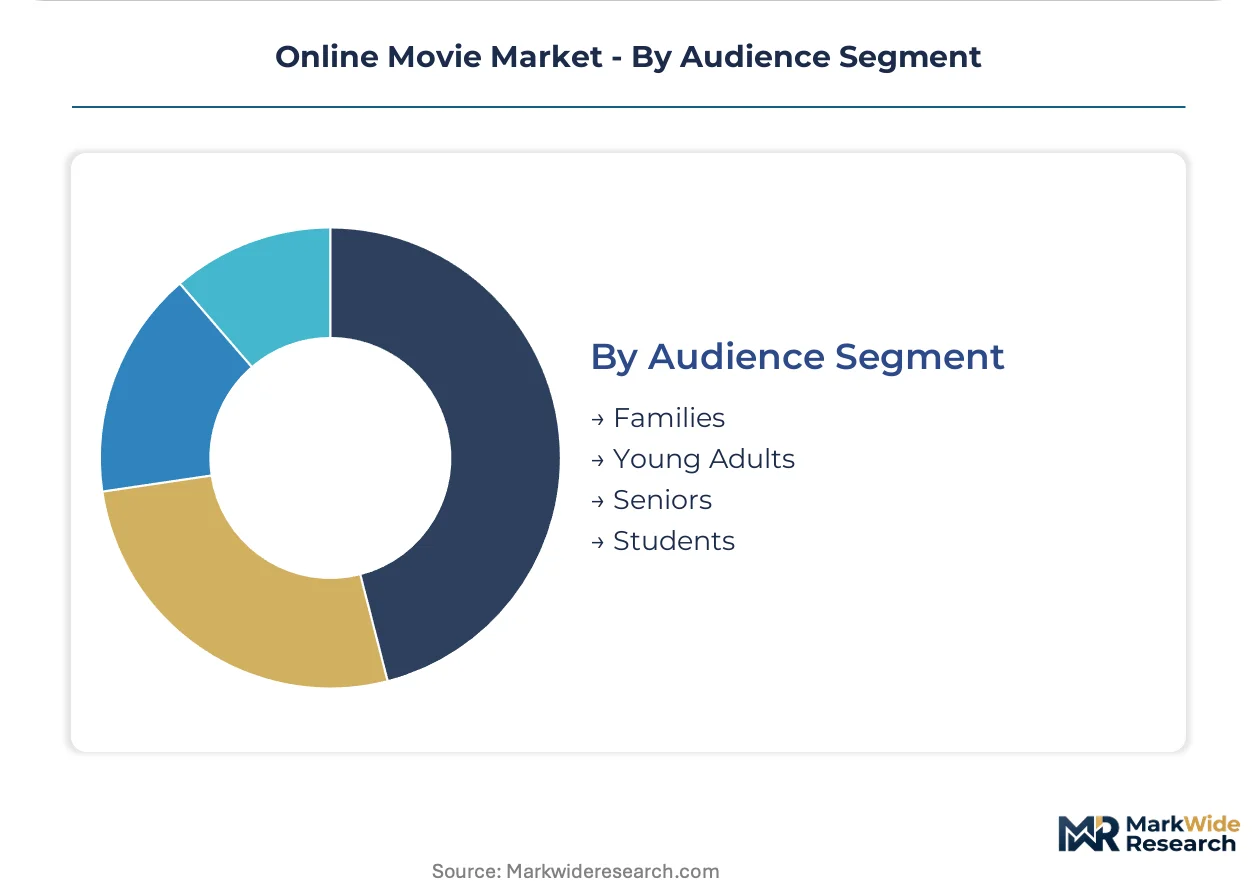
Audience Segment:
Demographic targeting shapes content commissioning slates and interface personalization algorithms.
- Families:Multi-generational accounts require robust parental controls and diverse content libraries. Disney and Netflix compete aggressively for co-viewing occasions in suburban US and Australian markets.
- Young Adults:18-34 demographics drive social media amplification and trend-responsive consumption. K-drama and anime fandoms concentrate in this segment across Southeast Asian cities.
- Seniors:Simplified interfaces and classic catalog content retain aging subscriber bases. Japanese and German platforms invest in accessibility features for this cohort.
- Students:Price-sensitive, time-fragmented viewing patterns favor mobile access and discounted plans. Indian and Brazilian edu-email verification unlocks steep subscription discounts.
Families represent the stickiest subscriber base; young adults are gaining share fastest through viral content mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korean and Japanese metropolitan corridors where 5G infrastructure enables premium 4K streaming tiers, while Indonesian and Nigerian markets operate on compressed mobile-bitrate economics with lower subscriber yields. This asymmetry shapes divergent platform investment priorities across developed and emerging economies.
United States
Federal Communications Commission net neutrality frameworks influence quality-of-service guarantees for streaming delivery. The FCC's ongoing broadband infrastructure mapping initiatives direct subsidy flows toward rural connectivity expansion. Los Angeles anchors original content production clusters where major studio licensing negotiations concentrate platform bargaining power.
India
Ministry of Information and Broadcasting content localization mandates require 30 percent domestic content quotas for foreign platforms. The TRAI's regulatory oversight extends to tariff transparency in platform-telecom bundling arrangements. Mumbai, Chennai, and Hyderabad host regional-language production hubs responding to mandated localization requirements.
South Korea
Millimeter-wave 5G spectrum deployment enables buffer-free 4K streaming on mobile devices. The Korea Communications Commission enforces platform content rating systems aligned with domestic broadcast standards. Seoul metropolitan subscribers are migrating from Wi-Fi-dependent viewing to seamless cellular consumption.
Germany
BfDI coordination with French CNIL on Digital Services Act enforcement timelines creates algorithmic audit obligations for large platforms. The country's national media regulator enforces youth protection standards for streaming content classification. Berlin and Munich house European headquarters operations for multiple international platforms navigating EU compliance requirements.
Brazil
ANVISA's regulatory scope intersects with streaming platforms through advertising content standards for health and pharmaceutical promotions. Cloud gaming convergence with interactive film formats drives adoption among young adult demographics. São Paulo and Rio de Janeiro production clusters supply Portuguese-language content for Latin American distribution.
Online Movie Market Competitive Environment
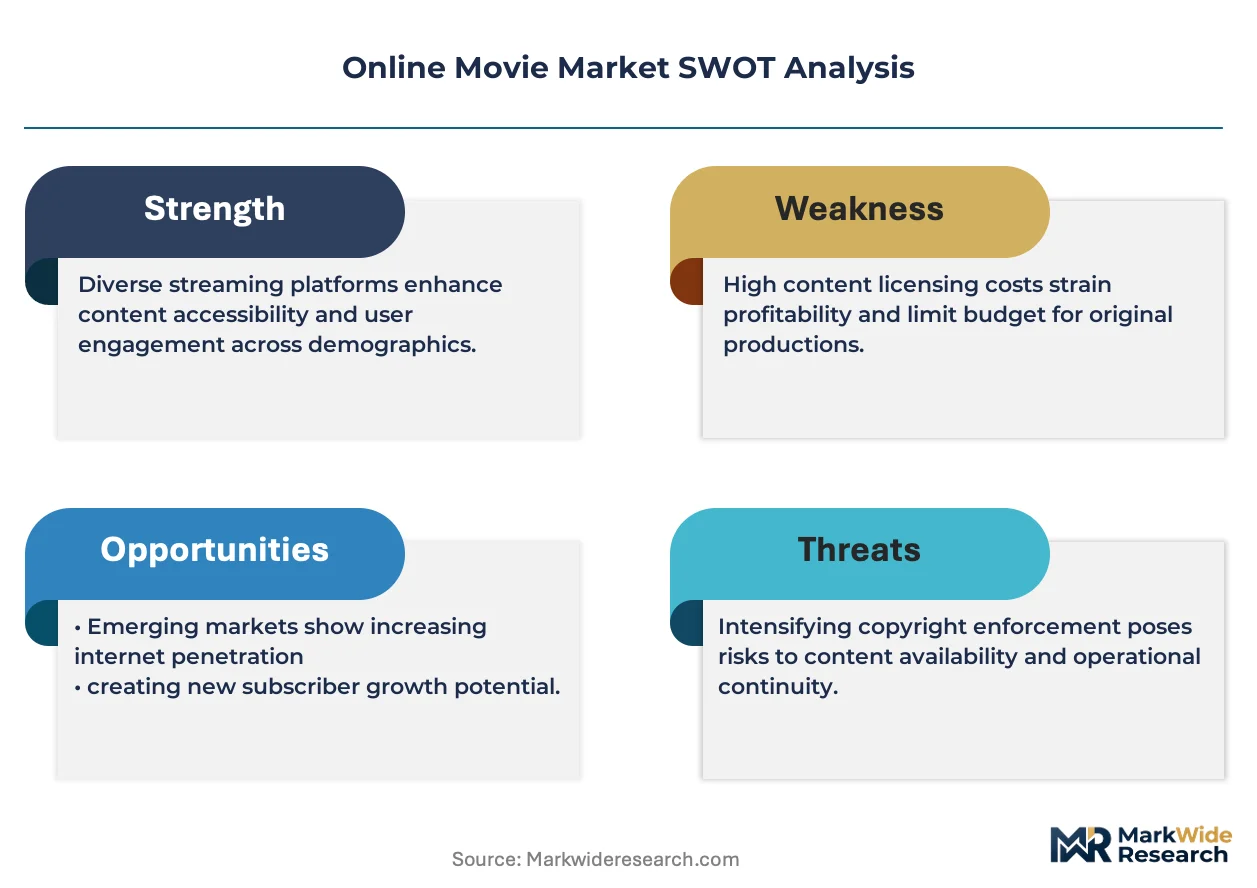
Concentration sits with vertically integrated technology conglomerates possessing cloud infrastructure and device ecosystems. The market structure consolidates around three tiers: global-scale subscription platforms, regional specialists with localized content depth, and hardware-anchored services leveraging installed device bases. Dominant competitive moves include exclusive content licensing to lock subscriber retention and cloud-gaming convergence to expand interactive entertainment addressable markets.
Among US-based technology conglomerates, Netflix Inc., Amazon.com Inc., and Apple Inc. occupy distinct strategic positions within the competitive architecture. Netflix exemplifies the pure-play streaming archetype with global production infrastructure. Amazon anchors its video proposition within broader e-commerce and logistics ecosystem integration. Apple represents the premium-tier hardware-software-services convergence model with theatrical-quality original production positioning.
| Leading Market Players |
|---|
| Netflix Inc. |
| Amazon.com Inc. (Prime Video) |
| The Walt Disney Company (Disney+) |
| Google LLC (YouTube) |
| Tencent Holdings Ltd (Tencent Video) |
| Hulu LLC |
| Apple Inc. (Apple TV+) |
| iQIYI Inc. |
| Warner Bros. Discovery (Max) |
| Others |
Value Chain & Pricing Dynamics
India's Ministry of Information and Broadcasting content localization mandates gate platform licensing qualification while simultaneously enabling price differentiation through exclusive regional-language catalog depth. Foreign operators must absorb compliance costs that domestic incumbents avoid, fragmenting pricing power across territorial licensing tiers.
Pricing Analysis
Configured-to-order pricing for localized content packages commands premium spreads against standard international catalog access in Southeast Asian markets. Subscription models stratify across premium 4K tiers, standard HD packages, and mobile-optimized economy plans, with price differentiation driven by content exclusivity windows and device concurrency limits. Cost compression in ad-supported tiers intensifies as bandwidth volatility squeezes CDN margins. Price-sensitive student demographics in Brazil and India exhibit highest elasticity, while family accounts in South Korea and Japan demonstrate lowest churn sensitivity to annual rate adjustments.
Supply Chain Analysis
South Korea and Japan anchor millimeter-wave 5G infrastructure deployment enabling buffer-free mobile streaming, while the United States and India host dominant content production clusters. Original content pipelines draw from Los Angeles studio licensing negotiations, Mumbai regional-language production hubs, and Seoul post-production facilities. Single-source vulnerability concentrates in three dominant Hollywood rights holders controlling major studio catalog access. Distribution runs through hyperscaler cloud infrastructure with edge caching nodes positioned for sub-200-millisecond latency delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-gaming convergence and interactive narrative formats that capture young adult engagement hours previously allocated to passive streaming consumption.
For Market Incumbents: Compound exclusive intellectual property retention through accelerated regional production hub investment in Mumbai, Chennai, and Hyderabad responding to India's localization mandates. Deepen backward integration into original content pipelines to defend against cloud-gaming platforms encroaching on interactive entertainment addressable markets. Prioritize algorithmic transparency infrastructure to preempt EU Digital Services Act enforcement timelines.
For New Entrants and Emerging Players: Mobile-only subscriber segments in Indonesian archipelago markets represent under-served white-space where fixed broadband scarcity and 4G saturation create addressable demand. Satellite-backhauled streaming infrastructure unlocks rural penetration across 17,000 islands bypassing terrestrial network limitations. Carrier billing integration and telco bundle partnerships provide lowest-friction go-to-market channels displacing direct platform relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across ad-supported tier operations as automated content moderation and AI-driven personalization reduce per-subscriber servicing costs. Long-term viability favors platforms with explainable recommendation engine investments and audit-ready algorithmic systems. Acquisition target archetype: regional specialists with deep localization talent pools in Vietnamese, Thai, and Bahasa Indonesia content production. Signal to monitor: regulatory fragmentation accelerating data localization mandates and cross-border licensing friction.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Production Hub Expansion | Mumbai and Hyderabad facilities satisfy India's 30% domestic content quota mandates. |
| Algorithmic Transparency Investment | Explainable recommendation engines preempt CNIL and BfDI audit enforcement timelines. |
| Cloud-Gaming Convergence | Interactive streaming formats capture Brazilian and Mexican young adult engagement hours. |
| Satellite-Backhauled Mobile Streaming | Indonesian archipelago infrastructure bypasses fixed broadband scarcity across 17,000 islands. |
| Carrier Billing Integration | Lagos and Nairobi telco bundles displace credit card dependency in African markets. |
Study Parameters
The analysis maps subscription, transactional, ad-supported, and rental service models, each validated through streaming platform executives, content licensing directors, CDN infrastructure engineers, and telecom bundling specialists. Primary stakeholder interviews combined with secondary validation from FCC net neutrality filings, TRAI tariff transparency databases, EU Digital Services Act regulatory texts, and Korea Communications Commission content rating standards. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from hyperscaler capex disclosures and studio licensing agreement patterns.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include service type, content format, device endpoint, and audience demographic cluster. CAGRs derived from subscriber growth trajectories, ARPU evolution patterns, and content spend intensity ratios. Industry-specific forecast inputs incorporated 5G deployment timelines, localization mandate compliance costs, and cloud-gaming technology adoption curves.
Material uncertainties — regulatory fragmentation intensifying platform compliance costs, bandwidth cost volatility from energy market fluctuations, and territorial licensing disputes delaying release windows — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding infrastructure deployment schedules and content localization investment trajectories. Recalibration cycles align with material shifts in net neutrality frameworks, data localization mandates, and interactive streaming technology convergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Blockchain in Media and Entertainment Market
Digital Media
Digital Content Creation Market
Digital Media
Global Stock Video Market
Digital Media
Video Content Management Market
Digital Media
4K Content Market
Digital Media
Visual Effects (VFX) Market
Digital Media
Entertainment Market
Digital Media
Video Wall Market
Digital Media
Online Gambling Market
Digital Media
Online Art Market
Digital Media
Global Playout Automation and Channel in a Box Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
Webtoons Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Middle East and Africa Animation Market
Digital Media
In Flight Entertainment Market