
 Europe Online Video Platform Market | 2026-2036
Europe Online Video Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Online Video Platform Market Intelligence
Enterprise training departments are rotating away from standalone learning management systems toward integrated video platforms that support live streaming and on-demand playback. Netflix leverages proprietary encoding pipelines to sustain bandwidth efficiency across continental networks. Brightcove specializes in monetization tooling for media companies navigating fragmented European advertising markets. Kaltura anchors the educational segment through campus-wide deployment contracts with universities in France and Germany.
Europe online video platforms are software systems that ingest, transcode, store, and deliver audiovisual content across IP networks using adaptive bitrate streaming protocols such as HLS and DASH to maintain playback quality under variable bandwidth conditions. These platforms serve commercial purposes spanning entertainment distribution, corporate communications, and institutional learning. Streaming services dominate product-type revenue as subscription VOD operators invest in original content production to differentiate regional catalogs. Cloud deployment models capture expanding share as media companies abandon capital-intensive on-premise infrastructure for elastic compute capacity. Edge computing nodes are emerging fastest within deployment models as latency-sensitive live streaming applications proliferate across sports and gaming verticals.
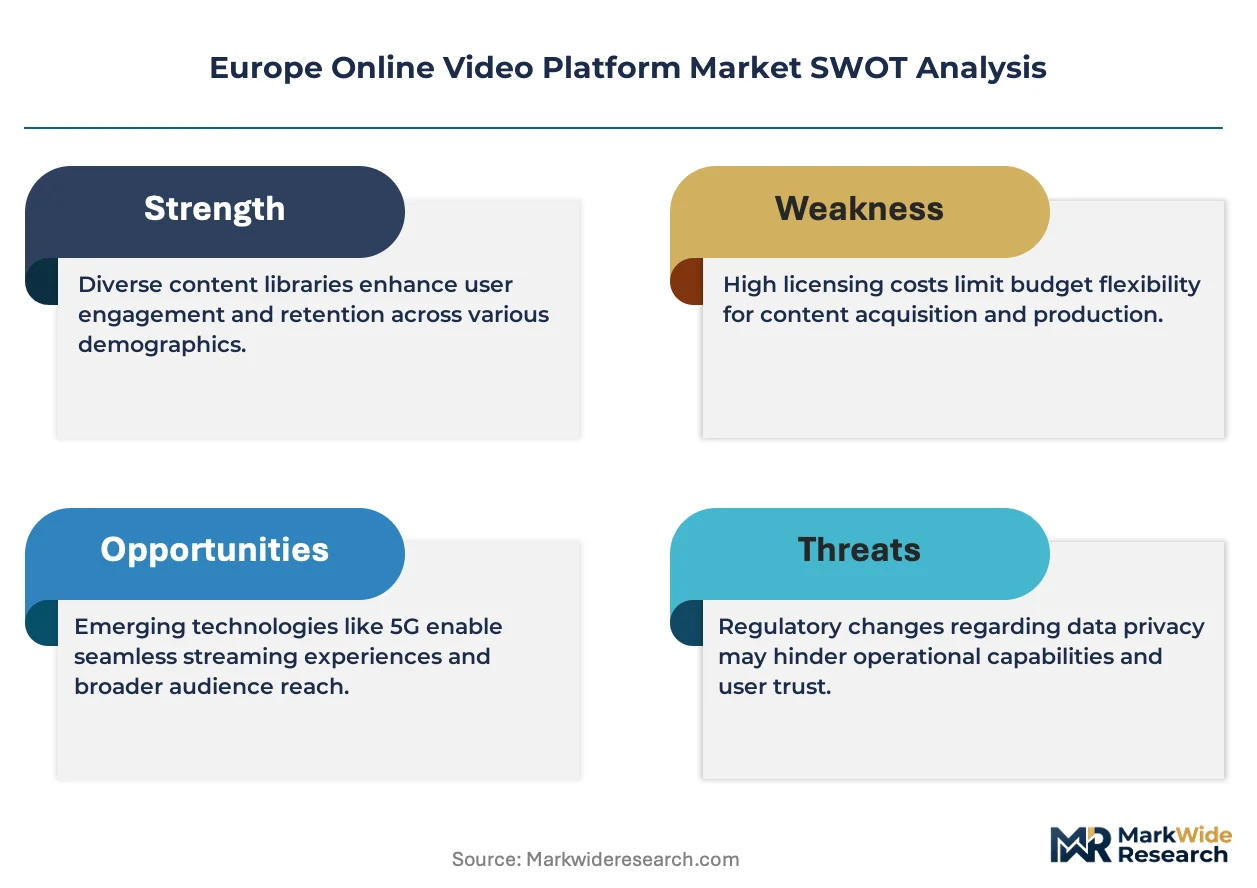
The EU AI Act imposes transparency requirements on automated content recommendation systems, forcing platforms to document algorithmic logic for regulatory audits. GDPR enforcement by national data protection authorities restricts cross-border viewer data processing, complicating pan-European personalization strategies. EMA content classification standards for pharmaceutical advertising on streaming platforms create specialized compliance burdens for health-sector video deployments. Stakeholders must monitor how the Digital Services Act's risk-management obligations will reshape platform liability for user-generated content distribution.
Market Dynamics
Enterprise migration from legacy learning management systems toward integrated video delivery platforms is compressing procurement cycles and reshaping vendor selection criteria across corporate training departments.
Growth Catalysts
- EU AI Act transparency mandates:Automated content recommendation systems face new documentation requirements, creating demand for compliance-integrated platform architectures that embed audit trails natively.
- Edge computing infrastructure:Latency-sensitive live streaming for sports and gaming verticals is accelerating deployment of distributed processing nodes across metropolitan networks.
- Campus-wide educational contracts:Universities in France and Germany are consolidating video infrastructure under single-vendor agreements, replacing fragmented departmental solutions.
Market Restraints
- GDPR cross-border friction:National data protection authorities restrict viewer data processing across member states, fragmenting personalization engines that rely on pan-European behavioral profiles.
- Bandwidth cost volatility:Transit pricing fluctuations between Tier-1 network providers compress margins for platforms delivering 4K and live content at scale.
- On-premise legacy lock-in:Media companies with substantial capital investment in owned encoding hardware face extended depreciation cycles that delay cloud migration decisions.
Strategic Opportunities
- Pharmaceutical advertising compliance:EMA content classification standards for health-sector video deployments create specialized platform requirements that incumbent generalists struggle to meet.
- Low-latency interactive streaming:WebRTC and SRT protocol convergence enables real-time audience participation features for wagering and live commerce applications.
- Digital Services Act preparedness:Risk-management obligations for user-generated content distribution will force smaller platforms to seek outsourced moderation infrastructure.
Industry Challenges
- Codec specialization shortage:Engineering talent with deep expertise in AV1 and VVC encoding optimization commands premium compensation, constraining platform R&D expansion.
- Multi-cloud orchestration complexity:Enterprises demanding redundancy across AWS, Azure, and GCP regions require sophisticated traffic management that stretches mid-tier vendor capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Online Video Platform Market |
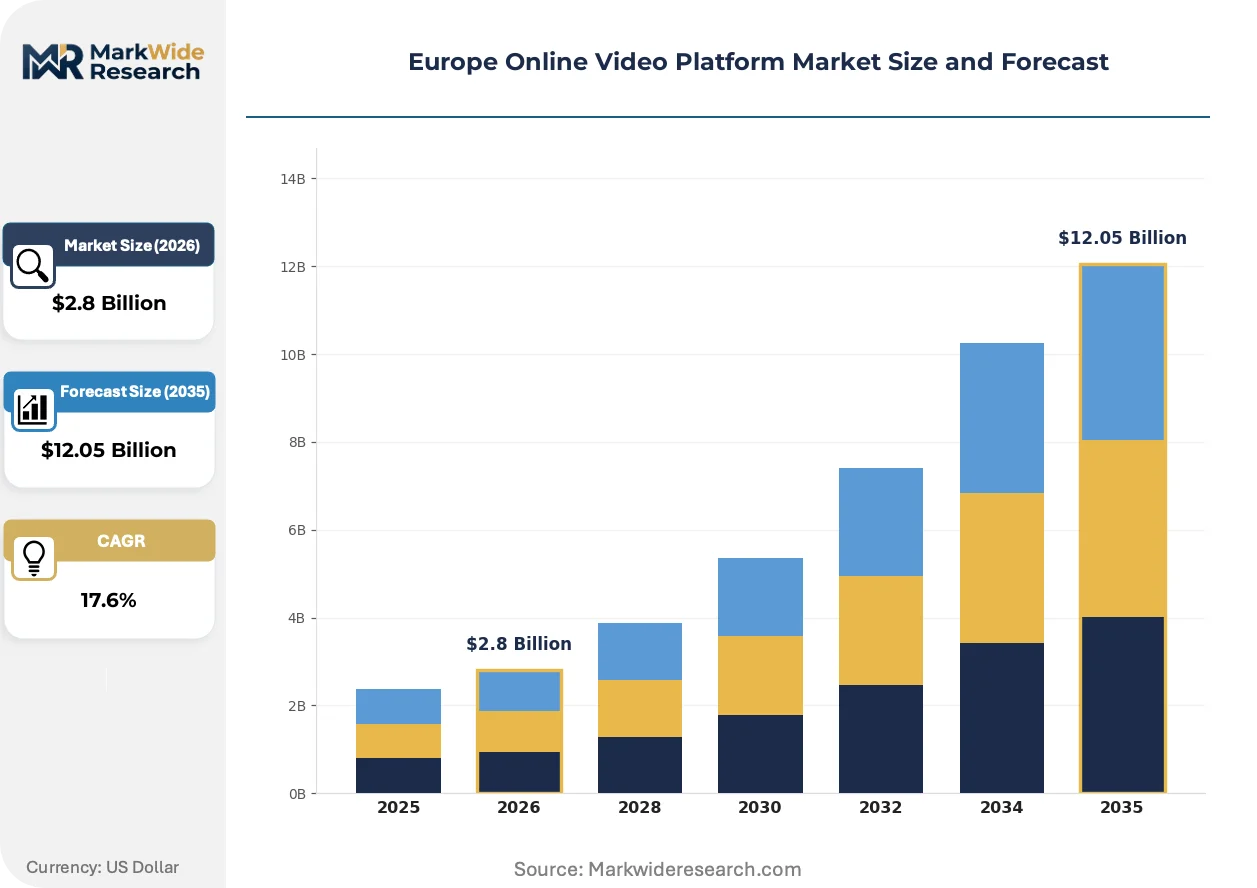
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.05 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streaming Services, Subscription VOD, Ad-supported VOD, Live Streaming Deployment Model: On-Premise, Cloud, Hybrid, Edge Computing End User: Media Companies, Enterprises, Educational Institutions, Individuals Service Type: Content Delivery, Video Editing, Encoding, Analytics |
| Companies Covered | HBO Max, YouTube, Netflix, Kaltura, Brightcove, Disney+, Viaplay, RTL Group, Amazon Prime Video, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Online Video Platform Market Strategic Shifts & Innovations
Encoding technology evolution and regulatory compliance architecture are converging to redefine platform differentiation, with efficiency and transparency emerging as dual competitive axes.
Per-title encoding optimization is miniaturizing bandwidth requirements for streaming operators. Netflix and regional subscription VOD services deploy machine learning-driven bitrate ladders that analyze visual complexity frame-by-frame. This compression efficiency is reducing CDN expenditure and enabling 4K delivery over constrained last-mile connections previously limited to HD.
GDPR enforcement patterns are reshaping data architecture decisions for personalization engines. National regulators in Germany and France impose divergent consent mechanisms and retention limits. Platforms now maintain jurisdiction-specific data silos, complicating unified recommendation models and increasing operational overhead for cross-border services.
Corporate training departments now specify outcome-based platform procurement rather than seat-licensed arrangements. Buyers demand usage analytics tied to knowledge retention metrics, displacing traditional learning management system contracts. This specification shift is most pronounced in German automotive and French pharmaceutical corporate academies.
Europe Online Video Platform Market Segmentation
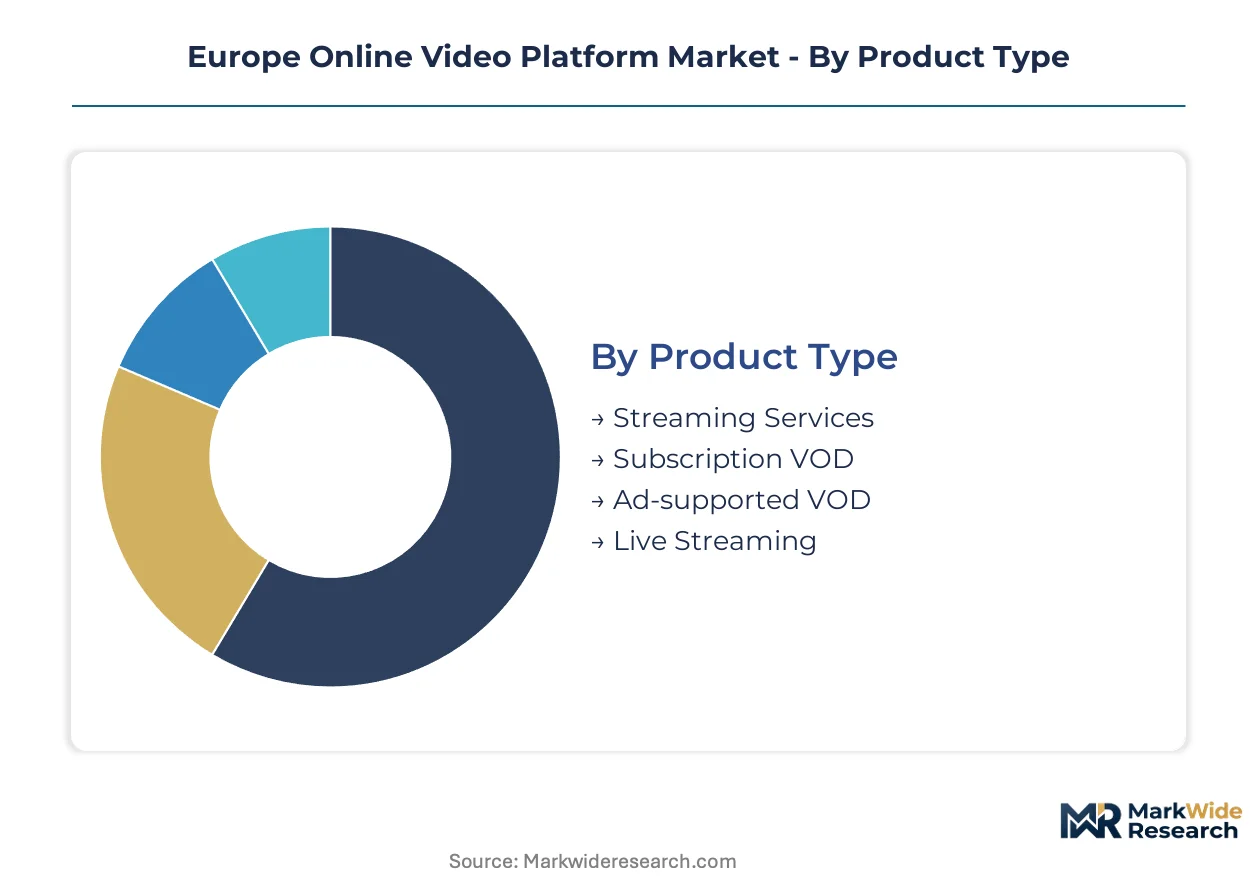
Segmentation in Europe's online video platform market reveals how substitution pressures from adjacent technologies reshape competitive boundaries. Understanding where streaming displaces broadcast, cloud supplants owned infrastructure, and enterprise video replaces legacy learning systems exposes vulnerability and opportunity across vendor portfolios.
Product Type:
Substitution pressure intensifies as streaming formats cannibalize traditional broadcast and physical media distribution, with live streaming now competing directly with scheduled television across sports and entertainment verticals.
- Streaming Services:These platforms deliver on-demand audiovisual content through adaptive bitrate protocols, maintaining playback quality across variable network conditions. Demand concentrates among subscription VOD operators in France and Germany investing in original regional content to differentiate against US catalog imports. EU AI Act transparency requirements for recommendation algorithms add compliance architecture costs that favor established operators with dedicated legal engineering teams.
- Live Streaming:Real-time video transmission enables synchronous audience participation for sports, gaming, and corporate communications. Latency-sensitive applications in UK wagering and German esports tournaments drive edge computing investments to sub-500 millisecond delivery targets. Bandwidth cost volatility between Tier-1 providers compresses margins for 4K live events at scale.
- Subscription VOD:Recurring revenue models fund original production slates tailored to national language preferences and cultural content regulations.
- Ad-supported VOD:Free-tier offerings monetize through programmatic advertising with GDPR-constrained targeting capabilities limiting yield optimization.
Streaming Services retains volume leadership; Live Streaming holds the steepest expansion curve.
Deployment Model:
Cost tier differentiation separates capital-intensive ownership from operational expenditure models, with hybrid architectures emerging as the compromise position for enterprises managing legacy encoding hardware alongside elastic cloud burst capacity.
- Cloud:Elastic compute and storage resources eliminate capital expenditure for encoding farms and origin servers, allowing media companies to scale with audience demand. French broadcasters and German publishers accelerate migration as depreciation cycles expire on owned hardware. Multi-cloud orchestration complexity across AWS, Azure, and GCP regions stretches mid-tier vendor engineering capabilities.
- Edge Computing:Distributed processing nodes position transcoding and caching infrastructure within metropolitan networks to minimize latency. UK sports streaming operators and Nordic gaming platforms deploy edge capacity for real-time interactivity features. Infrastructure investment requirements favor platforms with established CDN partnerships or telecommunications carrier relationships.
- On-Premise:Owned encoding hardware and private data centers persist where content security requirements or regulatory data localization mandates prohibit third-party infrastructure.
- Hybrid:Mixed architectures preserve sensitive workflow stages on private infrastructure while bursting transcoding and delivery to public cloud during peak demand.
Cloud deployment captures expanding share; Edge Computing is climbing the fastest as latency requirements harden.
End User:
Customer type segmentation maps to fundamentally different procurement patterns, with enterprise training departments rotating fastest from legacy learning management systems toward integrated video platforms.
- Enterprises:Corporate training departments specify outcome-based procurement tied to knowledge retention metrics rather than seat-licensed arrangements. German automotive and French pharmaceutical corporate academies consolidate video infrastructure under unified platforms supporting live streaming and on-demand playback. Procurement cycles compress as learning and development budgets shift from traditional LMS vendors.
- Educational Institutions:Universities in France and Germany execute campus-wide deployment contracts replacing fragmented departmental solutions. Kaltura anchors this segment through multi-year agreements covering lecture capture, virtual classroom, and media library functions. GDPR compliance for student data processing requires jurisdiction-specific architecture that complicates pan-European vendor standardization.
- Media Companies:Broadcasters and publishers monetize content through subscription, advertising, or licensing models with fragmented European advertising markets demanding sophisticated yield management tooling.
- Individuals:Creator economy participants and independent producers utilize self-service platforms for personal brand building and direct audience monetization.
Enterprises are gaining share fastest; Educational Institutions retain the deepest existing platform penetration.
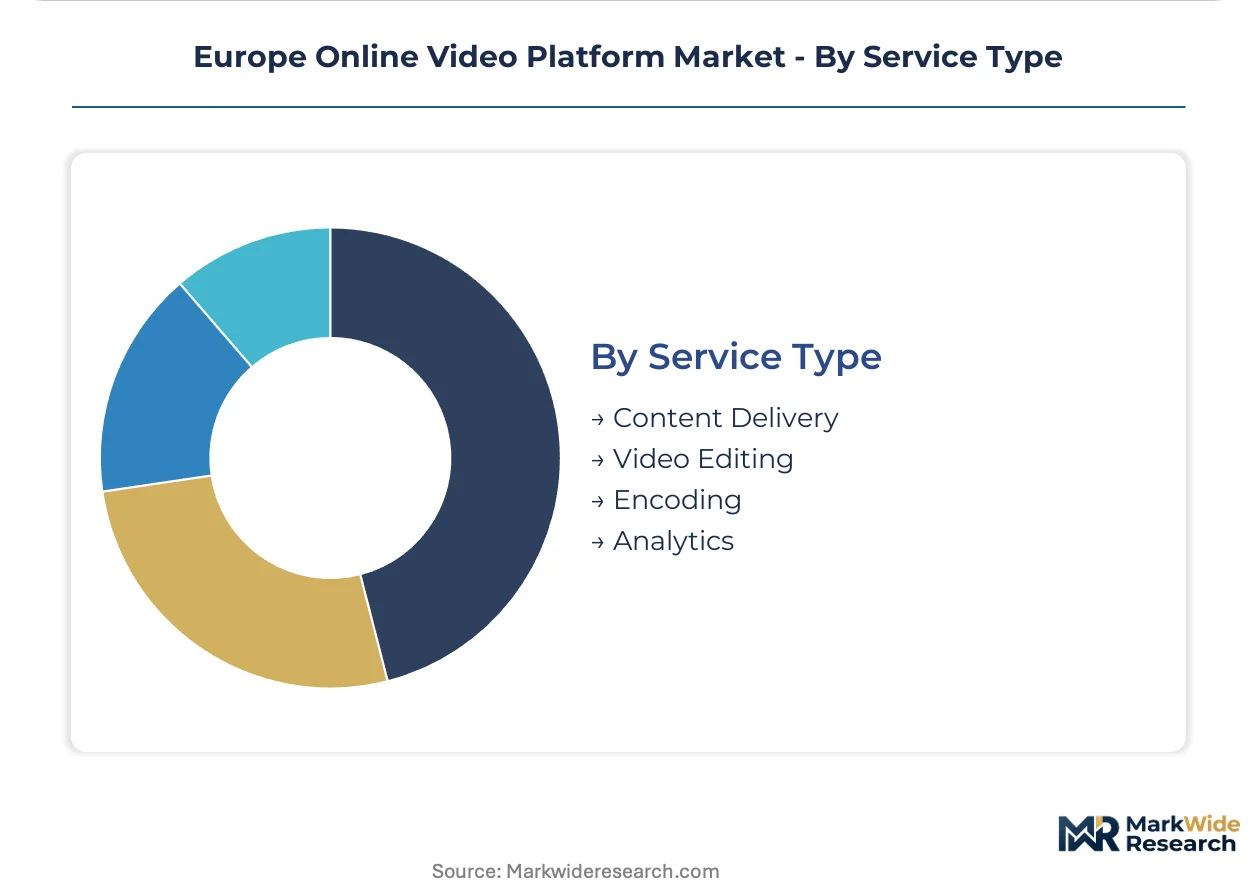
Service Type:
Supply concentration in specialized encoding expertise creates margin differentiation, with AV1 and VVC optimization talent commanding premium compensation that constrains platform R&D expansion.
- Encoding:Transcoding pipelines convert source media into multiple bitrate and resolution variants for adaptive streaming delivery. Netflix deploys proprietary per-title optimization analyzing visual complexity frame-by-frame to minimize bandwidth requirements. Codec specialization shortage limits vendor ability to differentiate on compression efficiency.
- Content Delivery:Global CDN networks cache and serve video segments from geographically distributed edge locations to minimize rebuffering and startup latency. Brightcove and regional specialists compete on European point-of-presence density and peering relationships with national ISPs.
- Video Editing:Cloud-native post-production tools enable collaborative workflows for distributed creative teams with browser-based timeline editing and asset management.
- Analytics:Engagement measurement and quality-of-experience monitoring inform content acquisition decisions and technical infrastructure optimization.
Content Delivery retains volume leadership; Encoding holds the steepest expansion curve as compression efficiency becomes competitive axis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise training departments concentrate procurement authority in France, Germany, and the United Kingdom, driving platform adoption across corporate academies and campus-wide educational contracts. National data protection authorities in these markets impose divergent consent frameworks that fragment personalization architectures.
Germany
Automotive corporate academies in Stuttgart and Munich specify outcome-based video platform procurement tied to knowledge retention metrics. The Federal Data Protection Authority enforces strict GDPR consent mechanisms for employee training data processing. Berlin anchors educational technology clusters where universities consolidate fragmented departmental video systems under unified campus contracts.
France
Pharmaceutical corporate training centers in Paris and Lyon demand platforms supporting EMA content classification for health-sector video deployments. CNIL imposes jurisdiction-specific data retention limits that complicate cross-border personalization engines. The Île-de-France region concentrates subscription VOD investment in original French-language production slates.
United Kingdom
Wagering operators and esports tournaments in London drive edge computing deployment for sub-500 millisecond live streaming latency. The Information Commissioner's Office restricts cross-border viewer data processing under GDPR enforcement patterns. Manchester and Birmingham host broadcast technology clusters migrating from owned encoding hardware to elastic cloud infrastructure.
Netherlands
Media companies in Amsterdam and Rotterdam accelerate multi-cloud orchestration across AWS, Azure, and GCP regions for redundancy requirements. The Dutch Data Protection Authority enforces transparency mandates for automated recommendation systems under EU AI Act implementation. Eindhoven's telecommunications infrastructure supports distributed edge node deployment for gaming platform operators.
Spain
Broadcasters in Madrid and Barcelona navigate fragmented European advertising markets with sophisticated yield management tooling. The Spanish Data Protection Agency aligns with GDPR cross-border friction patterns affecting pan-European services. Catalonia's technology corridor attracts platform vendors establishing southern European point-of-presence density.
Europe Online Video Platform Market Key Industry Players
Player mix skews toward subscription entertainment platforms and specialized enterprise video providers rather than pure-technology infrastructure vendors. Market structure exhibits tiered concentration with global streaming services occupying premium positions, regional broadcasters defending national language markets, and vertical specialists capturing educational and corporate training segments. Strategic archetypes include original content-funded subscription operators, compliance-integrated enterprise platforms, and edge-computing-enabled live streaming specialists. Dominant competitive moves encompass campus-wide contract consolidation in higher education and proprietary encoding pipeline development for bandwidth efficiency.
Within the subscription entertainment tier, Netflix and HBO Max exemplify original content investment strategies, while Disney+ occupies a position emphasizing franchise catalog depth. Among enterprise-focused providers, Kaltura represents the educational vertical specialist archetype through campus deployment concentration. Brightcove sits within the media monetization tier, addressing fragmented advertising market complexity. These three named entities anchor distinct competitive vectors without exhausting the vendor landscape.
| Leading Market Players |
|---|
| HBO Max |
| YouTube |
| Netflix |
| Kaltura |
| Brightcove |
| Disney+ |
| Viaplay |
| RTL Group |
| Amazon Prime Video |
| Others |
Cost & Logistics Intelligence
EU AI Act compliance certification gates platform vendor qualification while simultaneously enabling tiered pricing separation between audit-ready architectures and legacy systems lacking embedded transparency documentation. Pharmaceutical advertisers and financial services buyers pay premiums for EMA-aligned content classification modules that generalist platforms cannot provision without dedicated legal engineering investment.
Pricing Analysis
AV1 and VVC next-generation codec deployment commands 40-60% bandwidth cost savings over H.264 prior-generation baselines, creating pricing stratification across premium, standard, and economy service tiers. Subscription SaaS models dominate enterprise procurement, with outcome-based contracts displacing seat-licensed arrangements in German automotive academies. Price differentiation hinges on compression efficiency certification and GDPR jurisdiction-specific data architecture. Cost compression in live streaming tiers is intensifying because Tier-1 transit providers impose bandwidth volatility surcharges. Educational institutions exhibit highest price sensitivity; wagering operators demonstrate lowest sensitivity due to latency-driven performance requirements.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for encoding hardware components sourced from Taiwan and South Korea. Cloud infrastructure supply concentrates in Ireland, Netherlands, and Germany where hyperscaler regions anchor elastic compute capacity. Raw material dependencies span silicon wafers for GPU acceleration, specialized DRAM for edge node caching, and rare earth elements for optical transmission equipment. Single-source vulnerability in AV1 encoder ASIC supply from Taiwan-based foundries threatens platform R&D roadmaps. Distribution runs through telecommunications carrier partnerships and CDN peering agreements with national ISPs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's online video platform market sits at a high-growth inflection as EU AI Act transparency mandates force architectural rebuilds across incumbent recommendation engines. Edge computing deployment for sub-500 millisecond live streaming creates new competitive moats unattainable through software alone.
For Market Incumbents: Shield proprietary encoding pipelines through backward integration into custom ASIC development, denying challengers bandwidth efficiency parity. Consolidate campus-wide educational contracts in France and Germany before Kaltura anchors remaining fragmented departmental systems. Regulatory audit trail documentation represents the priority defensive lever against compliance-integrated entrants. For New Entrants and Emerging Players: GDPR jurisdiction-specific architecture certification fast-tracks penetration of pan-European services struggling with cross-border data fragmentation. White-space concentrates in pharmaceutical advertising compliance modules where EMA content classification standards exceed generalist platform capabilities. Target Dutch media companies pursuing multi-cloud orchestration redundancy as the most penetrable deployment segment. Go-to-market leverage rests on outsourced moderation infrastructure for Digital Services Act preparedness. For Investors and Strategic Acquirers: Carve-out targets emerge from telecommunications carriers with underutilized edge node infrastructure and stranded encoding hardware assets. Long-term viability favors platforms combining compression efficiency leadership with regulatory compliance architecture. Acquisition archetype: vertical specialists with campus deployment concentration in German-speaking markets. Signal to watch: EU AI Act enforcement patterns creating compliance-driven vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Encoding Pipeline Development | Netflix's per-title optimization demonstrates bandwidth cost advantages that compound at continental scale. |
| Edge Computing Infrastructure Partnership | UK wagering operators require sub-500 millisecond latency that only metropolitan node deployment satisfies. |
| Campus-Wide Educational Contract Consolidation | Kaltura's multi-year agreements with French and German universities establish switching cost barriers. |
| EMA Compliance Module Integration | Pharmaceutical advertisers in Paris and Lyon demand content classification capabilities generalists lack. |
| Multi-Cloud Orchestration Capability Buildout | Dutch media companies specify redundancy across AWS, Azure, and GCP regions stretching mid-tier vendors. |
Research Approach
Cross-validation between platform engineering executives and CDN infrastructure specialists anchors the qualitative findings on latency optimization tradeoffs. Primary interviews with enterprise learning and development officers, university IT procurement managers, streaming operations directors, and regulatory compliance leads informed vendor selection criteria shifts. Secondary sources encompassed EU AI Act implementation guidance, national data protection authority enforcement patterns, hyperscaler capex disclosures, and telecommunications carrier edge deployment announcements. Bottom-up contract value analysis triangulated against top-down market sizing from subscription VOD operator disclosures.
Sensitivity analysis across deployment model adoption curves, codec transition timelines, and regulatory enforcement intensity scenarios shaped the analytical framework. Segmentation dimensions modeled include product type, deployment architecture, end-user vertical, and service layer, with GDPR jurisdiction cluster as an additional cross-cutting variable. CAGRs derived from logistic diffusion curves fitted to enterprise migration patterns and cloud infrastructure spend trajectories. Industry-specific forecast inputs incorporated Tier-1 bandwidth pricing volatility indices and campus consolidation contract velocity.
Decision-makers should treat outputs as directional under sustained EU AI Act enforcement and stable hyperscaler expansion assumptions; material deviation would warrant model refresh. Forecasts reflect documented penetration rates for edge computing nodes and outcome-based procurement adoption. Bandwidth cost volatility, codec standardization delays, or fragmented national consent mechanism divergence could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Secondary Ticket Market
Digital Media
Anime Derivatives Market
Digital Media
Photography Services Market
Digital Media
Playout Solutions Market
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
Global Streaming Media Device Market
Digital Media
Drone Wedding Photography Market
Digital Media
Pro AV Market
Digital Media
Middle East and Africa Inflight Entertainment and Connectivity Market
Digital Media
Sports Graphics Market
Digital Media
Digital Content Creator Market
Digital Media
Photographic Services Market
Digital Media
China Webtoons Market
Digital Media
Digital Video Advertising Market
Digital Media
ACGN Subculture Market
Digital Media
Middle East Media and Entertainment Market