
 Production Optimization Software Market | 2026-2036
Production Optimization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Production Optimization Software Market Analytics
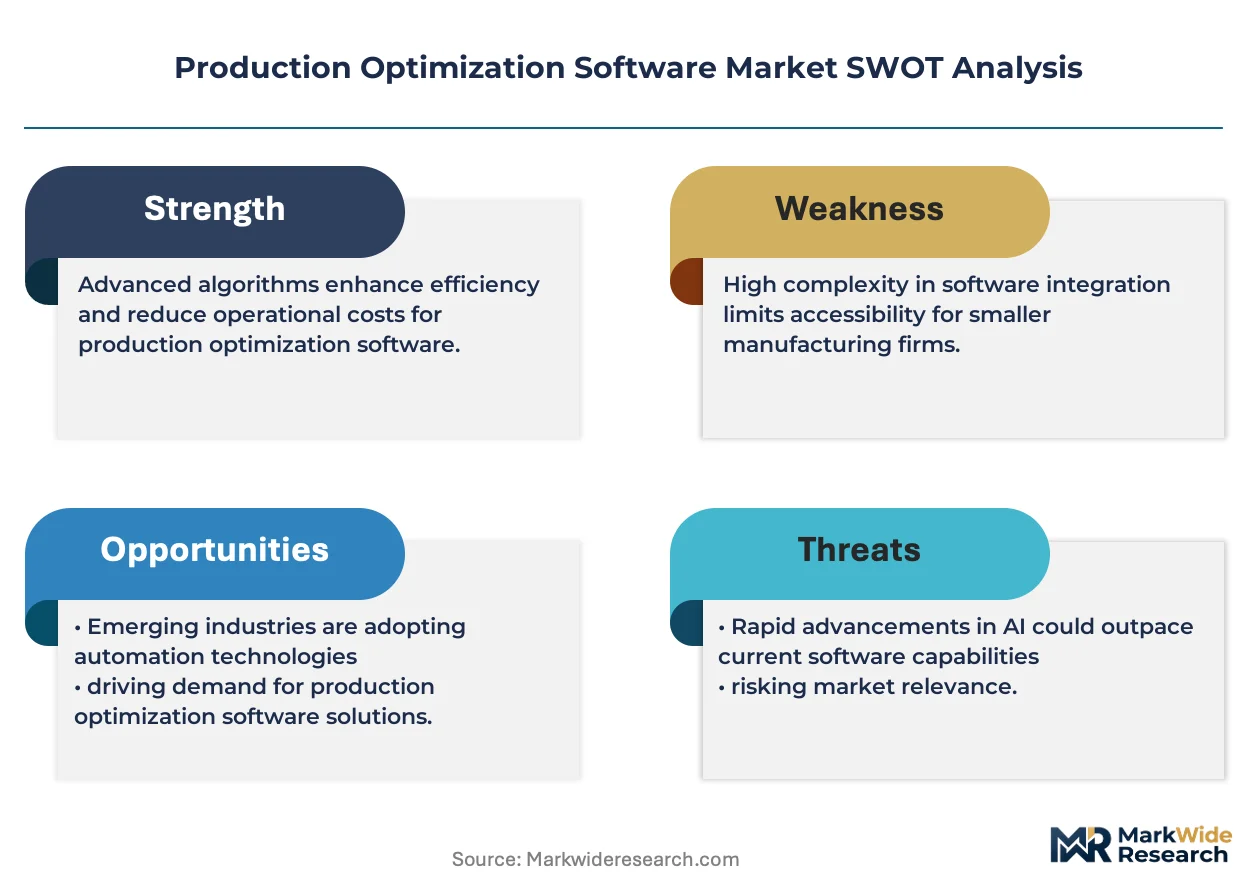
Data science talent scarcity is bifurcating the competitive landscape between full-stack platform vendors and niche optimization specialists. Accedia leverages its Bulgarian engineering base to deliver cost-advantaged custom implementations for European manufacturers. Software Mind sustains competitive presence through deep expertise in cloud-native architectures for process industries. Cognitops anchors its position with purpose-built warehouse and supply chain optimization modules.
Production optimization software encompasses algorithmic platforms that apply mathematical modeling, machine learning, and real-time data ingestion to maximize throughput, minimize waste, and synchronize equipment utilization across manufacturing operations. These systems typically integrate with SCADA, MES, and ERP layers through OPC-UA or MQTT protocols, processing sensor streams at sub-second latency to generate actionable setpoint adjustments. Cloud-based deployments capture expanding share as pharmaceutical and electronics manufacturers prioritize elastic compute for batch-to-batch variability analysis, while on-premise installations retain dominance in aerospace and defense sub-sectors where air-gapped security protocols govern infrastructure decisions. The automotive vertical concentrates investment in hybrid deployment models that balance edge-based line control with centralized supply chain orchestration.
ISO 22400 standards for key performance indicators in automated manufacturing operations shape functional requirements for cross-platform benchmarking, while FDA 21 CFR Part 11 compliance obligations in pharmaceutical applications mandate audit trails and electronic signature capabilities that extend software validation timelines. The EU AI Act introduces risk-classification requirements for autonomous optimization decisions in European facilities, pressuring vendors to embed explainability modules. Stakeholders must evaluate whether their current architectures can absorb impending regulatory complexity without fragmenting development roadmaps.
Market Dynamics
AI-driven predictive maintenance algorithms are compressing deployment timelines as oil and gas operators migrate from scheduled overhauls to condition-based intervention models. This shift is decomposing traditional service contracts and forcing vendors to restructure pricing around uptime guarantees rather than perpetual licenses.
Growth Catalysts
- FDA 21 CFR Part 11:Pharmaceutical manufacturers must maintain electronic audit trails and signatures, creating mandatory demand for validated optimization platforms with embedded compliance modules.
- Edge-to-cloud hybrid architectures:Automotive manufacturers balance millisecond-latency line control with centralized supply chain orchestration, driving dual-deployment software purchases.
- Real-time analytics platforms:Refinery operators in the United States deploy sensor fusion systems that reduce unplanned downtime through sub-second setpoint adjustments.
Market Restraints
- SCADA integration complexity:Legacy OPC-UA protocol stacks require expensive middleware development, inflating implementation budgets for brownfield facilities.
- EU AI Act risk classification:Autonomous optimization decisions in European facilities face mandatory explainability requirements, extending validation cycles.
- Specialized data science labor:Scarcity of industrial ML engineers concentrates talent in platform vendors, squeezing mid-tier implementation partners.
Strategic Opportunities
- ISO 22400 benchmarking modules:Cross-platform KPI standardization creates opening for vendors offering pre-configured performance measurement templates.
- Pharmaceutical batch variability analysis:Cloud-native elastic compute for biologics manufacturing remains underpenetrated relative to small-molecule facilities.
- China dual carbon goals:Energy-intensive process manufacturers face mandated efficiency improvements, accelerating demand for emissions-linked optimization algorithms.
Industry Challenges
- Air-gapped security protocols:Aerospace and defense sub-sectors require on-premise installations with zero external connectivity, complicating vendor cloud roadmaps.
- MES-ERP synchronization:Multi-layer integration projects frequently stall on data ontology mismatches between shop-floor and enterprise systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Production Optimization Software Market |
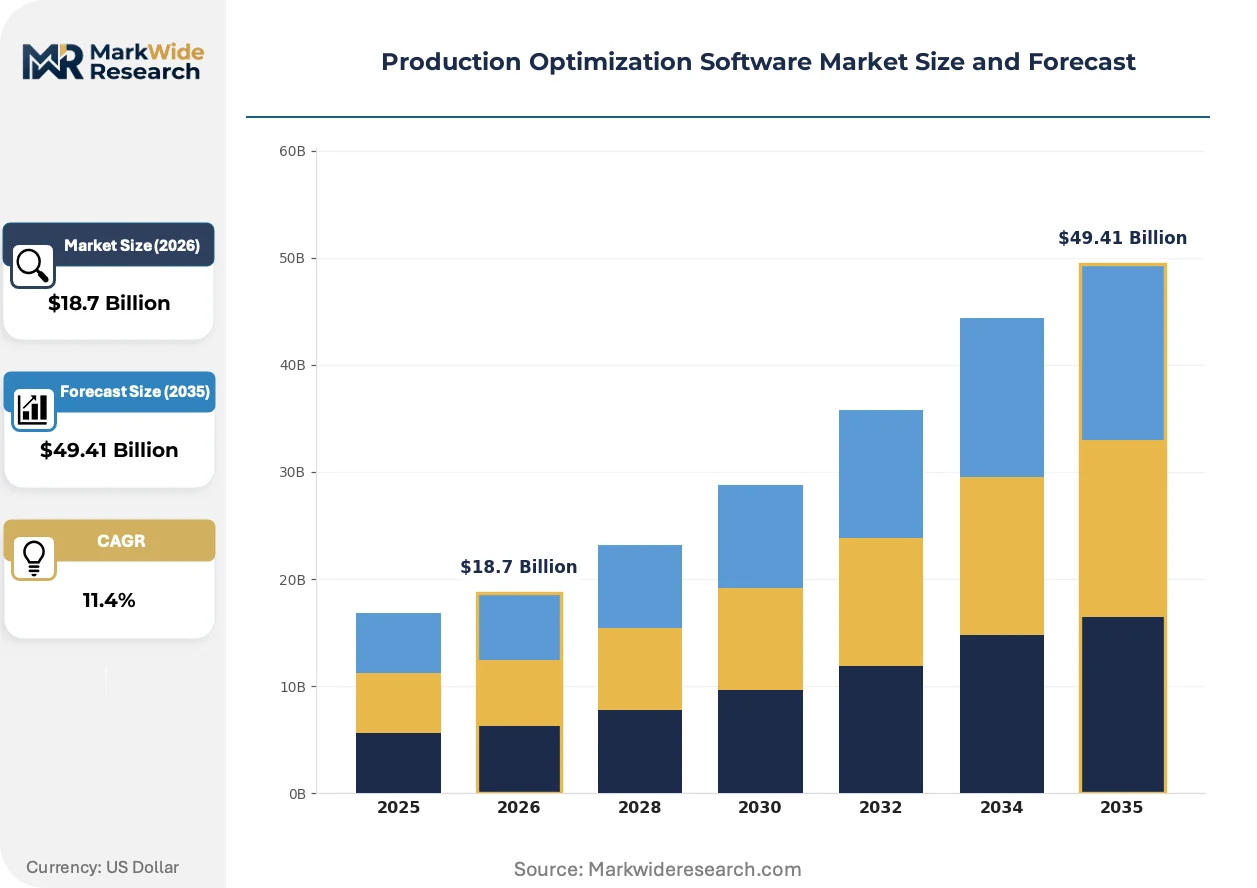
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Desktop End User: Manufacturers, Supply Chain Managers, Quality Assurance, Production Planners Industry Vertical: Aerospace, Automotive, Electronics, Pharmaceuticals Deployment Model: Private Cloud, Public Cloud, SaaS, On-Premises |
| Companies Covered | Accedia, *instinctools, ScienceSoft, CognitOps, Software Mind, Velvetech, ELEKS, Ulendo, Innowise Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Production Optimization Software Market Evolving Landscape
Digital twin architectures are migrating from visualization tools to closed-loop control systems, enabling real-time simulation of production scenarios before physical deployment. This evolution is compressing commissioning timelines and reducing capital risk for complex manufacturing investments.
Physics-informed neural networks are decomposing traditional first-principles modeling approaches in chemical processing. Specialty chemical manufacturers in Germany adopt these hybrid architectures to reduce pilot plant iterations. The technology is decomposing the competitive advantage of incumbent simulation vendors by lowering the barrier to accurate process prediction.
CSRD sustainability reporting mandates in Europe require granular energy and material flow documentation from manufacturing facilities. Industrial software vendors embed automated carbon accounting modules to capture compliance-driven procurement decisions. Pharmaceutical and electronics manufacturers in the Netherlands and France prioritize platforms with pre-built emissions calculation engines.
Subscription pricing for optimization modules is displacing perpetual license structures among mid-sized contract manufacturers. Equipment-as-a-service providers bundle software with hardware, capturing decision-making authority from traditional IT procurement functions. This pattern concentrates in German automotive supplier networks where OEMs dictate supplier technology stacks.
Production Optimization Software Market Segmentation
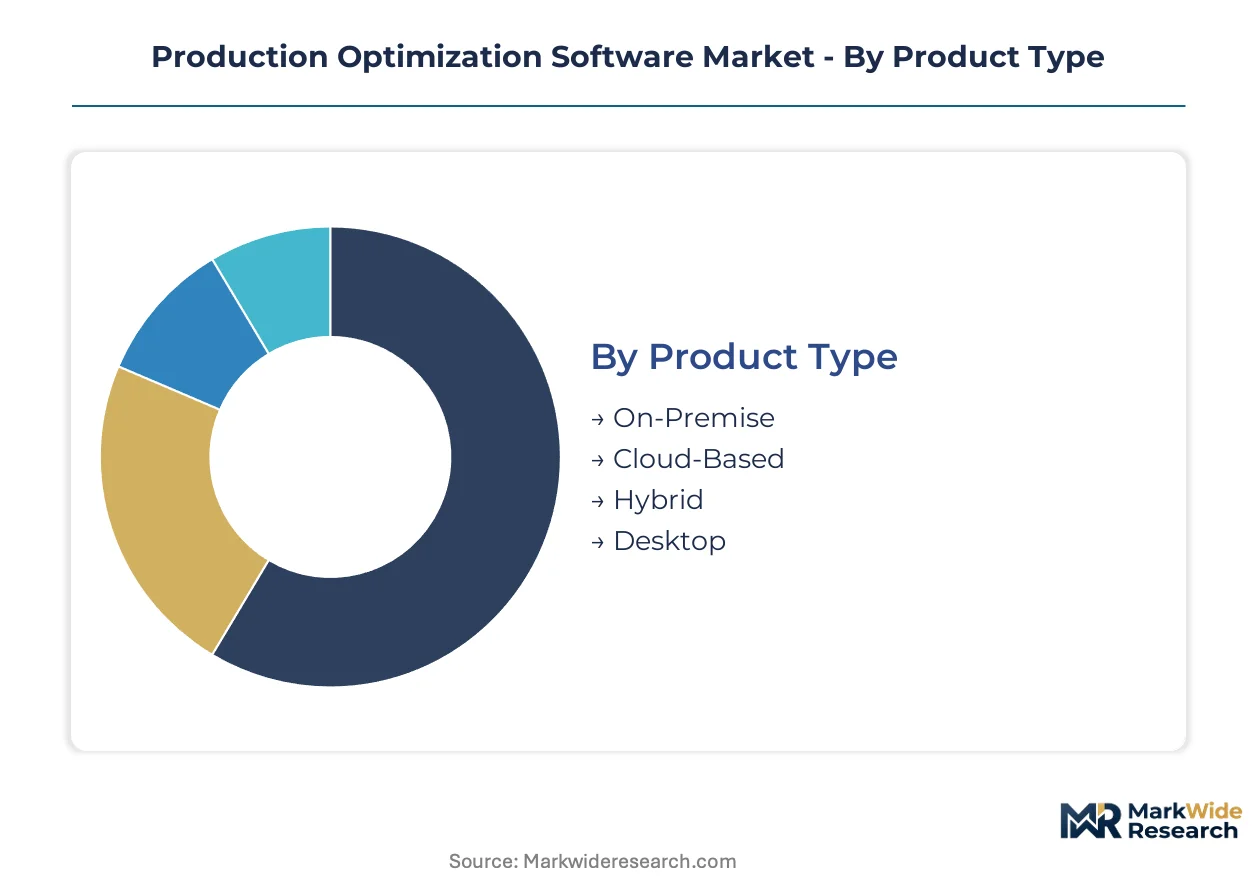
Production optimization software segments diverge sharply by infrastructure requirements and security postures. Deployment choices determine integration complexity, compliance validation timelines, and total cost of ownership across industrial verticals.
Product Type:
Cloud-based deployments face the most intense substitution pressure from hybrid architectures that reconcile latency constraints with elastic compute economics.
- On-Premise:Installed within facility data centers with zero external connectivity, satisfying air-gapped security mandates in aerospace and defense sub-sectors. Pharmaceutical manufacturers in Germany and the United States favor these installations for FDA 21 CFR Part 11 validation continuity, though upfront capital requirements constrain adoption among mid-tier contract manufacturers.
- Cloud-Based:Delivered through multi-tenant or dedicated tenant environments with automatic scaling for batch-to-batch variability analysis. Electronics manufacturers in Shenzhen and pharmaceutical clusters in the Netherlands prioritize these deployments for CSRD emissions reporting automation, despite persistent data residency concerns among European operators.
- Hybrid:Splits control logic between edge nodes for millisecond-latency line control and centralized cloud layers for supply chain orchestration. Automotive OEMs in Stuttgart and Detroit deploy these architectures to balance real-time production adjustments with enterprise ERP synchronization.
- Desktop:Legacy single-workstation installations persisting in small-batch chemical processing and toolroom environments. Limited scalability restricts these to pilot plant operations and educational training facilities.
On-premise installations retain volume leadership among regulated industries; hybrid deployments hold the steepest expansion curve as automotive manufacturers modernize legacy lines.
End User:
Cost tier stratification separates enterprise-wide platform purchases from departmental point solutions, with procurement authority increasingly shifting to operational technology budgets.
- Manufacturers:Plant operators seeking unified visibility across SCADA, MES, and ERP layers through OPC-UA or MQTT protocol integration. German automotive suppliers and Chinese steel producers drive demand for real-time throughput maximization modules.
- Supply Chain Managers:Procurement and logistics coordinators requiring demand forecasting alignment with production schedules. These users prioritize API connectivity to supplier networks and inventory optimization algorithms.
- Quality Assurance:Compliance officers mandating electronic audit trails and statistical process control documentation. FDA-regulated pharmaceutical facilities in North Carolina and Bavaria require validated software with embedded signature capabilities.
- Production Planners:Scheduling specialists balancing equipment utilization against changeover costs. Electronics contract manufacturers in Taiwan and Mexico concentrate investment in finite capacity scheduling modules.
Manufacturers dominate current procurement volumes; quality assurance represents the fastest-growing user category as regulatory validation requirements expand.
Industry Vertical:
Application maturity varies dramatically, with aerospace and defense retaining legacy on-premise dominance while electronics accelerates cloud-native adoption.
- Aerospace:Tier-one suppliers and airframe manufacturers governed by AS9100 quality standards and ITAR export controls. Boeing and Airbus supplier networks in Wichita and Toulouse require on-premise installations with zero external connectivity, complicating vendor cloud migration roadmaps.
- Automotive:OEMs and tier suppliers pursuing dual-deployment strategies for electric vehicle battery line optimization. Volkswagen, BMW, and BYD facilities deploy hybrid architectures balancing edge-based robotic control with centralized supply chain visibility.
- Electronics:Semiconductor and consumer device manufacturers prioritizing elastic compute for yield analysis and defect pattern recognition. TSMC and Samsung fabs in Hsinchu and Pyeongtaek drive demand for sub-second latency process control.
- Pharmaceuticals:Small-molecule and biologics manufacturers facing FDA 21 CFR Part 11 and EU GMP Annex 11 compliance obligations. Novartis and Roche facilities in Basel and Cambridge, Massachusetts require validated optimization platforms with embedded audit trail modules.
Automotive verticals capture the largest share of hybrid deployment investment; electronics manufacturing is expanding most quickly as foundry capacity constraints intensify.
Deployment Model:
Customer type concentration splits between capital-preference manufacturers favoring perpetual licenses and as-a-service adopters seeking operational expenditure alignment.
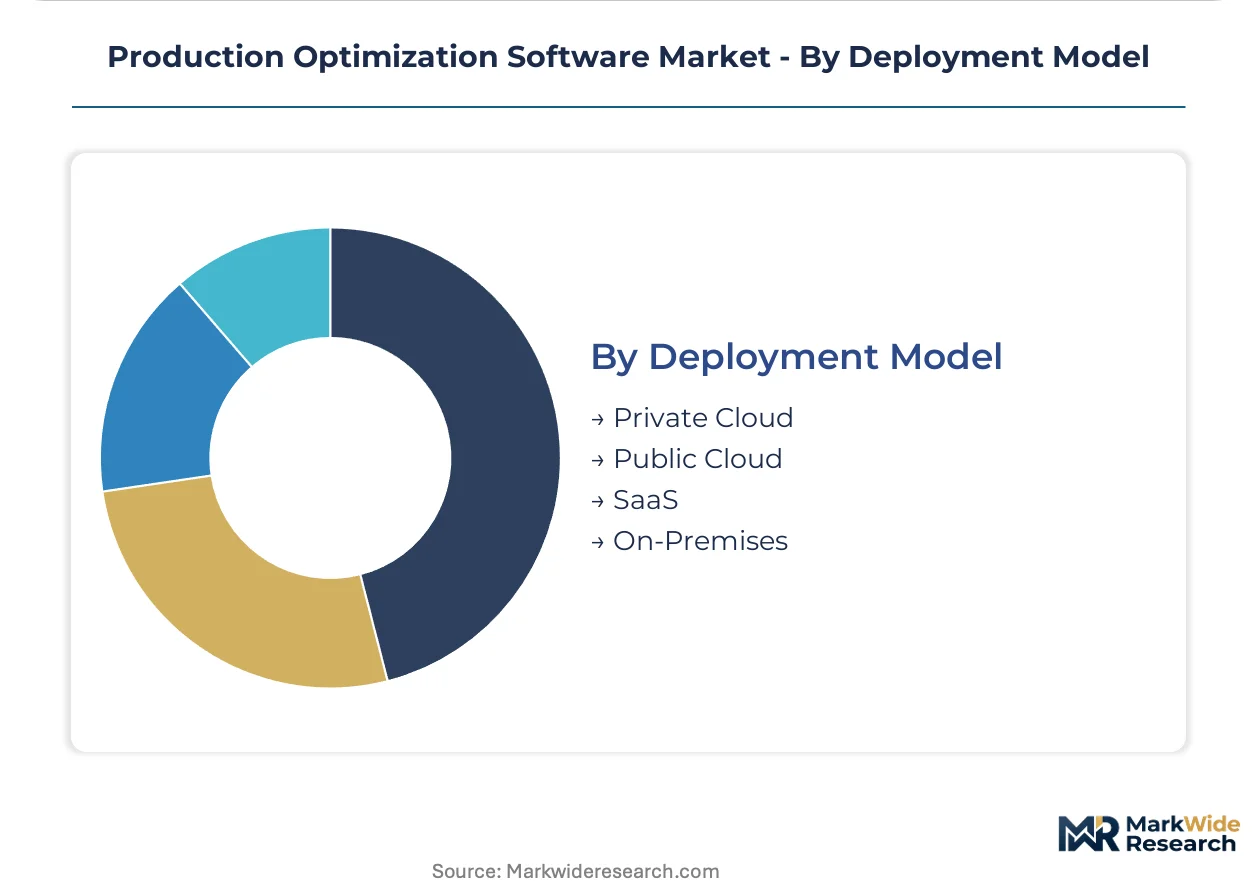
- Private Cloud:Single-tenant infrastructure deployed within enterprise data centers or dedicated colocation facilities. German automotive suppliers and Japanese precision manufacturers select these models for data sovereignty assurance.
- Public Cloud:Multi-tenant AWS, Azure, or GCP environments with consumption-based pricing. Mid-sized contract manufacturers in Vietnam and Poland adopt these for rapid deployment without infrastructure capital commitment.
- SaaS:Browser-accessible optimization modules with subscription pricing and automatic feature updates. Equipment-as-a-service providers bundle these with hardware, capturing procurement authority from traditional IT functions in German supplier networks.
- On-Premises:Perpetual-license software installed on customer-managed servers with annual maintenance contracts. Aerospace primes and defense contractors in California and Texas retain these for CMMC and ITAR compliance.
On-premises deployments retain dominance in security-critical applications; SaaS models are gaining share fastest among mid-tier contract manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers favor hybrid deployments balancing edge latency with cloud elasticity, while German operators prioritize on-premise validated systems for regulatory continuity, and Chinese steel and battery producers drive algorithmic intensity for emissions-linked efficiency mandates.
United States
Refinery operators in Texas and Louisiana deploy sensor fusion platforms for sub-second setpoint adjustments that compress unplanned downtime intervals. FDA 21 CFR Part 11 compliance obligations in North Carolina pharmaceutical clusters mandate validated software with embedded electronic signature capabilities. Boeing supplier networks in Wichita retain air-gapped on-premise installations under ITAR export controls.
Germany
Automotive OEMs in Stuttgart and Munich pursue dual-deployment architectures for electric vehicle battery line optimization. EU AI Act risk-classification requirements pressure Munich and Bavaria facilities to embed explainability modules in autonomous optimization decisions. Specialty chemical manufacturers in Ludwigshafen adopt physics-informed neural networks to reduce pilot plant iterations.
China
Steel producers in Tangshan and Baotou face MIIT-mandated efficiency improvements under dual carbon goals that accelerate emissions-linked algorithm adoption. NMPA validation frameworks for pharmaceutical facilities in Jiangsu and Zhejiang extend software deployment timelines. BYD and CATL battery fabs in Shenzhen and Ningbo drive sub-second latency process control investment.
Japan
Precision manufacturers in Nagoya and Osaka select private cloud models for data sovereignty assurance alongside METI-industry efficiency standards. JIS-compliant quality documentation requirements shape software functional specifications for Toyota supplier networks. Semiconductor equipment makers in Kyushu concentrate demand for yield analysis modules.
Netherlands
Pharmaceutical manufacturers in Rotterdam and Oss prioritize cloud-native platforms with pre-built CSRD emissions calculation engines for sustainability reporting automation. EMA-aligned validation protocols govern software selection for biologics facilities. Electronics contract manufacturers in Eindhoven deploy elastic compute for batch-to-batch variability analysis.
Production Optimization Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across deployment model expertise and vertical-specific validation capabilities. The competitive terrain separates full-stack platform vendors with cloud-native architectures from niche optimization specialists delivering cost-advantaged custom implementations. Three strategic archetypes dominate: engineering-base arbitrage players, compliance-focused validation specialists, and hybrid-deployment integrators. Market evolution is compressing through M&A consolidation of point-solution vendors and strategic partnerships bundling software with equipment-as-a-service offerings.
Within the engineering-base arbitrage tier, Accedia leverages its Bulgarian development center to deliver cost-advantaged implementations for European manufacturers. Software Mind exemplifies cloud-native architecture specialization for process industries. CognitOps occupies a position among purpose-built supply chain and warehouse optimization specialists. These three anchors represent distinct competitive vectors—geographic cost structure, technical architecture depth, and vertical module specificity—that define strategic positioning across the European and North American demand concentration.
| Leading Market Players |
|---|
| Accedia |
| *instinctools |
| ScienceSoft |
| CognitOps |
| Software Mind |
| Velvetech |
| ELEKS |
| Ulendo |
| Innowise Group |
| Others |
Value Network & Pricing Analysis
Ninety-day implementation cycles for brownfield SCADA integration concentrate pricing power with vendors possessing pre-built middleware libraries, compressing margins for implementation partners without protocol expertise. Pharmaceutical manufacturers in North Carolina and Bavaria absorb premium pricing for FDA-validated modules, while mid-sized contract manufacturers in Vietnam and Poland gravitate toward SaaS tiers that eliminate infrastructure capital.
Pricing Analysis
Project-based contracting dominates complex brownfield deployments, with perpetual licensing persisting in aerospace and defense applications governed by ITAR and CMMC requirements. Price differentiation hinges on FDA 21 CFR Part 11 validation tier and edge-to-cloud integration depth. Cost compression in the mid-market SaaS tier intensifies as equipment-as-a-service providers bundle software with hardware, eroding standalone procurement authority. Contract manufacturers in German automotive supplier networks exhibit highest price sensitivity due to OEM-mandated technology stack compliance; pharmaceutical quality assurance officers show lowest sensitivity where regulatory validation timelines dominate total cost.
Supply Chain Analysis
Specialized industrial ML engineering talent in Bulgaria, Poland, and Vietnam anchors delivery capacity for European and North American platform vendors. Software development draws from cloud-native architecture specialists, OPC-UA protocol engineers, and regulatory validation consultants. Single-source vulnerability concentrates in FDA validation expertise, where qualified practitioners cluster in Basel, Cambridge, and Research Triangle Park. Distribution runs through direct enterprise sales for on-premise deployments, with hyperscaler marketplaces capturing expanding SaaS volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive OEMs and Chinese battery producers, with procurement authority shifting from IT departments to operational technology budgets as equipment-as-a-service models proliferate.
For Market Incumbents: Secure embedded positions in FDA-validated pharmaceutical installations before NMPA-aligned frameworks extend validation timelines in China. Acquire boutique OPC-UA middleware specialists to compress brownfield implementation cycles and defend against engineering-base arbitrage players. Prioritize explainability module development ahead of EU AI Act enforcement waves. For New Entrants and Emerging Players: ISO 22400 benchmarking certification fast-tracks entry into German automotive supplier networks seeking cross-platform KPI standardization. Target cloud-native elastic compute for pharmaceutical batch variability analysis, where biologics manufacturing remains underpenetrated relative to small-molecule facilities. Pursue equipment-as-a-service bundling partnerships with European automation hardware distributors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial software conglomerates seeking to monetize non-core optimization modules. Five-to-ten-year viability favors hybrid-deployment integrators with validated pharmaceutical footprints over pure-play cloud vendors lacking regulatory continuity. Watch for MIIT efficiency mandate acceleration in Chinese steel and battery production as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | OPC-UA middleware acquisition compresses brownfield deployment timelines for European manufacturers. |
| Regulatory Validation Investment | FDA 21 CFR Part 11 pre-certification accelerates pharmaceutical procurement cycles in North Carolina clusters. |
| Geographic Expansion | Bulgarian and Polish engineering centers capture cost-advantaged implementation demand from mid-tier contract manufacturers. |
| Strategic Partnership | Equipment-as-a-service bundling with German automation OEMs shifts procurement authority from IT functions. |
| Acquisition of Specialist Firm | Physics-informed neural network talent acquisition decomposes incumbent simulation vendor advantage in specialty chemicals. |
Research Methodology
The analysis maps cloud-native deployment, hybrid architecture, on-premise installation, and desktop legacy segments, each validated through plant engineers, IT procurement officers, regulatory affairs leads, and integration specialists. Primary interviews combined with secondary validation from SEC filings, hyperscaler capex disclosures, FDA 510(k) and software validation databases, and EU MDR technical documentation. Bottom-up deployment model sizing triangulated against top-down vertical spending estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical application, integration complexity, and regional regulatory cluster. CAGRs derived from slope-intercept analysis of adoption curve inflection points, with inputs including MIIT efficiency mandate timelines, EU AI Act implementation waves, and pharmaceutical batch-to-batch variability compute demand curves.
Decision-makers should treat outputs as directional under assumptions of sustained FDA validation timeline stability and EU AI Act risk-classification adherence; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as NMPA framework convergence and CSRD reporting automation adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
System Infrastructure Software Market
Software & Services
Full Screen Website Screenshot Software Market
Software & Services
Software Testing Company Market
Software & Services
On-Call Scheduling Software Market
Software & Services
Session Support Software Market
Software & Services
Global Localization Software Market
Software & Services
Dealer Management System Market
Software & Services
Software-Defined Machine Market
Software & Services
Predictive Dialer Software Market
Software & Services
Global Email Software Market
Software & Services
Construction Simulation Software Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Online Project Management Software Market
Software & Services
Appointment Scheduling Software Market
Software & Services
Courier Software Market