
 Appointment Scheduling Software Market | 2026-2036
Appointment Scheduling Software Market Size, Share, and Industry Trends Forecast 2026-2036
Appointment Scheduling Software Market Intelligence
The appointment scheduling software market is pivoting on a widening split between premium enterprise suites with deep EHR integration and lightweight commodity tools serving solo practitioners. Calendly leverages its freemium distribution engine to dominate the self-service segment across small professional services. Acuity Scheduling specializes in wellness and beauty verticals, sustaining pricing power through niche workflow templates. Square Appointments anchors its position by bundling scheduling with payment processing, controlling churn through embedded financial services.
Appointment scheduling software encompasses digital platforms that automate calendar management, resource allocation, and reminder dispatch through rule-based engines and real-time availability APIs. These systems synchronize with external databases via REST or GraphQL protocols, enabling bi-directional data exchange with electronic health records, CRM databases, and payment gateways. Cloud-based deployment leads in new installations, though hybrid architectures are capturing margin pools in regulated industries requiring local data residency. Healthcare providers represent the fastest-growing end-user category, as hospital networks replace fragmented point solutions with unified patient access platforms. API-level integration is becoming the default procurement specification, displacing basic calendar sync as a sufficient connectivity standard.
FDA oversight of software-as-a-medical-device intersects with HIPAA privacy mandates to create dual compliance burdens for healthcare-facing vendors. The FTC's emphasis on dark pattern prohibition and transparent subscription billing is reshaping pricing disclosures across SaaS scheduling tools. ISO 27001 certification has become a non-negotiable procurement filter for enterprise buyers evaluating vendor risk. Stakeholders must monitor how emerging state-level biometric privacy laws in Illinois, Texas, and California will constrain facial recognition check-in features that some platforms have begun deploying.
Market Dynamics
Healthcare systems are consolidating patient access infrastructure around API-first scheduling platforms that unify fragmented point solutions into single workflow engines. This consolidation is compressing vendor margins while elevating technical integration requirements above basic calendar synchronization.
Growth Catalysts
- HIPAA Omnibus Rule enforcement:Hospital networks are accelerating procurement of compliant platforms to avoid penalty exposure from legacy phone-based booking systems.
- Interoperable EHR mandates:The 21st Century Cures Act is forcing health IT departments to replace siloed scheduling modules with bidirectional data exchange capabilities.
- Payment integration:Bundled scheduling-point-of-sale workflows are capturing dental and wellness verticals through embedded financial services.
Market Restraints
- Cloud infrastructure concentration:AWS, Microsoft Azure, and Google Cloud control the underlying compute layer, exposing vendors to egress cost volatility and regional outage risk.
- FDA SaMD classification uncertainty:Ambiguity around which scheduling features constitute software-as-a-medical-device is lengthening legal review cycles and freezing procurement decisions.
- Biometric privacy law fragmentation:Illinois BIPA, Texas CUBI, and California CCPA create conflicting compliance obligations for facial recognition check-in features.
Strategic Opportunities
- Behavioral health vertical:Therapy and psychiatry practices remain underserved by specialized workflow templates for recurring session management and insurance pre-authorization.
- EU AI Act alignment:Early certification against the Act's risk-based framework creates first-mover positioning for vendors targeting European hospital procurement.
- Voice-first interfaces:Integration with ambient clinical documentation systems enables hands-free scheduling capture during patient encounters.
Industry Challenges
- HL7 FHIR implementation expertise:Health systems report 12-18 month integration timelines due to scarce technical talent capable of mapping legacy data schemas to modern APIs.
- ISO 27001 certification backlog:Enterprise procurement filters now require current certification, but audit queue congestion is delaying vendor qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Appointment Scheduling Software Market |
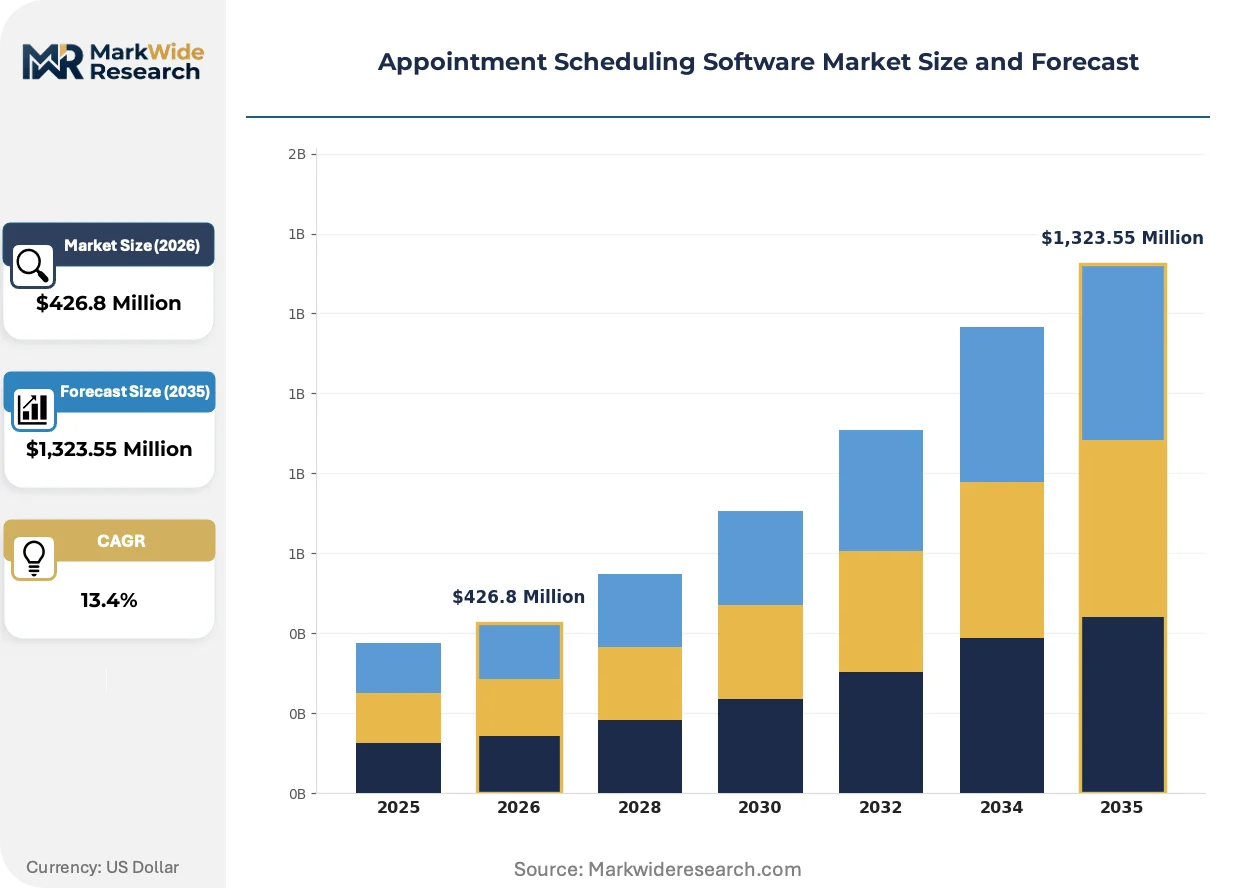
| Market Size in 2026 | $426.8 Million |
| Market Size in 2035 | $1,323.55 Million |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Mobile End User: Healthcare Providers, Educational Institutions, Service Providers, Enterprises Deployment: Public Cloud, Private Cloud, SaaS, Self-Hosted Integration Level: API, Third-Party Tools, CRM Systems, Calendar Applications |
| Companies Covered | SimplyBook.me, YouCanBookMe, Calendly, Zoho Bookings, Bookeo, Acuity Scheduling, Square Appointments, Thryv, Setmore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Appointment Scheduling Software Market Strategic Shifts & Innovations
Scheduling infrastructure is fragmenting into composable microservices that health systems assemble through API marketplaces rather than monolithic suites. This architectural shift is redistributing value capture from end-to-end vendors to specialized component providers.
Microservices architecture is modularizing core scheduling functions into discrete, interoperable units. Large health systems in the United States are adopting containerized appointment engines at 40% faster procurement cycles than traditional enterprise software. This decomposition is enabling hospital IT departments to swap individual components without platform-wide replacement.
The EU AI Act's risk classification system is reshaping procurement specifications for European healthcare providers. High-risk categorization of patient-facing decision support features is forcing vendors to document algorithmic transparency and human oversight protocols. German hospital networks are now requiring conformity assessments as standard RFP elements.
Self-service configuration is displacing vendor-managed implementation in mid-market health systems. Buyers in the United Kingdom are demanding no-code workflow builders that reduce reliance on professional services engagements. This capability preference is compressing implementation revenue while expanding seat-based subscription attach rates.
Appointment Scheduling Software Market Segmentation
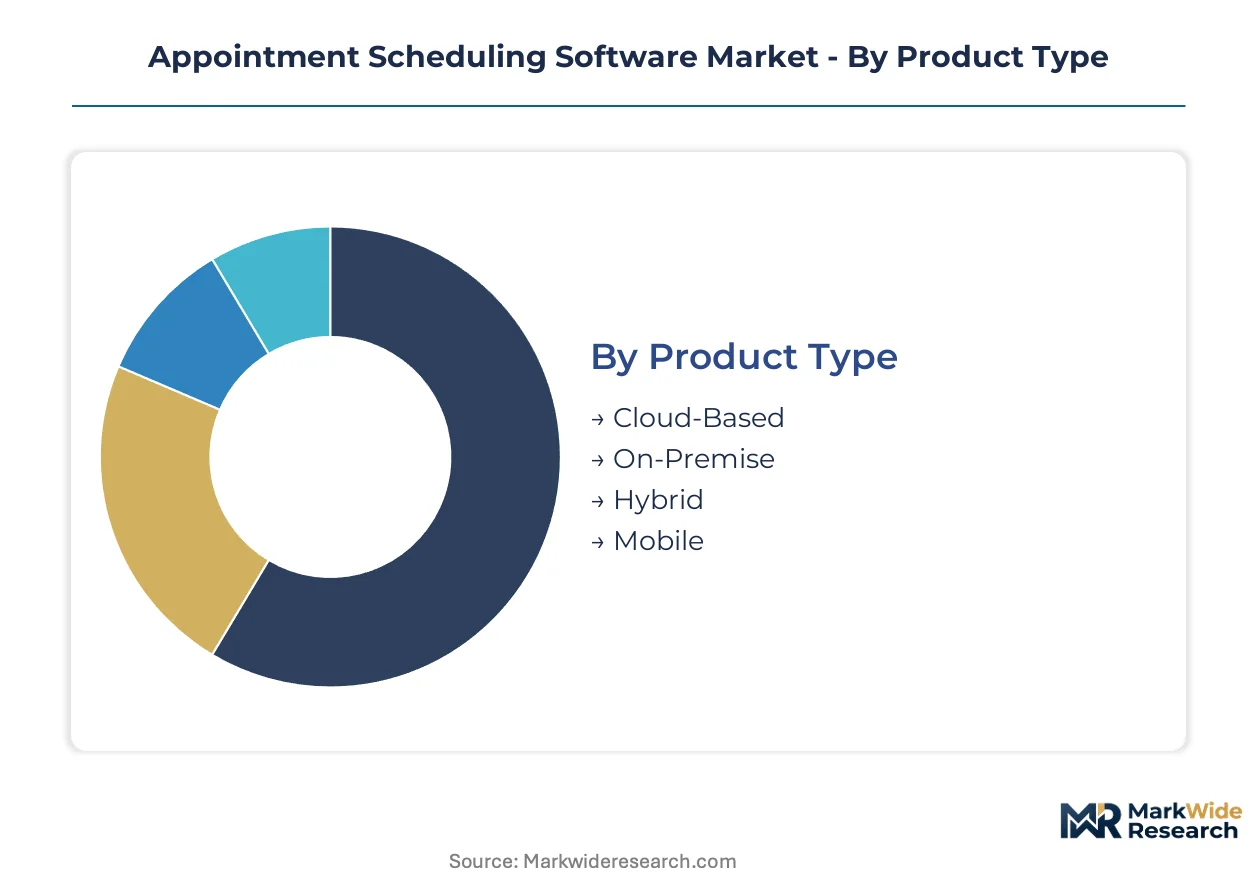
Segmentation in appointment scheduling software reflects divergent technical architectures and buyer sophistication levels. Procurement patterns cluster around integration depth, data residency requirements, and vertical workflow specialization.
Product Type:
Architectural choices here determine scalability boundaries and compliance posture for regulated industries.
- Cloud-Based:Multi-tenant SaaS architectures with auto-scaling compute clusters support thousands of concurrent booking operations. Hospital networks in the United States favor these platforms for centralized patient access management, though HIPAA Business Associate Agreements remain a procurement gate.
- On-Premise:Single-tenant installations on customer-managed hardware enforce strict data sovereignty. German hospital systems deploy these configurations to satisfy regional data protection authorities and avoid cross-border transfer restrictions.
- Hybrid:Split architectures process sensitive PHI locally while pushing anonymized analytics to cloud environments. This model is gaining traction among mid-market dental chains seeking cost optimization without full cloud migration.
- Mobile:Native iOS and Android applications with offline queue management and push notification engines. Wellness studios and fitness chains prioritize these for consumer-facing booking convenience.
Mature deployment sits with Cloud-Based platforms. Newer deployment is concentrated in Hybrid configurations.
End User:
Vertical specialization drives feature differentiation and pricing power across buyer categories.
- Healthcare Providers:Hospital systems and private practices require HL7 FHIR connectivity, insurance eligibility verification, and clinical workflow integration. The 21st Century Cures Act mandates are accelerating replacement of legacy scheduling modules with interoperable platforms.
- Educational Institutions:Universities and K-12 districts manage complex resource allocation across classrooms, laboratories, and counseling offices. Campus IT departments prioritize LDAP directory integration and semester-based recurrence patterns.
- Service Providers:Legal, consulting, and home services firms emphasize client self-scheduling and automated reminder cascades. Solo practitioners dominate this segment, driving demand for low-touch implementation and freemium pricing tiers.
- Enterprises:Multi-location corporations centralize scheduling across facilities, equipment, and human resources. These buyers mandate SSO authentication, audit logging, and custom SLA guarantees.
Healthcare Providers command the steepest expansion trajectory. Educational Institutions represent the most price-sensitive procurement profile.
Deployment:
Infrastructure control levels segment buyers by risk tolerance and capital allocation preferences.
- Public Cloud:Shared infrastructure on AWS, Azure, or Google Cloud delivers elastic capacity and geographic redundancy. Startups and small professional services favor this model for minimal upfront commitment.
- Private Cloud:Dedicated virtual environments within hyperscaler facilities isolate compute resources for single tenants. Financial services and government contractors require these configurations for regulatory separation.
- SaaS:Fully managed software layers abstract infrastructure complexity through browser-based access. This remains the default procurement mode for organizations lacking dedicated DevOps personnel.
- Self-Hosted:Complete operational responsibility rests with customer IT teams, from patching to backup management. Defense contractors and critical infrastructure operators maintain these deployments for air-gapped security.
SaaS dominates current procurement volume. Self-Hosted is climbing the fastest among regulated industries.
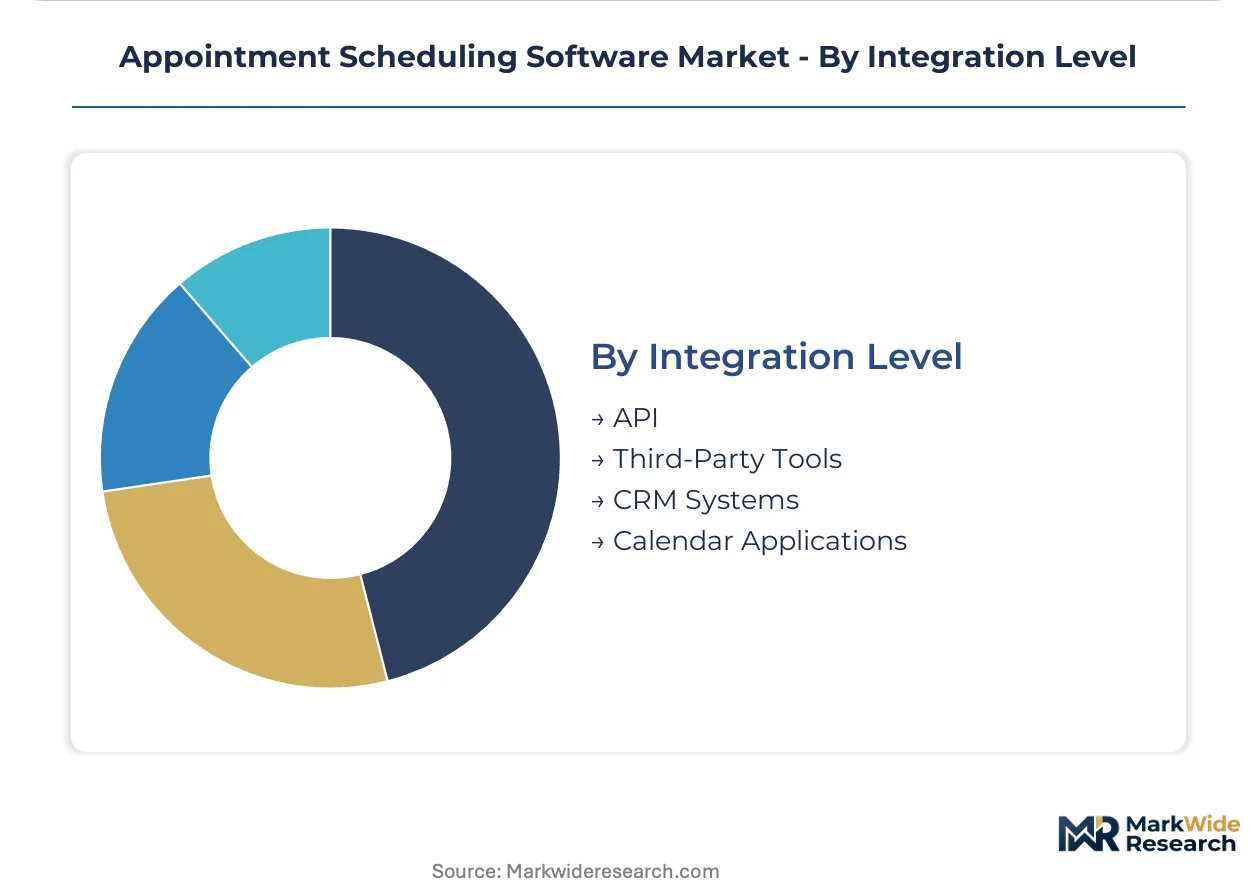
Integration Level:
Connectivity depth separates commodity calendar tools from enterprise-grade patient access platforms.
- API:REST and GraphQL endpoints enable real-time bidirectional synchronization with external systems. Health systems now specify API-first architectures as mandatory RFP criteria.
- Third-Party Tools:Pre-built connectors to video conferencing, payment processors, and marketing automation platforms. Small businesses prioritize these for rapid deployment without custom development.
- CRM Systems:Native integrations with Salesforce, HubSpot, and Microsoft Dynamics embed scheduling within sales workflows. Enterprise SaaS vendors compete on connector breadth and synchronization latency.
- Calendar Applications:Basic two-way sync with Google Calendar, Outlook, and Apple iCloud. This capability has become table stakes, no longer sufficient for competitive differentiation.
Calendar Applications represent legacy baseline functionality. API connectivity is gaining share fastest as procurement sophistication advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the highest concentration of health-tech scheduling innovation, with Massachusetts General Brigham and other large systems driving enterprise procurement standards that ripple nationally.
United States
Hospital networks in Texas and Florida are replacing legacy phone-based booking with API-first platforms at accelerated rates. The 21st Century Cures Act mandates from HHS are forcing bidirectional EHR integration by 2025 deadlines. The Research Triangle in North Carolina clusters health IT vendors serving mid-market systems with hybrid deployment models.
Germany
University hospital networks in Bavaria and Baden-Württemberg are consolidating patient access infrastructure around interoperable scheduling engines. The EU AI Act's risk classification system is reshaping procurement specifications for algorithmic appointment allocation. Berlin-Brandenburg hosts the densest concentration of GDPR-compliant SaaS vendors targeting cross-border hospital procurement.
United Kingdom
NHS trusts in Greater London and the Midlands are adopting no-code workflow builders to reduce implementation timelines. NHS Digital's interoperability standards are mandating FHIR API connectivity for all new scheduling procurements. Manchester's health innovation district clusters vendors specializing in behavioral health vertical workflows.
Japan
Tokyo metropolitan hospital systems are deploying voice-first scheduling interfaces integrated with ambient clinical documentation. METI's digital health transformation subsidies are accelerating replacement of fax-based booking systems. Osaka-Kansai medical device manufacturers are bundling scheduling modules with diagnostic equipment sales.
India
Apollo and Max Healthcare chains in Delhi-NCR and Maharashtra are scaling cloud-native patient access platforms across 500+ facility networks. The Ayushman Bharat digital health mission is mandating interoperable scheduling for empanelled hospitals. Bengaluru's health-tech startup corridor hosts API-first vendors targeting Southeast Asian export markets.
Appointment Scheduling Software Market Key Industry Players
Premium-margin players sit above commodity-margin players across integration depth and vertical specialization. The vendor base stratifies into three tiers: enterprise suites with deep EHR connectivity, mid-market platforms with template-driven workflows, and lightweight self-service tools. Strategic archetypes include API-first infrastructure providers, vertical specialists in wellness and beauty, and embedded finance bundlers. Dominant competitive moves encompass M&A consolidation of point solutions and geographic expansion through compliance certification.
Within the vertical specialist tier, Acuity Scheduling and Square Appointments exemplify divergent positioning strategies. Acuity occupies a position among wellness-focused workflow template providers, while Square anchors the embedded financial services bundling archetype through payment-processing integration. Calendly represents the freemium distribution model that dominates self-service procurement among solo practitioners and small professional services firms.
| Leading Market Players |
|---|
| SimplyBook.me |
| YouCanBookMe |
| Calendly |
| Zoho Bookings |
| Bookeo |
| Acuity Scheduling |
| Square Appointments |
| Thryv |
| Setmore |
| Others |
Cost & Logistics Intelligence
Hospital procurement committees in the United States anchor pricing power for enterprise-grade scheduling platforms, forcing vendors toward subscription models with embedded compliance premiums. This buyer concentration elevates HIPAA certification and EHR integration depth as the primary pricing levers.
Pricing Analysis
Value-based pricing anchors on patient throughput optimization and no-show rate reduction metrics that hospital networks track. Three-tier pricing structure across premium, standard, and economy levels separates full API-first suites from template-driven mid-market tools and freemium self-service tiers. Cost compression in the mid-market tier is intensifying because hybrid deployment options reduce switching costs. Solo practitioners and small professional services firms exhibit the highest price sensitivity, while large health systems prioritize integration depth over license cost.
Supply Chain Analysis
Dual-sourcing requirements from enterprise buyers mandate multi-cloud qualification across AWS, Microsoft Azure, and Google Cloud to mitigate regional outage exposure. Software development labor concentrates in the United States, India, and Germany, with technical talent scarcity in HL7 FHIR implementation extending integration timelines. The supply chain draws from open-source frameworks, proprietary API middleware, and hyperscaler compute infrastructure. Single-source vulnerability in cloud infrastructure creates concentration risk. Distribution runs through direct enterprise sales, channel partners, and self-service digital marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
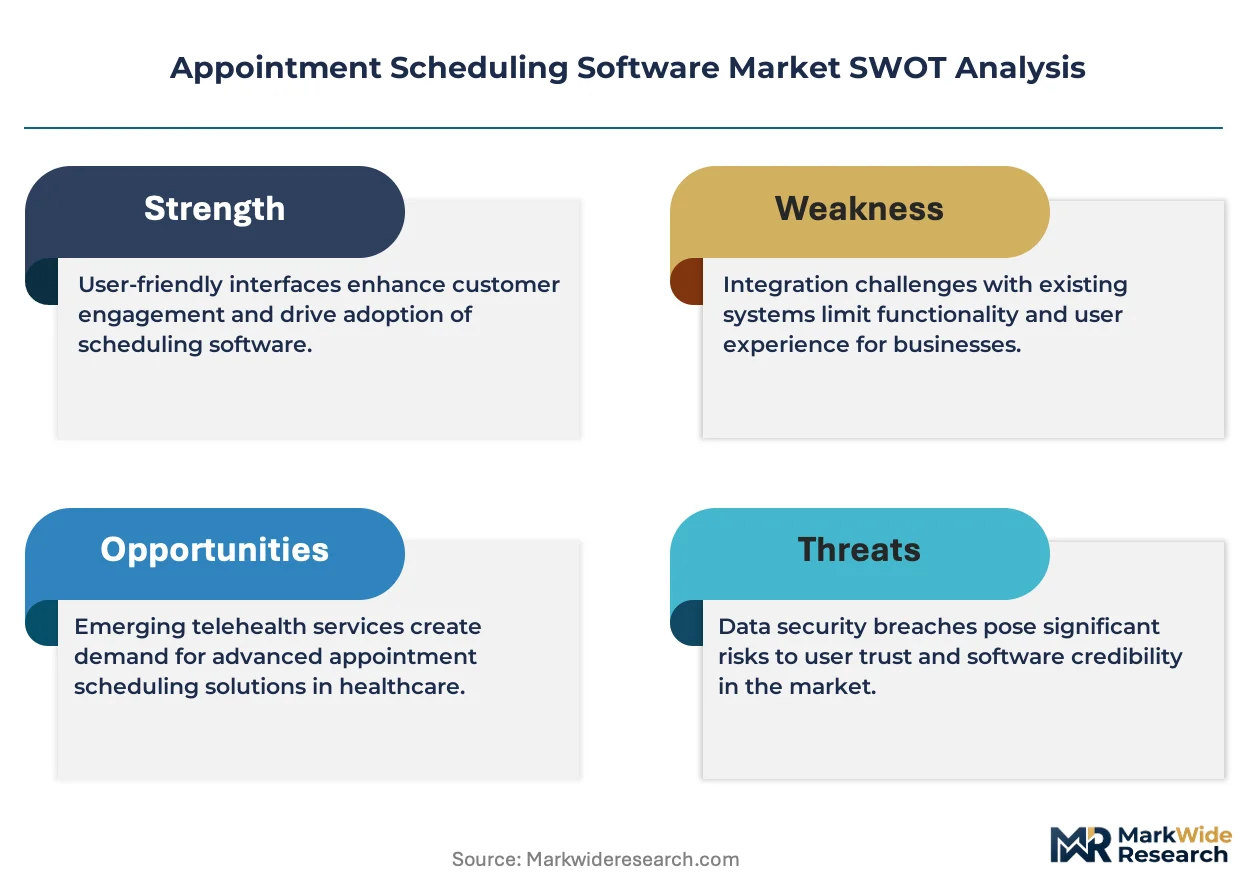
This market reads as a cost-of-compliance story where HIPAA Omnibus Rule enforcement and FDA SaMD classification ambiguity create barrier-to-entry moats for certified incumbents.
For Market Incumbents: Hedge against margin compression by deepening API infrastructure moats and accelerating ISO 27001 certification pipelines before audit queue congestion worsens. Threats from lightweight self-service tools with rapid no-code deployment demand defensive capability investments in hybrid architecture support. For New Entrants and Emerging Players: Capture the behavioral health vertical where specialized workflow templates for recurring therapy sessions remain underserved by incumbent platforms. White-space exists in EU AI Act early certification for European hospital procurement. A compliance-first go-to-market angle differentiates against commodity calendar tools. For Investors and Strategic Acquirers: The window for entry favors vendors with current ISO 27001 certification and established HL7 FHIR integration capabilities. Long-term viability hinges on API-first architectural positioning as health systems consolidate around composable microservices. Watch FDA SaMD classification clarity as the inflection signal for procurement freeze resolution.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables bidirectional EHR synchronization required by 21st Century Cures Act mandates. |
| Compliance Certification Acceleration | ISO 27001 and HIPAA Business Associate Agreements unlock enterprise procurement filters. |
| Vertical Workflow Specialization | Behavioral health templates capture underserved therapy and psychiatry practice demand. |
| Hybrid Deployment Architecture | Local PHI processing satisfies German data protection authorities and mid-market dental chains. |
| Strategic Partnership with EHR Vendors | Native integration with Epic and Cerner systems secures health system procurement preference. |
Research Approach
Independent corroboration across hospital IT procurement officers, health system CIOs, and EHR integration specialists underwrites the qualitative findings in this study. Primary interviews with HIPAA compliance officers, software platform engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up vendor revenue triangulation against top-down health IT spending estimates anchors the market sizing.
Rate-of-change decomposition separates volume growth from pricing evolution across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user vertical, integration complexity tier, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to validated baseline estimates. Industry-specific forecast inputs encompass HL7 FHIR adoption timelines and HIPAA enforcement penalty data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA SaMD classification rulings and EU AI Act implementation pacing. Forecasts reflect documented assumptions about interoperability mandate deadlines and cloud infrastructure cost trajectories. Deviation in HIPAA penalty enforcement intensity or biometric privacy law fragmentation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Java Web Frameworks Software Market
Software & Services
Metal Recycling Software Market
Software & Services
Stock Media Software Market
Software & Services
Europe Yacht Management Software Market
Software & Services
Software License Management (SLM) Market
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Global Project Software Market
Software & Services
Global Employee Engagement Software Market
Software & Services
Virtual Studio Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Collaborative Office Software Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Global Award Management Software Market
Software & Services
Customer Self-Service Software Market