
 Dealer Management System Market | 2026-2036
Dealer Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Dealer Management System Market Intelligence
The shift to subscription-based pricing models that lower upfront capital expenditure for dealerships is fragmenting the competitive landscape. This allows smaller, specialized vendors to challenge established incumbents. CDK Global leverages its extensive dealership network and comprehensive feature set to maintain market share. In contrast, Reynolds & Reynolds differentiates through its deeply integrated hardware and software solutions, while DealerSocket specializes in CRM-centric platforms for automotive retail.
A Dealer Management System is an integrated software platform centralizing a dealership's operational data streams. These systems unify disparate modules, such as sales, service, parts, and accounting, into a single database for streamlined workflows. Cloud-based software deployment now dominates the market, displacing traditional on-premises installations due to lower maintenance and greater accessibility. While vehicle retailers constitute the largest end-user base, core functionalities like customer relationship management and inventory management are critical across all dealer types.
Data governance regulations fundamentally shape DMS development, with frameworks like Europe's GDPR and consumer privacy rules enforced by the US FTC dictating strict requirements for customer data handling. These rules mandate secure storage and transparent consent management within CRM modules. Consequently, dealers must decide whether to commit to a single vendor's all-encompassing suite or navigate the complexities of integrating specialized, best-of-breed applications from multiple providers.
Market Dynamics
The central structural force shaping the Dealer Management System market is the transition to cloud-based, subscription models. This shift democratizes access to advanced software for smaller dealerships and intensifies competition among vendors on features and integration capabilities.
Growth Catalysts
- EV Retail Specialization:The expansion of electric vehicle sales requires new DMS modules for battery health monitoring, charging management, and unique financing models, creating demand for specialized software among EV-focused retailers.
- Data Governance Mandates:Regulations like Europe's GDPR compel dealerships to adopt modern DMS platforms with sophisticated CRM modules that ensure compliant customer data handling, consent management, and secure storage.
- AI and Analytics Integration:The incorporation of artificial intelligence into DMS platforms for predictive inventory ordering, service scheduling, and personalized marketing campaigns drives adoption among dealers seeking operational efficiency and higher customer retention.
Market Restraints
- High Total Cost of Ownership:Despite lower upfront costs from subscription models, long-term contracts, data migration fees, and mandatory training create a high total cost of ownership that can deter smaller, independent dealerships.
- Data Portability and Vendor Lock-In:Proprietary data formats and complex contract structures make it technically difficult and costly for dealerships to switch DMS providers, limiting competitive pressure and flexibility.
- Third-Party Integration Friction:Many core DMS platforms offer limited or costly APIs, creating significant friction for dealerships attempting to integrate specialized best-of-breed applications for digital retailing or service management.
Strategic Opportunities
- Expansion into Adjacency Markets:Vendors can adapt core DMS functionalities for underpenetrated sectors like marine, powersports, and agricultural equipment dealerships, which currently rely on less sophisticated or generic business software.
- Open API Ecosystems:Developing platforms with open APIs and certified third-party application marketplaces presents an opportunity to become the central hub for a dealership's entire technology stack, increasing stickiness.
- DMS for Emerging Auto Markets:Dealership networks in developing automotive markets, particularly in Southeast Asia and Latin America, are modernizing and represent a significant greenfield opportunity for cloud-based DMS implementation.
Industry Challenges
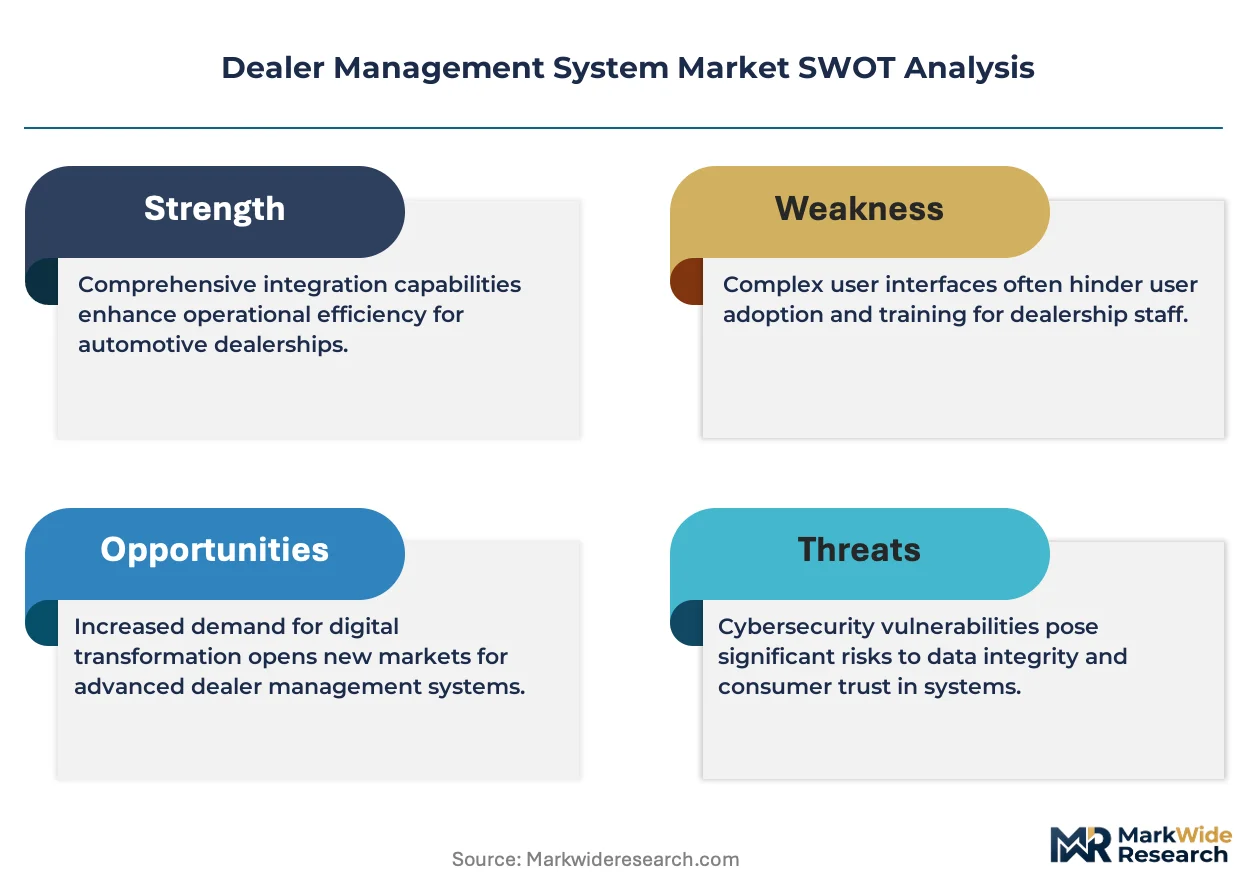
- Cybersecurity Vulnerabilities:Centralizing vast amounts of sensitive customer financial and personal data makes DMS platforms a high-value target for cyberattacks, demanding constant investment in advanced security measures and incident response plans.
- Legacy System Migration Risk:The process of migrating decades of data from on-premises legacy systems to new cloud platforms is complex, carrying significant operational risks of data corruption, loss, and business disruption.
- Dealership IT Skills Gap:A shortage of qualified IT personnel within dealerships who can effectively manage, customize, and secure increasingly complex DMS software limits the ability to maximize the return on software investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dealer Management System Market |
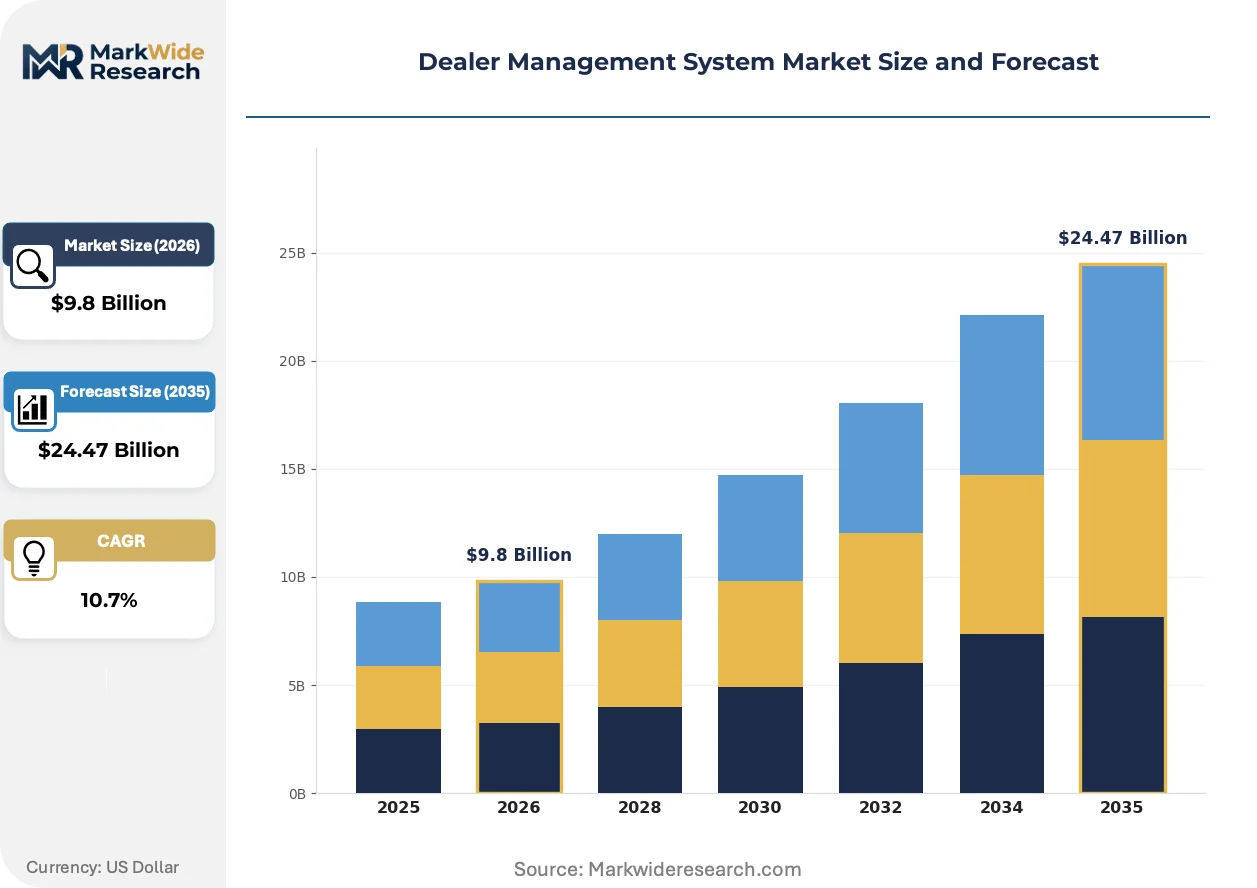
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $24.47 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Deployment: Cloud-Based, On-Premises, Hybrid, Web-Based Core Functionality: Inventory Management, Sales Tracking, Customer Relationship Management, Financial Reporting, Service Scheduling End User Type: Vehicle Retailers, Equipment Distributors, Machinery Dealers, Parts Suppliers, Heavy Vehicle Vendors Pricing Model: Subscription-Based, Perpetual License, Pay-As-You-Go, Freemium |
| Companies Covered | DealerSocket, Reynolds & Reynolds, CDK Global, EverLogic DMS, Dominion Dealer Solutions, DealerCenter, VinSolutions, Blackpurl, Autosoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dealer Management System Market Strategic Shifts & Innovations
The platformization of dealership operations defines the market's trajectory. Systems are evolving from monolithic record-keeping tools into interconnected hubs that orchestrate digital retail, service operations, and customer lifecycle management through open, extensible architectures.
Embedded artificial intelligence is a key product evolution. AI-powered analytics engines automate tasks like inventory forecasting based on regional sales data and customer segmentation for targeted marketing campaigns. Large, multi-franchise dealership groups are the primary adopters, seeking to standardize efficient processes across locations. This integration of artificial intelligence is digitizing core operational workflows, moving them from manual processes to automated, data-driven decisions.
Heightened regulatory scrutiny over data security is a primary innovation driver. Rules like the FTC's Safeguards Rule in the United States compel DMS providers to engineer and certify robust security protocols, including end-to-end encryption, multi-factor authentication, and detailed access logging. Finance & Insurance (F&I) and CRM modules are the most affected, requiring vendors to deliver auditable compliance features to protect dealerships from liability.
A preference for modular, best-of-breed software integration is altering procurement patterns. Dealerships are moving away from reliance on a single vendor's all-in-one suite, instead demanding DMS platforms with open APIs that can connect to specialized third-party tools. This trend is most visible in North America and Germany, where dealers seek to integrate advanced digital retailing platforms or standalone service-lane productivity applications.
Dealer Management System Market Segmentation
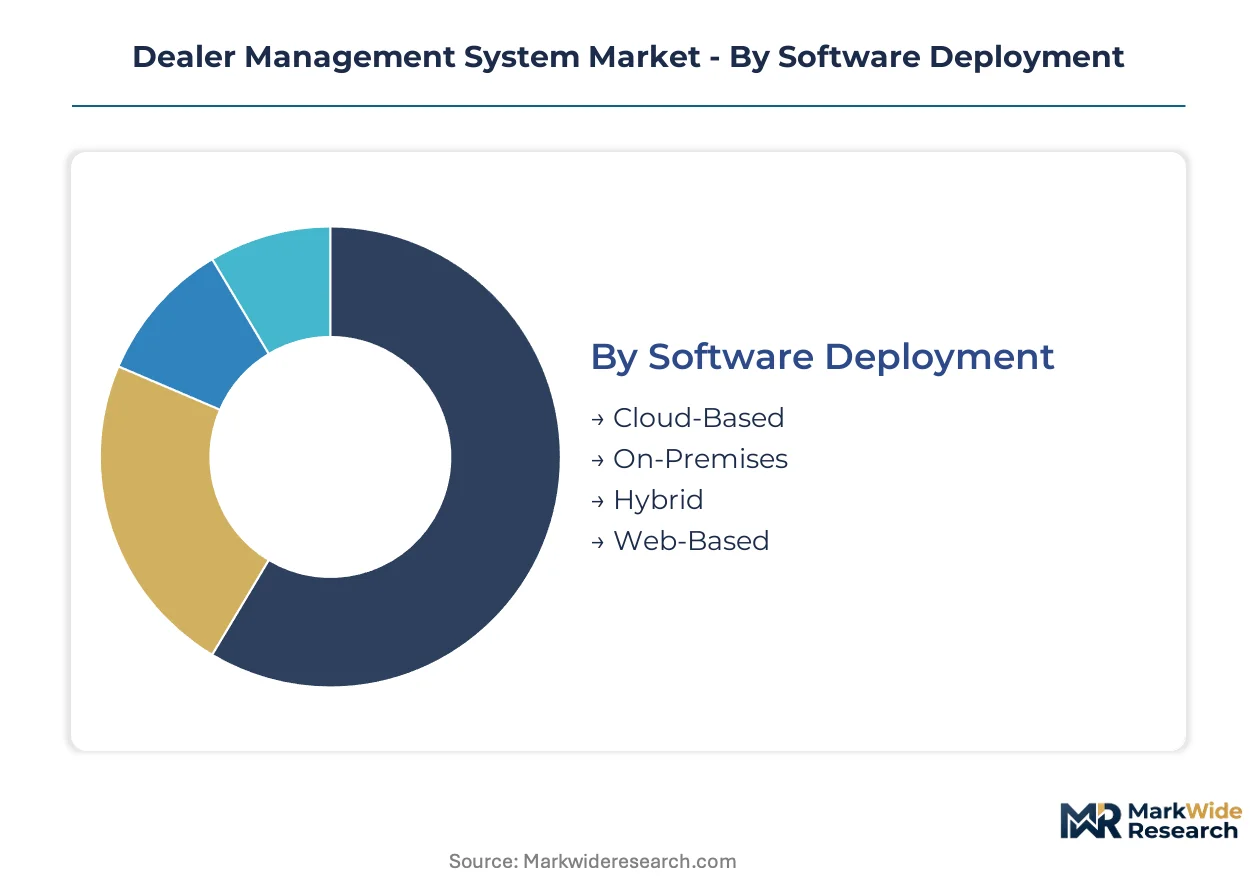
The Dealer Management System market's structure reflects diverse operational needs and technological preferences across automotive retail. Segmentation provides crucial insights into how vendors address varying dealership sizes, functional requirements, and deployment strategies. Understanding these distinct segments helps identify key growth vectors and competitive battlegrounds within the industry.
Software Deployment:
The lifecycle of DMS deployment models varies significantly, with some offering rapid implementation while others demand extensive integration periods.
- Cloud-Based:These platforms are hosted remotely by the vendor and accessed via the internet, reducing local IT infrastructure needs for dealerships. Demand concentrates in regions like Germany, driven by lower maintenance costs and enhanced accessibility.
- On-Premises:This traditional model involves software installed and run directly on a dealership's local servers and hardware, requiring significant upfront capital expenditure. Adoption persists among large dealership groups with existing IT departments and specific data sovereignty requirements.
- Hybrid:This model combines on-premises and cloud deployments, enabling dealerships to host sensitive data locally while utilizing cloud services for other operations.
- Web-Based:These applications are primarily accessed through a web browser, often reflecting a cloud-based architecture or browser-enabled on-premises systems.
On-Premises solutions anchor the legacy volume base while Cloud-Based deployment models gain share at the steepest rate.
Core Functionality:
The application of DMS functionalities directly impacts a dealership's operational efficiency and compliance posture.
- Customer Relationship Management:This module centralizes customer data, managing interactions, sales leads, and service history to enhance personalized engagement. Regulatory mandates like Europe's GDPR and US FTC rules compel dealerships to adopt advanced CRM features for compliant data handling.
- Inventory Management:This core function tracks vehicle stock, parts inventory, and accessories, optimizing ordering, pricing, and allocation across dealership locations. Large multi-franchise groups leverage AI-powered forecasting to minimize holding costs and maximize sales opportunities.
- Sales Tracking:This functionality monitors the entire sales pipeline, from initial inquiry to final vehicle delivery, providing insights into sales performance and conversion rates.
- Financial Reporting:These modules manage general ledger, accounts payable/receivable, and payroll, ensuring accurate financial statements and accounting compliance.
- Service Scheduling:This feature streamlines workshop operations, managing appointment bookings, technician availability, and service bay allocation for efficient customer service.
Customer Relationship Management is pivotal for regulatory compliance, while Inventory Management drives core operational efficiency.
End User Type:
DMS solutions are tailored to distinct customer types, each presenting unique operational challenges and software requirements.
- Vehicle Retailers:This segment comprises traditional automotive dealerships selling new and used vehicles, representing the largest end-user base for comprehensive DMS platforms. They require integrated solutions for sales, service, parts, and finance operations.
- Heavy Vehicle Vendors:These dealers specialize in selling commercial trucks, construction equipment, and agricultural machinery, often needing specialized modules for fleet management and heavy-duty parts. Demand expands in emerging markets for infrastructure development.
- Equipment Distributors:This category includes businesses distributing industrial, material handling, or power generation equipment, requiring DMS features for complex inventory tracking.
- Machinery Dealers:These entities sell specialized machinery for various industries, often demanding robust CRM and service modules for long-term customer relationships.
- Parts Suppliers:Businesses primarily focused on selling automotive or equipment parts utilize DMS to manage extensive catalogs and warehousing.
Vehicle Retailers represent the foundational demand, with Heavy Vehicle Vendors exhibiting significant expansion potential.
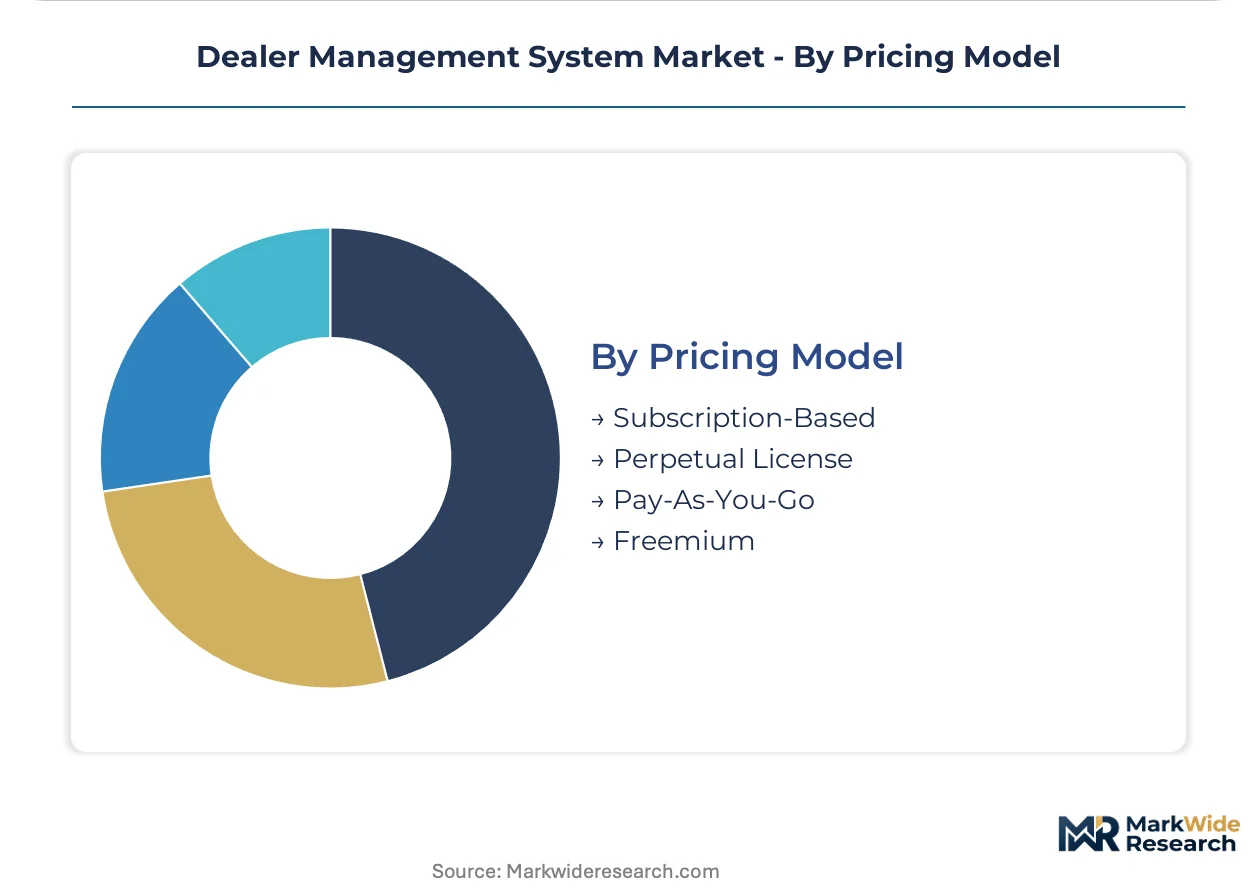
Pricing Model:
Different pricing models offer varying cost structures, influencing upfront investment and long-term expenditure for dealerships.
- Subscription-Based:Dealerships pay recurring fees, typically monthly or annually, for software access, updates, and support, reducing initial capital outlay. This model is preferred by smaller dealerships seeking predictable operational expenses and scalability.
- Perpetual License:This traditional model involves a one-time upfront purchase fee for the software license, granting indefinite usage rights, often with separate costs for maintenance and upgrades. Legacy dealerships with existing on-premises infrastructure frequently utilize this model.
- Pay-As-You-Go:This flexible model charges dealerships based on actual usage, such as transaction volume or users, offering scalability and cost control.
- Freemium:This model offers a basic DMS version for free, with advanced features or increased capacity available through paid subscriptions.
Subscription-Based models dominate new procurements, while Perpetual License models retain a substantial installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data governance regulations, such as Europe's GDPR and consumer privacy rules enforced by the US FTC, fundamentally shape Dealer Management System development. These mandates compel dealerships to adopt modern DMS platforms with sophisticated CRM modules. This regulatory landscape drives demand for advanced software capabilities across mature automotive markets.
Germany
Germany's stringent data privacy regulations, particularly GDPR, drive significant demand for compliant DMS platforms. Dealerships prioritize cloud-based solutions to manage customer data securely and efficiently. The automotive manufacturing cluster in Bavaria actively integrates advanced DMS for streamlined operations and sales tracking.
United States
US vehicle retailers require robust DMS solutions to meet consumer privacy rules enforced by the FTC. The shift to subscription-based models lowers upfront costs for dealerships, encouraging broader adoption. Silicon Valley's tech hubs contribute to innovation, fostering advanced AI and analytics integration within DMS platforms.
China
China's rapidly expanding electric vehicle market necessitates specialized DMS modules for battery management and unique financing structures. Government initiatives supporting EV adoption create opportunities for cloud-based DMS implementation. Major automotive cities like Shanghai and Guangzhou are seeing increased demand for integrated dealership solutions.
India
India's modernizing dealership networks present a significant greenfield opportunity for cloud-based DMS implementation. The country's growing automotive sector demands efficient inventory management and sales tracking functionalities. Major metropolitan areas such as Delhi-NCR and Mumbai drive adoption for streamlined dealership operations.
Brazil
Brazil's large automotive market and increasing digitalization efforts fuel demand for advanced DMS platforms. Local regulations governing data protection and consumer rights influence CRM module development. The industrial hub around São Paulo experiences significant adoption among vehicle retailers seeking operational efficiencies.
Dealer Management System Market Key Industry Players
On the supply side, the industry is fragmenting, characterized by a dynamic interplay between established incumbents and agile, specialized vendors. The competitive landscape features comprehensive suite providers, CRM-centric specialists, and hardware-integrated solution providers, each targeting distinct dealership needs. Dominant competitive moves include strategic partnerships to expand integration capabilities and targeted acquisitions of niche technology firms, aiming to enhance product portfolios and market reach. Vendors also focus on developing open API ecosystems to foster broader third-party integration.
Established market leaders, such as CDK Global, leverage their extensive dealership networks and comprehensive feature sets to maintain significant market share. These platforms offer end-to-end solutions, from sales to service and accounting, catering to large multi-franchise groups. Reynolds & Reynolds differentiates through its deeply integrated hardware and software solutions, providing a unified operational environment for dealerships. DealerSocket exemplifies a CRM-centric platform provider, specializing in customer relationship management and lead nurturing tools tailored specifically for automotive retail. These diverse approaches reflect the varied operational priorities and technological preferences across the dealership ecosystem.
| Leading Market Players |
|---|
| DealerSocket |
| Reynolds & Reynolds |
| CDK Global |
| EverLogic DMS |
| Dominion Dealer Solutions |
| DealerCenter |
| VinSolutions |
| Blackpurl |
| Autosoft |
| Others |
Cost & Logistics Intelligence
Vendor capacity to deliver cloud-based DMS solutions across diverse geographies influences both market entry strategies and subscription pricing models. This dynamic shapes how new functionalities are introduced and adopted, particularly in regions with varying technological maturity.
Pricing Analysis
Feature set breadth and depth creates the primary spread in Dealer Management System pricing. Subscription-based models dominate new procurements, offering predictable operational expenses to dealerships. Price differentiation stems from customization levels, the inclusion of advanced AI capabilities, and robust compliance features like GDPR modules. Pricing pressure intensifies due to the fragmentation of the competitive landscape, with specialized vendors offering targeted solutions. Smaller, independent dealerships exhibit higher price sensitivity, while large multi-franchise groups prioritize comprehensive, integrated solutions.
Supply Chain Analysis
Data sovereignty regulations, such as Europe's GDPR, limit cross-border data flows and shape DMS cloud infrastructure deployment. Supply for DMS software development concentrates in the United States, Germany, and India, reflecting tech expertise and automotive market focus. Core dependencies include cloud computing services, skilled software engineers, and robust cybersecurity expertise. Vendor lock-in, driven by proprietary data formats and complex migration processes, represents a significant supply chain risk. Distribution primarily occurs through direct sales channels and cloud marketplace partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dealer Management System market represents a substitution defense against fragmented, generic business software solutions. Incumbents must integrate advanced functionalities to prevent dealerships from adopting best-of-breed niche applications.
For Market Incumbents:Harden core DMS platforms by developing open API ecosystems that integrate specialized third-party applications. Acquire niche technology firms specializing in AI analytics or specific compliance modules to expand product portfolios. This approach mitigates the threat from agile, specialized vendors offering best-of-breed solutions. Investing in advanced compliance features like GDPR certification is also critical to maintain market leadership.
For New Entrants and Emerging Players:Build out cloud-native DMS platforms specifically tailored for underpenetrated adjacency markets like marine or powersports dealerships. Targeting emerging automotive markets in Southeast Asia with subscription-based models offers significant greenfield opportunities. Smaller, independent dealerships in these regions are highly receptive to lower upfront cost solutions. Focus on rapid deployment and essential CRM/inventory modules for initial market penetration.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among cloud-based DMS providers with strong subscription models, offering long-term revenue visibility. Acquisition targets should include specialized firms excelling in AI-driven analytics or robust data compliance features for CRM modules. The signal to watch is the increasing enforcement of data privacy regulations, which drives demand for advanced, compliant platforms. Providers with comprehensive integration capabilities also present attractive profiles.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Open API Ecosystems | Increases platform stickiness by integrating diverse third-party applications for vehicle retailers. |
| Acquire Niche AI/Analytics Firms | Enhances predictive capabilities for inventory ordering and personalized marketing campaigns for dealerships. |
| Expand into Adjacency Markets | Adapts core DMS functionalities for sectors like marine and powersports, diversifying revenue streams. |
| Invest in Enhanced Data Compliance | Ensures adherence to regulations like Europe's GDPR, protecting dealerships from significant liability. |
| Offer Flexible Subscription Models | Lowers upfront costs, enabling broader adoption among smaller, independent dealerships. |
Research Approach
A standing panel of dealership owners, IT managers, and DMS vendor product leads provided ongoing calibration for market insights. Primary interviews with these stakeholders were triangulated with extensive secondary research for validation. Sources included automotive industry association reports, technology market analyses, and regulatory documents from the FTC and EU. This approach ensured robust bottom-up and top-down data synthesis.
Scenario-bracketing techniques informed the quantitative forecast model across the analysis window, accounting for varying market conditions. Segmentation dimensions included software deployment, core functionality, end-user type, and pricing model, alongside regional adoption patterns. Compound annual growth rates were derived from historical data analysis and projected technological advancements. Key inputs included global vehicle sales forecasts and anticipated regulatory enforcement trends.
Practitioners should monitor rapid shifts in AI integration or new data privacy legislation for early signals of market disruption. Forecasts reflect current market assumptions and technological trajectories. Material shifts in regulatory frameworks or competitive landscape dynamics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Data Mining Software Market
Software & Services
Vlog Editing Software Market
Software & Services
Sales Compensation Software Market
Software & Services
Live Software Market
Software & Services
Subscription Management Software Market
Software & Services
Global Digital Signage Software Market
Software & Services
Global Human Capital Management Software Market
Software & Services
Global Time Tracking Software Market
Software & Services
Construction Simulation Software Market
Software & Services
Global ITSM Software Market
Software & Services
Category Management Software Market
Software & Services
Shift Planning Software Market
Software & Services
Global Catalog Management Software Market
Software & Services
Casino Management Systems Market
Software & Services
On-Demand Wellness Software Market
Software & Services
Federal Government Software Market