
 Global Email Software Market | 2026-2036
Global Email Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Email Software Market Foresight
North American cloud infrastructure is hardening around enterprise-grade email orchestration, with hyperscaler data centers in Virginia and Oregon expanding dedicated capacity for high-volume transactional processing. Microsoft Corporation leverages its Azure backbone to anchor government and healthcare contracts through FedRAMP-authorized environments. Salesforce, Inc. competes by extending its Customer 360 platform into real-time journey orchestration, while HubSpot, Inc. specializes in mid-market inbound marketing workflows that reduce dependency on fragmented point solutions.
Email software encompasses message routing engines, template rendering systems, deliverability optimization layers, and API gateways that process billions of SMTP transactions daily at throughput rates exceeding ten thousand messages per second. Cloud-based deployment leads solution type adoption as organizations abandon on-premises Exchange architectures for elastic, API-first infrastructure that scales with subscriber list growth. Marketing automation commands the fastest expansion within solution types, driven by AI-powered send-time optimization and predictive content personalization that lifts engagement metrics. Security and compliance represents the highest-margin pool, where encryption-at-rest, TLS enforcement, and audit logging justify premium pricing against tightening data protection enforcement.
The EU AI Act and GDPR impose algorithmic transparency requirements on automated email content generation, compelling vendors to document decision logic for regulatory inspection. The SEC in the United States mandates retention and archival standards for financial services email communications, while India's Digital Personal Data Protection Act establishes consent frameworks that restrict cold outreach velocity. Stakeholders must monitor divergence between regional compliance architectures to determine whether unified product stacks or geography-specific instances deliver sustainable operational economics.
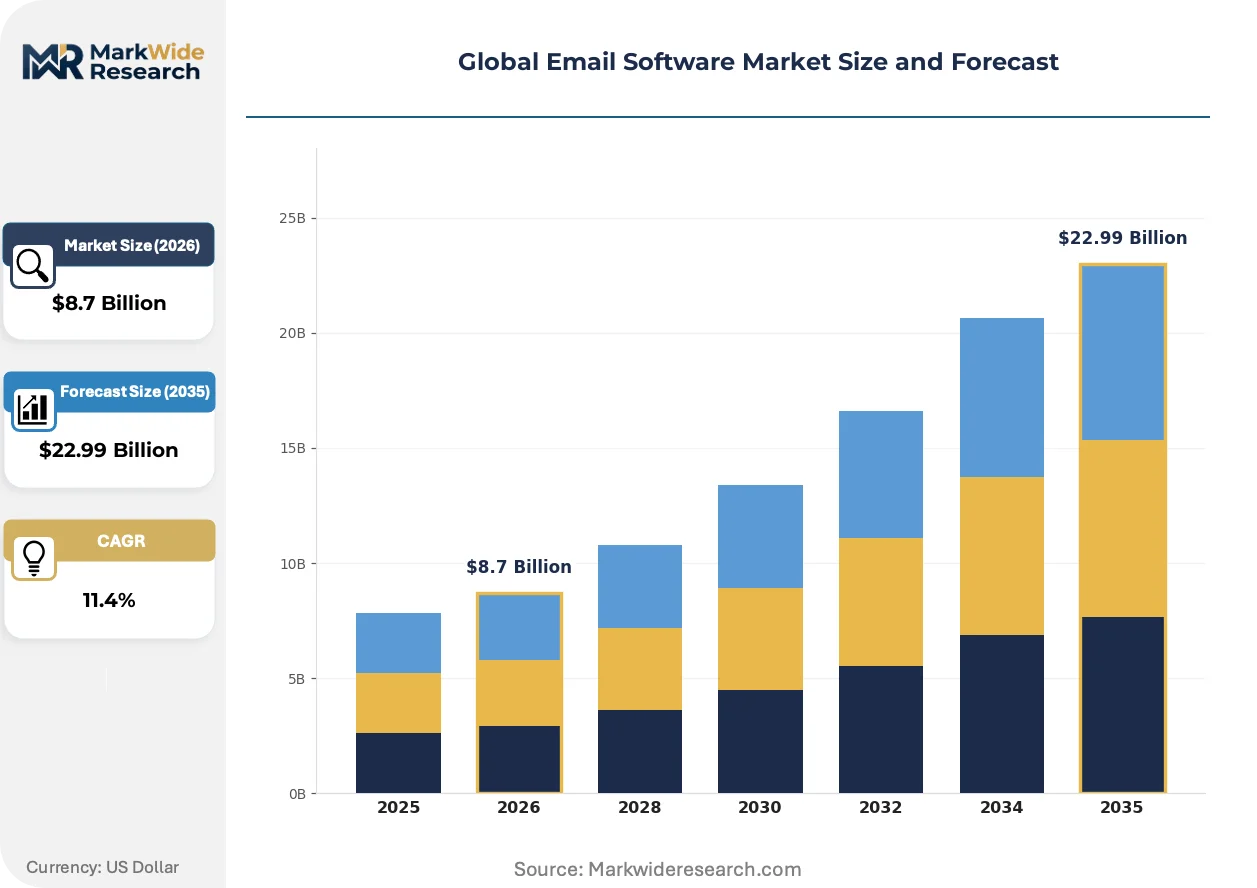
Market Dynamics
Enterprise migration from on-premises Exchange architectures to API-first cloud infrastructure is compressing deployment timelines and rewiring vendor procurement criteria around elastic throughput guarantees.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated content generation systems now require documented decision logic, creating upgrade cycles for compliance-ready platforms across German and French enterprise accounts.
- Retail and e-commerce marketing automation:AI-powered send-time optimization and predictive personalization are lifting engagement metrics, driving platform consolidation among mid-market operators.
- FedRAMP-authorized cloud environments:United States government and healthcare contracts now mandate authorized infrastructure, channeling procurement toward hyperscaler-backed solutions with dedicated Virginia and Oregon data center capacity.
Market Restraints
- Data sovereignty compliance costs:India's Digital Personal Data Protection Act and Germany's evolving localization rules force geography-specific instance deployment, fragmenting operational economics.
- SMTP infrastructure concentration:High-volume transactional processing depends on limited hyperscaler backbone capacity in key regions, creating throughput bottlenecks during peak campaign windows.
- TLS encryption standard fragmentation:Divergent national requirements for transport-layer security enforcement complicate unified product architecture and extend certification timelines.
Strategic Opportunities
- Mid-market inbound marketing workflows:HubSpot's segment specialization demonstrates whitespace for integrated platforms that reduce point-solution fragmentation without enterprise complexity.
- Real-time journey orchestration convergence:Customer 360 platform extensions into email represent a technology convergence opportunity between CRM data layers and message routing engines.
- Security and compliance premium tier:Encryption-at-rest, audit logging, and retention mandates under SEC financial services rules justify pricing differentiation against tightening enforcement.
Industry Challenges
- Deliverability engineering talent scarcity:Specialized expertise in inbox placement optimization, sender reputation management, and ISP relationship negotiation commands premium compensation and constrains platform scaling.
- Legacy on-premises integration friction:Hybrid architectures spanning abandoned Exchange servers and cloud-native APIs create message routing failures and compliance audit gaps during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Email Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted, Managed Services Solution Type: Transactional Email, Marketing Automation, Collaborative Platforms, Security & Compliance, Customer Support End User: SMBs, Large Enterprises, Educational Institutions, Government Agencies, Non-Profit Organizations Distribution Channel: Direct Sales, Online Marketplaces, Value-Added Resellers, System Integrators, Managed Service Providers |
| Companies Covered | Microsoft Corporation, Google LLC, Apple Inc., Salesforce, Inc., Oracle Corporation, HubSpot, Inc., Mailchimp, Klaviyo, Zoho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Email Software Market Shifts & Advancements
Generative AI is embedding into template rendering and content optimization layers, while regulatory pressure on algorithmic decision-making forces architectural transparency that vendors must engineer from infrastructure up.
Machine learning-powered predictive send-time optimization is expanding into high-frequency transactional messaging beyond traditional marketing campaigns. E-commerce operators with subscriber lists exceeding ten million addresses now deploy these systems for order confirmations and shipping notifications. The technology is expanding into real-time behavioral triggers that compress the latency between user action and message delivery from minutes to milliseconds.
GDPR and the EU AI Act now impose documented explainability requirements on automated subject line generation and content personalization algorithms. Vendors must maintain inspectable decision logs for regulatory examination. European enterprise procurement teams now weight algorithmic transparency as heavily as deliverability metrics in platform selection.
Buyer concentration among Fortune 500 technology stacks is consolidating procurement around integrated customer communication platforms. Mid-market operators previously dependent on fragmented point solutions now demand unified API gateways that collapse message routing, template management, and analytics into single-vendor relationships. This pattern is most visible in United States retail and financial services verticals where procurement teams prioritize vendor reduction over best-of-breed feature depth.
Global Email Software Market Segmentation
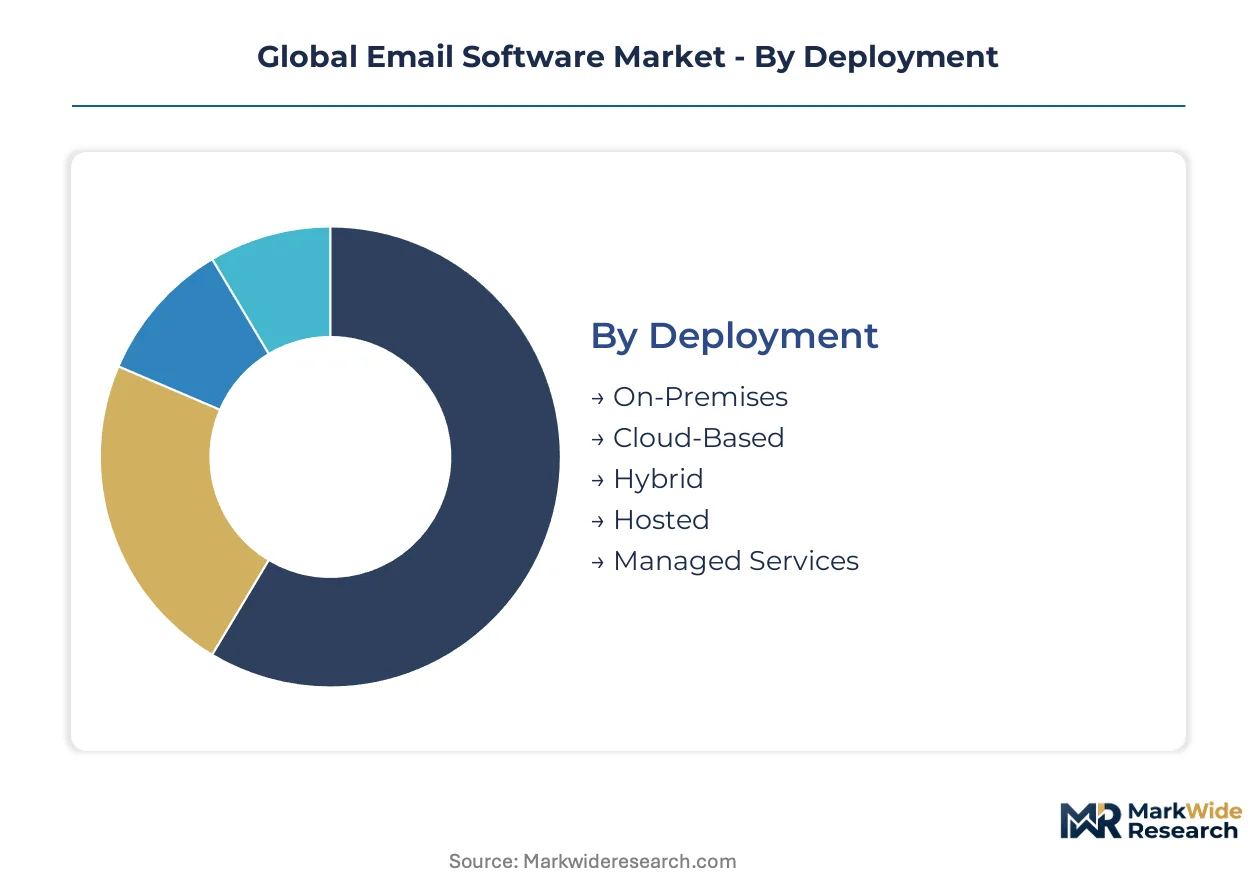
Email software procurement patterns diverge sharply between high-volume transactional operators and premium compliance-driven buyers, forcing vendors to architect separate pricing and feature tiers. Understanding deployment preferences, solution specialization, and channel economics reveals where margin pools concentrate and which segments drive technology roadmaps.
Deployment:
Cloud-based infrastructure commands volume leadership while hybrid architectures capture premium pricing from regulated verticals.
- On-Premises:Legacy Exchange architectures persist in defense contractors and classified government facilities where air-gapped networks are mandatory. German automotive suppliers and Indian public sector banks maintain these deployments to satisfy data localization audits, though maintenance costs accelerate replacement timelines.
- Cloud-Based:Elastic API-first infrastructure scales subscriber lists without capital expenditure, dominating United States retail and e-commerce adoption. Virginia and Oregon hyperscaler regions now dedicate capacity blocks for high-throughput transactional processing exceeding ten thousand messages per second.
- Hybrid:Split architectures route sensitive communications through on-premises gateways while marketing flows traverse public cloud, commanding 40-60% price premiums over pure cloud.
- Hosted:Single-tenant managed deployments serve mid-market operators seeking customization without operational overhead.
- Managed Services:Fully outsourced email operations including deliverability engineering and reputation management attract talent-constrained organizations.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Solution Type:
Marketing automation platforms expand fastest as AI-powered personalization penetrates mid-market budgets, while security modules defend margin in financial services.
- Transactional Email:High-reliability routing engines process order confirmations and password resets with sub-second latency guarantees. E-commerce operators with ten-million-plus subscriber lists now deploy predictive send-time optimization for these operational messages, not just campaigns.
- Marketing Automation:Journey orchestration platforms integrate CRM data layers with behavioral triggers, compressing message delivery latency from minutes to milliseconds. Retail consolidation around unified customer communication stacks is displacing fragmented point solutions.
- Collaborative Platforms:Shared inbox and internal notification systems serve distributed workforces with threaded conversation management.
- Security & Compliance:Encryption-at-rest, TLS enforcement, and audit logging modules justify premium pricing against SEC retention mandates and EU AI Act documentation requirements.
- Customer Support:Ticket-to-email threading and automated response routing reduce agent handling time for SaaS vendors and telecommunications operators.
Marketing Automation is climbing the fastest; Security & Compliance holds the deepest margin pool.
End User:
Large enterprises consolidate procurement around integrated stacks while SMBs prioritize vendor reduction over feature depth.
- SMBs:Inbound marketing workflows from unified platforms reduce dependency on fragmented tools, with mid-market United States operators leading consolidation.
- Large Enterprises:Fortune 500 technology budgets prioritize API gateways collapsing routing, templates, and analytics into single-vendor relationships, channeling procurement toward hyperscaler-backed solutions.
- Educational Institutions:Campus-wide communication systems manage student onboarding and alumni engagement with volume-based pricing.
- Government Agencies:FedRAMP-authorized environments in Virginia data centers anchor United States federal and healthcare contracts.
- Non-Profit Organizations:Discounted pricing tiers and donor management integrations serve fundraising and volunteer coordination.
Large Enterprises dominate current revenue; SMBs represent the steepest expansion trajectory as platform consolidation accelerates.
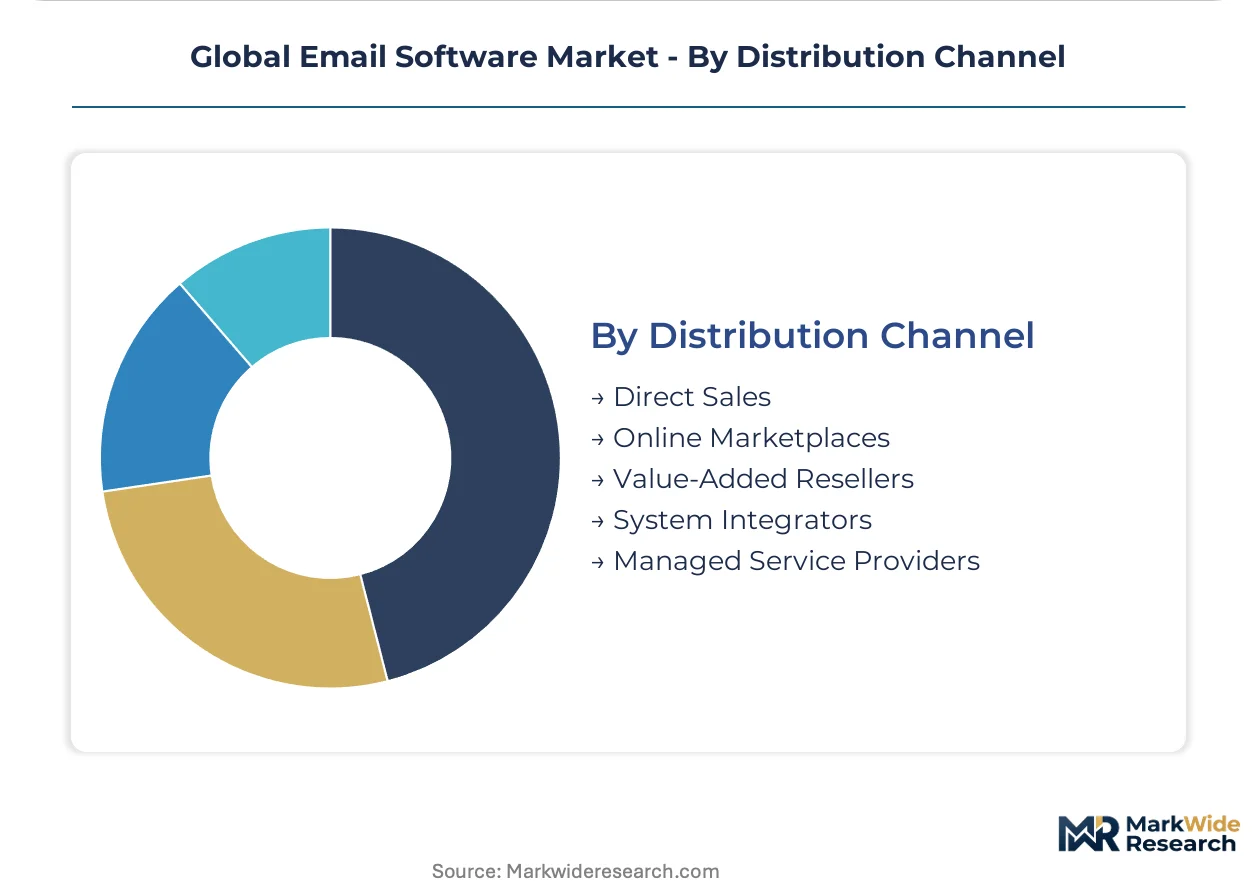
Distribution Channel:
Direct relationships dominate enterprise procurement while system integrators capture complex hybrid deployment projects.
- Direct Sales:Field teams secure multi-year enterprise contracts with elastic throughput guarantees and dedicated customer success resources.
- Online Marketplaces:Self-service provisioning attracts developers and small teams seeking immediate API access without procurement cycles.
- Value-Added Resellers:Regional specialists bundle email platforms with complementary marketing technology stacks.
- System Integrators:Accenture and Deloitte practices architect hybrid cloud migrations, commanding implementation fees exceeding license costs.
- Managed Service Providers:Outsourced operations including deliverability monitoring and reputation repair serve organizations lacking specialized talent.
Direct Sales captures the largest deal size; System Integrators are gaining share fastest on hybrid migration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between the EU AI Act's algorithmic transparency mandates and the United States' FedRAMP authorization pathways is creating compliance-cost arbitrage that shapes vendor deployment strategies across major economies.
United States
Fortune 500 technology budgets prioritize integrated customer communication stacks that collapse routing, templates, and analytics into single-vendor relationships. SEC retention and archival standards for financial services email communications drive demand for encryption-at-rest and audit logging modules. Virginia and Oregon hyperscaler data centers now dedicate capacity blocks for high-throughput transactional processing exceeding ten thousand messages per second.
Germany
Automotive suppliers and industrial manufacturers maintain hybrid architectures to satisfy data localization audits under evolving sovereignty rules. The EU AI Act imposes documented explainability requirements on automated subject line generation and content personalization algorithms. Munich and Frankfurt clusters anchor enterprise procurement teams that now weight algorithmic transparency as heavily as deliverability metrics in platform selection.
India
Mid-market retail and e-commerce operators accelerate cloud migration as subscriber list growth demands elastic, API-first infrastructure. The Digital Personal Data Protection Act establishes consent frameworks that restrict cold outreach velocity and force geography-specific instance deployment. Bangalore and Hyderabad technology corridors concentrate demand for marketing automation platforms with AI-powered send-time optimization.
United Kingdom
Financial services firms in the City of London drive premium pricing for security and compliance modules that justify costs against tightening enforcement. GDPR requirements intersect with FCA conduct rules to create layered documentation burdens for automated email content generation. The Thames Valley corridor hosts procurement teams consolidating around unified API gateways that reduce point-solution fragmentation.
Japan
Enterprise adoption concentrates among telecommunications operators and SaaS vendors seeking ticket-to-email threading and automated response routing. METI guidelines on data governance shape vendor selection criteria for cloud-based deployment. Tokyo and Osaka metropolitan areas anchor demand for real-time journey orchestration that compresses message delivery latency from minutes to milliseconds.
Global Email Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized compliance-ready configurations and mid-market inbound workflow simplification. The vendor base organizes around three archetypes: hyperscaler-backed platforms leveraging dedicated data center capacity, CRM-extended solutions converging customer data layers with message routing engines, and inbound marketing specialists reducing dependency on fragmented point solutions. Dominant competitive moves include strategic partnerships with system integrators architecting hybrid cloud migrations and portfolio diversification into security and compliance premium tiers.
Within the hyperscaler-backed tier, Microsoft Corporation and Google LLC anchor procurement toward FedRAMP-authorized environments, while Salesforce, Inc. occupies a position exemplifying CRM-to-email convergence through Customer 360 platform extensions. HubSpot, Inc. represents the mid-market specialization archetype, demonstrating whitespace for integrated platforms that reduce complexity without enterprise-scale infrastructure demands.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Apple Inc. |
| Salesforce, Inc. |
| Oracle Corporation |
| HubSpot, Inc. |
| Mailchimp |
| Klaviyo |
| Zoho Corporation |
| Others |
Supply & Pricing Matrix
Compliance-grade certification divergence between FedRAMP-authorized hyperscaler environments and geography-specific localized instances manifests in both subscription pricing stratification and data center supply chain fragmentation. Premium tiers anchored in Virginia and Oregon hyperscaler regions command substantial markups over standard cloud deployments, while hybrid architectures routing sensitive communications through on-premises gateways extract additional premiums from German automotive suppliers and Indian public sector banks facing data sovereignty audits.
Pricing Analysis
Distributor margin compression in system integrator channels intensifies as Accenture and Deloitte practices architect hybrid cloud migrations, commanding implementation fees that exceed license costs. Three-tier pricing structure across premium, standard, and economy levels segments by compliance certification depth, with encryption-at-rest and audit logging modules justifying top-tier positioning. Cost compression in mid-market SaaS tiers stems from subscriber list elasticity and API-first infrastructure commoditization. SMB procurement teams exhibit highest price sensitivity, prioritizing vendor reduction over feature depth, while Fortune 500 technology budgets demonstrate lowest sensitivity to per-seat costs when single-vendor consolidation is achieved.
Supply Chain Analysis
Regional distribution centers in Virginia and Oregon hyperscaler regions anchor hub-and-spoke patterns for high-throughput transactional processing exceeding ten thousand messages per second. Supply concentration rests on backbone capacity in the United States, Germany, and India, with Bangalore and Hyderabad technology corridors feeding mid-market retail demand. Raw material dependencies include dedicated server infrastructure, TLS certificate authority services, and deliverability engineering talent pools. Single-source vulnerability concentrates in SMTP infrastructure capacity during peak campaign windows. Distribution runs through direct sales relationships for enterprise contracts and online marketplaces for developer self-service provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement teams weight algorithmic transparency and compliance documentation as heavily as deliverability metrics, shifting demand toward premium-certified platforms.
For Market Incumbents: Lock in government and healthcare contracts through FedRAMP-authorized environment expansion before emerging entrants achieve authorization timelines. Defend against CRM-to-email convergence threats by deepening API gateway integration that collapses routing, templates, and analytics into unified stacks. Prioritize vertical integration into deliverability engineering talent pools, as specialized inbox placement expertise commands premium compensation and constrains competitor scaling.
For New Entrants and Emerging Players: Capture whitespace in mid-market inbound marketing workflows where HubSpot's specialization demonstrates demand for integrated platforms without enterprise complexity. Target German automotive suppliers and Indian public sector banks with hybrid architecture offerings that satisfy data localization audits under evolving sovereignty rules. Deploy through value-added reseller channels that bundle email platforms with complementary marketing technology stacks to bypass direct sales incumbent dominance.
For Investors and Strategic Acquirers: Consolidation pressure builds where algorithmic transparency mandates under the EU AI Act fragment operational economics and raise compliance costs for subscale vendors. Long-term viability favors platforms with hyperscaler-backed infrastructure and documented explainability architectures. Acquisition target archetype: mid-market inbound specialists with proven workflow simplification and established system integrator partnerships. Signal to watch: divergence between regional compliance architectures forcing geography-specific instance deployment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CRM-to-email convergence through Customer 360 extensions collapses routing and analytics layers. |
| Strategic Partnership | System integrator alliances with Accenture and Deloitte capture hybrid migration implementation fees. |
| Geographic Expansion | Virginia and Oregon hyperscaler capacity blocks secure FedRAMP-authorized government contract eligibility. |
| Acquisition of Specialist Firm | Deliverability engineering talent pools address scarcity constraining platform scaling velocity. |
| Product Launch | Security and compliance premium tiers with encryption-at-rest justify pricing against SEC retention mandates. |
Research Methodology
Coverage spans the United States, Germany, India, the United Kingdom, and Japan, with primary inputs from each regional cluster combining interviews with CTOs, IT procurement officers, platform engineers, and channel partners alongside secondary validation. SEC filings, hyperscaler capex disclosures, and EU regulatory documentation provided demand-side calibration. Bottom-up subscriber list modeling and top-down enterprise technology budget analysis were triangulated against vendor-reported capacity metrics.
Granularity-level modeling deployed deployment mode, organization size, vertical specialization, and regional adoption pattern dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted subscriber growth curves and compliance-driven upgrade cycle assumptions. AI-powered send-time optimization penetration rates and predictive personalization adoption thresholds informed solution-type trajectories.
Underlying measurement precision varies by segment; cloud-based deployment and marketing automation solution types carry tighter precision than legacy on-premises and collaborative platform categories. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and hyperscaler capacity expansion timelines. Decision-makers should treat outputs as directional within the stated assumption set, acknowledging that EU AI Act implementation divergence or TLS encryption standard fragmentation could materially revise trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Telecom Billing Software Market
Software & Services
Global Automation Software Market
Software & Services
Tag Management Software Market
Software & Services
Middleware Market
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
United States Donation Management Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
Attendance Management Software Market
Software & Services
Global Backup Restore Software Market
Software & Services
Global Webinar Software Market
Software & Services
Supply Chain Management (SCM) Software Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
Real Estate Software Market
Software & Services
Global Enterprise Architecture Tools Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Attendance Tracking Software Market