
 Predictive Dialer Software Market | 2026-2036
Predictive Dialer Software Market Size, Share, and Industry Trends Forecast 2026-2036
Predictive Dialer Software Market Intelligence
India is rewriting competitive dynamics in contact center outsourcing, pulling predictive dialer deployments toward cloud-native architectures at scale. Five9, Inc. leverages its integrated CCaaS platform to anchor enterprise accounts across North America. NICE Ltd. dominates compliance-rich environments with AI-driven workforce optimization layered into dialing workflows. Convoso competes aggressively on speed-to-lead capabilities for high-velocity sales teams.
Predictive dialer software is an automated outbound calling system that uses statistical algorithms to initiate multiple calls per available agent, filtering unanswered calls, busy signals, and voicemails to connect agents only to live human responses. The system typically processes call pacing ratios, abandonment rate thresholds, and agent availability signals in real time to optimize connect rates and minimize idle time. Cloud-Based deployment leads segment expansion as enterprises abandon capital-intensive on-premise hardware for elastic consumption models. AI-Driven technology represents the fastest-growing capability layer, embedding machine learning into call pacing and lead scoring. Call Centers remain the core end-user vertical, though Sales Teams show the steepest adoption curve as inside-sales operations digitize prospecting workflows.
The FCC enforces TCPA regulations that penalize non-compliant dialing practices, forcing vendors to embed consent management and abandonment-rate controls directly into platform architecture. GDPR in Europe and India's TRAI guidelines on unsolicited commercial communication impose parallel constraints on cross-border outbound campaigns. Stakeholders must monitor how generative AI integration into scripting and voice analytics reshapes regulatory scrutiny of automated consumer interactions.
Market Dynamics
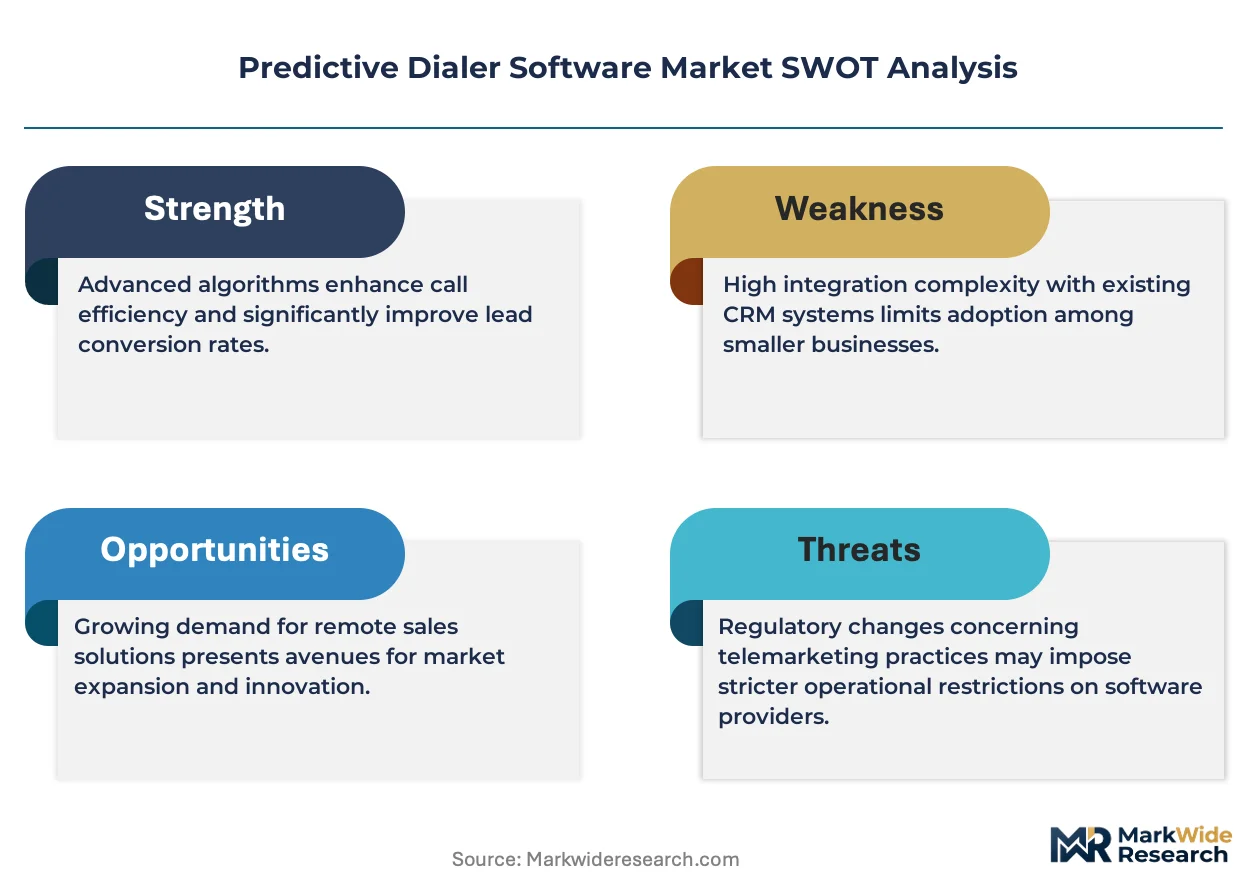
AI-driven call pacing algorithms are compressing agent idle time below legacy statistical thresholds, forcing vendors to rebuild core engines around real-time machine learning inference rather than rules-based statistical models.
Growth Catalysts
- Cloud-Native Architecture Migration:Elastic consumption models eliminate capital-intensive on-premise hardware refresh cycles. Contact centers in India and the Philippines are deploying cloud-native stacks at scale.
- FCC TCPA Compliance Mandates:Consent management and abandonment-rate controls embedded directly into platform architecture create vendor differentiation. Non-compliant dialers face statutory penalties per violation.
- Inside-Sales Digitization:High-velocity sales teams demand speed-to-lead capabilities that predictive algorithms optimize. CRM-integrated dialing workflows compress prospect response latency.
Market Restraints
- Telecom Carrier Concentration:Tier-1 carrier pricing power in the United States constrains per-minute cost structures for high-volume outbound operations.
- Regulatory Fragmentation:Parallel constraints from GDPR in Europe, TRAI guidelines in India, and FCC rules in the United States force multi-jurisdictional compliance architecture.
- Legacy System Entrenchment:On-premise ACD investments at established contact centers create technical debt friction against full-stack replacement.
Strategic Opportunities
- Generative AI Scripting Convergence:Large language models integrated into real-time agent guidance and voice analytics create new capability layers. Vendors embedding GPT-class engines differentiate on conversation quality.
- European GDPR-Compliant Expansion:Consent-first dialing architectures designed for FCC rules transfer with modification to EU markets. Ireland and Poland host emerging contact center clusters.
- API-First Distribution Channels:Embedded finance-style integration into CRM and workforce management platforms displaces standalone software procurement. Salesforce and HubSpot ecosystems drive attach rates.
Industry Challenges
- ML Engineering Talent Scarcity:Real-time call pacing algorithm development requires specialized machine learning operations expertise. Vendors compete for scarce data science talent in Bangalore and Silicon Valley.
- Cross-Platform Integration Complexity:Bi-directional synchronization with legacy CRM databases and proprietary ACD systems demands custom professional services engagements. Implementation timelines extend beyond SaaS benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Predictive Dialer Software Market |
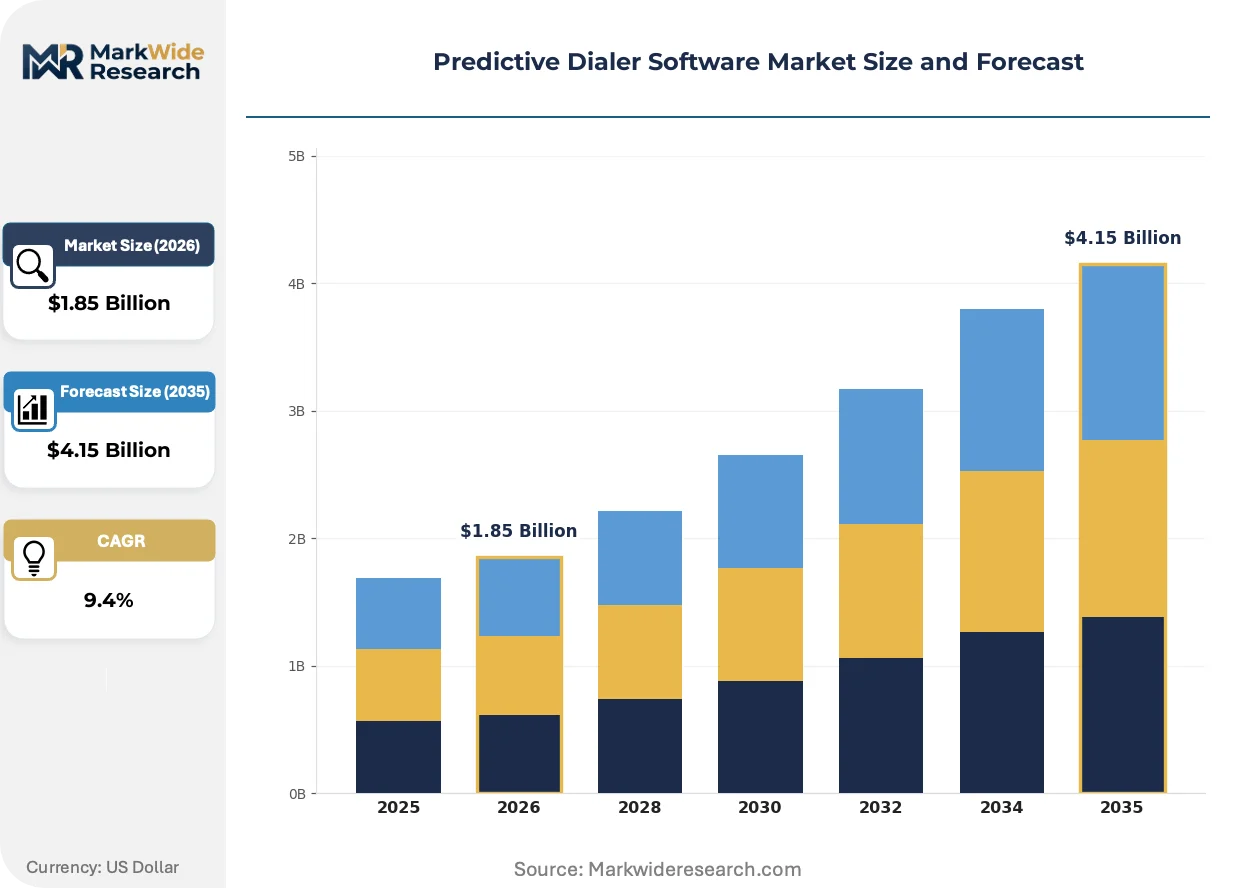
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Remote End User: Call Centers, Telemarketing Firms, Customer Support, Sales Teams Technology: VoIP, AI-Driven, Automatic Call Distribution, CRM Integration Feature: Real-Time Analytics, Call Recording, Agent Scripting, Predictive Analytics |
| Companies Covered | Five9, Inc., NICE Ltd., Convoso, RingCentral, Inc., Talkdesk Inc., DialedIn, Genesys Cloud Services Inc., Alvaria Inc., PhoneBurner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Predictive Dialer Software Market Strategic Shifts & Innovations
Neural call classification models are replacing statistical abandonment predictors, compressing the technology refresh cycle from multi-year enterprise agreements to continuous deployment pipelines.
Machine learning inference at the edge is rendering obsolete centralized batch-processing architectures for call pacing decisions. Mid-market contact centers in Texas and Arizona are adopting edge-deployed models to minimize latency. The shift enables sub-second agent availability signaling that legacy client-server stacks cannot match.
The FCC's STIR/SHAKEN framework for caller ID authentication imposes attestation requirements on outbound dialers. Robocall mitigation mandates force vendors to embed identity verification tokens into SIP headers. High-volume debt collection agencies face elevated blocking risk without A-level attestation, driving platform architecture redesign.
Subscription pricing for AI-enhanced seats is displacing perpetual licensing and usage-based minutes. Inside-sales departments at B2B software vendors favor predictable per-agent costs over variable telecom billing. The model concentrates most visibly among 50-200 seat operations in the United States seeking budget certainty.
Predictive Dialer Software Market Segmentation
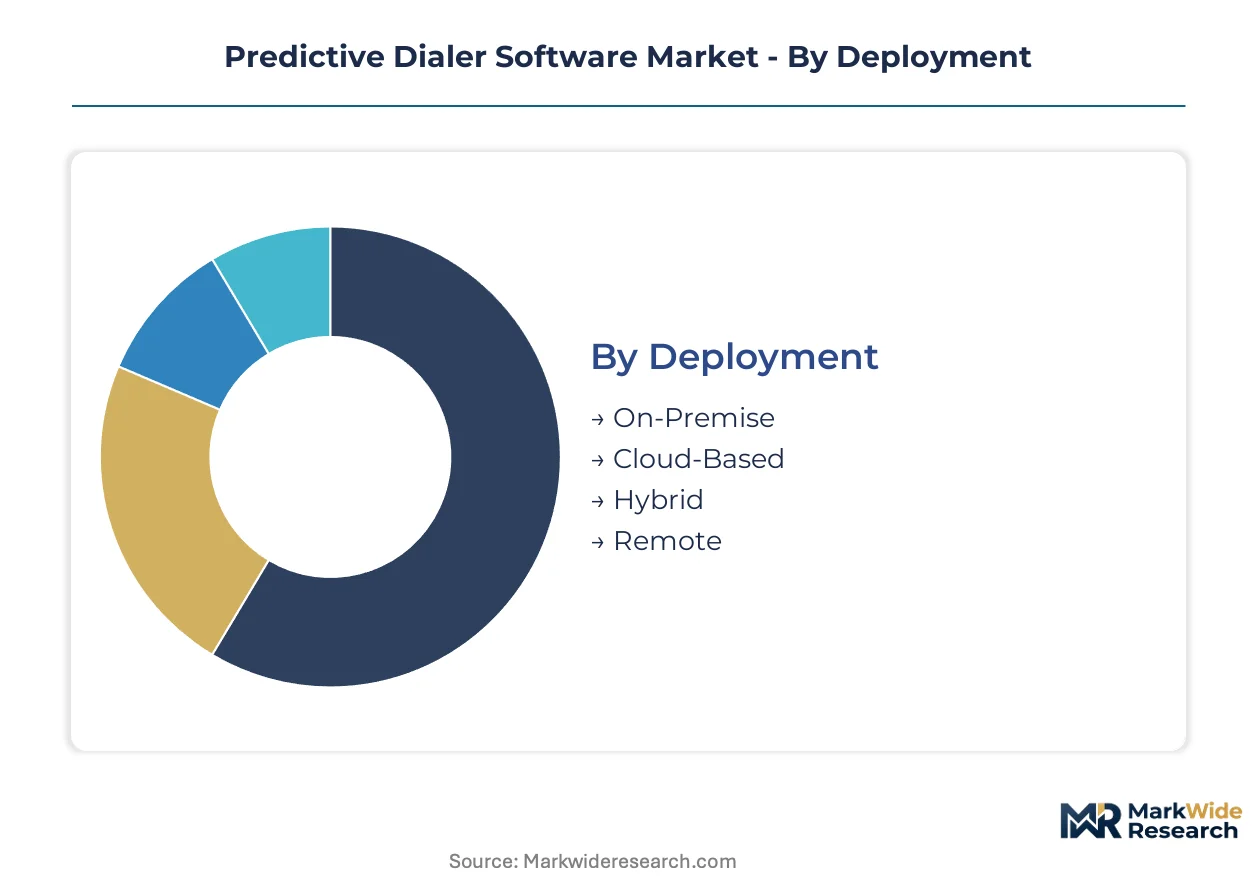
Predictive dialer software vendors architect product lines around deployment flexibility, end-user workflows, and intelligence layers. Segmentation choices directly determine compliance architecture, integration complexity, and pricing models across customer profiles.
Deployment:
Use-case spectrum spans capital-intensive legacy estates to elastic cloud-native operations, with hybrid architectures bridging technical debt constraints.
- Cloud-Based:Multi-tenant SaaS architectures provision compute and telephony resources on demand. Contact centers in India and the Philippines deploy these stacks at scale to eliminate hardware refresh cycles and enable distributed agent pools.
- On-Premise:Customer-managed infrastructure maintains physical control over call data and carrier interconnections. Established debt collection agencies in the United States retain these deployments to satisfy audit requirements and minimize third-party data exposure.
- Hybrid:Split architectures keep sensitive call recordings on local storage while routing live traffic through cloud dialer engines. Mid-market operations in Texas and Arizona adopt this pattern during phased migrations.
- Remote:Edge-deployed models run pacing algorithms on local devices to minimize latency for home-based agents. Post-pandemic workforce dispersion drives procurement among inside-sales departments seeking sub-second agent availability signaling.
The dominant share belongs to Cloud-Based, while Remote is closing the gap fastest.
End User:
Customer type determines feature prioritization, with compliance-heavy operations demanding audit trails and velocity-focused teams optimizing for speed-to-lead.
- Sales Teams:High-velocity B2B prospecting operations require CRM-embedded dialing with lead scoring and immediate callback triggers. Inside-sales departments at software vendors prioritize these capabilities to compress response latency.
- Call Centers:Large-scale inbound-outbound blended operations manage agent utilization across campaign types. Facilities in the United States drive volume procurement, layering workforce optimization and quality monitoring into core dialing workflows.
- Telemarketing Firms:Outbound-focused campaigns operate under strict abandonment-rate thresholds and consent management requirements. FCC TCPA compliance mandates shape platform selection for these operators.
- Customer Support:Service-oriented deployments emphasize callback scheduling and case-context preservation. Technical support divisions at enterprise technology vendors adopt these configurations to maintain continuity across touchpoints.
Sales Teams command the steepest expansion trajectory, though Call Centers retain the largest installed base.
Technology:
Maturity gradients separate established telephony protocols from emerging intelligence layers that reshape competitive differentiation.
- AI-Driven:Machine learning inference engines optimize call pacing ratios and abandonment predictions in real time. Vendors embedding neural classification models differentiate on connect-rate performance against legacy statistical approaches.
- VoIP:Session Initiation Protocol-based voice transport enables cost-efficient scaling across geographic agent pools. Carrier-grade implementations require STIR/SHAKEN attestation compliance to mitigate blocking risk.
- Automatic Call Distribution:Rules-based routing engines distribute connected calls to available agents based on skill matrices and queue depth. Legacy ACD investments create integration friction against modern predictive dialer replacements.
- CRM Integration:Bi-directional data synchronization with Salesforce, HubSpot, and proprietary databases embeds dialing into revenue workflows. API-first architectures displace standalone procurement through embedded finance-style distribution.
AI-Driven layers are gaining share fastest, while VoIP remains the foundational transport standard.
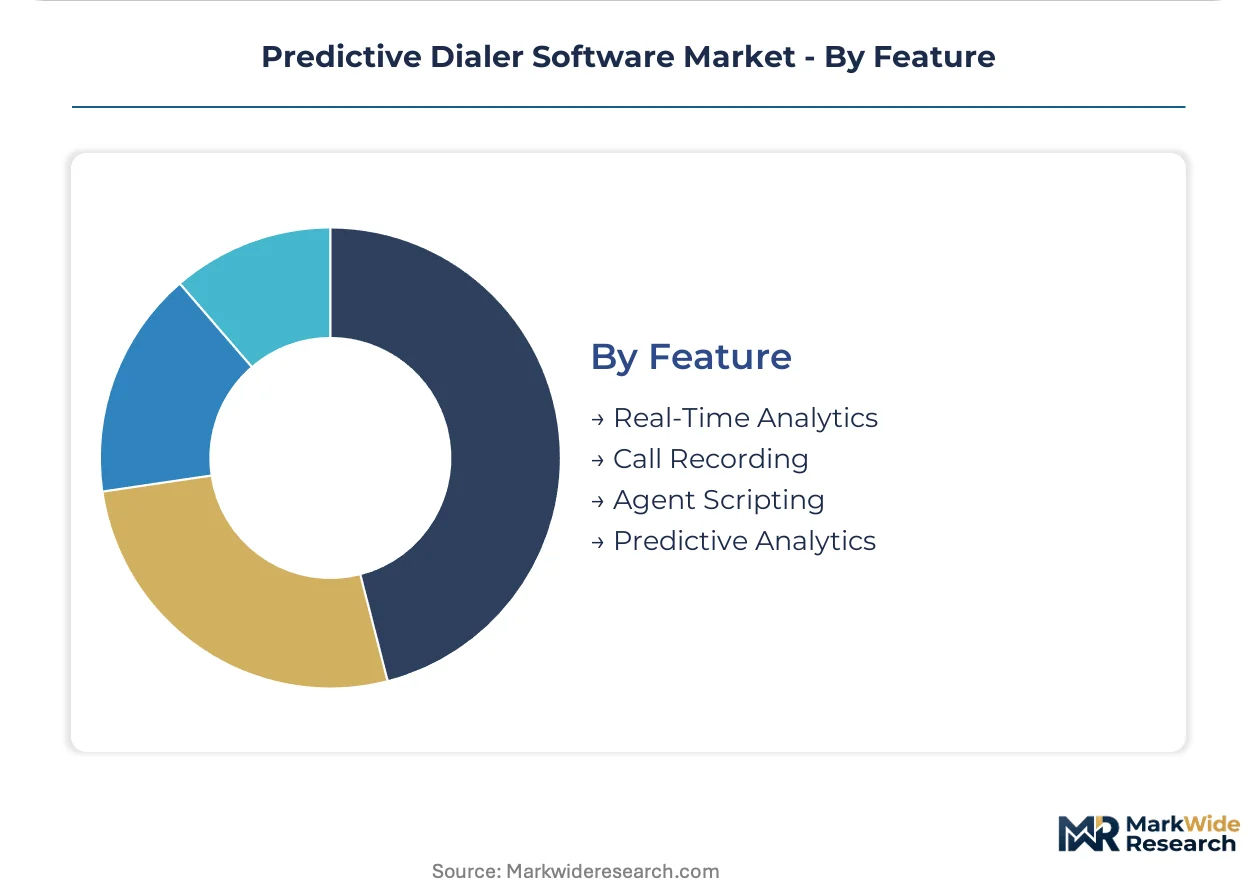
Feature:
Capability depth stratifies pricing tiers, with advanced analytics and automation commanding premium positioning over baseline compliance tooling.
- Predictive Analytics:Statistical and machine learning models forecast optimal contact windows, agent availability, and conversion likelihood. These capabilities compress idle time below legacy thresholds and justify per-seat premiums.
- Real-Time Analytics:Live dashboards track campaign performance, agent productivity, and regulatory compliance metrics. Operations managers in high-volume environments depend on these views for intraday pacing adjustments.
- Call Recording:Storage and retrieval infrastructure captures conversations for quality assurance and dispute resolution. GDPR and state-level consent requirements impose architecture constraints on cross-border deployments.
- Agent Scripting:Dynamic guidance surfaces contextual prompts based on customer responses and campaign objectives. Generative AI integration is displacing static scripts with large language model-powered real-time assistance.
Predictive Analytics anchors premium pricing, while Real-Time Analytics is penetrating mid-market deployments most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC TCPA enforcement anchors the United States as the regulatory benchmark for outbound dialing compliance worldwide. Cloud-native deployments concentrate in India and the Philippines as contact center outsourcing scales. European markets demand GDPR-aligned consent architectures that vendors adapt from FCC-compliant stacks.
United States
Large-scale debt collection agencies and inside-sales departments drive procurement volume across Texas, Arizona, and Florida contact center clusters. FCC STIR/SHAKEN attestation requirements force platform redesigns to embed identity verification tokens into SIP headers. Dallas-Fort Worth hosts concentrated deployments where high-volume outbound operations face elevated carrier blocking risk without A-level compliance.
India
TRAI guidelines on unsolicited commercial communication impose parallel constraints to FCC rules for cross-border campaign management. Bangalore and Hyderabad contact centers deploy cloud-native predictive dialer stacks at scale to eliminate hardware refresh cycles. The National Capital Region anchors vendor delivery centers where ML engineering talent scarcity intensifies competition for algorithm development expertise.
Germany
GDPR consent-first architectures transfer from FCC-compliant platforms with modification for European data residency requirements. Frankfurt and Berlin host emerging contact center clusters serving multilingual EU campaigns. The country's federal data protection authority enforces strict cross-border call recording restrictions that shape storage architecture decisions.
United Kingdom
Post-Brexit regulatory divergence from GDPR creates compliance complexity for vendors serving both UK and EU campaigns. London anchors financial services contact centers where debt collection and customer retention workflows demand audit-trail capabilities. Manchester and Glasgow clusters adopt hybrid deployments during phased cloud migrations.
Philippines
Outsourcing scale drives elastic consumption models as facilities abandon capital-intensive on-premise hardware. Metro Manila and Cebu City contact centers prioritize sub-second agent availability signaling through edge-deployed pacing algorithms. The country's national telecommunications commission imposes progressive dialing restrictions that vendors embed into platform architecture.
Predictive Dialer Software Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where AI-driven algorithm vendors compete against integrated CCaaS platforms. The vendor base spans pure-play dialer specialists, full-stack contact center suites, and API-first embedded finance distributors. Three archetypes dominate: compliance-rich enterprise suites, speed-to-lead sales accelerators, and cloud-native elasticity providers. Competitive moves center on generative AI scripting convergence and API-first distribution channel expansion into Salesforce and HubSpot ecosystems.
Within the integrated platform tier, Five9, Inc. and NICE Ltd. anchor enterprise positioning across North American accounts. Convoso occupies a position among velocity-focused specialists competing on speed-to-lead capabilities for high-velocity sales teams. These three exemplify how vendor archetypes map to end-user workflow priorities rather than geographic coverage alone.
| Leading Market Players |
|---|
| Five9, Inc. |
| NICE Ltd. |
| Convoso |
| RingCentral, Inc. |
| Talkdesk Inc. |
| DialedIn |
| Genesys Cloud Services Inc. |
| Alvaria Inc. |
| PhoneBurner |
| Others |
Cost & Logistics Intelligence
Carrier concentration in the United States anchors upstream pricing power for telecom interconnects, concentrating margin pools with Tier-1 network operators while predictive dialer vendors compete downstream on seat economics and AI feature premiums.
Pricing Analysis
Geographic price spreads separate North American deployments from Asia-Pacific rollouts, with US-based operations absorbing 40-60% higher per-minute carrier costs. The dominant pricing structure is subscription-based per-agent SaaS tiers, with AI-enhanced seats commanding premiums over baseline compliance packages. Price differentiation hinges on integration depth with Salesforce and HubSpot ecosystems, plus real-time analytics granularity. Pricing pressure stems from carrier rate negotiations and cloud infrastructure commoditization. Mid-market call centers in Texas and Arizona show highest price sensitivity, while enterprise debt collection agencies prioritize compliance over cost.
Supply Chain Analysis
Upstream feedstock for predictive dialer platforms centers on cloud compute from AWS, Microsoft Azure, and Google Cloud, with telephony infrastructure sourcing from Tier-1 carriers including AT&T, Verizon, and Lumen. Geographic supply concentration clusters in the United States for carrier interconnections, India for ML engineering talent, and Ireland for GDPR-aligned data residency. Raw material dependencies include GPU compute cycles for AI inference, SIP trunk capacity for voice transport, and API integration bandwidth for CRM synchronization. Supply chain risk concentrates in single-source carrier relationships for high-volume outbound operations. Distribution runs through direct enterprise sales, API-first embedded finance channels, and Salesforce AppExchange marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The predictive dialer market is crossing a platform-economics inflection where API-first distribution through Salesforce and HubSpot ecosystems is displacing standalone procurement, rewarding vendors who embed deeply into revenue workflow infrastructure.
For Market Incumbents: Harden defensive moats around FCC STIR/SHAKEN compliance certification and real-time AI inference latency below 200 milliseconds. Consolidate position through backward integration into carrier relationships to secure A-level attestation rates. Prioritize R&D investment in generative AI scripting engines to differentiate against emerging API-first entrants.
For New Entrants and Emerging Players: Build out white-space presence in European GDPR-compliant deployments, where FCC-hardened architectures transfer with modification. Target mid-market inside-sales departments at B2B software vendors seeking speed-to-lead capabilities without enterprise suite complexity. Lead with HubSpot-native embedded dialer apps to bypass standalone procurement cycles.
For Investors and Strategic Acquirers: Capital is best deployed toward AI-driven algorithm specialists with demonstrated connect-rate performance advantages over statistical dialers. Long-term viability favors vendors with proven ML engineering teams in Bangalore or Silicon Valley, plus established carrier attestation relationships. Watch for inflection signals in generative AI scripting adoption rates among high-velocity sales teams.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Salesforce and HubSpot embedding displaces standalone software procurement through embedded finance distribution models. |
| Acquisition of Specialist Firm | ML engineering talent scarcity in Bangalore drives consolidation of algorithm development capabilities among acquirers. |
| Product Launch | Generative AI scripting engines differentiate conversation quality against rules-based agent guidance competitors. |
| Strategic Partnership | Tier-1 carrier relationships secure STIR/SHAKEN A-level attestation to mitigate blocking risk for high-volume operations. |
| Geographic Expansion | GDPR-aligned data residency builds in Ireland and Germany open EU market access for FCC-hardened compliance architectures. |
Research Approach
A spread of perspectives from contact center operations directors, CRM integration specialists, carrier interconnection managers, and FCC compliance officers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from CCaaS vendors, FCC enforcement action databases, TRAI regulatory circulars, and hyperscaler cloud infrastructure disclosure reports. Bottom-up seat-count modeling and top-down addressable market sizing were triangulated against deployment data from India and Philippines outsourcing clusters.
Demand-supply balance dynamics across cloud-native provisioning capacity and carrier interconnect availability anchored the analytical framework. Segmentation dimensions modeled include deployment architecture, end-user workflow type, AI capability layer, and regional regulatory cluster. CAGRs were derived from installation base growth trajectories and seat economics evolution. Forecast inputs incorporated ML inference adoption curves and STIR/SHAKEN compliance penetration rates.
Stress conditions across carrier rate volatility, regulatory enforcement intensity, and generative AI integration costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cloud infrastructure cost curves and contact center outsourcing migration patterns. Cross-checking against hyperscaler earnings call commentary on communications platform revenue is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Ad Server Software Market
Software & Services
Business Activity Monitoring Software (BAM) Market
Software & Services
Global Gym Software Market
Software & Services
Apache Spark Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Global Open API Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Software Market
Software & Services
Airline Route Profitability Software Market
Software & Services
Problem Management Software Market
Software & Services
Global Help Desk Software Market
Software & Services
Case Management Software (CMS) Market
Software & Services
Global Microscope Software Market
Software & Services
Legal Software Market
Software & Services
Aviation Software Market
Software & Services
Global Portal Software Market