

Outsourced Digital Workplace Service Market Size, Share, and Industry Trends Forecast 2026-2036
Outsourced Digital Workplace Service Market Insights
The gap between premium integrated workplace platforms and commodity IT support is broadening as enterprises split procurement between transformation-grade partners and cost-driven maintenance vendors. Accenture leverages its consulting-to-operations pipeline to capture high-margin managed services contracts. HCLTech anchors its position through in-house digital workplace software stacks and deep manufacturing sector relationships. Cognizant competes aggressively on price in staff augmentation while building specialized application management practices for financial services clients.
Outsourced digital workplace services encompass the third-party provision of end-user computing environments, combining remote desktop management, cloud-based collaboration tools, security monitoring, and application support delivered through public cloud, private cloud, or hybrid infrastructure. These services operate on service-level agreements specifying uptime thresholds, ticket resolution times, and endpoint response benchmarks, with primary purpose being to replace or augment internal IT teams while standardizing employee experience across distributed locations. Cloud collaboration and security monitoring segments are expanding fastest as zero-trust architectures and persistent hybrid work normalize enterprise expectations, while desktop management remains mature with compressed margins and heavy automation. The hybrid cloud deployment model captures disproportionate value as regulated industries demand data residency controls without sacrificing SaaS flexibility.
GDPR enforcement by European data protection authorities, the EU AI Act's risk classification requirements, and ISO 27001 certification mandates are reshaping vendor qualification criteria and contract structures across European procurement. The US SEC's cybersecurity disclosure rules and HIPAA technical safeguards for healthcare endpoints create parallel compliance burdens that favor outsourced specialists with established governance frameworks. Stakeholders must evaluate whether their provider's certification portfolio matches the regulatory perimeter of their operating geographies before committing to multi-year engagement models.
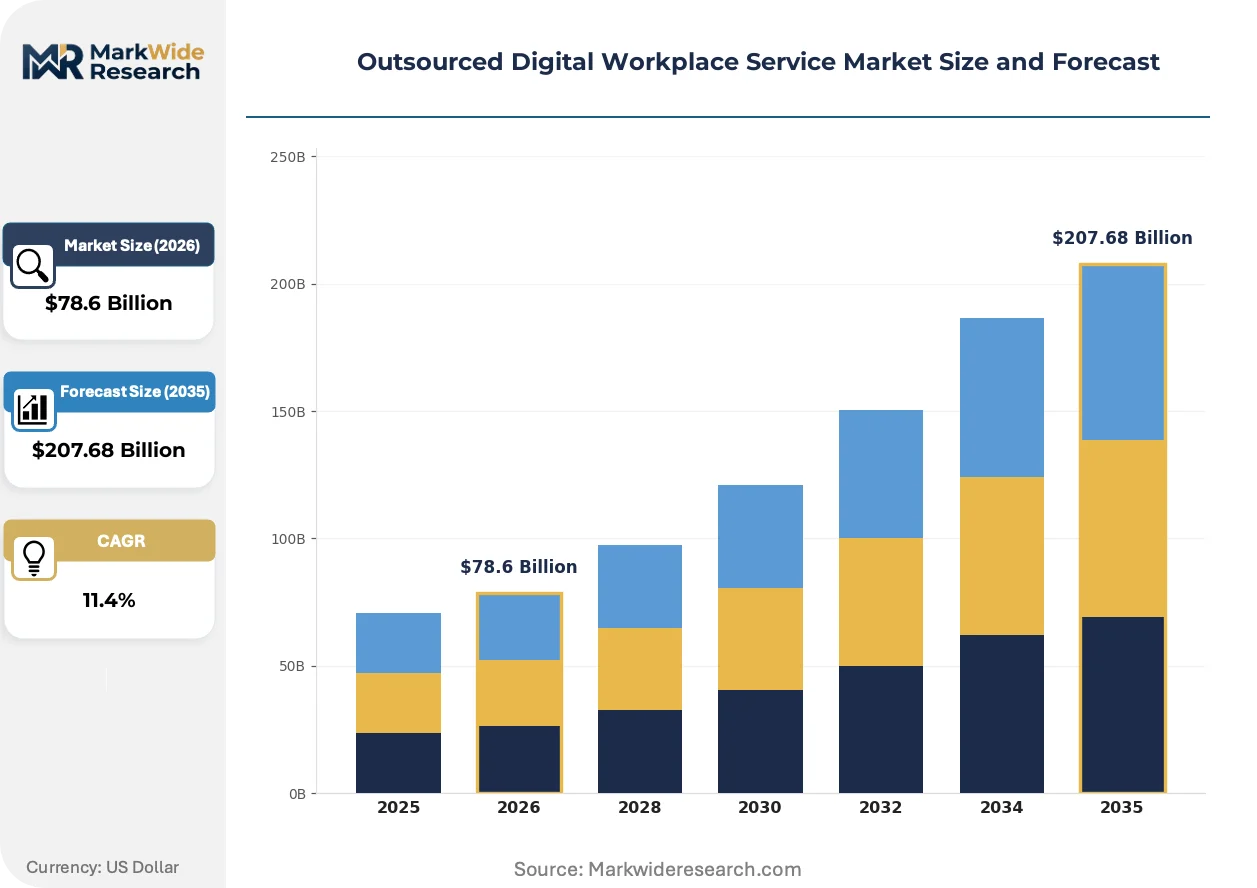
Market Dynamics
Zero-trust security architectures and persistent hybrid work models are compressing legacy desktop management margins while elevating cloud collaboration and security monitoring to premium pricing tiers. This structural shift forces vendors to rebalance portfolios toward integrated platforms or accept commoditization in endpoint support.
Growth Catalysts
- EU AI Act risk classification:European enterprises face mandatory governance requirements for AI-enabled workplace tools, driving procurement of outsourced compliance monitoring and documentation services from specialized providers.
- Financial services endpoint standardization:Banks and insurers require consistent employee experiences across trading floors, branch networks, and remote workers, consolidating vendor relationships around managed desktop and cloud collaboration suites.
- Zero-trust architecture deployment:Continuous verification models demand 24/7 security operations capabilities that internal IT teams cannot sustain, accelerating outsourcing of identity management and endpoint detection.
Market Restraints
- Specialized cybersecurity talent scarcity:Certified security operations analysts command compensation premiums that compress margins for multi-tenant service delivery models.
- Cloud infrastructure concentration:Hyperscaler dependency in Germany, the United States, and India creates single-point-of-failure exposure and limits negotiation leverage for mid-market buyers.
- Data residency fragmentation:Conflicting sovereignty requirements across operating geographies force redundant infrastructure deployments that dilute economies of scale.
Strategic Opportunities
- India domestic market expansion:PLI scheme incentives and multinational back-office consolidation create demand for standardized digital workplace platforms serving distributed workforces.
- Convergence of endpoint AI and security monitoring:Intelligent automation of threat detection and user behavior analytics opens new service categories at higher margin profiles than traditional desktop support.
- US SEC cybersecurity disclosure compliance:Public companies require documented governance frameworks for material incident reporting, creating attach opportunities for outsourced risk assessment services.
Industry Challenges
- ISO 27001 certification timeline compression:Enterprise procurement mandates increasingly require current certification, disqualifying vendors with renewal gaps or audit findings.
- Legacy application containerization complexity:Decades-old financial services and manufacturing software resists cloud-native refactoring, forcing expensive emulation or parallel infrastructure maintenance.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outsourced Digital Workplace Service Market Trends and Innovations
Artificial intelligence is embedding into every layer of workplace service delivery, from predictive endpoint remediation to autonomous security response. This technological infusion is redrawing competitive boundaries between consulting-led transformation and operational efficiency plays.
Generative AI copilots integrated into service desk operations is electrifying first-line support economics. Microsoft and Google embed these capabilities natively into collaboration suites, forcing pure-play outsourcers to differentiate through vertical-specific training data and workflow customization. Financial services firms pilot these tools for code documentation and compliance query resolution, compressing resolution times while elevating escalated ticket complexity.
GDPR enforcement actions by European data protection authorities are tightening cross-border data processing rules for workplace analytics. Germany's BSI technical guidelines and France's CNIL recommendations now explicitly address employee monitoring boundaries, requiring explicit consent frameworks that complicate productivity measurement services. Vendors serving multinational clients must architect tenant isolation and processing location controls that satisfy divergent national interpretations.
Enterprise buying committees now mandate outcome-based pricing with measurable employee experience metrics rather than per-seat or ticket-volume arrangements. Device-as-a-service bundles combining hardware refresh, management, and support gain traction in healthcare and professional services verticals where capital efficiency priorities override ownership preferences. Germany and the United States show the fastest contract structure evolution, with India following as multinational shared service centers import these procurement standards.
Outsourced Digital Workplace Service Market Segmentation
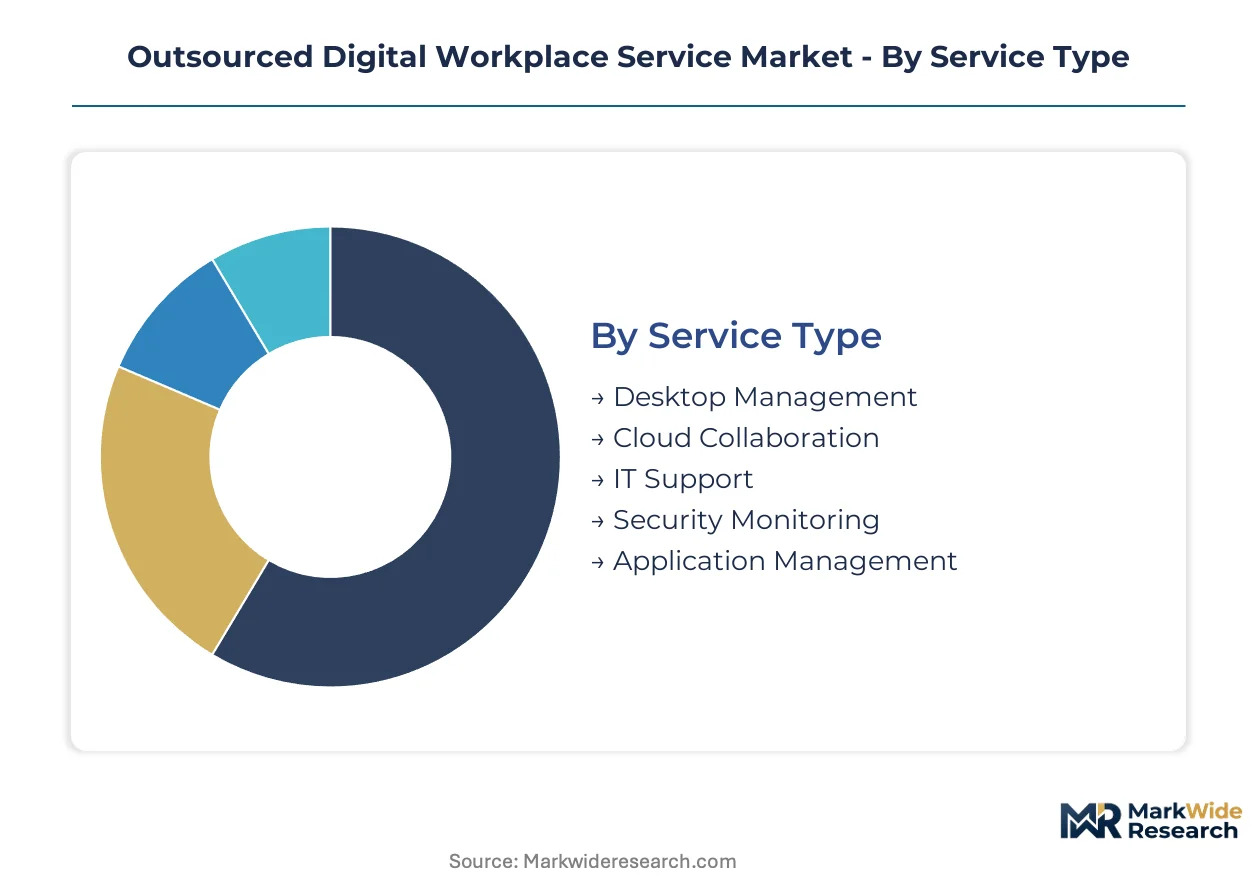
Segmentation reveals how procurement committees weight cost predictability against transformation ambition. Buyers segment first by risk tolerance, then by infrastructure legacy, creating distinct vendor qualification tracks across the market.
Service Type:
Cost tier determines vendor pool access, with premium integrated platforms commanding separate RFP processes from commodity maintenance contracts.
- Desktop Management:Endpoint provisioning, patch management, and hardware lifecycle administration delivered through automated orchestration layers. Financial services firms in Germany and the United States concentrate procurement here, driven by trading floor uptime requirements and SEC cybersecurity disclosure obligations. Volume sits with desktop management; growth tilts toward security monitoring.
- Cloud Collaboration:Unified communication platforms combining messaging, video conferencing, and document co-authoring with identity federation. Multinational shared service centers in India drive demand fastest, importing US and German procurement standards for standardized employee experiences.
- IT Support:Service desk operations spanning incident resolution, request fulfillment, and knowledge base maintenance.
- Security Monitoring:Continuous threat detection, identity management, and compliance documentation for zero-trust architectures.
- Application Management:Legacy software maintenance, cloud-native refactoring, and SaaS integration support.
Margin compression in desktop support pushes vendors toward security monitoring attach rates.
Deployment Model:
Application sensitivity to data residency rules shapes infrastructure selection more than cost optimization.
- Hybrid Cloud:Workload portability between private data centers and public hyperscalers with policy-driven placement. European BFSI and healthcare sectors anchor demand, compelled by GDPR enforcement and divergent national sovereignty interpretations. Procurement concentrates here; expansion runs through private cloud.
- Public Cloud:Multi-tenant SaaS delivery with shared infrastructure and rapid elasticity.
- Private Cloud:Dedicated tenant environments with single-customer resource isolation.
- Hosted:Traditional colocation with vendor-managed hardware refresh cycles.
- Virtual Desktop Infrastructure:Centralized desktop streaming to thin clients and personal devices.
Regulated industries fragment procurement across hybrid and private cloud to satisfy compliance perimeters.
End User Industry:
Vertical-specific certification requirements filter vendor participation before technical evaluation begins.
- BFSI:Trading floor resilience, branch network standardization, and regulatory reporting infrastructure. German banks and US insurers lead contract value, integrating EU AI Act governance with SEC cybersecurity disclosure frameworks. Revenue concentrates here; fastest expansion occurs in telecommunications.
- Telecommunications:Field technician enablement, customer service operations, and network operations center support.
- Manufacturing:Shop floor device management, supply chain collaboration, and quality system documentation.
- Education:Campus-wide device provisioning, learning management integration, and research data protection.
- Government:Classified and unclassified network segmentation with civilian and defense procurement streams.
BFSI sustains largest deal sizes; telecommunications climbs fastest on 5G field workforce enablement.
Engagement Model:
Outcome maturity determines whether buyers accept input-based pricing or demand measurable employee experience guarantees.
- Managed Services:Comprehensive SLA-backed operations with defined uptime, resolution time, and endpoint performance thresholds. German and US enterprises consolidate here, seeking single-accountability transformation partners over fragmented vendor panels. Contract value peaks here; staff augmentation retains volume.
- Staff Augmentation:Temporary personnel placement with client-directed supervision and task assignment.
- Transactional:Per-ticket or per-incident pricing without ongoing relationship commitment.
- Project-Based:Defined-scope transformation initiatives with fixed deliverables and timelines.
Managed services capture strategic budgets; staff augmentation fills capacity gaps in cyclical industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's banking corridor drives European procurement concentration for managed workplace services, with financial institutions consolidating vendor relationships around standardized digital employee experiences across distributed operations.
United States
Financial services firms in Manhattan and Chicago anchor contract value through trading floor resilience requirements and SEC cybersecurity disclosure mandates. The SEC's incident reporting rules push public companies toward outsourced governance frameworks with documented risk assessment capabilities. Silicon Valley technology clusters accelerate cloud collaboration adoption as hybrid work models normalize persistent distributed operations.
Germany
Automotive manufacturers in Stuttgart and Munich demand shop floor device management integrated with cloud-based collaboration platforms for supply chain coordination. BSI technical guidelines and GDPR enforcement by data protection authorities compel hybrid cloud deployments with strict data residency controls. The Rhine-Ruhr industrial belt concentrates managed services procurement as conglomerates consolidate fragmented IT vendor panels.
India
Multinational shared service centers in Bangalore and Hyderabad import US and German procurement standards for standardized employee experiences across back-office operations. PLI scheme incentives accelerate domestic market expansion for digital workplace platforms serving distributed workforces. Mumbai's financial district drives BFSI adoption of managed desktop and security monitoring services.
United Kingdom
London's insurance sector integrates EU AI Act governance requirements with legacy Lloyd's market infrastructure modernization. The Financial Conduct Authority's operational resilience rules push firms toward managed services with defined uptime thresholds and incident response capabilities. Edinburgh's asset management cluster concentrates cloud collaboration procurement for remote analyst enablement.
Japan
Tokyo's electronics manufacturers balance zero-trust security architectures with legacy shop floor system constraints requiring specialized application management. METI's digital transformation incentives accelerate outsourcing of endpoint detection and identity management capabilities. Osaka's pharmaceutical cluster drives demand for compliant document collaboration platforms with audit trail documentation.
Outsourced Digital Workplace Service Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the consulting-to-operations spectrum, with transformation-grade contracts commanding separate procurement processes from cost-driven maintenance engagements. The vendor base organizes into three tiers: integrated consulting-led platforms, specialized operational efficiency providers, and staff augmentation specialists. Consolidation pressures intensify as enterprise buyers reduce vendor panels toward single-accountability partners. Dominant competitive moves include vertical capability acquisition and outcome-based pricing model adoption.
Within the integrated platform tier, Accenture and HCLTech exemplify divergent archetypes. Accenture leverages its consulting heritage to capture high-margin managed services contracts through transformation-led engagements. HCLTech anchors its position through in-house software stacks and deep sector relationships. Cognizant occupies the price-competitive staff augmentation segment while building specialized practices. These three patterns represent the strategic positioning spectrum available to competitors.
| Leading Market Players |
|---|
| Accenture |
| Atos |
| Capgemini |
| Cognizant |
| DXC Technology |
| Fujitsu |
| HCLTech |
| IBM |
| Kyndryl |
| Others |
Pricing and Supply Chain Analysis
Horizontal integration across hyperscaler partnerships anchors supply positioning and pricing power for outsourced digital workplace providers, with multi-cloud orchestration capabilities commanding premium positioning against single-tenant infrastructure plays. German automotive manufacturers and US financial services firms pay differential rates for identical service tiers based on data residency certification depth and ISO 27001 audit currency.
Pricing Analysis
Outcome-based pricing tied to employee experience metrics and security incident response times anchors contract structures, displacing per-seat arrangements in enterprise procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and vertical specialization depth, with GDPR-compliant managed services in Germany commanding substantial premiums over commodity desktop support. Cost compression in staff augmentation runs through aggressive offshore competition from Indian providers, while zero-trust security monitoring retains pricing resilience. Mid-market buyers in India exhibit highest price sensitivity; regulated BFSI clients in Germany and the United States prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Device refresh and hardware lifecycle management flows through reverse-logistics networks concentrated in Germany, the United States, and India, with refurbishment capabilities reducing net new equipment procurement for sustainability-conscious enterprises. Hyperscaler infrastructure dependencies draw from AWS, Microsoft Azure, and Google Cloud data center footprints, creating single-source vulnerability for multi-tenant service delivery. Supply chain risk centers on cloud infrastructure concentration in Frankfurt, Virginia, and Mumbai regions, where regulatory restrictions on cross-border data flows complicate failover architecture. Distribution runs through direct enterprise sales teams for managed services contracts and channel partners for mid-market standardized offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI copilots and autonomous security response capabilities are displacing legacy service desk and manual threat detection workflows, compressing margins for undifferentiated labor arbitrage while elevating premium pricing for intelligent automation integration.
For Market Incumbents: Anchor market position through in-house AI training data development and vertical-specific workflow customization that pure-play hyperscaler offerings cannot replicate. Consolidate fragmented vendor relationships by acquiring specialized security monitoring boutiques with established EU AI Act compliance documentation. Defend against margin erosion from generative AI commoditization by embedding proprietary IP into outcome-based pricing structures. For New Entrants and Emerging Players: Enter via cloud-native security monitoring for mid-market manufacturing clients in Germany's industrial belt, where legacy application constraints delay incumbent platform transitions. Target India's domestic enterprise segment as PLI scheme incentives accelerate back-office consolidation beyond multinational shared service centers. Pursue channel partnerships with hyperscalers rather than direct enterprise sales to minimize customer acquisition cost exposure. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays by integrated consulting firms seeking managed services attach rates. Long-term viability favors providers with captive AI development capabilities and established governance frameworks for EU AI Act and SEC cybersecurity disclosure compliance. Monitor ISO 27001 certification renewal timelines as inflection indicators for vendor qualification disqualification risk.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified endpoint management with Microsoft 365 and Google Workspace federation reduces vendor fragmentation for multinational clients. |
| Acquisition of Specialist Firm | Security operations boutiques with EU AI Act documentation capabilities command premium multiples from transformation-grade acquirers. |
| Geographic Expansion | India domestic market entry captures PLI scheme tailwinds as manufacturing and BFSI sectors consolidate distributed workforces. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure provide infrastructure scale without capital-intensive data center buildouts. |
| Product Launch | Intelligent automation of threat detection opens new service categories at margin profiles exceeding traditional desktop support. |
Research Methodology
Multi-period observation of contract structure evolution, certification mandate adoption, and vendor consolidation patterns anchored the trend analysis, supplemented by interviews with CTOs at financial services and manufacturing enterprises, IT procurement officers at multinational shared service centers, platform engineers at hyperscaler partners, and integration specialists at systems integrators. Secondary validation drew from SEC cybersecurity disclosure filings, EU AI Act implementation guidance, ISO 27001 certification databases, and hyperscaler capex disclosures. Bottom-up service provider revenue analysis and top-down enterprise IT spending allocation estimates were triangulated to derive market sizing.
Segment-weighting across deployment model, service type, and end-user industry dimensions shaped the analytical framework, with hybrid cloud and security monitoring segments receiving differentiated growth assumptions based on regulatory enforcement intensity. CAGRs were derived from trend extrapolation of contract value and volume indicators across the projection horizon, incorporating EU AI Act compliance cost pass-through assumptions and generative AI productivity impact estimates for service desk operations.
Revisions become necessary when regulatory enforcement timelines accelerate, hyperscaler infrastructure availability constraints materialize, or generative AI capabilities commoditize service desk economics faster than modeled. Practitioners should monitor ISO 27001 audit finding rates, EU AI Act penalty announcement patterns, and hyperscaler data center expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.