
 Global Product Lifecycle Management Market | 2026-2036
Global Product Lifecycle Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Product Lifecycle Management Market Foresight
Mid-sized discrete manufacturers are reorganizing their software procurement around subscription-based platforms with lower capital barriers. Siemens AG leverages its digital twin portfolio to anchor high-complexity aerospace and automotive workflows. Dassault Systèmes SE differentiates through 3D experience platforms that unify design simulation with manufacturing execution. PTC Inc. specializes in IoT-integrated PLM for service lifecycle extensions in heavy equipment sectors.
Product Lifecycle Management encompasses software systems that govern data, processes, and business systems across a product's entire existence, from initial concept through engineering design, manufacturing, service, and disposal, typically operating through centralized data vaults with version control, workflow automation, and multi-CAD interoperability. Cloud-based and SaaS deployment models are capturing the fastest expansion as manufacturers seek elastic compute for global supplier coordination without fixed infrastructure commitments. Collaborative design and change management solutions command disproportionate margin pools because they sit at the intersection of engineering rework avoidance and regulatory audit trails.
The U.S. FDA's 21 CFR Part 11 electronic records requirements, the EU's CE marking and MDR traceability mandates, and Japan's METI-guided Smart Manufacturing standards collectively elevate PLM from optional efficiency tool to compliance infrastructure. China's GB standards and NMPA medical device regulations further tighten product data retention and revision tracking obligations for manufacturers selling into those jurisdictions. Stakeholders must weigh sovereign cloud requirements against the interoperability gains of multi-tenant platforms when architecting their next deployment cycles.
Market Dynamics
Cloud-native PLM architectures are compressing deployment cycles from eighteen months to under ninety days, forcing incumbent vendors to restructure their professional services revenue models around subscription retention rather than perpetual license maintenance.
Growth Catalysts
- Digital Thread Mandates:Aerospace primes in Wichita, Toulouse, and Hamburg now require tier-one suppliers to maintain federated data models linking engineering BOMs to shop-floor execution systems.
- EU MDR Traceability:Medical device manufacturers must maintain complete design history files accessible to notified bodies, elevating PLM from efficiency tool to compliance infrastructure.
- AI-Assisted Design Validation:Machine learning algorithms embedded in PLM workflows are compressing simulation cycles for automotive crash testing and thermal management.
Market Restraints
- Data Sovereignty Fragmentation:Germany's BSI IT-Grundschutz requirements, Japan's APPI amendments, and US CLOUD Act jurisdictional conflicts force multi-region infrastructure duplication.
- Legacy System Entrenchment:Discrete manufacturers in industrial machinery retain twenty-year-old PLM installations with custom API layers that resist cloud migration.
- Specialized Talent Scarcity:Systems integrators capable of configuring Aras, Siemens Teamcenter, and Dassault ENOVIA simultaneously command premium rates exceeding standard IT consulting by forty percent.
Strategic Opportunities
- SMB Cloud Penetration:Mid-sized automotive suppliers in Stuttgart and Detroit remain underserved by current PLM pricing tiers, creating whitespace for modular SaaS entry.
- Service Lifecycle Extension:Heavy equipment OEMs are attaching PLM data to field service management platforms, monetizing post-sale parts and retrofit engineering.
- Battery Passport Compliance:EU Battery Regulation digital product passport requirements will mandate PLM integration for cell manufacturers and pack assemblers by 2027.
Industry Challenges
- CAD Data Migration Complexity:Converting proprietary legacy CAD formats to modern neutral standards without geometric integrity loss consumes twelve to eighteen months for complex assemblies.
- Cross-Functional Alignment:Engineering, manufacturing, and quality teams maintain conflicting data governance priorities that stall PLM governance committee decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Product Lifecycle Management Market |
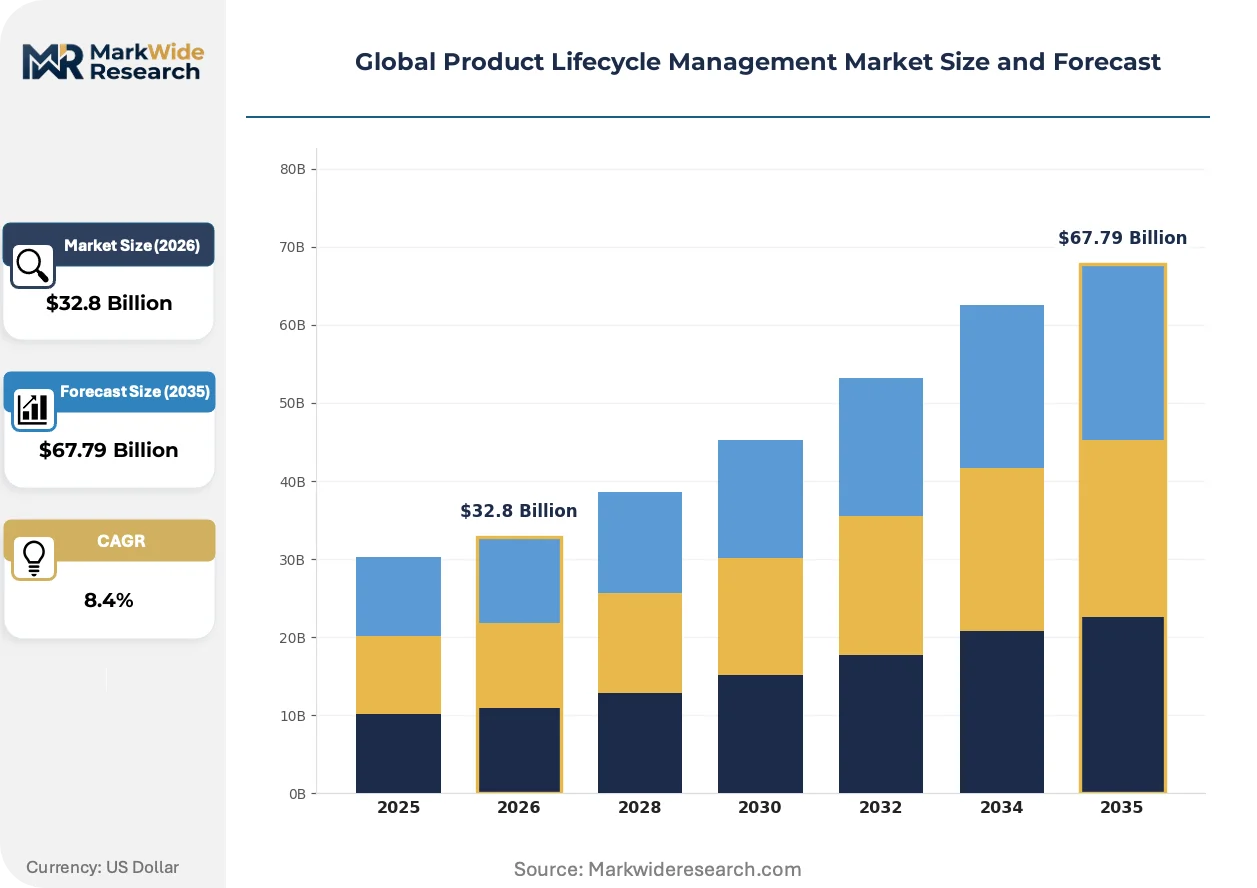
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS, Private Cloud Solution Type: Collaborative Design, Process Management, Quality Management, Compliance Management, Change Management Application: New Product Development, Product Data Management, Supplier Collaboration, Service Lifecycle Management, Production Planning End User Industry: Manufacturing OEMs, Aerospace Vendors, Consumer Electronics Producers, Heavy Equipment Assemblers, Consumer Goods Firms |
| Companies Covered | Siemens AG, Dassault Systèmes SE, PTC Inc., Autodesk, Inc., SAP SE, Oracle Corporation, IBM Corporation, Infor, Inc., Aras Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Product Lifecycle Management Market Shifts & Advancements
Generative design algorithms and sovereign cloud requirements are simultaneously expanding computational demands and constraining where data may physically reside, reshaping vendor infrastructure strategies.
Model-based systems engineering (MBSE) is displacing document-centric requirements management in defense and aerospace programs. Lockheed Martin and Northrop Grumman suppliers now deliver digital thread artifacts rather than static specifications. This shift compresses design review cycles and eliminates transcription errors between systems engineering and mechanical design teams.
REACH substance restriction updates and EU CSRD scope expansions are forcing PLM vendors to embed materials compliance screening directly into design workflows. Product stewards in chemical and consumer goods sectors now receive automated alerts when restricted substances appear in supplier component libraries, preventing late-stage redesigns that previously cost millions in delayed launches.
Subscription-based platform procurement is replacing capital-intensive on-premise deployments among discrete manufacturers with revenues between fifty million and five hundred million dollars. These buyers now prioritize API extensibility and pre-configured industry templates over customization depth. The pattern is most pronounced in German automotive supply chains, where OEMs are pushing compliance costs downstream to tier-two and tier-three vendors.
Global Product Lifecycle Management Market Segmentation
PLM procurement patterns diverge sharply across deployment architectures and solution types, with compliance mandates and supply chain digitization forcing heterogeneous technology stacks even within single enterprises. Understanding segment substitution pressures reveals where vendors face commoditization risk versus sustainable differentiation.
Deployment:
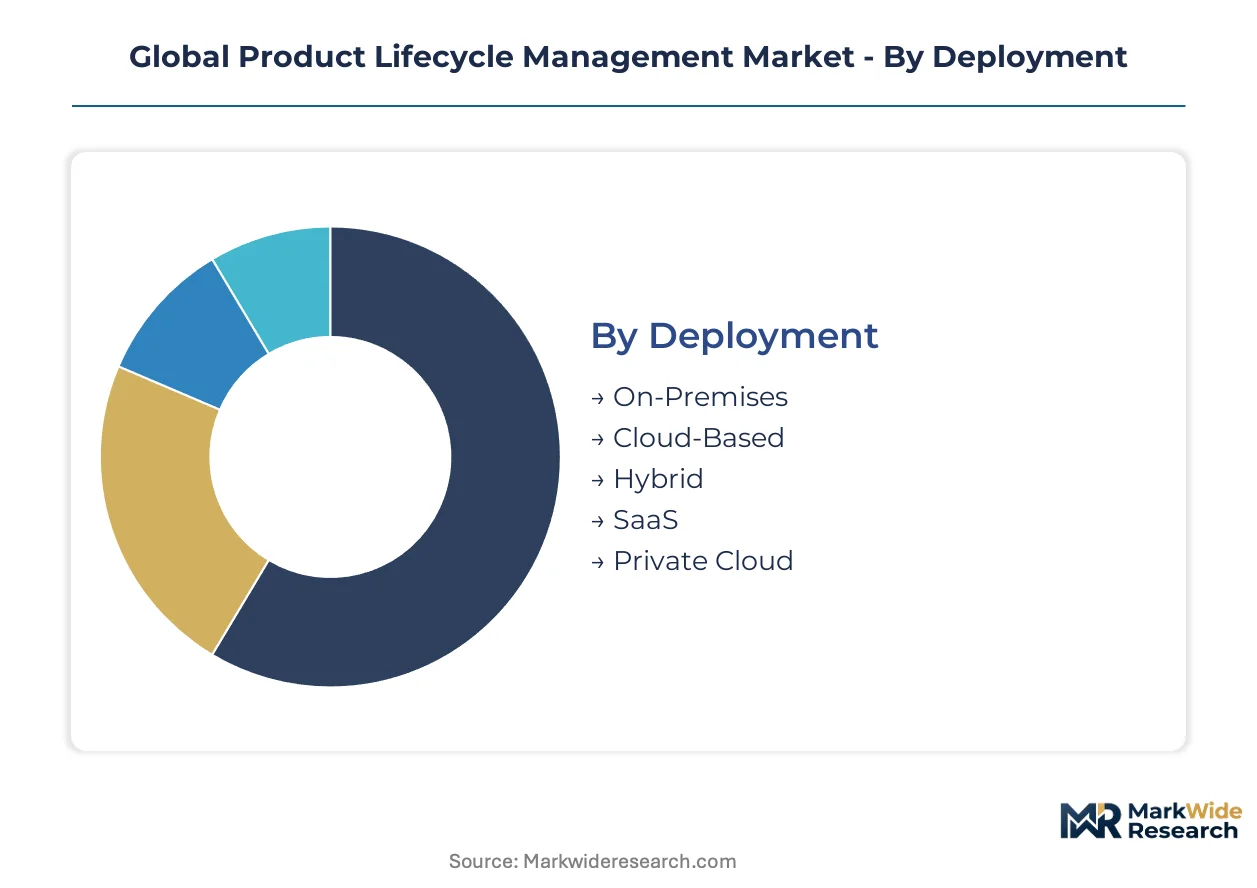
Cloud-native substitutes threaten legacy on-premises installations most acutely in mid-market accounts, while data sovereignty requirements preserve hybrid architectures in regulated sectors.
- Cloud-Based:Multi-tenant architectures with elastic compute provisioning dominate new procurement among automotive suppliers in Stuttgart and Detroit seeking supplier coordination without fixed infrastructure. German automotive OEMs now mandate cloud data residency within EU sovereign zones, compressing vendor infrastructure strategies.
- SaaS:Subscription platforms with pre-configured industry templates capture fastest expansion among discrete manufacturers with revenues between fifty million and five hundred million dollars. These buyers prioritize API extensibility over customization depth, displacing perpetual license models.
- On-Premises:Legacy installations with custom API layers persist in industrial machinery sectors where twenty-year system entrenchment resists migration.
- Hybrid:Split architectures satisfy Japanese APPI amendments and US CLOUD Act jurisdictional conflicts through multi-region data segregation.
- Private Cloud:Single-tenant dedicated instances address BSI IT-Grundschutz requirements for defense and medical device manufacturers in Germany.
On-Premises retains volume leadership; SaaS holds the steepest expansion curve.
Solution Type:
Margin concentration follows regulatory audit trail intensity, with compliance modules commanding premium pricing against commoditized design tools.
- Compliance Management:Embedded FDA 21 CFR Part 11, EU MDR traceability, and China NMPA retention workflows transform PLM from efficiency tool to mandatory infrastructure. Medical device manufacturers in Massachusetts and Bavaria now treat these capabilities as non-negotiable procurement criteria.
- Change Management:Federated data models linking engineering BOMs to shop-floor execution systems sit at the intersection of rework avoidance and regulatory documentation. Aerospace primes in Wichita, Toulouse, and Hamburg require tier-one suppliers to maintain these digital thread artifacts.
- Collaborative Design:Multi-CAD interoperability and version control face substitution pressure from standalone CAD vendor platforms.
- Quality Management:CAPA workflows and non-conformance tracking integrate with MES layers for closed-loop manufacturing.
- Process Management:Workflow automation for document routing and approval cycles competes with generic BPM platforms.
Change Management captures the highest margin pool; Compliance Management is climbing fastest on regulatory tailwinds.
Application:
Service lifecycle extensions create new revenue pools previously outside PLM scope, while supplier collaboration faces ERP vendor encroachment.
- Service Lifecycle Management:Field service management integration for post-sale parts and retrofit engineering monetizes installed base data. Heavy equipment OEMs in Peoria and Kawasaki attach PLM records to service platforms, generating recurring revenue streams.
- Supplier Collaboration:Federated BOM sharing and design review workflows concentrate demand in German automotive supply chains where OEMs push compliance costs downstream. Tier-two and tier-three vendors in Baden-Württemberg and Lower Saxony represent underserved whitespace.
- New Product Development:Requirements management and concept-to-launch workflows face competition from specialized stage-gate software.
- Product Data Management:Centralized vaults with revision control remain foundational but face margin compression.
- Production Planning:Integration with MES and ERP systems blurs functional boundaries with manufacturing operations software.
Product Data Management anchors volume; Service Lifecycle Management expands most quickly as OEMs pursue aftermarket monetization.
End User Industry:
Technology requirements diverge by product complexity and regulatory exposure, with aerospace and medical device demands pulling capabilities ahead of mainstream manufacturing.
- Aerospace Vendors:Model-based systems engineering and digital thread mandates from Lockheed Martin and Northrop Grumman suppliers displace document-centric specifications. MBSE artifacts now replace static requirements documents in Wichita and Hamburg supply chains.
- Manufacturing OEMs:Discrete producers of industrial machinery in Ohio and Baden-Württemberg retain legacy entrenchment with custom API layers resisting cloud migration, creating vendor lock-in and integration service opportunities.
- Consumer Electronics Producers:Rapid design cycles and global supplier coordination favor cloud-native platforms with elastic compute.
- Heavy Equipment Assemblers:Long product lifecycles and aftermarket service monetization prioritize service lifecycle management integration.
- Consumer Goods Firms:REACH substance screening and EU CSRD scope expansions drive materials compliance workflow adoption among chemical and consumer product stewards.
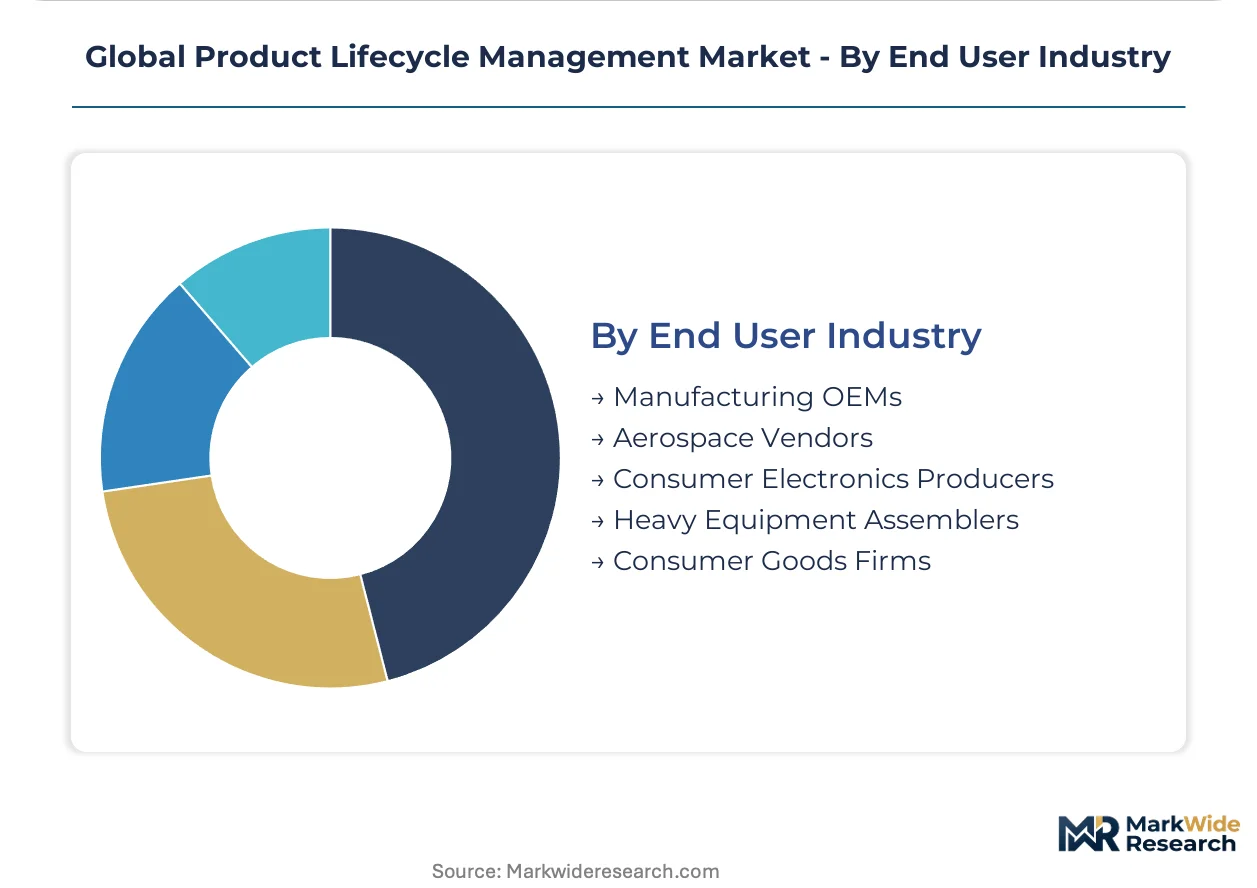
Manufacturing OEMs retain volume leadership; Aerospace Vendors hold the steepest capability advancement trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German PLM vendors export cloud-native platforms to automotive supply chains in Detroit and Stuttgart, while Japanese industrial software flows into Southeast Asian manufacturing hubs.
United States
Aerospace primes in Wichita and defense contractors near Washington DC drive digital thread mandates for federated data models. FDA 21 CFR Part 11 electronic records requirements elevate PLM from efficiency tool to compliance infrastructure for medical device manufacturers in Massachusetts.
Germany
Automotive OEMs in Munich and Stuttgart anchor the largest implementation clusters for subscription-based platforms. BSI IT-Grundschutz requirements preserve private cloud architectures for defense and medical device manufacturers in Bavaria.
China
Domestic battery cell manufacturers and EV assemblers adopt PLM systems to satisfy GB standards and NMPA medical device regulations. Yangtze River Delta industrial corridors concentrate demand for supplier coordination platforms.
Japan
Heavy equipment OEMs in Kawasaki and precision machinery builders in Nagoya prioritize service lifecycle management for aftermarket monetization. METI-guided Smart Manufacturing standards tighten product data retention obligations.
India
Mid-sized automotive suppliers in Pune and Chennai represent underserved whitespace for modular SaaS entry. PLI scheme incentives accelerate domestic manufacturing digitization across tier-two vendor networks.
Global Product Lifecycle Management Market Competitive Landscape
Listed leaders compete with private specialists across deployment architecture and industry vertical depth. The vendor base stratifies into three tiers: diversified technology conglomerates with broad platform portfolios, pure-play PLM specialists with deep CAD integration, and emerging cloud-native challengers attacking mid-market price points. Dominant competitive moves include vertical integration into adjacent manufacturing execution systems and strategic partnerships with hyperscale cloud providers for sovereign data residency.
Within the diversified conglomerate tier, Siemens AG and Dassault Systèmes SE occupy positions as anchors for high-complexity aerospace and automotive workflows. PTC Inc. exemplifies the IoT-integrated specialist archetype targeting service lifecycle extensions. These three represent distinct strategic postures: European industrial software heritage, 3D experience platform unification, and connected product data monetization respectively.
| Leading Market Players |
|---|
| Siemens AG |
| Dassault Systèmes SE |
| PTC Inc. |
| Autodesk, Inc. |
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| Infor, Inc. |
| Aras Corporation |
| Others |
Supply & Pricing Matrix
Ninety-day deployment cycles for cloud-native PLM architectures concentrate pricing power with vendors possessing elastic sovereign infrastructure, while legacy on-premises entrenchment in German machinery corridors preserves premium maintenance revenue streams for incumbents.
Pricing Analysis
Cloud-native versus legacy on-premises versus hybrid private cloud pricing gaps now span three distinct technology generations. Subscription-based SaaS tiers dominate new procurement, with price differentiation resting on data residency certification levels and API extensibility depth. Pricing pressure stems from mid-market buyers in Stuttgart and Detroit prioritizing pre-configured templates over customization. Tier-two automotive suppliers exhibit highest price sensitivity; aerospace primes with digital thread mandates show lowest.
Supply Chain Analysis
Hyperscale cloud region availability in Frankfurt, Tokyo, and Virginia underwrites PLM vendor infrastructure strategies for regulated deployments. Software development concentrates in Germany, the United States, and France; data center capacity draws from regional hyperscaler partnerships. Supply chain risk centers on single-source vulnerability for sovereign cloud certification compliance. Distribution runs through systems integrators commanding forty percent premiums for multi-platform configuration expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PLM adoption sits in early-cycle expansion as battery passport mandates and EU MDR traceability requirements convert discretionary efficiency tools into compulsory compliance infrastructure across automotive and medical device supply chains.
For Market Incumbents: Compound platform stickiness through embedded AI-assisted design validation workflows and backward integration into manufacturing execution systems. Cloud-native challengers threaten maintenance revenue in mid-market accounts; defend through sovereign cloud certification investments in German BSI-compliant zones. For New Entrants and Emerging Players: FDA 21 CFR Part 11 fast-track certification unlocks medical device manufacturer procurement in Massachusetts and Bavaria. White-space concentrates in tier-three automotive suppliers across Baden-Württemberg and Detroit lacking digital thread readiness. Go-to-market through OEM-mandated supplier compliance programs accelerates land-and-expand cycles. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because regulatory audit trail mandates embed PLM into customer operating expenditure rather than discretionary capital budgets. Acquisition targets should display multi-CAD interoperability depth and existing aerospace tier-one supplier relationships. Watch EU Battery Regulation enforcement timing as inflection indicator for cell manufacturer PLM procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies PLM data with MES layers for closed-loop manufacturing in Hamburg aerospace clusters. |
| Strategic Partnership | Hyperscaler alliances enable sovereign cloud residency for German BSI IT-Grundschutz compliance. |
| Acquisition of Specialist Firm | MBSE tooling targets Lockheed Martin and Northrop Grumman supplier digital thread mandates. |
| Geographic Expansion | Modular SaaS entry captures underserved tier-two automotive suppliers in Pune and Chennai. |
| Product Launch | Battery passport modules address EU Regulation digital product passport requirements for cell manufacturers. |
Research Methodology
The analysis maps cloud deployment architectures, compliance management modules, and service lifecycle extensions, each validated through CTOs at discrete manufacturers, PLM implementation leads at systems integrators, and procurement officers at automotive OEMs. Primary fieldwork combined with secondary validation against SEC 10-K filings, hyperscaler infrastructure capex disclosures, and EU regulatory mandate documentation. Bottom-up vendor revenue triangulation against top-down industry spend estimates anchored segmentation sizing.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include deployment model, organization revenue tier, vertical industry, and integration complexity with adjacent manufacturing systems. CAGRs derived from fitted growth curves incorporating digital thread mandate adoption curves and regulatory compliance deadline clustering. Industry-specific inputs encompassed aerospace prime supplier qualification timelines and medical device FDA submission velocity.
Decision-makers should treat outputs as directional under sustained regulatory enforcement of EU MDR and Battery Regulation timelines; material deviation in compliance deadline extensions or sovereign cloud standard fragmentation would warrant model refresh. Practitioners should keep alternative scenarios live as AI-assisted design validation penetration and generative algorithm embedding rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mobile Tracking Solution Market
Digital Solutions
Marketing Automation Market
Digital Solutions
Product Engineering Services Market
Digital Solutions
North America Everything As a Service (Xaas) Market
Digital Solutions
Global Interactive Whiteboard (IWB) Market
Digital Solutions
Germany Digital Twin Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
Context Rich Systems Market
Digital Solutions
Communication Intelligence Market
Digital Solutions
Digital Manufacturing Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
Global DDI Market
Digital Solutions
Middle East Smart Card Market