
 Global Media (Video) Processing Solutions Market | 2026-2036
Global Media (Video) Processing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Media (Video) Processing Solutions Market Foresight
Multi-source vendor strategies for video transcoding infrastructure is shifting as broadcasters and streaming services diversify beyond single-platform dependencies. Akamai Technologies, Inc. leverages its edge computing footprint to reduce latency for live video delivery. Harmonic Inc. anchors its position through software-based cloud-native solutions that replace legacy hardware deployments. Amazon Web Services, Inc. dominates cloud-based processing capacity with elastic scaling for peak viewership events.
Global Media (Video) Processing Solutions encompass hardware and software systems that encode, transcode, multiplex, and stream video content across IP networks, typically supporting H.264, H.265, AV1, and emerging VVC codecs with resolutions up to 8K at 120 frames per second. These systems serve broadcasters, telecom operators, and streaming services by compressing raw video into distribution-ready formats while preserving visual fidelity and minimizing bandwidth consumption. Cloud-based technology leads deployment models as enterprises abandon capital-intensive on-premise installations for operational expenditure models. AI-powered processing represents the fastest-expanding technology segment, with machine learning algorithms optimizing encoding parameters in real time to reduce bitrates without perceptible quality loss. Transcoders occupy the central margin pool within product types, since every multi-format distribution workflow requires format conversion at scale.
The Federal Communications Commission shapes US market access through net neutrality frameworks that affect how video traffic traverses ISP networks, while the European Union's GDPR and Digital Services Act impose data handling and content moderation obligations on platforms processing EU viewer streams. China's MIIT enforces GB standards for video compression and transmission security that foreign vendors must satisfy for market participation. Stakeholders must monitor evolving codec royalty structures and sovereign data localization mandates as these forces determine which processing architectures achieve regulatory clearance in priority markets.
Market Dynamics
The migration from hardware-based transcoding appliances to cloud-native software pipelines is compressing capital requirements while elastic scaling demands reshape procurement patterns across broadcast and streaming operations.
Growth Catalysts
- AI-powered encoding optimization:Machine learning algorithms dynamically adjust quantization parameters during live streams, reducing bandwidth consumption for 4K and 8K delivery without perceptible quality degradation.
- India's direct-to-consumer video expansion:Telecom operators and regional streaming platforms are deploying edge processing nodes to serve fragmented language markets with localized content delivery.
- FCC net neutrality frameworks:Regulatory clarity on video traffic prioritization enables ISPs to invest in dedicated streaming infrastructure without litigation exposure.
Market Restraints
- Codec royalty stacking:Patent pools for H.265, AV1, and emerging VVC standards impose cumulative licensing costs that squeeze margins for transcoding hardware vendors.
- Cloud concentration risk:Hyperscaler dominance in elastic compute creates single-platform dependency for mid-tier streaming services lacking multi-cloud orchestration capabilities.
- Edge node deployment friction:Physical infrastructure requirements for sub-50ms latency delivery limit rural and emerging market penetration where fiber backhaul remains sparse.
Strategic Opportunities
- Underpenetrated live sports vertical:Regional leagues in Brazil and Saudi Arabia lack broadcast-grade streaming infrastructure, creating whitespace for real-time processing deployments.
- EU Digital Services Act compliance tooling:Content moderation and traceability mandates for live streams create demand for integrated processing pipelines with automated metadata tagging.
- Convergence of 5G broadcast and streaming:3GPP Release 17 specifications enable hybrid multicast-unicast delivery, requiring new processing architectures that bridge cellular and IP networks.
Industry Challenges
- Codec engineering talent scarcity:Deep expertise in entropy coding and perceptual optimization resides with a narrow cohort of specialists concentrated in South Korea and the United States.
- Legacy SDI integration complexity:Broadcast facilities maintain substantial baseband infrastructure, forcing hybrid processing workflows that increase operational overhead and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Media (Video) Processing Solutions Market |
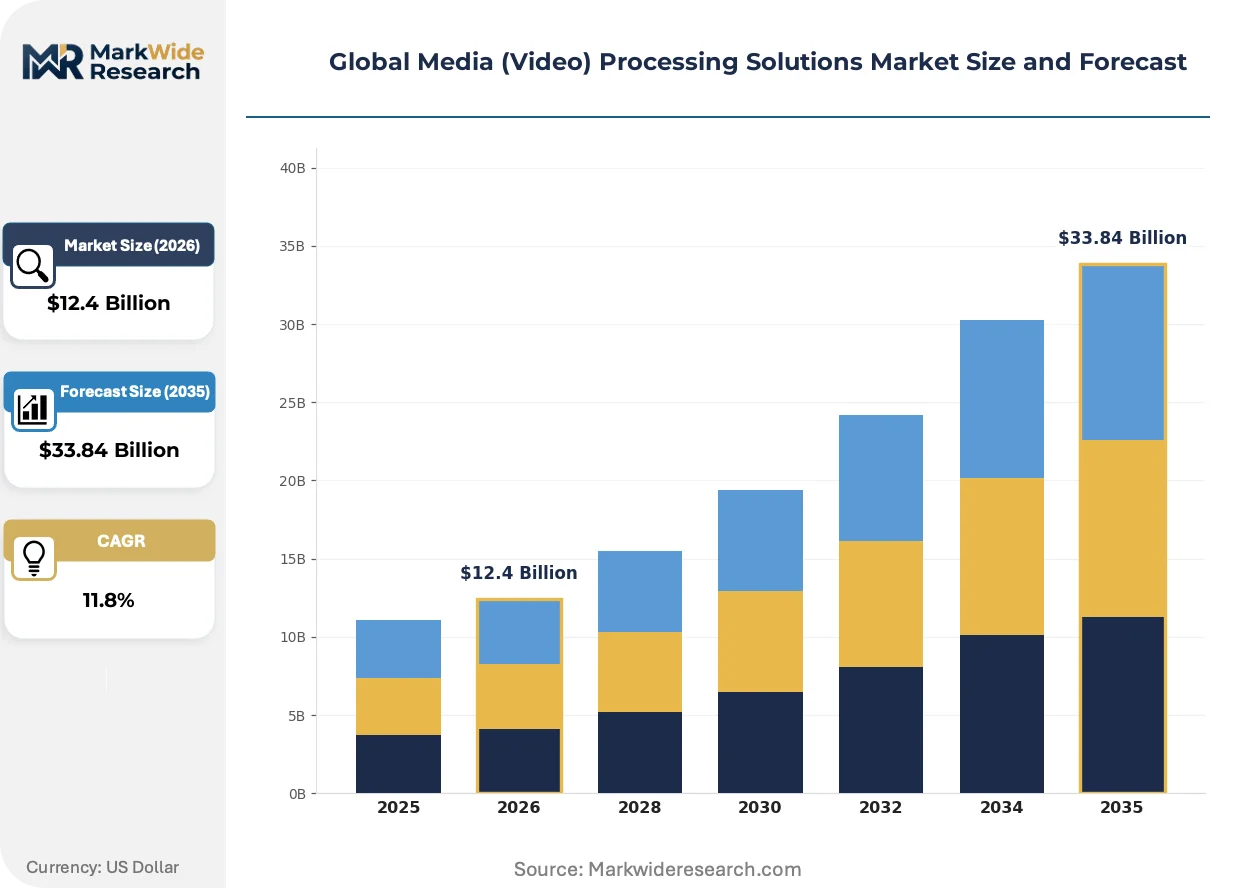
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $33.84 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Encoders, Decoders, Transcoders, Multiplexers, Streamers, Processors Technology: Hardware-Based, Software-Based, Cloud-Based, Edge Computing, AI-Powered, FPGA-Based Application: Broadcasting, Video Surveillance, Content Delivery Networks, Video Conferencing, OTT Platforms, Digital Signage End User: Telecom Operators, Content Providers, Streaming Services, Post-Production Studios, Educational Institutes, Advertising Agencies |
| Companies Covered | Amazon Web Services, Inc., Akamai Technologies, Inc., Ateme SA, Telestream, LLC, Kaltura, Inc., Harmonic Inc., M2A Media Ltd., Imagine Communications Corp., MediaKind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Media (Video) Processing Solutions Market Shifts & Advancements
Real-time streaming infrastructure is undergoing architectural transformation as latency requirements tighten and processing migrates toward network edges, reshaping vendor competitive positioning across hardware and software domains.
Per-title encoding powered by neural network analysis is expanding into live sports and gaming broadcasts where scene complexity varies dramatically frame-to-frame. Broadcasters in Germany and Japan are deploying these systems for marquee events. The technology is expanding into premium tier workflows by compressing bitrates twenty to forty percent below fixed-quantization baselines without viewer-perceptible artifacts.
China's MIIT enforcement of GB/T 41818-2022 streaming security standards mandates domestic encryption modules and audit logging for foreign-sourced processing equipment. Vendors must redesign firmware architectures to satisfy these requirements. Equipment shipments to Chinese streaming platforms now face extended certification timelines that compress competitive windows for non-compliant suppliers.
Usage-based pricing for transcoding capacity is displacing committed-use contracts among mid-market streaming services. Platforms in India and Southeast Asia prefer operational expenditure models that scale with viewership spikes. This pattern concentrates purchasing power with cloud-native vendors offering granular billing and automated burst scaling.
Global Media (Video) Processing Solutions Market Segmentation
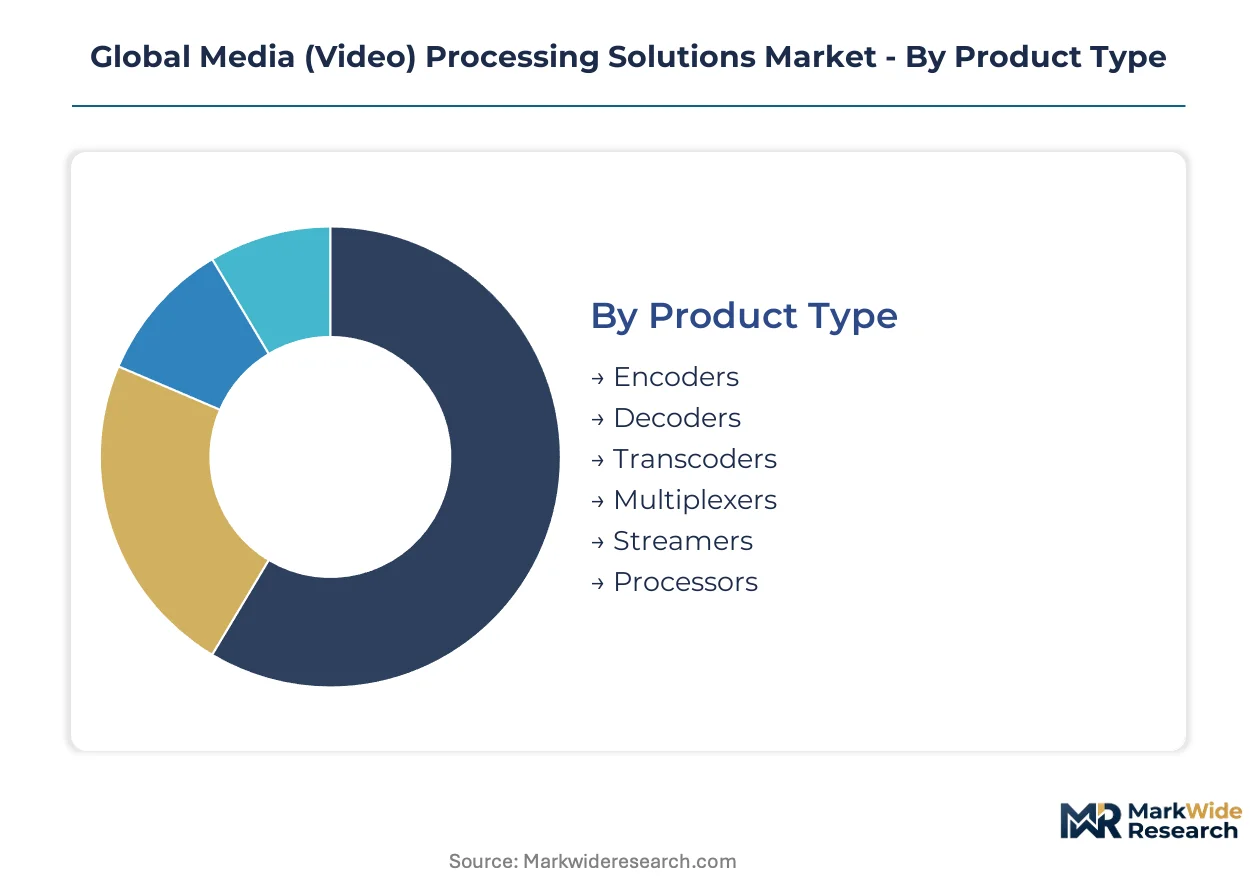
Video processing solutions fragment across multiple technical and commercial dimensions, with each segmentation axis revealing distinct procurement patterns and margin structures. Buyers prioritize different performance attributes depending on their distribution scale, latency requirements, and legacy infrastructure exposure.
Product Type:
Equipment selection hinges on where operators sit in the content distribution chain and their format conversion intensity.
- Transcoders:These systems convert between compression formats and bitrates to enable multi-platform distribution from a single source feed. Broadcasters in Germany and Japan deploy them for simultaneous HD and 4K output streams. Demand concentrates among streaming services managing fragmented device ecosystems where H.264, H.265, and AV1 coexist.
- Encoders:Raw video compression engines that ingest uncompressed baseband signals and output distribution-ready streams. Live sports broadcasters in Brazil require sub-frame latency variants for real-time wagering integration. Telecom operators in India favor software-defined encoders that scale elastically during cricket viewership spikes.
- Decoders:Reverse compression systems for monitoring, quality control, and headend signal verification.
- Multiplexers:Stream aggregation equipment combining multiple program feeds into single transport streams.
- Streamers:Origin servers and packetizers for IP network delivery.
- Processors:Signal manipulation systems handling frame rate conversion, resolution scaling, and color space transformation.
Transcoders lead volumes today; AI-powered encoder variants are gaining share fastest.
Technology:
Deployment architecture determines capital intensity and operational flexibility across broadcast and streaming operations.
- Cloud-Based:Virtualized processing instances running on hyperscaler infrastructure with elastic scaling for peak events. Streaming services in India and Southeast Asia prefer operational expenditure models that align costs with viewership. Mid-tier platforms lacking multi-cloud orchestration face concentration risk with single-vendor dependency.
- AI-Powered:Machine learning algorithms optimize encoding parameters frame-by-frame to reduce bandwidth without perceptible quality loss. Per-title encoding systems in Germany and Japan compress bitrates twenty to forty percent below fixed baselines for premium tier workflows. Post-production studios adopt these for archival remastering where storage costs dominate.
- Hardware-Based:Dedicated appliance deployments in facilities requiring deterministic latency.
- Software-Based:On-premise virtualized solutions replacing legacy hardware in broadcast facilities.
- Edge Computing:Distributed processing nodes positioned close to viewers for sub-50ms delivery.
- FPGA-Based:Field-programmable gate arrays for specialized acceleration of entropy coding operations.
Cloud-based deployments dominate new procurement; AI-powered systems are expanding most quickly into live workflows.
Application:
Use case requirements vary dramatically in latency tolerance, scale elasticity, and quality thresholds.
- OTT Platforms:Direct-to-consumer streaming services requiring adaptive bitrate delivery across unmanaged internet connections. Regional platforms in India deploy edge processing nodes to serve fragmented language markets with localized content. FCC net neutrality frameworks shape how these operators negotiate traffic prioritization with ISPs.
- Broadcasting:Traditional linear television distribution with strict regulatory compliance and failover requirements. Legacy SDI integration complexity forces hybrid workflows that increase operational overhead. China's MIIT enforces GB/T 41818-2022 security standards that extend certification timelines for foreign equipment.
- Video Surveillance:Security and monitoring applications with storage-optimized compression priorities.
- Content Delivery Networks:Cache and origin infrastructure for geographically distributed streaming.
- Video Conferencing:Real-time communication with ultra-low latency requirements.
- Digital Signage:Scheduled playback systems with relaxed latency tolerances.
OTT platforms anchor current demand; broadcasting applications are seeing steepest technology refresh cycles.
End User:
Procurement sophistication and technical requirements diverge sharply across customer categories.
- Streaming Services:Pure-play digital platforms without legacy infrastructure burdens. Usage-based pricing for transcoding capacity is displacing committed-use contracts among mid-market operators. These buyers prioritize granular billing and automated burst scaling during tentpole content releases.
- Telecom Operators:Converged carriers offering bundled video, broadband, and mobile services. India's direct-to-consumer expansion drives edge node deployment for last-mile optimization. These entities negotiate wholesale content deals that require processing capacity guarantees.
- Content Providers:Studios and rights holders managing original production libraries.
- Post-Production Studios:Facilities handling color grading, visual effects, and mastering workflows.
- Educational Institutes:Institutions deploying lecture capture and remote learning infrastructure.
- Advertising Agencies:Creative shops producing campaign video for multi-platform distribution.
Telecom operators lead procurement volumes today; streaming services are climbing the fastest as cord-cutting accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors video processing innovation through hyperscaler engineering centers and venture-backed codec startups. Regional demand concentrates in the United States, China, India, Germany, and Brazil as these markets scale direct-to-consumer streaming infrastructure and modernize broadcast facilities.
United States
OTT platforms and broadcasters drive demand for elastic transcoding capacity during tentpole sporting events. The FCC's net neutrality frameworks shape how streaming services negotiate traffic prioritization agreements with ISPs. Los Angeles and New York media clusters host post-production studios deploying AI-powered per-title encoding for archival remastering workflows.
China
Domestic streaming giants and telecom operators require processing equipment compliant with sovereign security mandates. MIIT enforcement of GB/T 41818-2022 standards mandates domestic encryption modules and audit logging for foreign-sourced equipment. Beijing and Shenzhen technology corridors concentrate firmware engineering teams redesigning architectures for extended certification timelines.
India
Regional streaming platforms and telecom operators deploy edge processing nodes to serve fragmented language markets with localized content delivery. TRAI regulations on net neutrality and content pricing influence infrastructure investment patterns. Mumbai and Bangalore clusters concentrate software development for cloud-native transcoding solutions serving cricket viewership spikes.
Germany
Public broadcasters and commercial streaming services invest in real-time processing for live sports and cultural programming. GDPR and the EU Digital Services Act impose data handling and content moderation obligations on platforms processing viewer streams. Munich and Berlin engineering centers specialize in per-title encoding systems for premium tier workflows.
Brazil
Regional sports leagues and telecom operators seek broadcast-grade streaming infrastructure for real-time wagering integration. ANVISA and national telecommunications regulators shape equipment certification requirements for imported processing hardware. São Paulo media clusters concentrate system integrators bridging legacy SDI infrastructure with IP-based delivery networks.
Global Media (Video) Processing Solutions Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-native and AI-optimized processing architectures. The market structures around three tiers: hyperscaler cloud platforms with elastic compute capacity, specialized transcoding vendors with codec expertise, and regional system integrators serving legacy broadcast transitions. Dominant competitive moves include strategic partnerships between cloud providers and broadcast technology vendors, plus portfolio diversification into adjacent content moderation and metadata tagging services.
Within the hyperscaler tier, Amazon Web Services, Inc. exemplifies scale-driven positioning through virtualized processing instances with automated burst scaling capabilities. Among specialized codec vendors, Harmonic Inc. and Ateme SA occupy positions emphasizing software-defined and cloud-native solution architectures. Akamai Technologies, Inc. represents the edge computing archetype, anchoring distributed processing strategies for latency-sensitive live delivery workflows.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Akamai Technologies, Inc. |
| Ateme SA |
| Telestream, LLC |
| Kaltura, Inc. |
| Harmonic Inc. |
| M2A Media Ltd. |
| Imagine Communications Corp. |
| MediaKind |
| Others |
Supply & Pricing Matrix
Mid-tier streaming services in India and Southeast Asia now dominate procurement volumes, forcing vendors toward usage-based SaaS tiers that eliminate committed-use contracts and compress margin structures across the transcoding stack.
Pricing Analysis
Input-cost pass-through from FPGA chip shortages and codec patent pool royalties is intensifying margin pressure on hardware appliance vendors. Three-tier pricing structure across premium, standard, and economy levels separates hyperscaler-integrated solutions from regional system integrators and open-source alternatives. Price differentiation hinges on certification grade for China's MIIT GB/T 41818-2022 compliance and volume scale during cricket or tentpole sporting events. Margins are tightening due to cloud-native competitors offering granular billing granularity that legacy hardware vendors cannot match. Telecom operators exhibit highest price sensitivity given wholesale content deal structures; post-production studios in Los Angeles and New York show lowest sensitivity where storage cost reductions from AI-powered encoding justify premium positioning.
Supply Chain Analysis
China's MIIT enforcement of domestic encryption modules and India's phased manufacturing programs are reshaping component sourcing for foreign vendors seeking market access. Manufacturing concentrates in China, Taiwan, and South Korea for specialized entropy coding ASICs and high-throughput networking silicon. Raw material dependencies span gallium nitride substrates for RF components, high-bandwidth memory stacks for AI inference acceleration, and precision optics for fiber backhaul termination. Supply chain risk centers on single-source vulnerability for advanced codec IP cores concentrated among South Korean and US engineering cohorts. Distribution runs through hyperscaler marketplaces and regional system integrators serving legacy broadcast transitions in Brazil and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Digital Services Act's live-stream content moderation mandates are compounding demand for integrated processing pipelines, making regulatory compliance tooling a structural demand driver across the analysis window.
For Market Incumbents: Hedge against hyperscaler encroachment by deepening firmware certification investments for China's GB/T 41818-2022 and India's emerging security frameworks. Anchor margin position through backward integration into AI inference silicon design, reducing dependency on external GPU supply. Acquire edge-native transcoding startups before cloud providers integrate their latency-optimized architectures into bundled offerings. For New Entrants and Emerging Players: Regional sports leagues in Brazil and Saudi Arabia offer the most penetrable whitespace, lacking broadcast-grade infrastructure for real-time wagering integration. Cloud-native vendors should target telecom operators in India seeking elastic scaling without multi-cloud orchestration capabilities. Partner with system integrators bridging legacy SDI facilities to IP networks rather than competing head-on with hyperscaler scale. For Investors and Strategic Acquirers: Hyperscaler cloud divisions are the most active acquirer in this space, seeking codec expertise to differentiate transcoding APIs from commodity compute. Long-term viability favors vendors with sovereign compliance certifications across three-plus regulatory jurisdictions. Watch for MIIT certification timeline compression as the inflection signal—vendors achieving faster Chinese market entry will capture disproportionate share in the world's largest streaming market.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Encoding Optimization | Machine learning algorithms reduce bandwidth consumption for 4K and 8K delivery without perceptible quality degradation. |
| Edge Computing Infrastructure Deployment | Akamai Technologies leverages distributed nodes for sub-50ms latency delivery to regional streaming platforms. |
| Regulatory Compliance Certification | MIIT GB/T 41818-2022 compliance extends competitive windows for foreign vendors redesigning firmware architectures. |
| Cloud-Native Software Transition | Harmonic Inc. replaces legacy hardware deployments with elastic scaling for peak cricket viewership events in India. |
| Strategic Hyperscaler Partnership | Amazon Web Services dominates processing capacity with automated burst scaling during tentpole sporting events. |
Research Methodology
Direct dialogue with CTOs at streaming platforms, broadcast technology procurement leads, telecom network planning officers, and post-production facility engineers grounded the qualitative foundation. Secondary validation drew from FCC net neutrality filings, MIIT GB standard publications, EU Digital Services Act implementation guidance, and hyperscaler capex disclosures. Bottom-up and top-down triangulation cross-referenced vendor shipment data with enterprise software spending patterns across the analysis window.
Segment-level outputs trace product type, deployment technology, application vertical, and end-user sophistication across the projection horizon. The analytical framework models elastic scaling coefficients for live sports viewership spikes, sovereign certification timeline impacts, and codec royalty stacking effects on vendor margins. CAGRs derive from regression against streaming subscriber growth curves and broadcast facility modernization cycles, with AI-powered processing penetration serving as the primary growth acceleration input.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to VVC codec adoption timelines and 5G broadcast multicast-unicast convergence. The analysis assumes sustained OTT platform investment, stable net neutrality frameworks, and continued hyperscaler infrastructure expansion. Codec engineering talent scarcity, edge node deployment friction in fiber-sparse regions, and legacy SDI integration complexity warrant ongoing watch as forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
Policy Orchestration Market
Digital Solutions
UAE ICT Market
Digital Solutions
Digital Certificates Market
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
United States ICT Market
Digital Solutions
Czech Republic ICT Market
Digital Solutions
Warehouse Management System (WMS) Market
Digital Solutions
Cloud Field Service Management (FSM) Market
Digital Solutions
Email Deliverability Tools Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Online Laundry Services Market
Digital Solutions
Digital Assistant Market
Digital Solutions
Interactive Response Technology Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Europe IT Asset Disposition Market