
 Demand Side Platform (DSP) Market | 2026-2036
Demand Side Platform (DSP) Market Size, Share, and Industry Trends Forecast 2026-2036
Demand Side Platform (DSP) Market Analysis
Retail media buyers is redrawing demand patterns across the DSP landscape as CPG and grocery advertisers shift budgets from traditional search toward programmatic retail networks. The Trade Desk leverages its unified ID strategy to anchor identity resolution across connected TV and digital audio inventory. Quantcast competes through its AI-driven audience modeling and direct publisher integrations. Simpli.fi sustains its position in localized programmatic by dominating geo-fenced campaign execution for multi-location brands.
A demand side platform constitutes a software system that enables advertisers and agencies to purchase digital advertising inventory across multiple exchanges through real-time bidding protocols, typically processing bid decisions within 100 milliseconds per impression. Its primary commercial purpose centers on automating media buying while enabling audience targeting, frequency capping, and cross-channel attribution across fragmented publisher ecosystems. Self-service platforms lead the service type category as mid-market advertisers seek direct control over campaign parameters without managed service fees. Video ads within the advertising format dimension capture expanding margin pools as connected TV inventory commands premium CPMs against declining display efficiency. E-commerce verticals concentrate retargeting spend through demand side platforms, particularly where first-party transaction data enables closed-loop measurement.
The Federal Trade Commission and state-level privacy frameworks in California and Virginia shape data collection practices that directly constrain targeting granularity available through demand side platforms. The European GDPR and the EU AI Act impose algorithmic transparency requirements that affect automated bidding logic and audience segmentation methodologies. Stakeholders must monitor evolving state privacy legislation and platform identity alternatives to determine technology investments that preserve addressability without violating emerging compliance boundaries.
Market Dynamics
Third-party cookie deprecation is fragmenting identity resolution architectures and forcing advertisers to rebuild targeting infrastructure around first-party data ecosystems and alternative identifiers.
Growth Catalysts
- GDPR enforcement:European privacy mandates accelerate investment in consent management platforms and clean room infrastructure for compliant audience activation.
- Connected TV inventory expansion:Streaming platform ad-supported tiers create addressable impression pools that rival traditional linear television reach.
- Retail media networks:Closed-loop transaction data from grocery and CPG ecosystems enables deterministic attribution that bypasses traditional cookie-based measurement.
Market Restraints
- Identity fragmentation:Proliferation of competing universal ID solutions complicates cross-platform frequency management and audience deduplication.
- Supply concentration:Dominant walled garden platforms restrict data portability and limit independent DSP access to premium inventory sources.
- Technical latency:Real-time bidding protocols require sub-100-millisecond decision windows that constrain machine learning model complexity.
Strategic Opportunities
- India programmatic adoption:Underdeveloped addressable television infrastructure creates first-mover advantages for DSPs building localized supply partnerships.
- Audio streaming convergence:Digital podcast and music inventory integration with video planning workflows enables unified cross-channel campaign orchestration.
- EU AI Act transparency:Algorithmic audit requirements favor DSPs with interpretable bidding logic and documented audience segmentation methodologies.
Industry Challenges
- Data engineering talent scarcity:Shortage of engineers skilled in distributed streaming architectures limits platform scaling velocity.
- Legacy SSP integration:Outdated supply-side platform APIs create bid request parsing errors that degrade auction participation rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Demand Side Platform (DSP) Market |
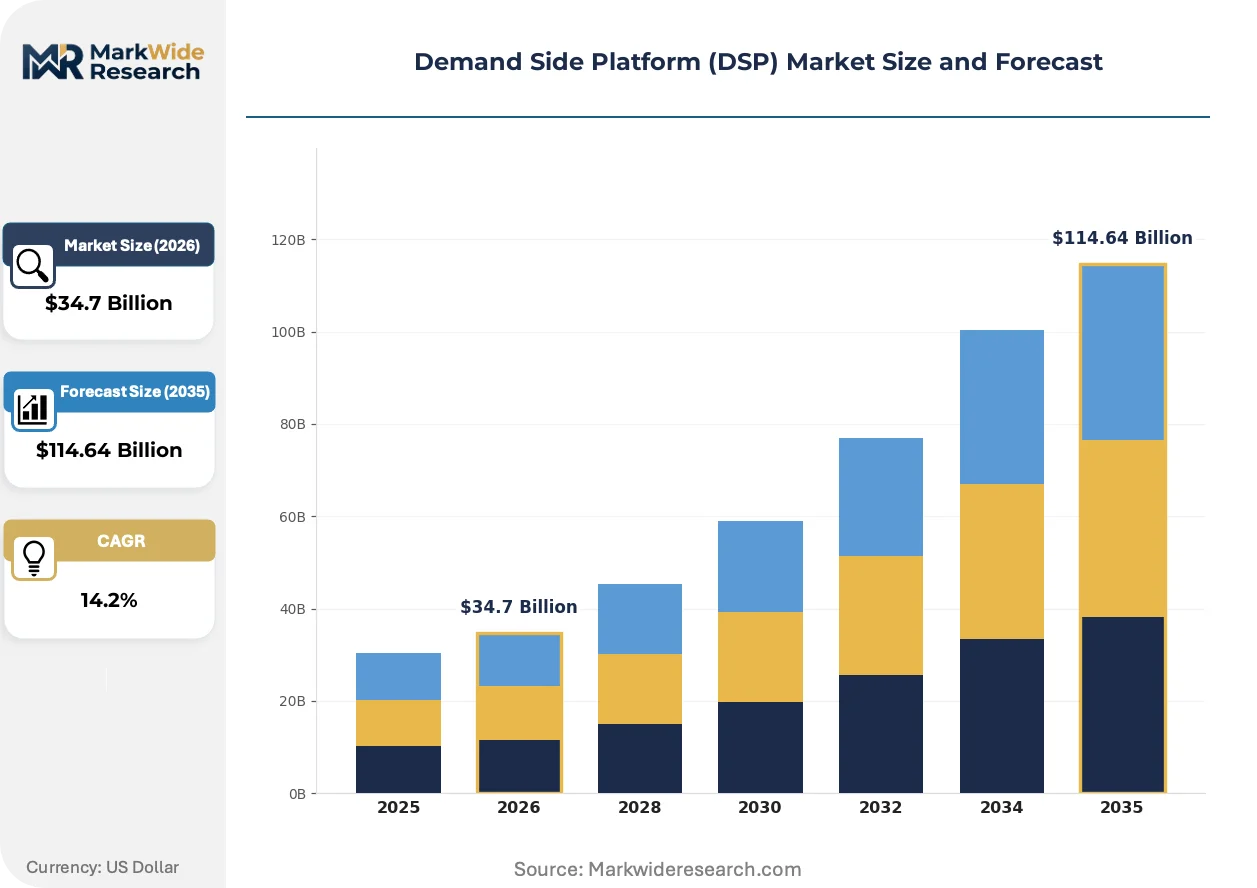
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $114.64 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, Self-Service Platforms, Hybrid Solutions, Advisory Services Advertising Format: Display Ads, Video Ads, Native Ads, Audio Ads Industry Vertical: E-commerce, Entertainment, Travel, Automotive Campaign Objective: Brand Awareness, Lead Generation, Customer Acquisition, Retargeting |
| Companies Covered | Quantcast, Simpli.fi, The Trade Desk, illumin, Viant Technology, StackAdapt, Basis Technologies, Opera Ads, Google Display & Video 360, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Demand Side Platform (DSP) Market Emerging Trajectories
Privacy-preserving measurement techniques are displacing conventional attribution models as regulatory pressure and browser restrictions eliminate persistent cross-site tracking capabilities.
Server-side ad insertion technology is fragmenting the relationship between content delivery and ad decisioning. Media owners deploy SSAI to bypass client-side ad blockers and maintain quality-of-service metrics. Premium publishers adopt this architecture fastest, compressing available transparent inventory and pushing buyers toward private marketplace transactions.
The EU AI Act imposes documentation requirements on automated bidding algorithms that affect how DSPs train and deploy machine learning models. Platform engineering teams must maintain model cards and risk assessments for audience segmentation logic. European advertisers face heightened compliance scrutiny, prompting demand for transparent optimization methodologies over black-box automation.
CPG procurement teams consolidate agency relationships and bring programmatic buying in-house through self-service platform licenses. Trading desk staff transition to brand-side roles, replacing traditional media agency retainers with direct technology contracts. This pattern appears most pronounced in North American markets where retail media networks offer closed-loop measurement that justifies internal capability investment.
Demand Side Platform (DSP) Market Segmentation
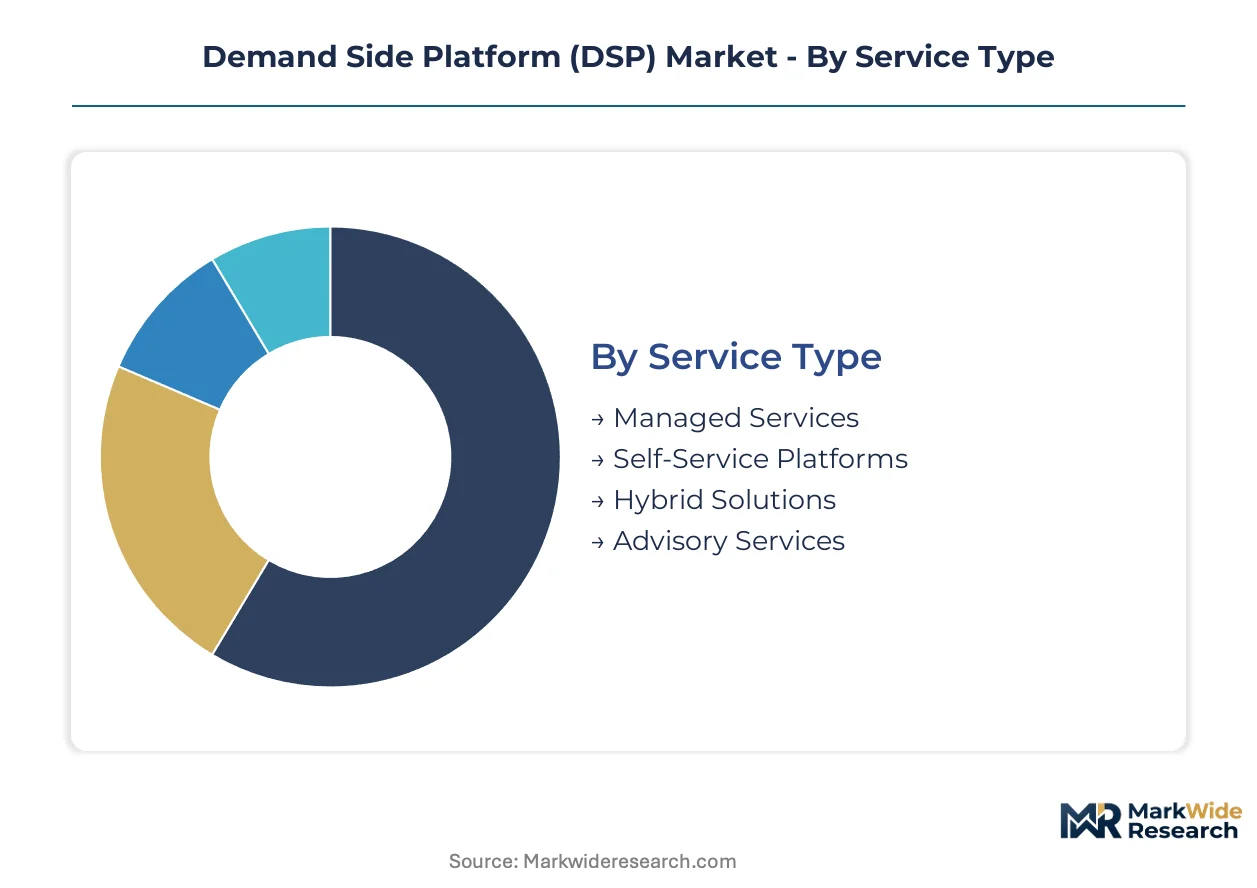
DSP segmentation reveals how advertisers balance control, creative format, and measurement precision. Each dimension captures distinct trade-offs between automation depth and strategic flexibility.
Service Type:
Self-service platforms face intensifying substitution pressure from in-house trading desks and direct publisher deals as brands seek to bypass technology fees entirely.
- Self-Service Platforms:Advertisers access full campaign control through browser-based interfaces with real-time bidding dashboards and audience builder tools. Mid-market CPG brands in the United States concentrate procurement here to eliminate managed service margins while retaining frequency capping and cross-device attribution capabilities.
- Managed Services:Dedicated trading teams execute campaigns on behalf of advertisers, layering strategic planning atop platform infrastructure. Automotive OEMs with complex dealer network hierarchies rely on this model to coordinate localized geo-fenced activations without building internal programmatic expertise.
- Hybrid Solutions:Combines platform access with on-demand analyst support for campaign optimization.
- Advisory Services:Strategic consulting on programmatic architecture and martech stack configuration.
Managed Services anchors the volume base while Self-Service Platforms gains share at the steepest rate.
Advertising Format:
Margin compression across display inventory pushes DSPs toward higher-yielding formats where supply scarcity sustains pricing power.
- Video Ads:Connected TV and in-stream digital video inventory command premium CPMs through deterministic viewability measurement and completion rate optimization. Streaming platform ad-supported tiers in the United States expand addressable pools as cord-cutting accelerates, drawing budget shifts from linear television upfronts.
- Audio Ads:Programmatic podcast and music streaming placements enable sequential messaging with video campaigns through unified frequency management. Digital audio inventory integrates with planning workflows fastest in North American markets where streaming subscription fatigue drives ad-tier adoption.
- Display Ads:Standard banner and rich media units face efficiency erosion from ad blocking and viewability challenges.
- Native Ads:In-feed sponsored content formats match publisher editorial aesthetics for reduced intrusiveness.
Display Ads anchors the volume base while Video Ads climbs the fastest as connected TV inventory scales.
Industry Vertical:
First-party data richness determines vertical attractiveness, with transaction-heavy sectors commanding closed-loop attribution premiums.
- E-commerce:Direct-to-consumer retailers activate site visitor data through product feed-based dynamic creative optimization. Closed-loop purchase measurement enables return-on-ad-spend bidding strategies that justify elevated platform fees against performance marketing alternatives.
- Automotive:Dealer network complexity and lengthy purchase cycles demand geo-fenced conquesting alongside CRM onboarding for prospect nurturing. Multi-location brand structures favor DSPs with localized budget allocation and inventory access controls.
- Entertainment:Streaming services and gaming publishers promote content releases through cross-platform reach and frequency management.
- Travel:Airlines and hospitality brands leverage search intent signals and booking window targeting for yield optimization.
E-commerce anchors the volume base while Automotive expands most quickly as dealer digital transformation accelerates.
Campaign Objective:
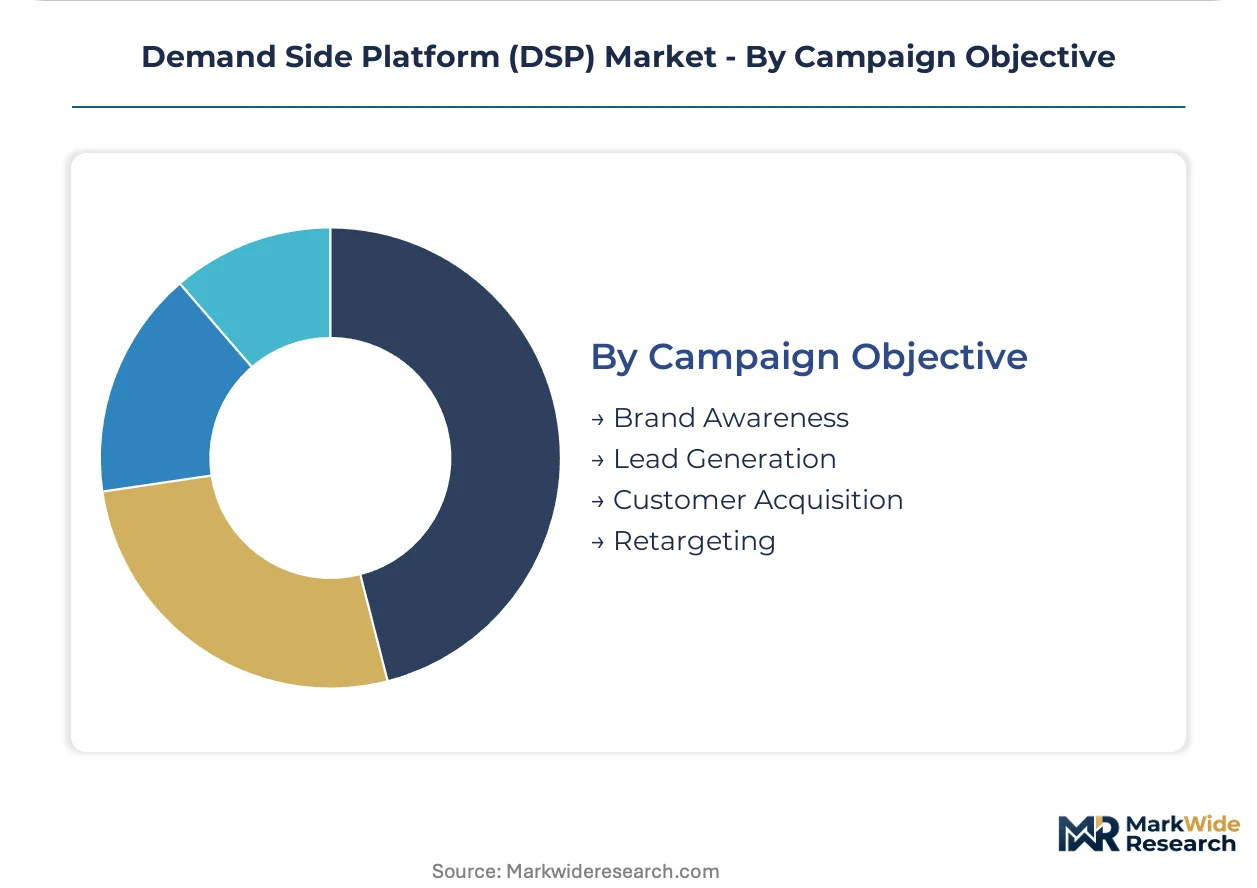
Objective-based buying structures reveal how advertisers sequence platform investment from prospecting through conversion.
- Retargeting:Site visitor re-engagement campaigns leverage first-party pixel data and dynamic product feeds to recover abandoned carts. E-commerce advertisers concentrate spend here where deterministic attribution proves incremental value against baseline conversion rates.
- Customer Acquisition:Lookalike modeling and prospecting audiences expand brand customer files through machine learning-based affinity scoring. Retail media networks in the United States enable this objective through closed-loop transaction data that bypasses cookie-based measurement limitations.
- Brand Awareness:Reach and frequency optimization against demographic or interest-based segments.
- Lead Generation:Form-fill and call-based conversion tracking for B2B and high-consideration categories.
Retargeting anchors the volume base while Customer Acquisition gains share at the steepest rate as privacy constraints elevate first-party data value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landing stations and cloud region interconnects underpin digital advertising infrastructure across major economies. Cross-border data flows enable real-time bidding architectures that process impression decisions within milliseconds.
United States
Connected TV inventory expansion and retail media network maturation drive platform investment. The FTC and state-level frameworks in California and Virginia constrain targeting granularity through data collection restrictions. New York and Los Angeles anchor demand concentration where streaming platform ad tiers scale fastest.
United Kingdom
GDPR enforcement accelerates consent management platform adoption among programmatic buyers. The Information Commissioner's Office scrutinizes algorithmic decision-making in automated bidding systems. London's financial services cluster generates substantial B2B programmatic demand through CRM onboarding and account-based marketing workflows.
Germany
Automotive OEM procurement teams consolidate agency relationships and bring programmatic buying in-house. The Federal Data Protection Act and GDPR impose strict processing limitations on cross-site tracking methodologies. Munich and Stuttgart industrial corridors concentrate manufacturing advertiser spend on dealer network localization.
India
Underdeveloped addressable television infrastructure creates first-mover opportunities for localized supply partnerships. TRAI regulations govern cross-media ownership and data localization requirements for advertising platforms. Bangalore and Mumbai technology hubs incubate domestic SSP-DSP integrations for vernacular language inventory.
Japan
Digital audio streaming convergence with video planning workflows enables unified campaign orchestration. METI guidelines influence data governance standards for programmatic transactions. Tokyo's media conglomerates deploy private marketplace structures to maintain inventory control against open exchange commoditization.
Demand Side Platform (DSP) Market Vendor Landscape
Concentration sits with integrated identity resolution and cross-channel attribution capabilities. The vendor landscape stratifies across three tiers: enterprise platforms with unified ID strategies, mid-market specialists in localized execution, and browser-originated networks with captive inventory access. Competitive positioning hardens around first-party data clean room partnerships and supply path optimization technologies. M&A activity targets consent management and measurement attribution assets; strategic alliances concentrate on retail media network integrations.
Among independent programmatic specialists, Quantcast, Simpli.fi, and The Trade Desk exemplify distinct archetype positioning. Quantcast occupies the AI-driven audience modeling tier through direct publisher integrations and predictive intelligence engines. Simpli.fi anchors localized programmatic execution with geo-fenced campaign infrastructure for multi-location brand structures. The Trade Desk sits within the enterprise self-service tier, leveraging unified ID strategies across connected TV and digital audio inventory pools.
| Leading Market Players |
|---|
| Quantcast |
| Simpli.fi |
| The Trade Desk |
| illumin |
| Viant Technology |
| StackAdapt |
| Basis Technologies |
| Opera Ads |
| Google Display & Video 360 |
| Others |
Supply Flow & Price Mechanics
First-party data clean rooms are replacing third-party cookie infrastructure as the primary targeting input, simultaneously shifting supply partnerships toward retail media networks in the United States and compressing pricing premiums for legacy audience segments. This substitution redraws geographic value capture as closed-loop measurement capabilities command technology fees that open-exchange inventory cannot sustain.
Pricing Analysis
Volume-discount tiering structures dominate DSP commercial models, with annual minimum commitments unlocking preferential CPM rates and platform fee reductions. Price differentiation hinges on data enrichment depth and cross-channel attribution granularity, with premium tiers commanding substantial markups for unified identity resolution. Cost compression in display inventory is intensifying because ad-blocking penetration and viewability challenges erode buyer willingness to pay. Mid-market CPG advertisers exhibit the highest price sensitivity, while automotive OEMs with complex dealer networks demonstrate lower elasticity due to localized campaign requirements.
Supply Chain Analysis
Inventory latency constraints in real-time bidding compress supply chain decision windows to sub-100-millisecond thresholds, tethering platform engineering to distributed cloud architectures. Supply concentration centers on the United States, United Kingdom, and Germany where retail media networks and connected TV inventory mature fastest. Raw material dependencies span consent management platforms, identity resolution vendors, and supply-side platform APIs. Single-source vulnerability sits with dominant walled garden platforms that restrict data portability. Distribution runs through direct technology contracts with brands and managed service arrangements with agency trading desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as CPG procurement teams consolidate agency relationships and bring programmatic buying in-house through self-service platform licenses, fragmenting traditional media agency retainers.
For Market Incumbents: Fortify identity resolution capabilities through unified ID partnerships that anchor cross-device attribution as third-party cookie deprecation accelerates. Deepen vertical integration into consent management platforms to capture GDPR and EU AI Act compliance spend. Prioritize clean room infrastructure investments that preserve addressability without violating emerging privacy boundaries. For New Entrants and Emerging Players: Certification fast-tracks for EU AI Act algorithmic transparency requirements open white-space opportunities in European markets where interpretable bidding logic commands procurement preference. Target India's underdeveloped addressable television infrastructure through localized SSP partnerships. Pursue audio streaming convergence as the most penetrable format expansion, integrating podcast inventory with video planning workflows. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-market DSPs possessing retail media network integrations but lacking connected TV scale. Long-term viability over the coming decade hinges on first-party data ecosystem positioning rather than open-exchange volume capture. Watch retail media network consolidation velocity as the signal indicating platform addressability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Clean Room Infrastructure Investment | Enables closed-loop measurement that bypasses cookie deprecation for CPG advertisers. |
| Unified ID Partnership Expansion | Anchors cross-device attribution across connected TV and digital audio inventory pools. |
| Retail Media Network Integration | Captures deterministic transaction data from grocery and closed-loop ecosystems. |
| EU AI Act Compliance Certification | Unlocks European procurement preference through documented algorithmic transparency. |
| Localized Supply Partnership Buildout | Establishes first-mover position in India's emerging addressable television infrastructure. |
Methodological Framework
The analysis maps self-service platforms, managed services, video advertising formats, and retail media network integrations, each validated through programmatic traders, ad technology engineers, and brand-side marketing directors. Primary interviews with demand-side platform executives, supply-side platform operators, and retail media network strategists combined with secondary validation against SEC filings, IAB programmatic spend reports, and regulatory disclosure databases. Bottom-up segment sizing and top-down market triangulation ensured consistency across service type, advertising format, and industry vertical dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment model, advertiser size tier, vertical data maturity, and regional privacy regime as segmentation dimensions. CAGRs were derived from trend extrapolation anchored in documented technology adoption curves and inventory expansion trajectories. Forecast inputs incorporated connected TV ad-tier rollout schedules and state-level privacy legislation progression patterns.
Decision-makers should treat outputs as directional under assumptions of sustained GDPR enforcement and third-party cookie deprecation timelines; material deviation in regulatory implementation or browser technology would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Hybrid Events Software Market
Digital Solutions
Crew Management Systems Market
Digital Solutions
Digital Library Software Market
Digital Solutions
Smart Dictation Systems Market
Digital Solutions
Cloud Manufacturing Execution System (MES) Market
Digital Solutions
Global Product Design and Development Market
Digital Solutions
Intelligent Virtual Store Design Solution Market
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
Thin Client Market
Digital Solutions
Cloud Service Assurance Market
Digital Solutions
Global Sharing Economy Market
Digital Solutions
US Digital Twin Market
Digital Solutions
Digital Shelf Market
Digital Solutions
IT Monitoring Tools Market
Digital Solutions
Big Data As a Service (Bdaas) Market
Digital Solutions
Web Real Time Communication Solution Market