
 Italy Lip Care Products Market | 2026-2036
Italy Lip Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Lip Care Products Market Intelligence
Pharmacy retail is reconfiguring how lip care reaches Italian consumers, with chains like Farmacia Igea and Parafarmacia networks expanding dedicated dermocosmetic zones. Labello leverages its heritage positioning to sustain pharmacy shelf dominance. KIKO MILANO S.p.A. competes through color-cosmetic cross-selling in flagship stores. Bottega Verde S.p.A. anchors its plant-based narrative in regional specialty retail across Tuscany and Emilia-Romagna.
Lip care products are topical formulations—typically comprising occlusive agents like petrolatum or plant waxes, humectants such as hyaluronic acid or glycerin, and protective filters—designed to prevent desiccation, repair barrier function, and shield vermillion tissue from environmental stressors. Manufacturing involves emulsion stabilization at controlled temperatures to preserve thermolabile actives, followed by filling into twist-base sticks or squeeze tubes. Balm formats occupy the largest revenue pool given their year-round utility and higher per-unit pricing, while treatment segments with ceramide or peptide complexes represent the fastest-expanding margin tier. Stick packaging dominates unit volume for on-the-go convenience, though jar formats capture premium positioning in pharmacy and specialty channels.
Italy's Ministry of Health enforces the EU Cosmetics Regulation through its national vigilance system, requiring safety assessments and responsible-person designation for all marketed products. BIS-equivalent conformity assessments for imported packaging materials add compliance layers for non-EU suppliers. REACH chemical registration rules govern novel emollient introductions, while the EU Green Deal's packaging-waste directives pressure format innovation. Stakeholders must monitor tightening microplastic restrictions and evolving biodegradability standards for rinse-off claims.
Market Dynamics
Pharmacy retail chains across Milan, Rome, and Turin are expanding dedicated dermocosmetic zones, reconfiguring how Italian consumers access treatment-grade lip care and compressing traditional mass-market distribution.
Growth Catalysts
- EU Cosmetics Regulation (EC) No 1223/2009:Mandatory safety assessments and responsible-person designation elevate pharmacy-channel credibility, steering consumers toward verified formulations with documented efficacy claims.
- SPF-integrated anti-aging actives:Women aged 25-45 in metropolitan centers demand multifunctional balms combining UV protection with ceramide complexes, expanding the treatment-grade segment faster than basic moisturizing formats.
- Plant-derived emollient substitution:Reformulation toward natural waxes and botanical oils aligns with Emilia-Romagna's regional specialty retail positioning, attracting consumers seeking traceable ingredient sourcing.
Market Restraints
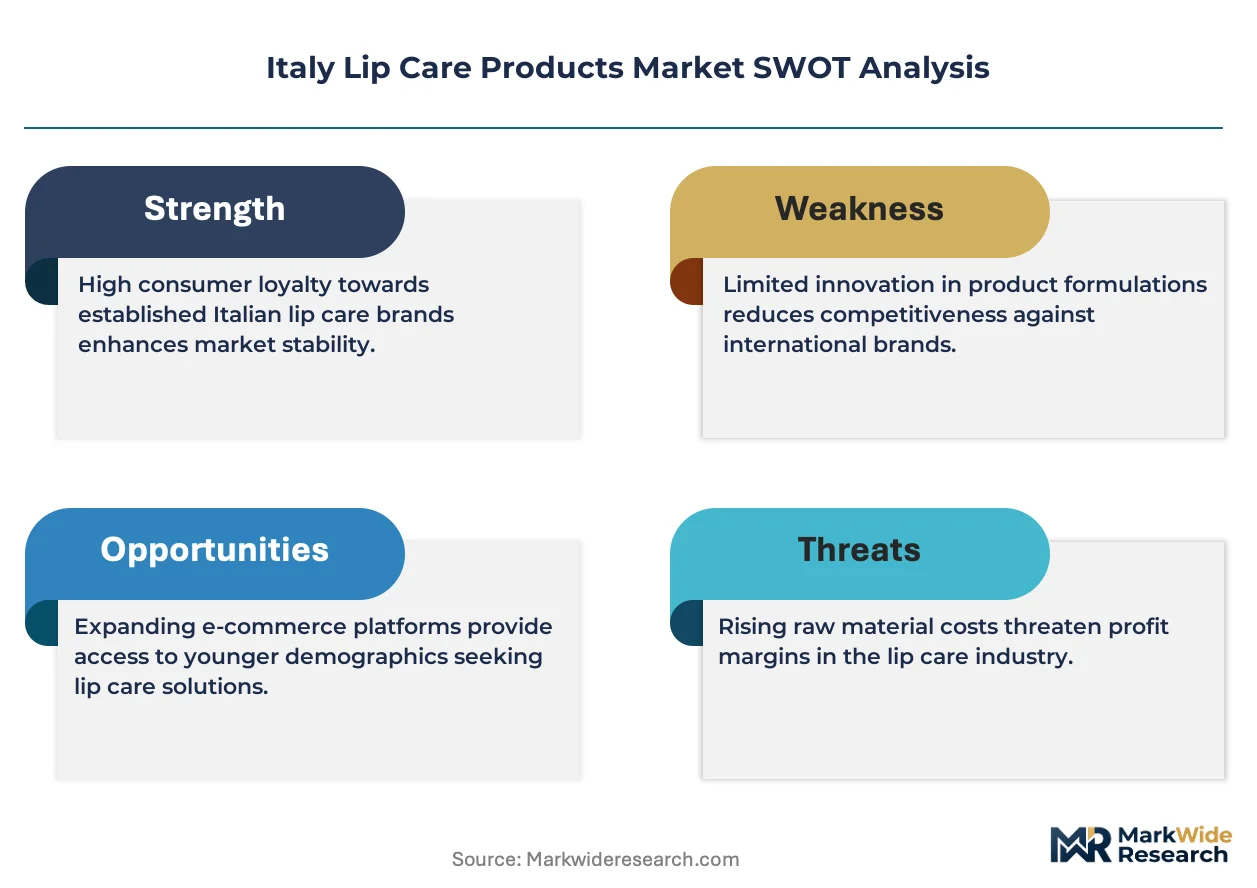
- Petrolatum price volatility:Remaining dependence on petroleum-derived occlusives exposes margins to energy-market fluctuations, complicating cost planning for mid-tier manufacturers.
- Non-EU packaging compliance:BIS-equivalent conformity assessments for imported stick and jar materials add 8-12 week lead times, disadvantaging suppliers without EU-based molding capacity.
- Microplastic restriction tightening:Evolving biodegradability standards for rinse-off claims threaten legacy synthetic film-formers, forcing premature R&D redirection before regulatory deadlines clarify.
Strategic Opportunities
- Southern Italy pharmacy penetration:Naples and Palermo retail networks remain underdeveloped for premium dermocosmetic positioning, offering first-mover shelf space before national chains consolidate.
- EU Green Deal packaging-waste directives:Biodegradable twist-base sticks and refillable jar systems qualify for emerging extended-producer-responsibility incentives, differentiating compliant brands in pharmacy procurement.
- Peptide-ceramide convergence:Barrier-repair technologies borrowed from facial skincare are migrating into lip treatment formats, enabling 40-60% price premiums over standard balms in specialty channels.
Industry Challenges
- Thermolabile active stabilization:Emulsion processing at controlled temperatures demands precision equipment upgrades, straining capital allocation for smaller regional manufacturers.
- REACH novel emollient registration:Pre-market chemical dossiers for plant-derived alternatives extend development timelines by 18-24 months, compressing competitive response windows.
- Cross-channel pricing coherence:Flagship store color-cosmetic bundling conflicts with pharmacy-exclusive treatment positioning, eroding brand equity when identical SKUs appear at divergent price points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Lip Care Products Market |
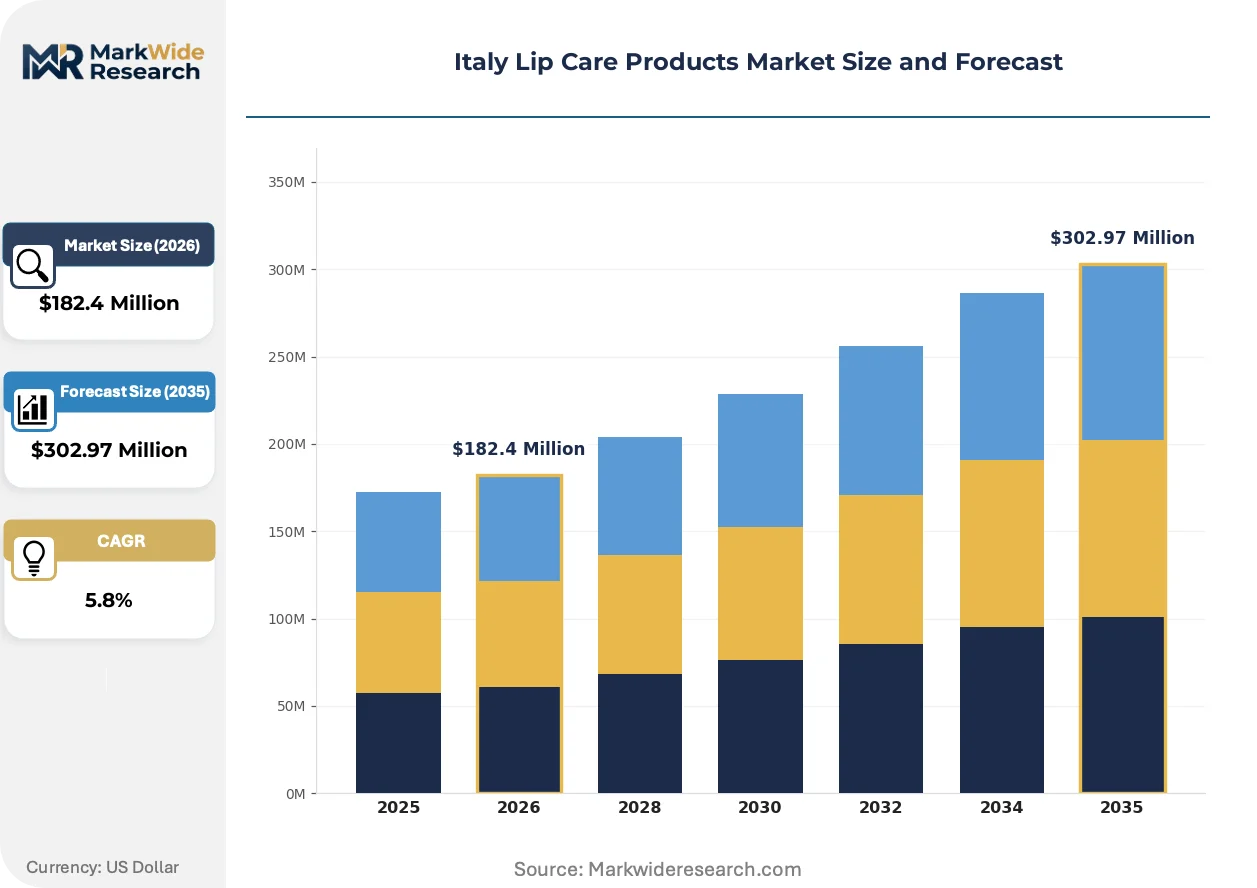
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $302.97 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balm, Gloss, Stick, Treatment Packaging Type: Tubes, Jars, Pots, Sticks Distribution Channel: Pharmacies, Supermarkets, Online Retail, Specialty Stores Target Audience: Women, Men, Teens, Children |
| Companies Covered | Labello, Clarins Group, KIKO MILANO S.p.A., Essence Cosmetics, Rimmel London, L'Oréal S.A., Bottega Verde S.p.A., Avon Products, NIVEA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Lip Care Products Market Strategic Shifts & Innovations
Biotechnology-derived alternatives and regulatory packaging mandates are actively restructuring formulation priorities and manufacturing footprints across Italian lip care production.
Biotechnology platforms utilizing fermented squalane and lab-grown ceramides are rendering obsolete petroleum-derived occlusive bases that dominated mass-market sticks for decades. Treatment-grade buyers in northern pharmacy networks are accelerating adoption, with Milan-based dermocosmetic consultants now specifying biotech ingredients in professional recommendations. This shift compresses input cost exposure to crude oil markets while enabling premium positioning through molecular traceability claims.
REACH chemical registration rules governing novel emollient introductions now require full toxicological dossiers before commercial deployment, extending development cycles for plant-derived alternatives. Manufacturers must pre-validate biodegradability metrics and aquatic toxicity profiles, adding compliance layers that favor established players with dedicated regulatory affairs capacity. The treatment segment with peptide complexes faces the steepest documentation burden, as these actives fall under stricter hazard classification protocols than basic moisturizers.
Regional specialty retail across Tuscany and Emilia-Romagna is consolidating procurement around certified-organic and zero-waste format suppliers, displacing conventional mass-market distributors in these catchments. Bottega Verde's plant-based narrative anchors this channel shift, with farm-to-lip storytelling now expected by consumers in these provinces. The behavior is most visible among women aged 35-50 seeking gift-positioned products, where packaging aesthetics and ingredient provenance outweigh price sensitivity in purchase decisions.
Italy Lip Care Products Market Segmentation
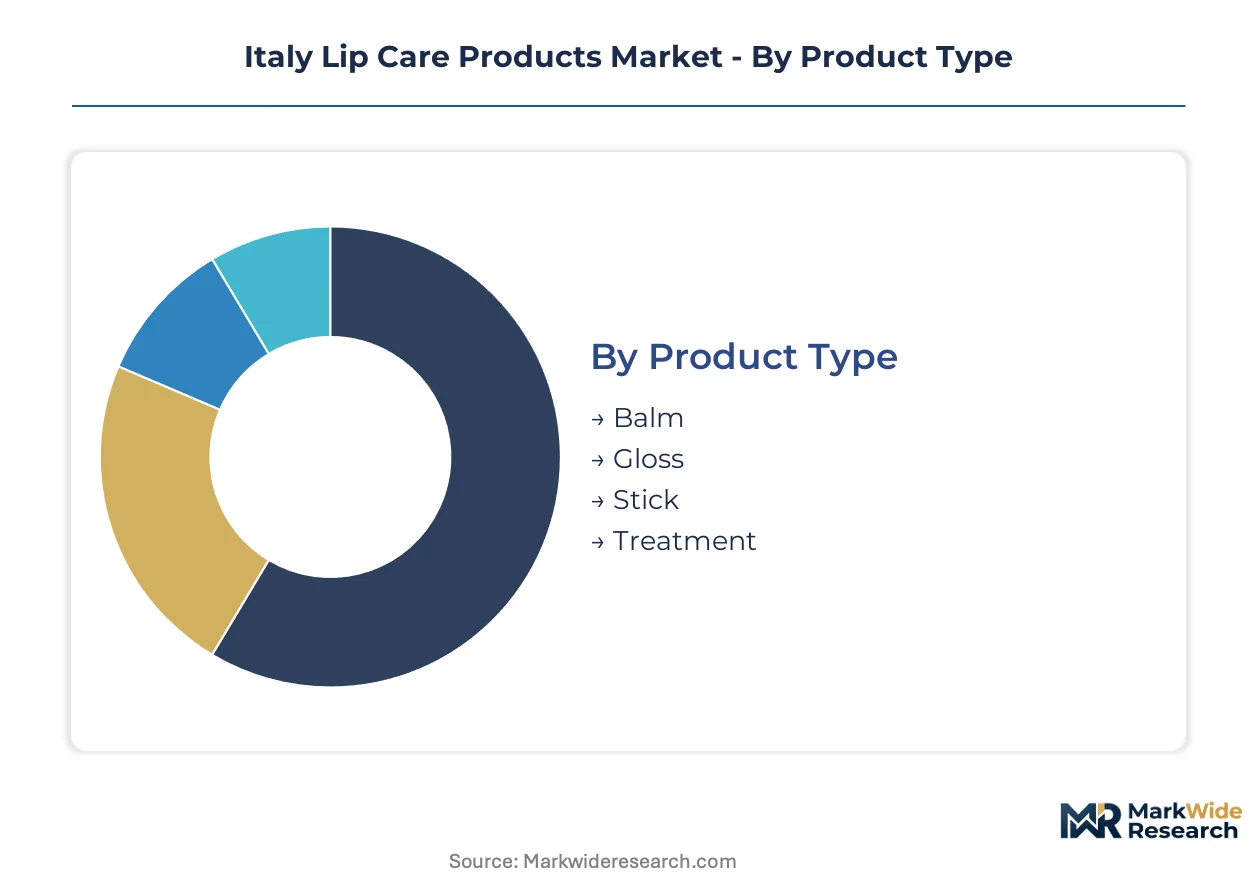
Lip care segmentation in Italy reflects divergent usage occasions spanning daily maintenance, cosmetic enhancement, and clinical repair. Product formats, packaging systems, and channel access each create distinct margin architectures that manufacturers must navigate simultaneously.
Product Type:
Functional demands range from basic occlusion through barrier reconstruction to aesthetic finish, mapping directly to price elasticity and pharmacy credential requirements.
- Balm:Occlusive formulations combining petrolatum or plant waxes with humectants such as glycerin deliver year-round moisture retention. Milan pharmacy chains allocate expanded shelf space to balm SKUs given their traffic-driving frequency and impulse purchase velocity at checkout counters.
- Treatment:Ceramide complexes, peptide actives, and SPF-integrated systems target barrier repair and photodamage prevention. Women aged 25-45 in metropolitan centers concentrate demand here, accepting 40-60% price premiums over standard formats for documented efficacy claims verified through EU Cosmetics Regulation safety dossiers.
- Gloss:Sheer color and shine formulations prioritize cosmetic finish over therapeutic benefit. KIKO MILANO S.p.A. leverages cross-selling in flagship stores to move gloss SKUs alongside color cosmetics.
- Stick:Solid formats in twist-base dispensers dominate on-the-go convenience use cases. Stick packaging captures volume leadership through portability and single-hand application.
The dominant share belongs to Balm, while Treatment is closing the gap fastest.
Packaging Type:
Format selection dictates thermal stability requirements, shelf presence, and compliance burden under evolving waste directives.
- Sticks:Twist-base polypropylene or biodegradable alternatives dominate unit volume for commuter and travel occasions. Stick formats face tightening microplastic restrictions that threaten legacy synthetic film-formers and force premature R&D redirection.
- Jars:Wide-mouth glass or post-consumer recycled containers signal premium positioning in pharmacy and specialty channels. Tuscany and Emilia-Romagna specialty retail networks favor jar formats for gift-positioned SKUs where packaging aesthetics drive purchase decisions.
- Tubes:Squeeze-dispense systems accommodate fluid emulsions and treatment-grade actives. Tube filling demands precision temperature control to preserve thermolabile ingredients.
- Pots:Compact circular containers target handbag portability and sampling programs. Pot formats sacrifice some hygiene perception against stick alternatives.
Sticks command volume leadership, though Jars capture margin concentration in premium channels.
Distribution Channel:
Channel selection determines regulatory scrutiny intensity, pricing architecture, and consumer education depth.
- Pharmacies:Farmacia Igea and Parafarmacia networks across Milan, Rome, and Turin anchor treatment-grade positioning through dermocosmetic zone expansion. Pharmacy procurement increasingly demands documented biodegradability metrics and extended-producer-responsibility compliance.
- Specialty Stores:Bottega Verde S.p.A. and regional chains across Tuscany and Emilia-Romagna consolidate around certified-organic suppliers with farm-to-lip traceability narratives. Specialty retail displaces conventional mass-market distributors in these catchments through gift-positioned merchandising.
- Supermarkets:Mass-market velocity channels prioritize price-point accessibility and promotional elasticity. Supermarket distribution compresses margin for mid-tier manufacturers exposed to petrolatum input volatility.
- Online Retail:Direct-to-consumer platforms enable peptide-ceramide convergence storytelling and subscription replenishment models. E-commerce penetration remains underdeveloped in Southern Italy relative to northern metropolitan centers.
Pharmacies retain the dominant share, with Specialty Stores expanding most quickly through regional consolidation.
Target Audience:
Demographic targeting aligns format innovation with life-stage specific concerns from pediatric safety through anti-aging repair.
- Women:The 25-45 metropolitan cohort concentrates demand for multifunctional balms combining UV protection with barrier-repair actives. Women drive treatment-grade segment expansion faster than basic moisturizing formats.
- Men:Simplified, fragrance-neutral formats with matte finish claims capture growing attention. Men show lower channel loyalty and higher price sensitivity than female counterparts.
- Teens:Gloss and tinted formats with social media-driven aesthetic positioning dominate. Teen demand concentrates in KIKO MILANO S.p.A. flagship stores and online discovery channels.
- Children:Pediatric safety requirements restrict actives and mandate simplified INCI lists. Children represent a compliance-heavy, margin-constrained segment with concentrated pharmacy distribution.
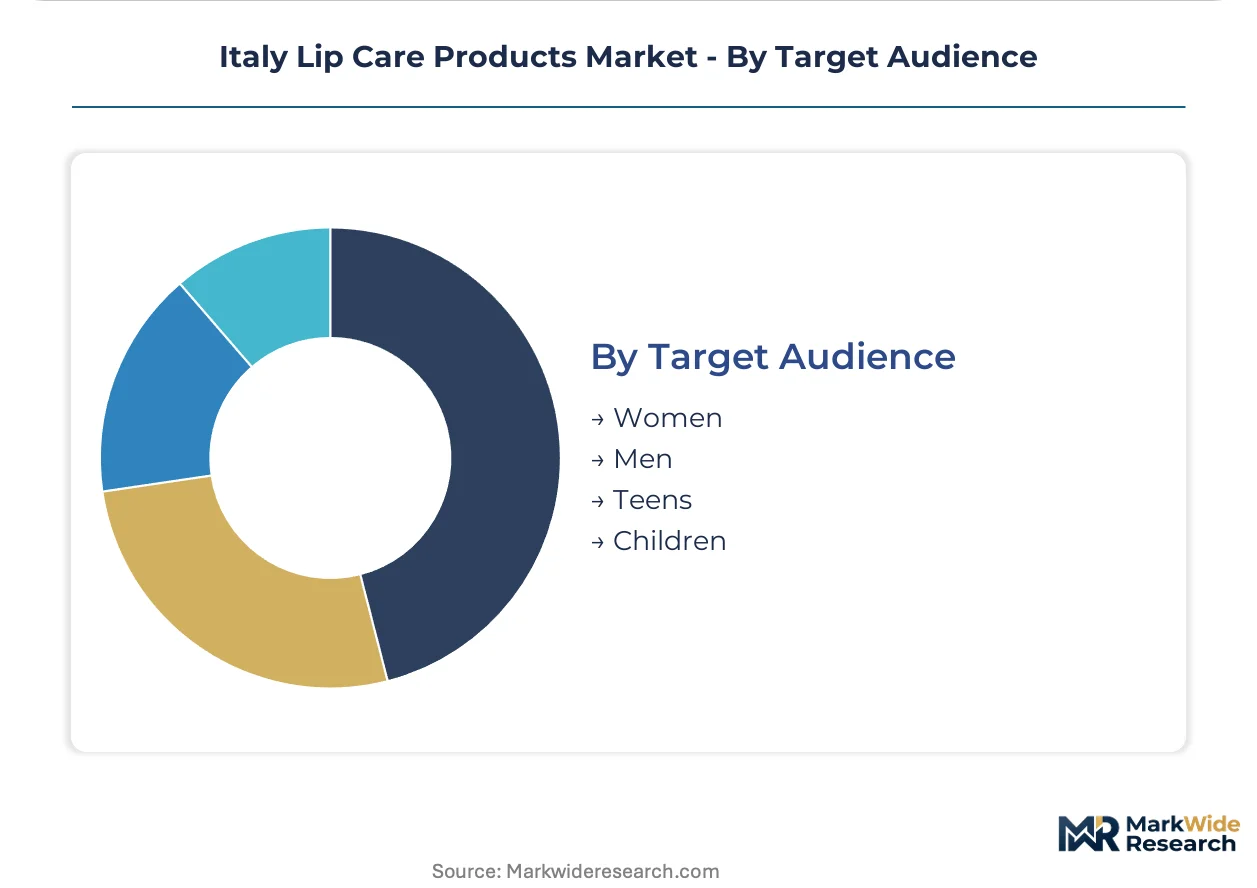
Women hold the dominant share, while Men represent the steepest expansion trajectory as grooming routines extend beyond facial skincare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Genoa anchors northwestern Italy's import infrastructure for raw botanical oils and packaging materials, while the Milan-Turin logistics corridor distributes finished lip care products to pharmacy networks across the Po Valley industrial belt.
Lombardy
Milan pharmacy chains Farmacia Igea and Parafarmacia networks drive treatment-grade demand among women aged 25-45 seeking SPF-integrated ceramide complexes. The EU Cosmetics Regulation (EC) No 1223/2009 mandates safety assessments through Italy's Ministry of Health national vigilance system. The Milan metropolitan area concentrates dermocosmetic zone expansion across 340+ pharmacy locations.
Piedmont
Turin's industrial fabric supports precision temperature-control equipment manufacturing for emulsion stabilization processes. REACH chemical registration rules govern novel emollient introductions through ECHA documentation requirements. Turin-based suppliers serve contract manufacturers across the northwestern manufacturing triangle.
Emilia-Romagna
Regional specialty retail networks consolidate procurement around certified-organic suppliers with farm-to-lip traceability narratives. The EU Green Deal's packaging-waste directives pressure format innovation toward biodegradable twist-base systems. Bologna and Modena anchor this channel shift through Bottega Verde S.p.A.'s plant-based positioning.
Lazio
Rome pharmacy retail chains expand dedicated dermocosmetic zones, compressing traditional mass-market distribution reach. BIS-equivalent conformity assessments for imported packaging materials add compliance layers for non-EU suppliers. Rome's metropolitan pharmacy density exceeds 280 locations with accelerating premium SKU penetration.
Tuscany
Specialty retail across Florence and Siena favors jar formats for gift-positioned SKUs where packaging aesthetics drive purchase decisions. Microplastic restriction tightening threatens legacy synthetic film-formers in rinse-off claims. Tuscan retail networks displace conventional mass-market distributors through certified-organic consolidation.
Italy Lip Care Products Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream. Pharmacy retail chains and specialty store networks reconfigure distribution economics, compressing mass-market intermediation. Three archetypes dominate: heritage pharmacy brands leveraging decades of shelf presence, color-cosmetic cross-sellers exploiting flagship store traffic, and regional organic specialists anchoring farm-to-lip narratives. Competitive moves concentrate on dermocosmetic zone shelf space capture and biodegradable format R&D redirection.
Among heritage-positioned specialists, Labello occupies a position exemplifying pharmacy-channel dominance through sustained shelf presence. KIKO MILANO S.p.A. sits within the color-cosmetic cross-selling archetype, leveraging flagship store networks for gloss and tinted format velocity. Bottega Verde S.p.A. represents the regional organic specialist tier, anchoring plant-based narratives across Tuscany and Emilia-Romagna specialty retail.
| Leading Market Players |
|---|
| Labello |
| Clarins Group |
| KIKO MILANO S.p.A. |
| Essence Cosmetics |
| Rimmel London |
| L'Oréal S.A. |
| Bottega Verde S.p.A. |
| Avon Products |
| NIVEA |
| Others |
Cost & Logistics Intelligence
The Milan-Turin logistics corridor channels botanical oil imports from the Port of Genoa to Po Valley contract manufacturers, concentrating supply-side leverage among northwestern Italian emulsion specialists while compressing margin buffers for mid-tier brands competing on petrolatum-based formulations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Italian lip care, with pharmacy-channel treatment-grade SKUs commanding substantial premiums over mass-market petrolatum sticks. Price differentiation hinges on certification grade under EU Cosmetics Regulation dossiers and volume scale in procurement negotiations with Farmacia Igea networks. Cost compression in the standard tier is intensifying because of petroleum-derived occlusive input volatility. Supermarket buyers exhibit highest price sensitivity, while specialty retail consumers in Tuscany prioritize ingredient provenance over unit economics.
Supply Chain Analysis
Tariff exposure between non-EU packaging suppliers and Italian molders dominates supply chain risk assessment, with BIS-equivalent conformity assessments adding procedural friction to stick and jar material sourcing. Manufacturing concentrates in Italy, Germany, and France for precision temperature-control equipment and emulsion stabilization systems. Raw material dependencies center on plant-derived waxes from Mediterranean suppliers, fermented squalane from biotechnology platforms, and petroleum-derived petrolatum from energy markets. Single-source vulnerability threatens legacy synthetic film-formers facing microplastic restriction tightening. Distribution runs through pharmacy retail chains and regional specialty networks, bypassing traditional mass-market intermediation in northern catchments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's lip care sector represents early-cycle expansion, with peptide-ceramide convergence in treatment-grade formats driving pharmacy-channel premiumization faster than basic moisturizing segment maturation.
For Market Incumbents: Build regulatory dossier depth as the primary moat, accelerating EU Cosmetics Regulation safety assessments ahead of REACH novel emollient deadlines. Secure backward integration into botanical oil supply from Emilia-Romagna cultivators to offset petrolatum price volatility. Defend Farmacia Igea shelf space through biodegradable format R&D redirection before national chains consolidate procurement. For New Entrants and Emerging Players: Southern Italy pharmacy networks in Naples and Palermo represent the most penetrable entry point, with underdeveloped dermocosmetic zones offering first-mover shelf space before regional consolidation. Peptide-ceramide treatment formats for men aged 25-40 capture steepest expansion trajectory with lower incumbent saturation. Direct-to-consumer subscription models bypass pharmacy channel gatekeeping while building efficacy documentation for eventual retail placement. For Investors and Strategic Acquirers: Regional organic specialists with captive botanical supply and certified-organic positioning offer acquisition exposure to Emilia-Romagna and Tuscany channel consolidation. Long-term viability frames around biodegradability compliance capacity and REACH registration expertise across the analysis window. Watch peptide-ceramide SKU velocity in Milan pharmacy networks as inflection indicator for treatment-grade segment maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Format Development | EU Green Deal packaging-waste directives qualify compliant brands for extended-producer-responsibility incentives in pharmacy procurement. |
| Peptide-Ceramide SKU Expansion | Treatment-grade convergence enables 40-60% price premiums over standard balms in Farmacia Igea dermocosmetic zones. |
| Southern Italy Pharmacy Penetration | Naples and Palermo retail networks remain underdeveloped for premium positioning before national chains consolidate shelf space. |
| Botanical Oil Backward Integration | Captive supply from Emilia-Romagna cultivators insulates margins from petroleum-derived occlusive price volatility. |
| REACH Dossier Pre-Validation | Novel emollient registration timelines favor established players with dedicated regulatory affairs capacity over smaller regional manufacturers. |
Research Approach
Initial hypotheses were tested against primary input from pharmacy procurement managers, contract manufacturing plant engineers, dermocosmetic brand managers, and regional specialty retail buyers, then refined through secondary validation. Primary fieldwork encompassed structured discussions with emulsion stabilization equipment suppliers and botanical oil distributors. Secondary sources included Italy's Ministry of Health vigilance filings, ECHA REACH registration databases, EU Cosmetics Regulation guidance documents, and pharmacy retail audit data. Bottom-up SKU-level volume estimates were triangulated against top-down category expenditure figures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, packaging format, distribution channel, and target demographic cohort. CAGRs were derived from trajectory fitting to historical pharmacy sales velocity and projected treatment-grade adoption curves. Industry-specific forecast inputs incorporated REACH novel emollient approval timelines and EU Green Deal packaging-waste directive implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in energy market pricing for petroleum-derived inputs or euro-zone consumer confidence indices would shift the trajectory. Forecasts reflect documented assumptions on regulatory deadline adherence and channel consolidation pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
Glow in the Dark Cosmetics Market
Cosmetics & Skincare
Lip Scrub Market
Cosmetics & Skincare
Cosmetics Private Label and Contract Manufacturing Market
Cosmetics & Skincare
Camellia Skincare and Cosmetics Market
Cosmetics & Skincare
Halal Cosmetic Products Market
Cosmetics & Skincare
Face Wash Market
Cosmetics & Skincare
Vietnam Skin Care Products Market
Cosmetics & Skincare
Mushroom Cosmetics Market
Cosmetics & Skincare
Organic Soaps Market
Cosmetics & Skincare
Skin Care Products Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Lip Products Pigment Market
Cosmetics & Skincare
Night Cream Market
Cosmetics & Skincare
Makeup Setting Powder Market
Cosmetics & Skincare
Waterproof Eyebrow Liner Market