
 Epigenetic Cosmetic Products Market | 2026-2036
Epigenetic Cosmetic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Epigenetic Cosmetic Products Market Foresight
The gap between premium epigenetic formulations and mass-market commodity skincare is shifting from packaging claims to verifiable biomarker modulation. L'Oréal Groupe leverages its integrated dermatology research network to sustain clinical validation pipelines for epigenetic active compounds. Estée Lauder Companies anchors its positioning through proprietary biofermentation platforms that differentiate its serum tier from competitors relying on off-the-shelf peptide suppliers. Merck KGaA dominates the upstream ingredient layer, supplying DNA methylation-modulating compounds to multiple downstream cosmetic houses.
Epigenetic cosmetic products comprise topical formulations engineered to influence gene expression patterns—specifically DNA methylation, histone modification, and non-coding RNA activity—without altering underlying genomic sequences, typically incorporating concentrations of 0.5-5% bioactive polyphenols or short-chain peptides designed to modulate cellular senescence markers. Their primary commercial purpose centers on delivering measurable, claim-substantiated skin aging intervention beyond conventional moisturization or surface exfoliation. Serums command the deepest margin pools due to higher permissible active loading and consumer willingness to pay for concentrated delivery formats, while marine extract ingredient sourcing is expanding fastest as sustainable biotechnology replaces wild harvesting with controlled aquaculture cultivation. The aging skin concern segment retains volume leadership, though sensitivity-targeted epigenetic formulations are capturing disproportionate growth as dermatologist-channel credibility transfers to retail.
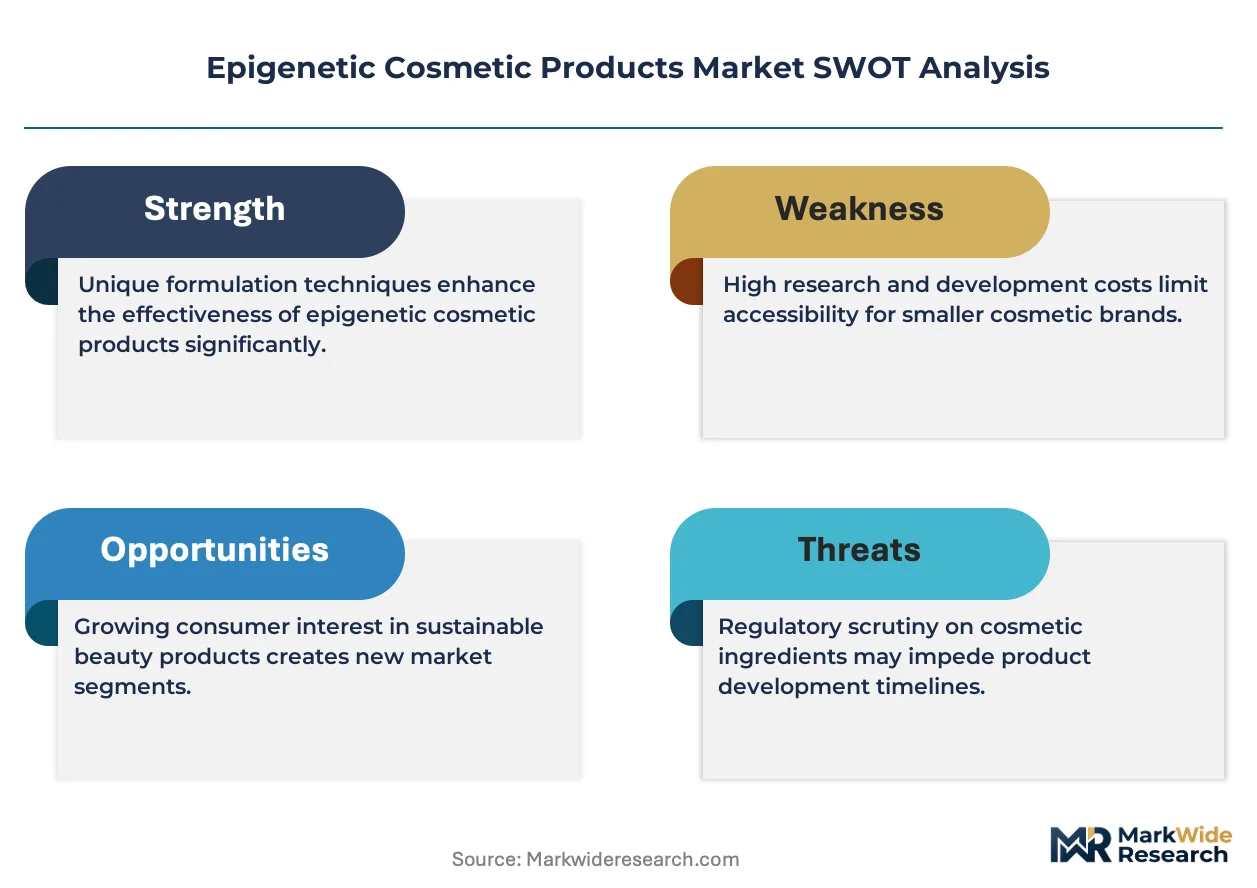
The EU Cosmetics Regulation and REACH frameworks mandate full ingredient traceability and safety dossiers for epigenetic actives, effectively filtering out suppliers lacking toxicological investment capacity. FDA oversight through the Cosmetic Modernization Act is tightening adverse event reporting requirements, pushing brands toward pre-market safety substantiation that smaller peptide houses struggle to fund. China's NMPA cosmetic registration rules for novel bioactive ingredients create dual-track compliance costs for multinational portfolios. Stakeholders must monitor regulatory divergence between jurisdictions that classify epigenetic claims as cosmetic versus those edging toward quasi-drug designation, as this boundary will determine channel access and clinical substantiation budgets.
Market Dynamics
Regulatory divergence between cosmetic and quasi-drug classification regimes is compressing formulation timelines and forcing parallel compliance architectures across multiple jurisdictions simultaneously.
Growth Catalysts
- EU Cosmetics Regulation disclosure mandates:Tightened ingredient traceability requirements are accelerating reformulation investments among established houses seeking claim substantiation advantages.
- Dermatology clinic channel expansion:Medical spas and aesthetic clinics are integrating professional-grade epigenetic protocols, transferring clinical credibility to retail-tier products.
- Controlled aquaculture biotechnology:Marine extract sourcing is displacing wild harvesting with sustainable cultivation systems, securing supply continuity for polyphenol-dependent formulations.
Market Restraints
- Peptide synthesis cost volatility:Short-chain peptide precursors face input cost pressure from pharmaceutical-sector demand competition, squeezing mid-tier formulation margins.
- Upstream supply concentration:DNA methylation-modulating compound production clusters in German and Swiss chemical corridors, creating single-source vulnerability for downstream cosmetic houses.
- Clinical validation timelines:Biomarker modulation claims require extended dermatological testing protocols that extend product development cycles beyond conventional skincare.
Strategic Opportunities
- Sensitivity-targeted formulations:Dermatologist-channel credibility is transferring to retail through barrier-function epigenetic products, opening white space beyond aging-focused SKUs.
- South Korea beauty cluster penetration:Seoul-Incheon manufacturing infrastructure offers contract development capacity for brands seeking Asian market entry without captive facilities.
- China NMPA novel ingredient pathway:Registration rules for bioactive cosmetics create first-mover advantages for houses with pre-submitted safety dossiers.
Industry Challenges
- Cross-functional talent scarcity:Formulation chemists with dual expertise in dermatological biomarkers and regulatory dossier construction command premium compensation and limited availability.
- Legacy ERP integration friction:Batch-level ingredient traceability systems required by REACH conflict with decades-old manufacturing software architectures at mid-tier houses.
- Patent thickets around delivery systems:Liposomal and nanostructured carrier technologies face dense intellectual property landscapes that complicate independent formulation development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epigenetic Cosmetic Products Market |
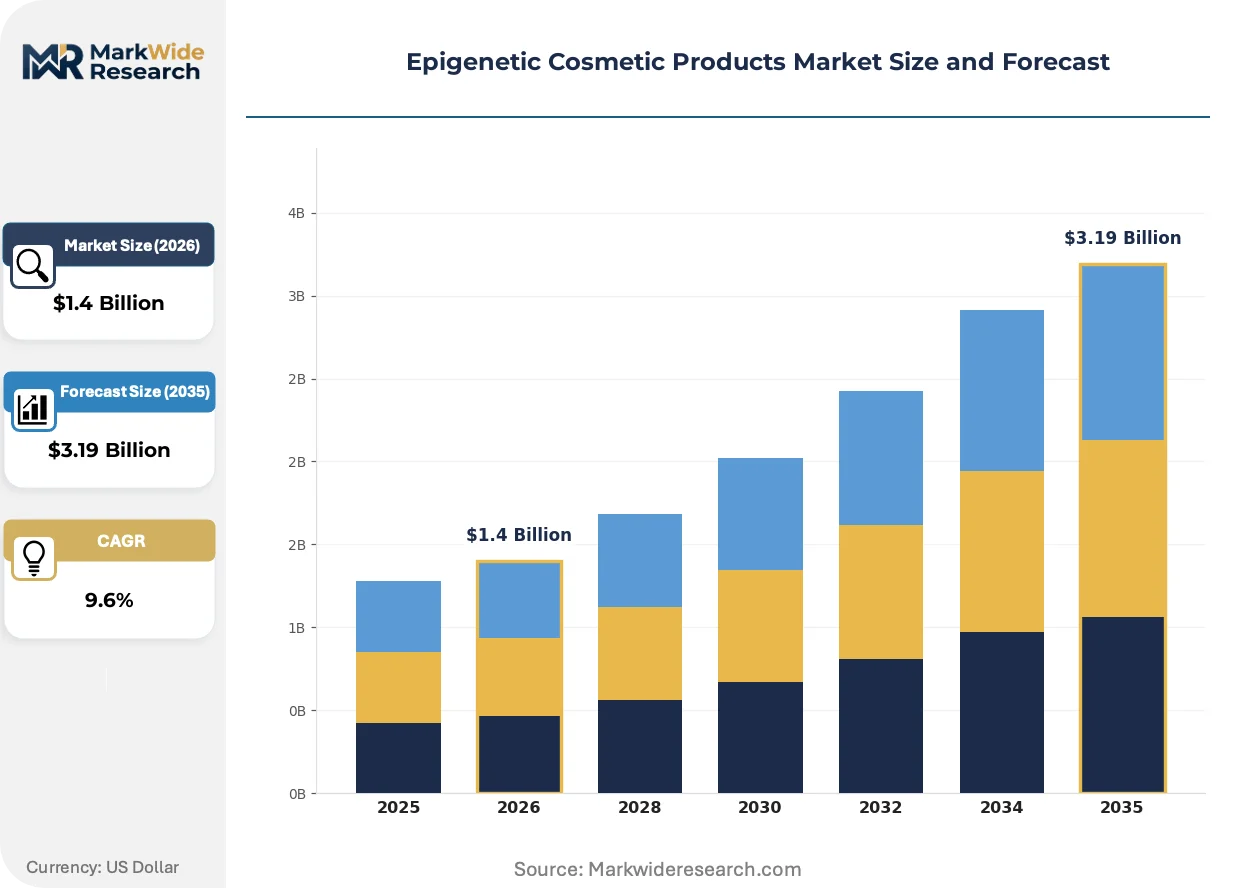
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.19 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serums, Creams, Masks, Oils Ingredient Source: Plant-based, Synthetic, Marine Extracts, Peptides Target Skin Concern: Aging, Hydration, Brightening, Sensitivity Distribution Channel: Online Retail, Specialty Stores, Department Stores, Salons |
| Companies Covered | L'Oréal Groupe, Estée Lauder Companies, Avon Products Inc., Biotique, Dermalogica India, TruDiagnostic, Skin Care Institute, Clinique, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epigenetic Cosmetic Products Market Shifts & Advancements
Biofermentation platforms and marine biotechnology are converging to displace conventional extraction methods, while regulatory frameworks in major jurisdictions are hardening around pre-market safety substantiation.
Marine-derived polyphenol production is expanding into controlled aquaculture systems that replace wild harvesting with batch-consistent cultivation. Korean and Norwegian biotechnology firms are deploying these platforms at commercial scale. This controlled sourcing is expanding into supply security guarantees that premium cosmetic houses require for multi-year formulation commitments.
REACH and the EU Cosmetics Regulation now mandate full toxicological dossiers for epigenetic actives, filtering out suppliers lacking analytical investment capacity. The industrial consequence is consolidation among ingredient houses capable of funding chronic toxicity studies. Serum and concentrated treatment categories face the steepest compliance cost escalation, accelerating private-label partnerships with established toxicological laboratories.
Clinical-channel credibility is rotating into direct-to-consumer marketing as dermatologist-endorsed protocols migrate to retail shelves. Medical spa protocols are being repackaged for home use, with Seoul-based brands leading this translation. Germany and South Korea represent the most visible geographies where professional endorsement structures are compressing traditional advertising expenditure models.
Epigenetic Cosmetic Products Market Segmentation
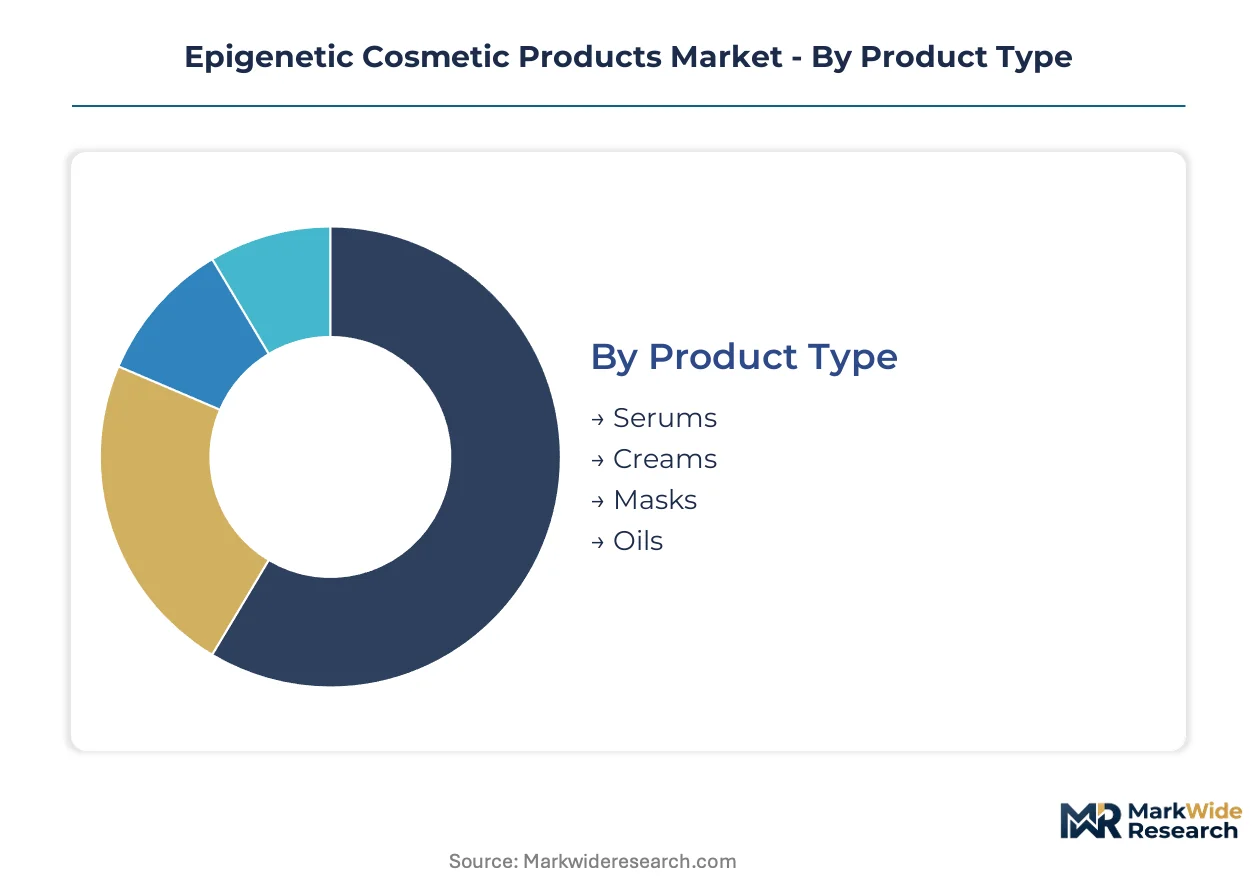
Epigenetic cosmetic segmentation reflects divergent consumer priorities around concentration tolerance, ethical sourcing preferences, and channel trust hierarchies. Manufacturers calibrate formulation investments across these dimensions to capture margin pools while managing regulatory compliance costs.
Product Type:
Buyers in this category segment by their willingness to pay for active loading density and absorption technology sophistication.
- Serums:Water-based formulations carry 0.5-5% bioactive polyphenol or peptide concentrations in liposomal delivery systems. Dermatology clinics in Seoul and Frankfurt drive professional-tier demand for biomarker-validated serum protocols.
- Creams:Emulsion-based vehicles accommodate broader consumer bases through lower irritation profiles and occlusive moisture retention. German precision manufacturers dominate cream formulation R&D for mass-premium hybrid positioning.
- Masks:Occlusive treatment formats concentrate actives for periodic intensive intervention rather than daily maintenance regimens.
- Oils:Lipid-soluble epigenetic compounds in squalane or jojoba carriers target barrier-compromised skin segments with dry-climate geographic concentration.
Serums lead volumes today; masks are gaining share fastest through medical spa protocol translation to home use.
Ingredient Source:
Raw material procurement strategies divide houses by sustainability certification requirements and supply security investment capacity.
- Plant-based:Polyphenol extraction from grape seed, green tea, and resveratrol-rich botanicals. Korean biotechnology firms deploy controlled cultivation to replace wild-harvested precursors.
- Marine Extracts:Controlled aquaculture systems in Norway and South Korea now supply fucoidan and astaxanthin with batch-consistent methylation-modulating activity. REACH dossier requirements filter out wild-harvest dependent suppliers.
- Synthetic:Laboratory-engineered epigenetic actives offer purity standardization for clinical-channel products requiring toxicological traceability.
- Peptides:Short-chain sequences targeting histone modification face pharmaceutical-sector demand competition for synthesis capacity.
Plant-based inputs retain volume leadership; marine extracts are expanding most quickly as sustainable biotechnology displaces conventional harvesting.
Target Skin Concern:
Clinical validation budgets concentrate where dermatologist endorsement transfers most directly to retail premiumization.
- Aging:Cellular senescence marker modulation through DNA methylation intervention commands the deepest R&D investment pools. Estée Lauder's biofermentation platforms anchor this segment's credibility architecture.
- Sensitivity:Barrier-function epigenetic products capture disproportionate growth as redness and reactivity concerns expand beyond traditional aging demographics. Seoul-based brands lead formulation translation from prescription to cosmetic channels.
- Hydration:Aquaporin expression modulation offers measurable claim substantiation through transepidermal water loss testing protocols.
- Brightening:Melanogenesis-regulating epigenetic actives face stricter quasi-drug classification scrutiny in multiple Asian jurisdictions.
Aging-focused SKUs dominate current revenue; sensitivity-targeted lines show the steepest expansion trajectory.
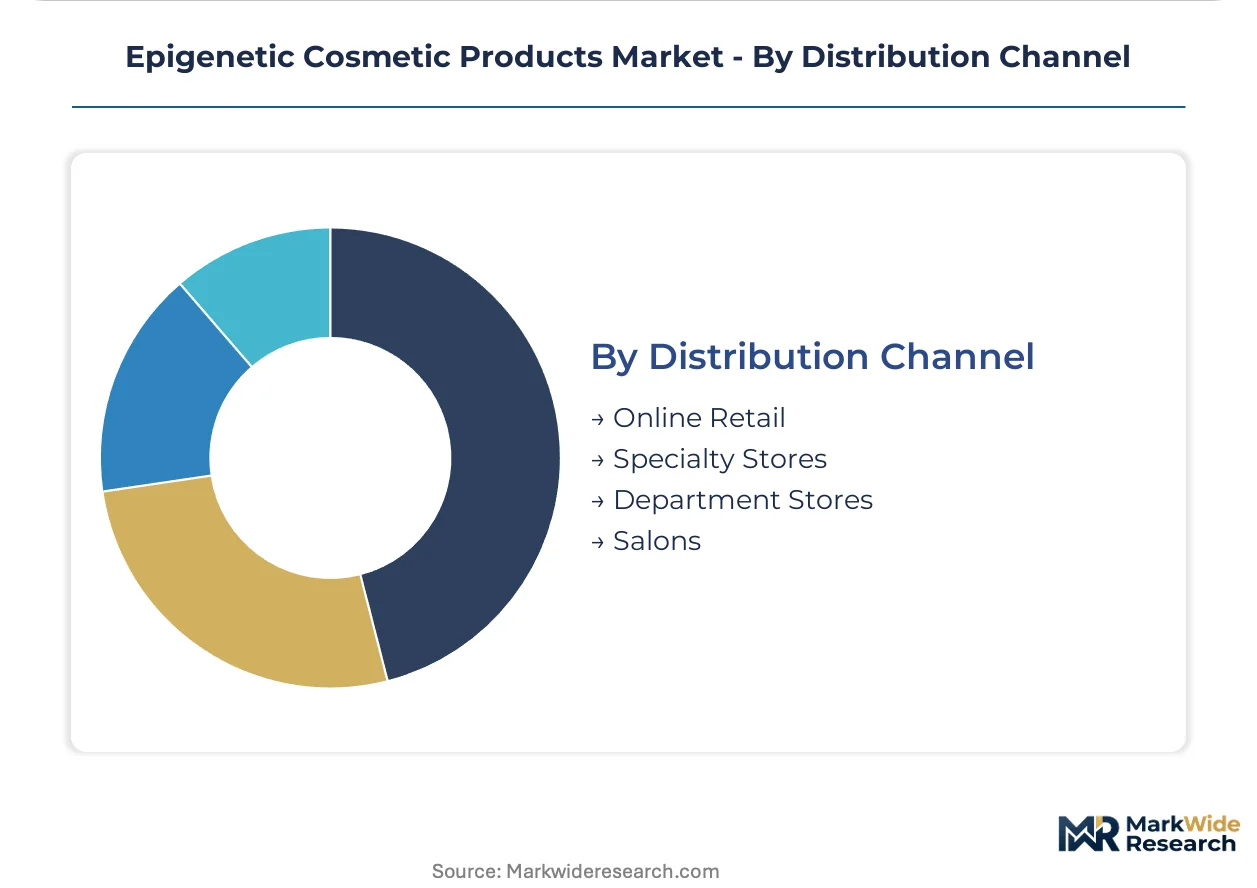
Distribution Channel:
Channel selection determines permissible claim language and required clinical substantiation depth.
- Specialty Stores:Sephora and Douglas-tier retailers demand pre-submitted safety dossiers and biomarker study summaries for epigenetic claim authorization. This channel concentrates premium pricing power.
- Online Retail:Direct-to-consumer platforms enable subscription models for serum replenishment but face intensifying FDA adverse event reporting scrutiny through the Cosmetic Modernization Act.
- Department Stores:Traditional counter models retain importance in Japan and South Korea where tactile sampling drives conversion for texture-sensitive cream formulations.
- Salons:Medical spa and aesthetic clinic channels transfer professional protocol credibility to retail-tier products through endorsed home-care extensions.
Specialty stores capture the largest value share; salon-channel distribution is climbing the fastest as clinical credibility compresses conventional advertising expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Seoul-Incheon beauty cluster outpaces German manufacturing corridors in epigenetic formulation velocity, while the United States concentrates dermatology-channel credibility transfer to retail shelves.
United States
FDA oversight through the Cosmetic Modernization Act tightens adverse event reporting requirements for epigenetic serums. Medical spa protocol translation to home-use products accelerates through Los Angeles and Miami aesthetic clinic networks. The Pacific Northwest hosts marine biotechnology partnerships supplying controlled aquaculture extracts to premium formulation houses.
Germany
REACH dossier mandates filter out peptide suppliers lacking chronic toxicity study capacity. The precision skincare manufacturing corridor between Düsseldorf and Frankfurt anchors DNA methylation-modulating compound production for downstream cosmetic houses. Bavarian biotechnology clusters deploy biofermentation platforms at commercial scale for polyphenol standardization.
South Korea
MFDS cosmetic registration pathways for novel bioactive ingredients create first-mover advantages for pre-submitted safety dossiers. Seoul-Incheon contract development organizations offer Asian market entry capacity without captive facility investment. Sensitivity-targeted epigenetic formulations lead prescription-to-cosmetic channel translation.
China
NMPA novel ingredient rules impose dual-track compliance costs on multinational epigenetic portfolios. Yangtze River Delta manufacturing infrastructure concentrates marine extract processing for domestic and export markets. Shanghai-based dermatology clinics validate biomarker modulation claims for retail-tier product authorization.
France
ANSM oversight of quasi-drug classification boundaries determines clinical substantiation budgets for epigenetic brightening claims. Paris-Sophia Antipolis corridors anchor L'Oréal Groupe's integrated dermatology research network for active compound validation. Île-de-France specialty retailers demand pre-submitted biomarker study summaries for shelf placement authorization.
Epigenetic Cosmetic Products Market Competitive Landscape
Top-tier vendors anchor integrated dermatology research networks, while mid-tier peptide houses struggle with toxicological investment capacity. The vendor base stratifies across three tiers: multinational cosmetic conglomerates with captive biofermentation platforms, specialized ingredient suppliers controlling upstream DNA methylation-modulating compound production, and regional contract manufacturers serving private-label demand. Strategic moves concentrate on clinical validation pipeline partnerships and controlled aquaculture supply security guarantees.
Within the multinational tier, L'Oréal Groupe and Estée Lauder Companies occupy positions defined by proprietary platform differentiation rather than off-the-shelf sourcing. Merck KGaA anchors the upstream ingredient layer as a German-based chemical conglomerate supplying methylation-modulating compounds across downstream cosmetic houses. These three entities exemplify the structural division between formulation credibility, biofermentation scale, and chemical synthesis control that characterizes competitive positioning in epigenetic skincare.
| Leading Market Players |
|---|
| L'Oréal Groupe |
| Estée Lauder Companies |
| Avon Products Inc. |
| Biotique |
| Dermalogica India |
| TruDiagnostic |
| Skin Care Institute |
| Clinique |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Captive biofermentation capacity anchors pricing power for serum-tier epigenetic formulations, as houses with in-house polyphenol standardization command premium positioning against peptide-dependent competitors facing pharmaceutical-sector synthesis competition. REACH dossier investments create fixed-cost barriers that stratify the vendor base between toxicology-capable suppliers and reformulation-challenged mid-tier houses.
Pricing Analysis
Capacity additions in South Korea's controlled aquaculture facilities are reshaping price floors for marine-derived epigenetic actives, compressing wild-harvest premium tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by biomarker validation depth and delivery system sophistication. Cost compression in mid-tier peptide formulations is intensifying because pharmaceutical-sector demand competition for synthesis capacity squeezes margins. Dermatology clinics show least price sensitivity; mass-market retail channels exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Seoul-Incheon and Düsseldorf-Frankfurt operate as hub-and-spoke nodes for epigenetic active compounds. Upstream production clusters in Germany, South Korea, and Switzerland anchor DNA methylation-modulating compound supply. Raw material dependencies center on fucoidan-rich seaweed cultivars, short-chain peptide precursors, and resveratrol-standardized botanicals. Single-source vulnerability concentrates in Swiss-German chemical corridors for histone-modulating actives. Distribution runs through specialty retail and medical spa channels with batch-level traceability mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor houses with captive biotechnology infrastructure, as controlled aquaculture sourcing and biofermentation scale displace higher-cost wild-harvest and outsourced peptide dependencies.
For Market Incumbents: Extend clinical validation pipelines into sensitivity-targeted formulations before Seoul-based competitors consolidate prescription-to-cosmetic translation advantages. Deepen backward integration into controlled aquaculture partnerships in Norway and South Korea to secure fucoidan supply continuity against pharmaceutical-sector peptide synthesis competition. Anchor dermatology clinic channel exclusivity through biomarker study co-development that raises retail-tier claim substantiation barriers.
For New Entrants and Emerging Players: Medical spa channel partnerships offer the most penetrable entry vector for professional-protocol credibility transfer without captive R&D infrastructure. Target white space in barrier-function epigenetic products for reactive skin demographics underserved by aging-focused incumbent SKUs. Pursue contract manufacturing arrangements with Seoul-Incheon development organizations to bypass facility capital requirements while accessing MFDS registration expertise.
For Investors and Strategic Acquirers: Roll-up economics work for toxicology-capable peptide houses because REACH compliance investments have already filtered out sub-scale competitors, leaving acquisition targets with embedded regulatory moats. Mid-tier formulation houses with pre-submitted NMPA dossiers represent priority targets for Asian market access. Watch for inflection when marine biotechnology platforms achieve cost parity with conventional extraction, signaling margin structure reset.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled Aquaculture Partnership | Secures batch-consistent fucoidan supply for REACH-compliant polyphenol formulations. |
| Biomarker Validation Pipeline | Builds dermatology clinic credibility transferable to retail shelf positioning. |
| MFDS Pre-Submission Dossier | Creates first-mover advantage for novel bioactive ingredient registration in South Korea. |
| Medical Spa Channel Alliance | Compresses conventional advertising expenditure through professional endorsement structures. |
| Peptide Synthesis Backward Integration | Insulates margin pools from pharmaceutical-sector capacity competition. |
Research Methodology
Bottom-up serum and cream formulation modeling reconciled against top-down ingredient supply tracking forms the analytical core of this study. Primary interviews with dermatology clinic procurement directors, cosmetic house formulation chemists, marine biotechnology facility managers, and REACH compliance officers combined with secondary validation from ECHA substance dossiers, MFDS cosmetic registration databases, and Korean biotechnology trade association filings. Cross-referencing of customs records for epigenetic active compound trade flows against manufacturer capacity disclosures enabled supply-side triangulation.
Historical trendline analysis of biomarker-validated product launches and regulatory submission timelines informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type concentration tier, ingredient source sustainability certification, target skin concern clinical validation depth, and distribution channel claim authorization requirements. CAGRs derived from volume-weighted average of segment growth trajectories, incorporating marine biotechnology cost curves and peptide synthesis capacity utilization as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between cosmetic and quasi-drug classification regimes, marine cultivation yield variability, and pharmaceutical-sector peptide demand cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Organic Makeup Remover Market
Cosmetics & Skincare
E Commerce Cosmetic and Fragrance Market
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market
Cosmetics & Skincare
Organic Color Cosmetics Products Market
Cosmetics & Skincare
BB Cream Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
Moisturizing Spray Market
Cosmetics & Skincare
Lip Products Pigment Market
Cosmetics & Skincare
Eyeliner Industry Status and Prospects Professional Market
Cosmetics & Skincare
Natural and Organic Lipstick Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
Foundation Cream Market
Cosmetics & Skincare
Lipstick Market
Cosmetics & Skincare
Waterproof Eyebrow Liner Market
Cosmetics & Skincare
Israel Cosmetics Products Market