
 Private Label Cosmetics Market | 2026-2036
Private Label Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Private Label Cosmetics Market Insights
Specialty retailers and direct-to-consumer brands is bifurcating demand away from traditional mass-market grocers, forcing contract manufacturers to reconfigure capacity and service models. Fareva leverages its European manufacturing footprint to serve premium private-label skincare lines. Cosmax anchors its position through dedicated R&D centers in Seoul that support K-beauty-inspired formulations for Western retailers. Intercos competes by controlling color cosmetics innovation pipelines across Italy and the United States.
Private label cosmetics comprise formulations manufactured by third-party producers and sold under a retailer's or brand's own trademark, typically involving custom ingredient decks, stability testing, and compliance with regional cosmetic safety standards. These products serve commercial purposes ranging from margin expansion for retailers to market-entry vehicles for digital-native brands. Skincare commands the deepest margin pools as consumers associate retailer-exclusive serums and creams with clinical efficacy, while haircare represents the most mature segment with established supply chains and slower innovation cycles. Online Retail channels are capturing the fastest growth as TikTok and Instagram-native brands bypass traditional shelf-space negotiations.
FDA cosmetic regulations under the Modernization of Cosmetics Regulation Act and EU REACH compliance requirements now mandate fragrance allergen disclosure and substantiated safety claims, raising barriers for new contract manufacturers. ISO 22716 Good Manufacturing Practices certification has become a baseline qualifier for supplier qualification by major retailers rather than a differentiator. Stakeholders must monitor how evolving state-level ingredient bans in California and New York reshape permissible formulation palettes ahead of federal alignment.
Market Dynamics
Clean beauty certification requirements and EU REACH compliance are forcing contract manufacturers to rebuild formulation pipelines around disclosed fragrance allergens and substantiated safety claims. This regulatory compression favors scaled producers with dedicated regulatory affairs teams over smaller regional competitors.
Growth Catalysts
- EU REACH compliance:Mandatory fragrance allergen disclosure is accelerating retailer demand for pre-certified manufacturing partners, consolidating procurement toward established contract manufacturers with European laboratory infrastructure.
- Direct-to-consumer channel expansion:TikTok-native brands require small-batch, fast-turn production capabilities that traditional mass-market suppliers cannot accommodate, creating dedicated capacity investments by specialty contract manufacturers.
- Biotechnology-derived actives:Lab-grown ceramides and fermented extracts are replacing petroleum-based emollients in premium private-label skincare, enabling margin expansion through clinical-positioned ingredient storytelling.
Market Restraints
- Raw material concentration:Specialty surfactant and active ingredient supply concentrates among German and Swiss chemical producers, exposing margin pressure from euro-denominated input volatility.
- ISO 22716 certification timeline:Good Manufacturing Practices qualification requires 12-18 month facility audits, creating a structural barrier for new contract manufacturers seeking entry into major retailer supply bases.
- Silicone substitution pressure:Clean beauty formulators are eliminating cyclopentasiloxane and dimethicone, forcing costly reformulation of established haircare and skincare bases without equivalent performance substitutes at scale.
Strategic Opportunities
- Indian domestic market penetration:BIS cosmetic safety standards alignment with international norms is enabling Western private-label brands to access India's organized retail expansion through local contract manufacturing partnerships.
- Refill and concentrated formats:Waterless beauty pods and solid shampoo bars are opening shelf-space negotiations with sustainability-positioned specialty retailers seeking packaging waste reduction credentials.
- AI-driven formulation optimization:Machine learning platforms predicting stability and skin penetration are compressing R&D cycles from months to weeks for digital-native brands with limited technical staff.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation scientists with dual expertise in clean ingredient compliance and scale-up manufacturing are concentrated among senior staff at established producers, constraining expansion timelines.
- Legacy ERP integration:Batch record systems at mid-sized contract manufacturers require manual data entry for traceability compliance, creating friction with retailer demands for real-time supply chain visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Label Cosmetics Market |
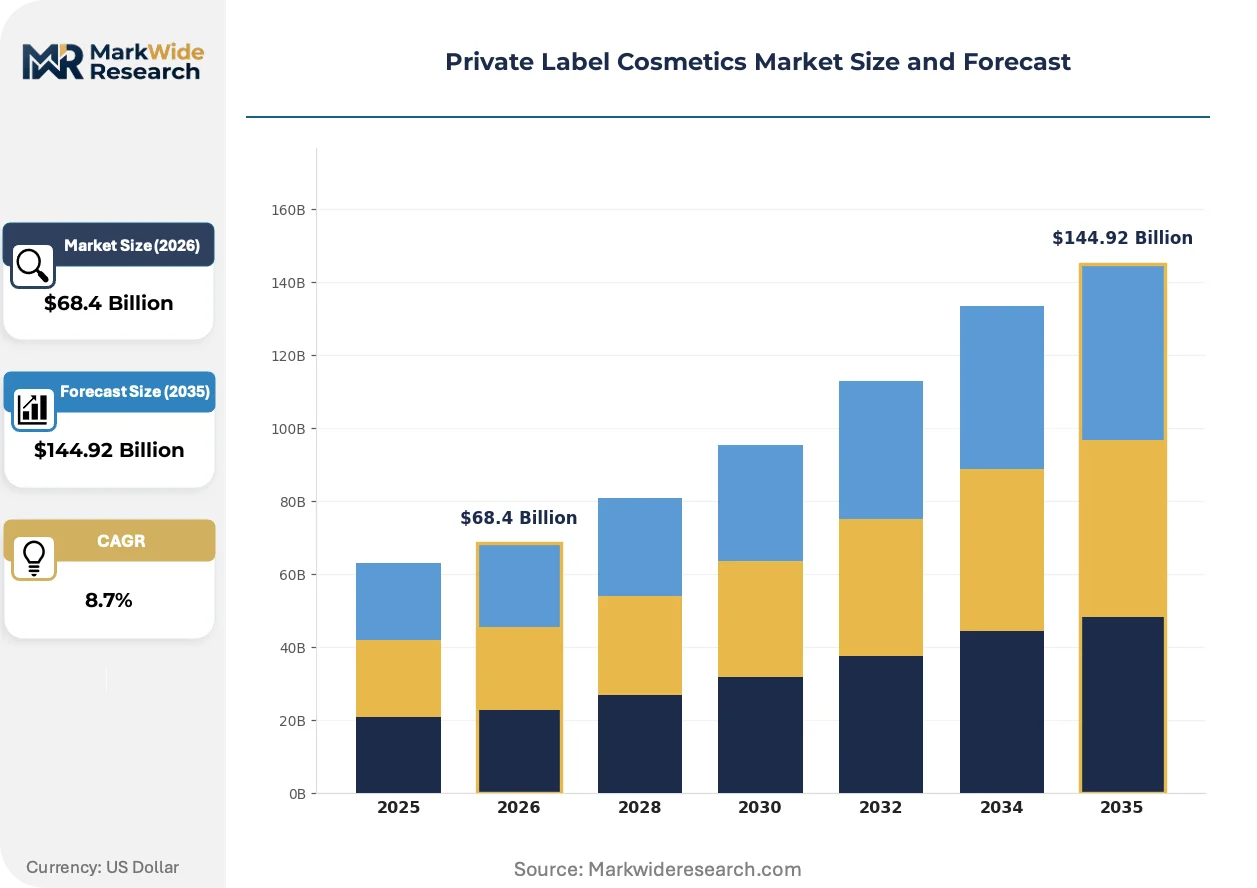
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Makeup, Skincare, Fragrance, Haircare Packaging Type: Tubes, Jars, Bottles, Compacts Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores Price Tier: Economy, Premium, Luxury, Mid-Range |
| Companies Covered | Fareva, Mana Products, Cosmax, Cosmetic Solutions, Lady Burd, Intercos, HSA Cosmetics, RainShadow Labs, Kolmar Korea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Label Cosmetics Market Trends and Innovations
Biotechnology, regulatory transparency mandates, and channel fragmentation are simultaneously compressing production timelines and elevating technical requirements across private-label cosmetics manufacturing.
Biotechnology-derived active ingredients are bifurcating the supplier base between fermentation-capable producers and traditional chemical synthesis operations. Direct-to-consumer brands in North America and Western Europe are adopting lab-grown squalane and postbiotic complexes at three times the rate of mass-market retailers. This technology shift is compressing minimum order quantities while expanding margin pools for manufacturers with in-house bioreactor capacity.
EU REACH annex amendments now mandate individual fragrance allergen labeling above 0.001% concentration in leave-on products, forcing reformulation of legacy perfume bases. The industrial consequence is a surge in fragrance-free and naturally-scented positioning among private-label skincare lines. South Korean contract manufacturers serving Western retailers are most affected, accelerating investment in European regulatory affairs staffing to maintain market access.
Retailer procurement teams are consolidating supplier relationships around full-service partners capable of stability testing, regulatory filing, and packaging sourcing under single contracts. This behavior change is displacing fragmented multi-vendor arrangements common five years ago. The shift is most visible among specialty beauty retailers in Germany and France seeking to reduce compliance coordination overhead across distributed brand portfolios.
Private Label Cosmetics Market Segmentation
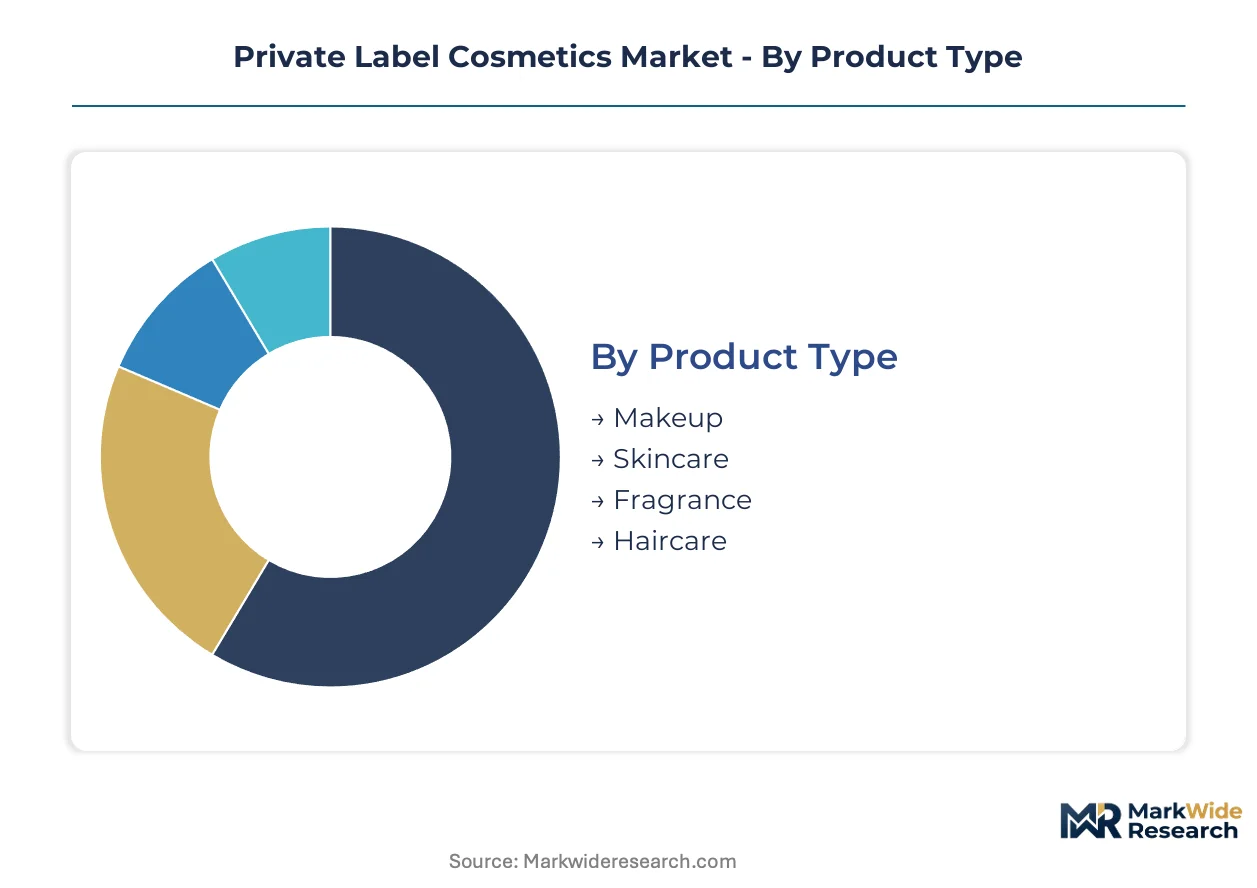
Segmentation in private label cosmetics reveals how formulation complexity, packaging requirements, and channel economics create distinct procurement patterns. Each dimension carries implications for minimum order quantities, regulatory documentation, and margin structures that shape contract manufacturer selection.
Product Type:
Channel-mix dynamics vary sharply across product categories, with skincare and makeup flowing predominantly through specialty retail and direct-to-consumer platforms while haircare and fragrance maintain stronger supermarket penetration.
- Makeup:Color cosmetics require extensive shade-matching capabilities and batch-to-batch consistency protocols that strain smaller contract manufacturers. Demand concentrates among TikTok-native brands seeking rapid SKU rotation with six-week turnaround cycles that traditional suppliers cannot execute.
- Skincare:Serums, moisturizers, and treatment products command the deepest margin pools due to clinical efficacy positioning and biotechnology-derived active ingredients. South Korean contract manufacturers anchor formulation leadership here, serving Western retailers with fermented extracts and lab-grown ceramides.
- Fragrance:EU REACH fragrance allergen disclosure mandates have compressed private-label participation as reformulation costs escalate; fragrance-free positioning now dominates retailer-exclusive scent categories.
- Haircare:Established supply chains and slower innovation cycles characterize this mature segment, with silicone substitution pressures forcing costly base reformulations without equivalent performance substitutes at scale.
Haircare dominates installed base. Skincare is where expansion concentrates.
Packaging Type:
Cost tier differentiation runs through packaging selection, with luxury price tiers demanding airless pump systems and weighted glass while economy segments accept standard polymer tubes and jars.
- Tubes:Laminated and extruded plastic tubes serve high-volume haircare and skincare applications with efficient filling-line compatibility; sustainability-positioned retailers are driving demand for mono-material recyclable tube structures.
- Jars:Thick-walled glass and premium polymer jars anchor skincare positioning across premium and luxury tiers, with refillable jar systems gaining traction among German and French specialty retailers seeking packaging waste reduction credentials.
- Bottles:PET and glass bottles with treatment pumps or flip-cap closures span shampoo, conditioner, and body care categories; lightweighting initiatives are reducing resin content per unit without structural compromise.
- Compacts:Pressed powder and cushion compact formats require precision molding capabilities concentrated among specialized packaging suppliers in Italy and South Korea.
Jars dominate installed base. Tubes are expanding most quickly.
Distribution Channel:
Customer-type segmentation separates mass-market grocers seeking scale efficiencies from digital-native brands requiring small-batch flexibility and rapid formulation iteration.
- Online Retail:Direct-to-consumer brands bypass traditional shelf-space negotiations through TikTok and Instagram-native launches, demanding minimum order quantities below five thousand units and turnaround cycles compressed to four weeks.
- Supermarkets:Mass-market grocers prioritize cost engineering and supply security, with procurement teams consolidating around full-service contract manufacturers capable of stability testing and regulatory filing under single contracts.
- Pharmacies:Drugstore channels in Germany and France emphasize dermocosmetic positioning with substantiated safety claims and ISO 22716 certification as baseline qualifiers.
- Specialty Stores:Sephora, Ulta, and comparable specialty retailers represent the fastest-expanding buyer segment, bifurcating demand away from traditional mass-market channels and forcing contract manufacturers to reconfigure service models.
Supermarkets dominate installed base. Online Retail is where expansion concentrates.
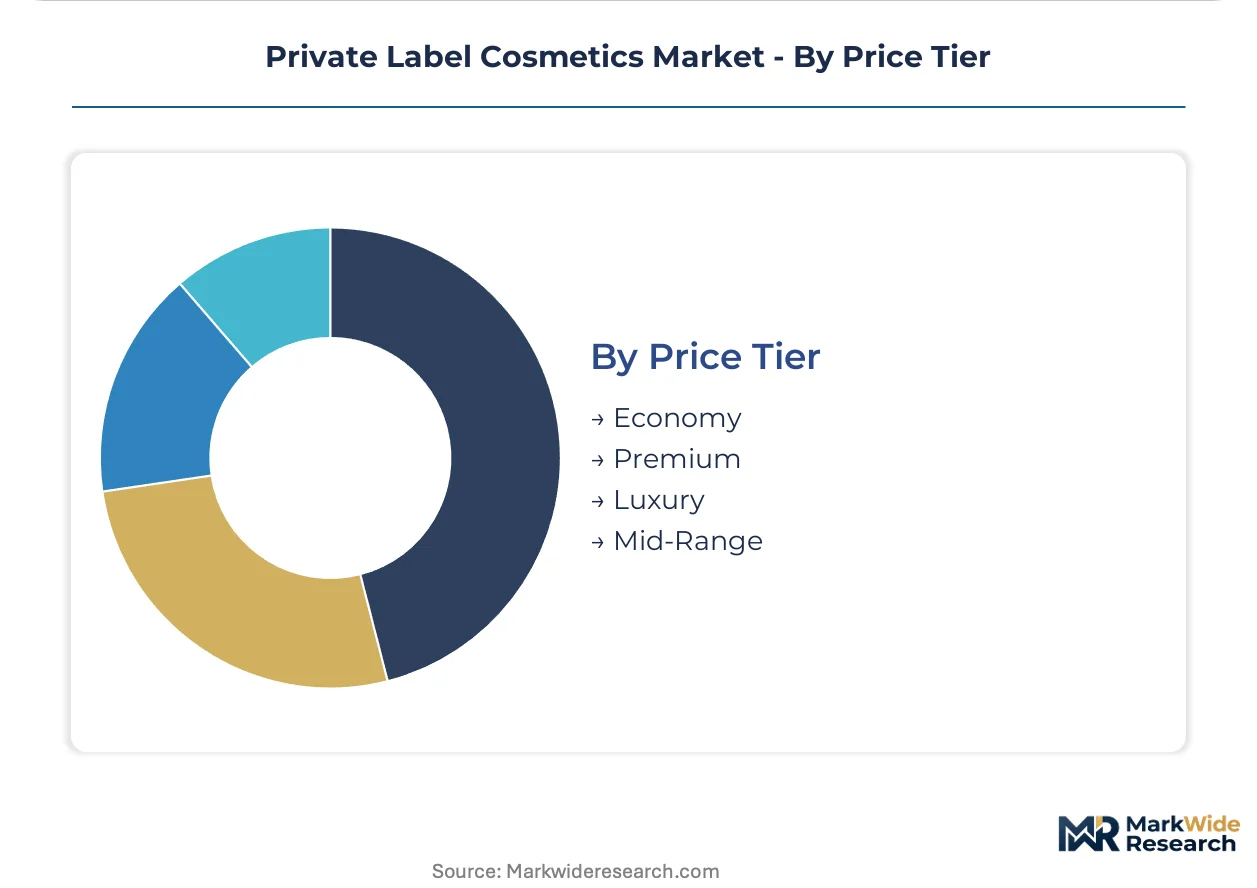
Price Tier:
Margin stratification across price tiers reflects ingredient grade concentration, with biotechnology-derived actives and clean beauty certifications reserved for premium and luxury positioning.
- Economy:Value-positioned formulations rely on established petrochemical emollients and standard preservative systems with minimal marketing claim support; procurement concentrates among high-volume retailers in India's organized retail expansion.
- Mid-Range:This tier captures the broadest retail footprint, balancing performance positioning with accessible price points through hybrid natural-synthetic ingredient decks.
- Premium:Clinical efficacy claims and disclosed fragrance allergen compliance define this tier, with Fareva and Cosmax anchoring supply through dedicated R&D centers and European regulatory affairs infrastructure.
- Luxury:Weighted packaging, single-origin ingredient storytelling, and limited production runs characterize this segment, with Italian and French contract manufacturers controlling color cosmetics innovation pipelines here.
Mid-Range dominates installed base. Premium is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's contract manufacturing corridor exports K-beauty-inspired formulations to Western specialty retailers and direct-to-consumer brands. This trade flow anchors the fastest-expanding segment of private-label cosmetics procurement.
United States
TikTok-native brands drive demand for small-batch, fast-turn production capabilities that traditional mass-market suppliers cannot accommodate. FDA cosmetic regulations under the Modernization of Cosmetics Regulation Act mandate substantiated safety claims and fragrance allergen disclosure. California's state-level ingredient bans are reshaping permissible formulation palettes ahead of federal alignment, with Los Angeles-based contract manufacturers investing in clean beauty certification infrastructure.
South Korea
Fermented extracts and lab-grown ceramides from Seoul's R&D centers serve Western retailers seeking clinical efficacy positioning. MFDS cosmetic safety standards align with international norms, enabling export-oriented production. The Seoul Capital Area concentrates dedicated bioreactor capacity and regulatory affairs staffing to maintain EU REACH compliance for European market access.
Germany
Pharmacy-channel dermocosmetic positioning emphasizes ISO 22716 Good Manufacturing Practices certification as baseline qualifier for supplier qualification. ECHA REACH annex amendments mandate individual fragrance allergen labeling above threshold concentrations. North Rhine-Westphalia hosts full-service contract manufacturers capable of stability testing, regulatory filing, and packaging sourcing under single contracts.
France
Specialty retailers consolidate procurement around partners reducing compliance coordination overhead across distributed brand portfolios. ANSM enforces cosmetic safety standards with emphasis on substantiated marketing claims. The Île-de-France region anchors color cosmetics innovation pipelines serving luxury private-label positioning with precision molding capabilities.
India
BIS cosmetic safety standards alignment with international norms enables Western private-label brands to access organized retail expansion. The country's national pharmaceutical regulator maintains harmonized requirements for imported formulations. Maharashtra and Gujarat host local contract manufacturing partnerships serving domestic market penetration strategies.
Private Label Cosmetics Market Competitive Landscape
Listed leaders compete with private specialists across regulatory affairs infrastructure and bioreactor capacity. The supplier base concentrates around scaled producers with dedicated European laboratory infrastructure, displacing fragmented multi-vendor arrangements common five years ago. Three archetypes dominate: full-service partners controlling stability testing and packaging sourcing; fermentation-capable biotechnology specialists; and regional manufacturers serving fast-turn digital-native brands. Competitive moves center on M&A to acquire regulatory affairs teams and capacity expansion into small-batch flexible production lines.
Among European-based manufacturers, Fareva exemplifies the full-service archetype with continental manufacturing footprint. Cosmax anchors the biotechnology-specialist tier through Seoul-based R&D centers. Intercos occupies a position within color cosmetics innovation, representing the precision-molding and shade-matching capabilities concentrated in Italy.
| Leading Market Players |
|---|
| Fareva |
| Mana Products |
| Cosmax |
| Cosmetic Solutions |
| Lady Burd |
| Intercos |
| HSA Cosmetics |
| RainShadow Labs |
| Kolmar Korea |
| Others |
Pricing and Supply Chain Analysis
Minimum viable scale for bioreactor capacity utilization anchors price floors across private-label cosmetics manufacturing, with fermentation-capable producers commanding premium positioning while smaller compounders absorb margin compression from underutilized cleanroom assets.
Pricing Analysis
Next-generation biotechnology-derived actives command 40-60% premiums over petroleum-based emollients, while legacy silicone-based formulations face price erosion from clean beauty substitution mandates. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with ISO 22716 compliance and EU REACH pre-certification separating premium tiers. Pricing pressure stems from euro-denominated specialty surfactant volatility. Mass-market grocers exhibit highest price sensitivity; luxury private-label positioning shows lowest elasticity.
Supply Chain Analysis
Inbound logistics costs from Rotterdam and Hamburg port congestion elevate landed costs for German and Swiss chemical inputs, compressing margins on just-in-time formulations. Supply concentrates in South Korea, Germany, and Italy, with Seoul anchoring bioreactor capacity, North Rhine-Westphalia hosting regulatory affairs infrastructure, and Lombardy controlling precision molding. Specialty surfactants, lab-grown ceramides, and fragrance allergen-compliant bases constitute critical dependencies. Single-source vulnerability runs through concentrated German chemical producers. Distribution runs through full-service contract manufacturers consolidating previously fragmented multi-vendor arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation scientists with dual expertise in clean ingredient compliance and scale-up manufacturing represent the scarcest capability layer, constraining expansion timelines and consolidating competitive advantage among established producers with senior technical staff retention.
For Market Incumbents: Consolidate regulatory affairs infrastructure through dedicated European laboratory staffing to maintain EU REACH compliance velocity against emerging biotechnology specialists. Acquire small-batch flexible production lines to serve TikTok-native brands bypassing traditional mass-market suppliers. Vertical integration into captive bioreactor capacity defends margin position against fermentation-capable competitors. For New Entrants and Emerging Players: Differentiate on AI-driven formulation optimization serving digital-native brands with compressed R&D cycles and limited technical staff. Target India's organized retail expansion through BIS-aligned local contract manufacturing partnerships. Pursue waterless beauty formats opening shelf-space negotiations with sustainability-positioned German and French specialty retailers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors full-service contract manufacturers with stability testing, regulatory filing, and packaging sourcing under single contracts. Long-term viability hinges on bioreactor capacity and European regulatory affairs staffing rather than regional manufacturing footprint alone. Monitor MFDS-EU regulatory harmonization progress as inflection indicator for South Korean export-oriented production scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | Fermentation-capable producers capture margin pools from lab-grown ceramides and postbiotic complexes. |
| EU REACH Regulatory Affairs Staffing | Pre-certified manufacturing partners consolidate procurement from retailers seeking compliance coordination reduction. |
| Small-Batch Flexible Production Lines | Four-week turnaround capabilities serve TikTok-native brands with sub-five-thousand-unit minimum orders. |
| AI-Driven Formulation Platforms | Machine learning compresses R&D cycles from months to weeks for technical-staff-constrained digital brands. |
| Waterless Format Development | Solid shampoo bars and beauty pods unlock sustainability-positioned specialty retail shelf-space negotiations. |
Research Methodology
A standing panel of contract manufacturing executives, regulatory affairs leads at European laboratories, specialty retailer procurement managers, and formulation scientists provided ongoing calibration across primary fieldwork. Secondary validation drew from MFDS cosmetic safety filings, ECHA REACH annex amendments, FDA Modernization of Cosmetics Regulation Act guidance documents, and customs trade data tracking K-beauty export flows. Bottom-up capacity utilization models and top-down retailer procurement surveys underwent iterative triangulation.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled included product type, packaging format, distribution channel, and price tier alongside regulatory compliance cluster. CAGRs derived from facility capacity expansion announcements, retailer private-label penetration rates, and biotechnology ingredient adoption curves. Forecast inputs incorporated EU fragrance allergen disclosure implementation timelines and state-level ingredient ban progression patterns.
The analysis sits within stated boundaries; outcomes outside sustained clean beauty certification momentum and EU-Asia regulatory harmonization would require recalibration. Forecasts reflect documented assumptions regarding specialty surfactant supply stability and digital-native brand formation rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Beauty Pillowcases Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Shower Gel Market
Beauty & Personal Care
Intimate Hygiene Products Market
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Herbal Shampoo Market
Beauty & Personal Care
Luxury Cosmetics Market
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Hair Removal Products Market
Beauty & Personal Care
DIY Haircut Kits Market
Beauty & Personal Care
India Hair Oil Market
Beauty & Personal Care
Pre-Shave Care Market
Beauty & Personal Care
Emea Beauty Devices Market
Beauty & Personal Care
Lip Care Products Market
Beauty & Personal Care
Nail Strengtheners Market
Beauty & Personal Care
Australia Beauty and Personal Care Products Market