
 Matte Lipstick Market | 2026-2036
Matte Lipstick Market Size, Share, and Industry Trends Forecast 2026-2036
Matte Lipstick Market Insights
Professional makeup artistry and social media content creation is recalibrating demand toward long-wear, camera-ready formulations. L'Oréal leverages its dermatological research infrastructure to develop transfer-resistant matte polymers. MAC Cosmetics anchors its professional channel dominance through artist-education programs and backstage sponsorships. Shiseido competes in Asia-Pacific prestige counters with hybrid skincare-lipcare positioning.
Matte lipstick denotes a pigmented lip cosmetic engineered with high concentrations of volatile silicones, wax blends, and spherical powders to deliver a flat, light-absorbing finish with minimal reflectance. The formulation typically incorporates isododecane or cyclopentasiloxane as film-forming agents that evaporate post-application, leaving concentrated colorants bound to the lip surface for extended wear. Liquid formats lead volume due to their precision applicators and social media visual appeal, while bullet formats retain margin strength in prestige retail where tactile luxury signals quality. Cream-to-matte hybrids within the semi-matte finish category represent the fastest-growing segment as consumers seek comfort without sacrificing the aesthetic.
FDA color additive regulations govern permissible pigments in US-marketed matte lipsticks, directly constraining formulation palettes for brands selling cross-border. The EU REACH framework and subsequent microplastic restrictions further limit glitter and certain film-forming polymers, pushing reformulation investment toward biodegradable alternatives. India's BIS cosmetics standards create additional compliance layers for imported finished goods. Stakeholders must monitor evolving state-level ingredient disclosure mandates in California and New York, as these sub-national rules increasingly dictate national formulation baselines through market scale effects.
Market Dynamics
Social media-driven beauty tutorials among Gen Z consumers are recalibrating how brands formulate and market matte lip products, forcing accelerated innovation cycles in film-forming polymer chemistry and transfer-resistant finishes.
Growth Catalysts
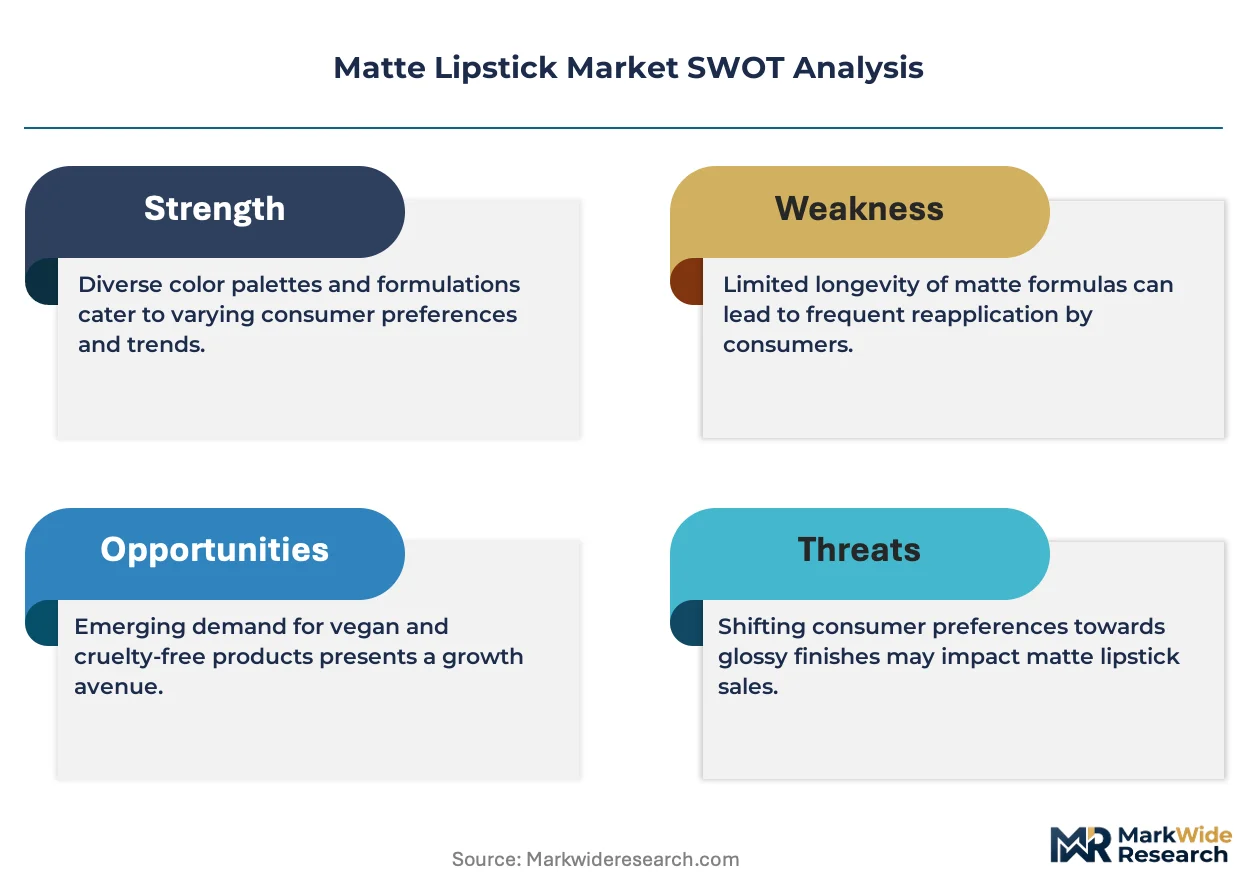
- EU REACH microplastic restrictions:The regulation is pushing manufacturers toward biodegradable film-forming alternatives, creating first-mover advantages for suppliers with bio-based polymer pipelines.
- Content creator economy:Professional makeup artistry and social media content creation is recalibrating demand toward long-wear, camera-ready formulations that perform under high-definition lighting.
- India's tier-one cities:Mass-premium hybrid brands are expanding retail footprints aggressively in Mumbai, Delhi, and Bangalore, concentrating visible demand growth in these urban clusters.
Market Restraints
- Isododecane price volatility:This key volatile silicone feedstock experiences supply tightness from specialty chemical producers, compressing formulation margins for mid-tier brands.
- FDA color additive constraints:The regulatory framework governing permissible pigments directly limits formulation palettes for brands selling cross-border into the United States.
- Film-forming polymer substitution:Traditional cyclopentasiloxane-based systems face displacement pressure from water-based and hybrid alternatives, stranding existing inventory investments.
Strategic Opportunities
- India's tier-two expansion:Underpenetrated cities such as Pune, Hyderabad, and Chennai present whitespace for mass-premium hybrid distribution models.
- Cream-to-matte hybrid segment:This fastest-growing finish category combines comfort aesthetics with matte visual appeal, opening formulation differentiation for skincare-lipcare positioning.
- California ingredient disclosure mandates:State-level transparency requirements are creating compliance-as-service opportunities for formulation houses serving multi-market brands.
Industry Challenges
- Polymer chemistry talent scarcity:Formulation scientists with expertise in volatile silicone evaporation dynamics and spherical powder suspension remain concentrated among legacy suppliers.
- Multi-jurisdiction compliance timelines:Simultaneous navigation of FDA, EU REACH, and India's BIS cosmetics standards extends product launch cycles and strains regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Matte Lipstick Market |
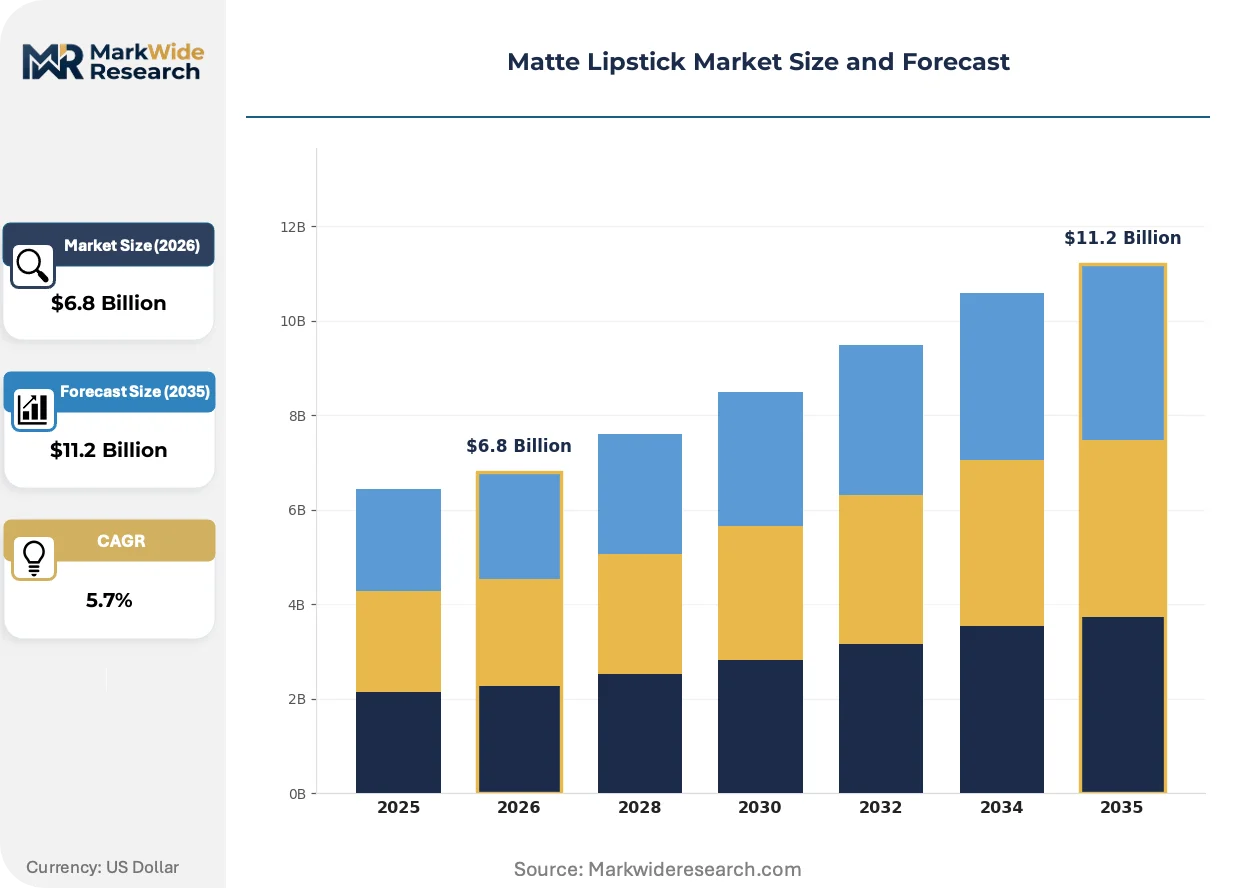
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Bullet, Pencil, Cream Finish: Matte, Semi-Matte, Velvet, Satin Application Area: Lips, Face, Eyes, Cheeks Skin Type: Oily, Dry, Combination, Normal |
| Companies Covered | L'Oréal, Estée Lauder Companies, Revlon, Coty, Shiseido, Procter & Gamble, Chanel, MAC Cosmetics, NARS Cosmetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Matte Lipstick Market Trends and Innovations
Formulation chemistry, regulatory compliance architecture, and content-driven distribution models are converging to reshape competitive positioning in matte lip cosmetics.
Micro-encapsulated color release systems are decentralizing the traditional trade-off between comfort and wear duration in matte formulations. Premium brands in South Korea and the United States are adopting these systems at accelerated pace for seasonal collections. The technology is decentralizing formulation R&D from centralized corporate labs toward specialized encapsulation technology suppliers.
EU REACH framework expansions on microplastic restrictions are eliminating glitter and certain non-biodegradable film-forming polymers from permitted ingredient lists. Export-oriented manufacturers serving European markets are reformulating entire product lines to maintain market access. Liquid matte formats with high polymer loads face the steepest compliance costs and are responding fastest with bio-based alternative sourcing.
Direct-to-consumer sampling through short-form video platforms is compressing traditional retail discovery cycles for new matte launches. Influencer-seeded trial is displacing counter-based testing in prestige channels across Gen Z demographics. This behavioral shift is most visible in India's urban centers and among Southeast Asian markets where mobile commerce penetration exceeds developed-market benchmarks.
Matte Lipstick Market Segmentation
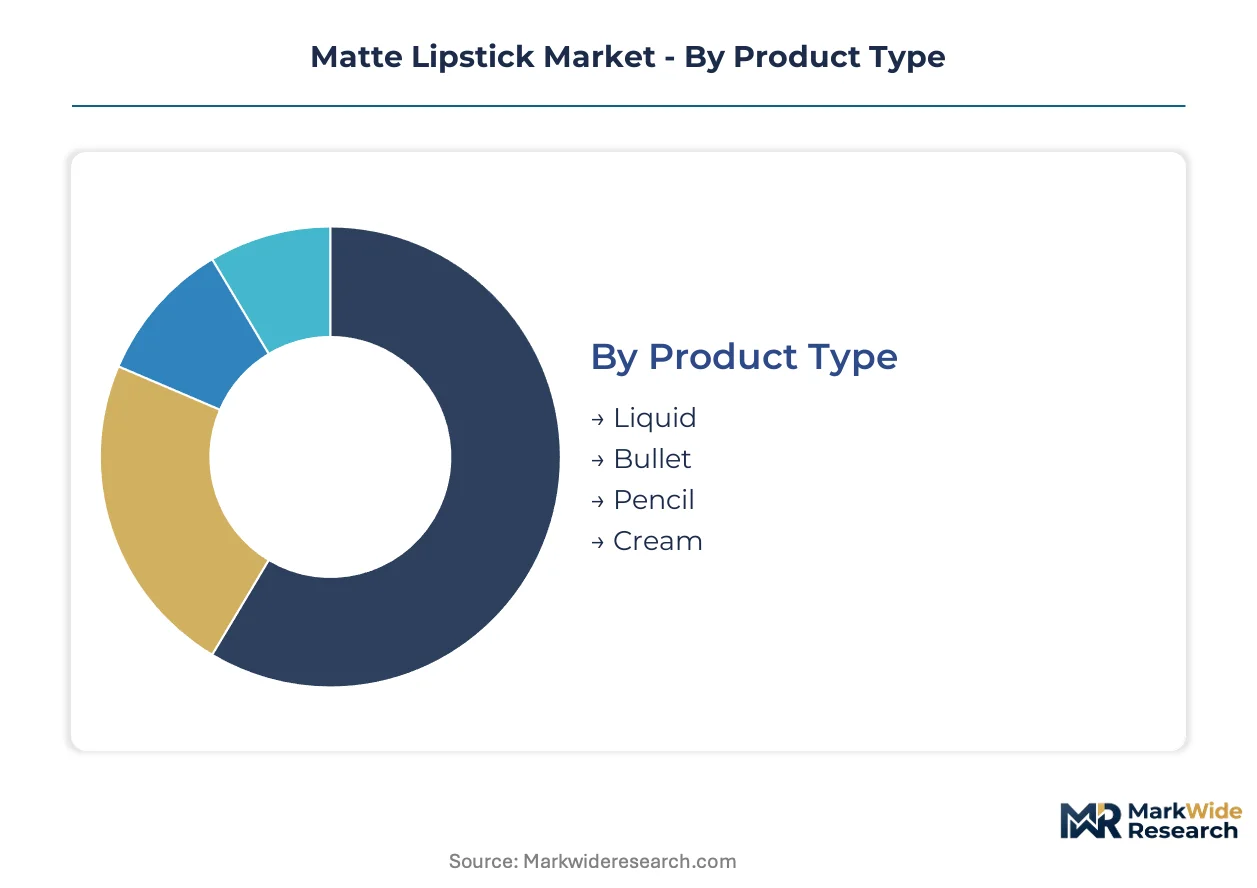
Matte lipstick segmentation reveals how formulation chemistry, application format, and skin-specific positioning create distinct competitive arenas. Manufacturers must align polymer R&D investments with the format-skin type combinations showing highest commercial traction.
Product Type:
Supply concentration in volatile silicone film-formers and precision applicator manufacturing favors formats with scale economics in polymer procurement.
- Liquid:High-load isododecane and cyclopentasiloxane formulations evaporate post-application, depositing concentrated pigments through precision doe-foot applicators. Demand concentrates among Gen Z content creators in India's tier-one cities, where camera-ready transfer resistance drives repurchase frequency.
- Bullet:Traditional wax-oil matrices with spherical silica powders deliver tactile luxury through metal casing heft and direct lip contact. Prestige retail in Mumbai and Delhi retains margin strength here, as counter-based sampling still converts high-value customers.
- Pencil:Hybrid crayon formats combine the portability of bullets with the precision of liquid applicators, targeting mobile touch-up occasions.
- Cream:Emulsion-based systems with lower volatile content prioritize comfort over extended wear, appealing to consumers with dry lip conditions.
Today's leader: Liquid. Tomorrow's challenger: Bullet.
Finish:
Cost tier stratification across premium, standard, and economy levels maps directly to polymer sophistication and pigment load intensity.
- Matte:Maximum light absorption through high spherical powder concentrations and zero emollient residue defines this specification. Professional makeup artistry channels in the United States and South Korea anchor volume, as backstage durability requirements override comfort preferences.
- Semi-Matte:Cream-to-matte hybrids incorporating micro-encapsulated color release systems are gaining share fastest, particularly among consumers seeking day-long wear without surface tightness.
- Velvet:Soft-focus silica blends create diffused, plush appearances with marginally higher emollient content than true matte specifications.
- Satin:Low-reflectance cream finishes with substantial oil phase content serve entry-price positioning and mature demographic comfort preferences.
Current volume anchor: Matte. Emerging preference shift: Semi-Matte.
Application Area:
Volume concentration in multi-use formulations is accelerating as consumers reduce kit complexity and brands pursue SKU efficiency.
- Lips:Dedicated lip formulations with optimized film-flexibility for oral movement remain the revenue core, with polymer chemistry tuned for eating and speaking durability.
- Face:Matte multi-sticks designed for lip-cheek-eyelid application concentrate demand among minimalist beauty adopters in urban India and Southeast Asia.
- Eyes:Eye-safe matte pigments with enhanced adhesion and crease-resistance properties extend lipstick chemistry into shadow and liner substitution.
- Cheeks:Cream-matte blush formats leverage shared pigment grinding and filling infrastructure with lip products.
Established revenue base: Lips. Format expansion opportunity: Face.
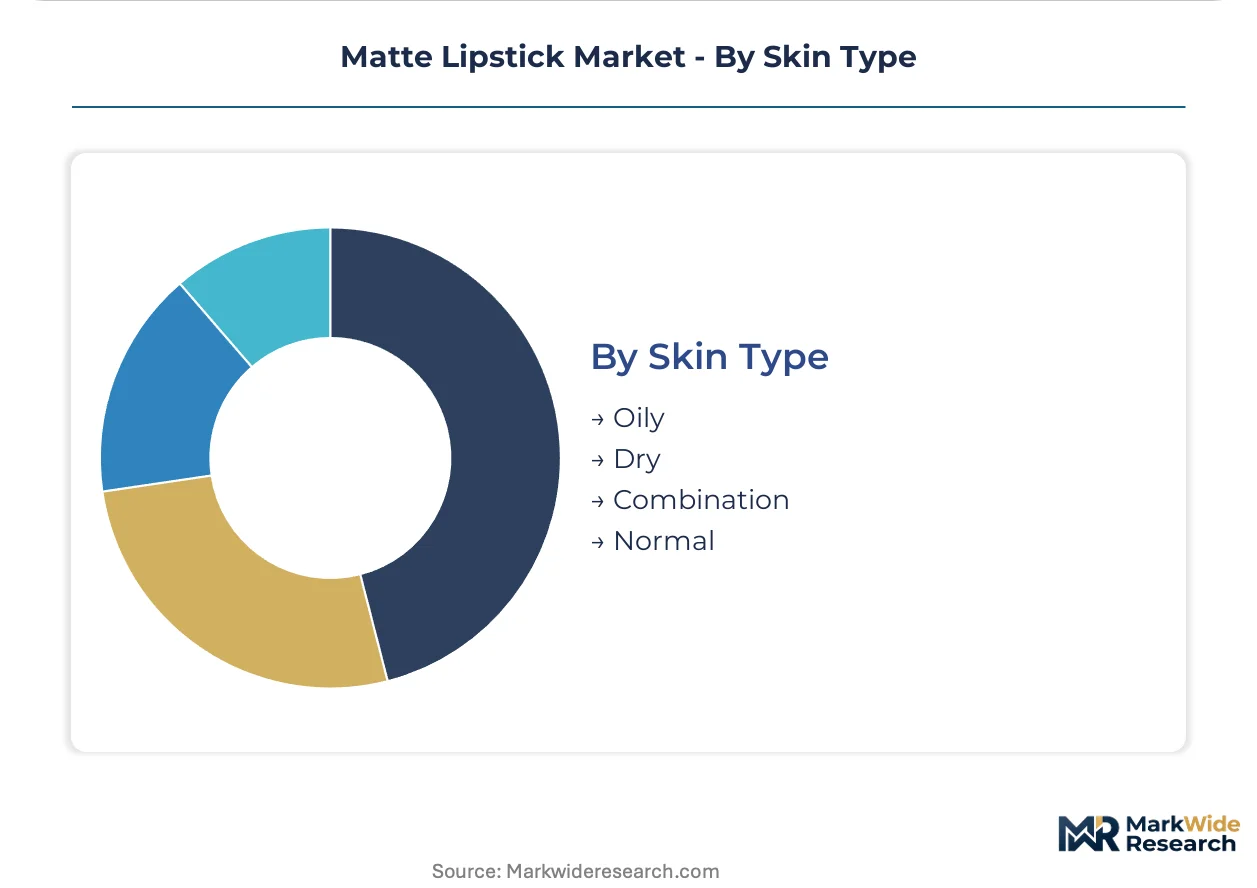
Skin Type:
Customer type stratification around dermatological concerns is forcing ingredient disclosure granularity and hypoallergenic certification investments.
- Dry:Ceramide-infused and squalane-enriched matte bases address flaking and tightness complaints that drive churn in standard formulations. Demand clusters in climates with low ambient humidity and among consumers over 35.
- Oily:Oil-absorbing kaolin and silica-loaded mattes with minimal emollient phase serve tropical markets and younger demographics with sebum overproduction.
- Combination:Zone-adaptive formulations with differential film-former density across the lip surface target the largest addressable population segment.
- Normal:Standard polymer loads without compensatory additives serve baseline positioning and price-sensitive trial.
Current formulation focus: Dry. Underserved positioning: Combination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai and Delhi anchor the most visible demand expansion for matte lip cosmetics, with professional makeup artistry channels and social media content creation driving formulation innovation cycles across multiple geographies.
United States
Professional makeup artistry and backstage sponsorships concentrate demand for transfer-resistant, camera-ready formulations in Los Angeles and New York. FDA color additive regulations constrain permissible pigment palettes for cross-border formulations. New York City serves as the primary testing ground for direct-to-consumer sampling through short-form video platforms.
India
Gen Z consumers in tier-one cities are recalibrating brand marketing strategies through beauty tutorial engagement. BIS cosmetics standards create compliance layers for imported finished goods. Mumbai, Delhi, and Bangalore host aggressive retail footprint expansion by mass-premium hybrid brands.
South Korea
Prestige counter positioning with hybrid skincare-lipcare formulations drives premium segment innovation. MFDS cosmetic safety regulations govern ingredient disclosure requirements. Seoul anchors micro-encapsulated color release system adoption for seasonal collections.
Germany
EU REACH microplastic restrictions are pushing manufacturers toward biodegradable film-forming alternatives. ECHA enforcement of chemical safety standards reshapes export-oriented formulation pipelines. Hamburg and Düsseldorf concentrate regulatory affairs bandwidth for multi-jurisdiction compliance.
France
Luxury heritage positioning in matte lip cosmetics maintains margin strength through tactile packaging and direct lip contact formats. ANSM cosmetic surveillance monitors post-market safety reporting. Paris anchors professional channel dominance through artist-education program investments.
Matte Lipstick Market Competitive Landscape
Portfolio diversification dominates the current landscape, with players consolidating around three structural tiers. Multinational conglomerates with dermatological research infrastructure occupy the premium positioning layer. Mid-tier specialists leverage regional manufacturing scale to serve mass-premium price points. Private-label contract manufacturers capture economy-tier volume through shared filling infrastructure. M&A activity and geographic licensing agreements represent the dominant competitive moves.
Within the multinational tier, L'Oréal and Estée Lauder Companies exemplify integrated research-to-retail positioning. Shiseido occupies a distinct Asia-Pacific prestige counter specialization. These three anchors demonstrate how dermatological research infrastructure, professional channel investment, and hybrid skincare-lipcare positioning create differentiated competitive moats in formulation-intensive segments.
| Leading Market Players |
|---|
| L'Oréal |
| Estée Lauder Companies |
| Revlon |
| Coty |
| Shiseido |
| Procter & Gamble |
| Chanel |
| MAC Cosmetics |
| NARS Cosmetics |
| Others |
Pricing and Supply Chain Analysis
Isododecane feedstock costs cascade through volatile silicone procurement tiers, compressing mid-brand margins as specialty chemical producers in Germany and Japan maintain oligopoly pricing power over film-forming polymer supply.
Pricing Analysis
Distributor margins in prestige retail channels absorb the steepest markup layers, with counter-based sampling infrastructure and artist-education programs justifying 40-60 point spreads over mass-market equivalents. Three-tier pricing structure across premium, standard, and economy levels stratifies by polymer sophistication and pigment load intensity. Cost compression in mid-tier liquid formats is intensifying because isododecane supply tightness from specialty chemical producers strains formulation budgets. Mass-market consumers show highest price sensitivity, while professional makeup artists demonstrate inelastic demand for transfer-resistant, camera-ready specifications.
Supply Chain Analysis
India's BIS cosmetics standards and domestic-content preferences for contract manufacturing are reshaping sourcing patterns toward local filling operations in Mumbai and Delhi. Raw material dependencies center on isododecane and cyclopentasiloxane from German and Japanese specialty chemical suppliers, spherical silica powders from Chinese mineral processors, and precision applicator molds from South Korean injection-molding specialists. Single-source vulnerability concentrates in volatile silicone film-former supply. Distribution runs through prestige counters in tier-one Indian cities, direct-to-consumer sampling via short-form video platforms, and mass-premium hybrid retail expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The matte lipstick market compounds steadily as social media content creation perpetually refreshes demand for camera-ready, transfer-resistant formulations across Gen Z demographics.
For Market Incumbents: Anchor professional channel dominance through backstage sponsorship investments and artist-education program scale in Mumbai, Delhi, and Los Angeles. Deepen backward integration into biodegradable film-forming polymer R&D to preempt EU REACH microplastic compliance costs. Secure exclusive supply agreements with encapsulation technology suppliers as micro-encapsulated color release systems displace conventional formulation architectures.
For New Entrants and Emerging Players: Begin with cream-to-matte hybrid positioning in India's tier-two cities—Pune, Hyderabad, Chennai—where mass-premium distribution whitespace exceeds competitive saturation. Target dry-skin formulations with ceramide-infused bases, an underserved segment relative to standard polymer loads. Pursue direct-to-consumer sampling through influencer-seeded trial on short-form video platforms, compressing traditional retail discovery cycles.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory affairs bandwidth strains under simultaneous FDA, EU REACH, and BIS compliance timelines. The 5-10 year viability window favors acquisition targets with dermatological research infrastructure and hybrid skincare-lipcare positioning. Monitor state-level ingredient disclosure mandates in California and New York as inflection indicators—these sub-national rules increasingly dictate national formulation baselines through market scale effects.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Transition | EU REACH microplastic restrictions eliminate non-biodegradable film-formers, forcing reformulation investment. |
| Micro-Encapsulation Technology Licensing | Encapsulation suppliers decentralize R&D from corporate labs, creating partnership opportunities. |
| Tier-Two India Distribution Expansion | Underpenetrated cities present whitespace for mass-premium hybrid retail footprint growth. |
| Professional Channel Sponsorship Scale-Up | Backstage durability requirements anchor inelastic demand from makeup artistry professionals. |
| Compliance-as-Service Offering | California and New York disclosure mandates create service revenue for formulation houses. |
Research Methodology
Multiple input streams—primary interviews with formulation scientists, brand managers, and regulatory affairs leads at multinational cosmetics houses; secondary validation through FDA color additive filings, EU REACH substance registrations, and BIS cosmetics standard notifications; plus customs data on isododecane and cyclopentasiloxane trade flows—were reconciled through bottom-up and top-down triangulation. Primary fieldwork concentrated on professional makeup artistry channels in Los Angeles and New York, prestige counter operations in Mumbai and Delhi, and encapsulation technology suppliers in Seoul. Secondary sources included SEC 10-K disclosures from listed beauty conglomerates, Nielsen retail audit data from Indian tier-one cities, and MFDS cosmetic safety filings.
Data-stream reconciliation across product type, finish specification, application area, and skin-type positioning generated volume and value estimates across the analysis window. Modeled dimensions included liquid versus bullet versus pencil formats, true matte versus semi-matte versus velvet finishes, dedicated lip versus multi-use face applications, and dry versus oily versus combination skin targeting. CAGRs were derived from trend extrapolation of social media engagement metrics, professional channel sponsorship volumes, and regulatory compliance cost trajectories. Industry-specific inputs incorporated Gen Z content creator economy expansion rates and EU REACH microplastic restriction implementation timelines.
Several conditions sit outside the modeled scope, including abrupt raw material supply disruptions, unanticipated regulatory amendments, and macroeconomic demand shocks in key consumption clusters. Forecasts reflect documented assumptions about polymer chemistry innovation cycles and content platform algorithm changes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
UK Lip Care Products Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
Face Cream Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Global Cosmetic Applicator Foam Market
Cosmetics & Skincare
Waterproof Eyebrow Liner Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Setting Spray Market
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Dark Circles Removing Eye Cream Market
Cosmetics & Skincare
Period Balm Market
Cosmetics & Skincare
Global Cosmetic Shea Butter Market
Cosmetics & Skincare
Bangladesh Face Wash Market