
 Natural Cosmetic Color Market | 2026-2036
Natural Cosmetic Color Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Cosmetic Color Market Outlook
India is rewriting supply dynamics for natural cosmetic color through expanded botanical extraction capacity in Gujarat and Maharashtra. Sensient Cosmetic Technologies leverages integrated pigment sourcing from regional turmeric and annatto cooperatives. Sun Chemical anchors its position through dedicated R&D centers in Mumbai focused on mineral-derived color stability. Koel Colours Private Limited dominates indigenous supply chains for iron oxide and carmine alternatives across South Asian markets.
Natural cosmetic color comprises pigments, dyes, and extracts derived from botanical, mineral, or certified organic sources, typically processed through aqueous or supercritical CO2 extraction to preserve chromophore integrity for skin-safe applications. These colorants serve primary functions in tinting creams, lip products, and hair formulations where regulatory restrictions prohibit coal-tar derivatives or heavy-metal contaminants. Colorants and extracts lead product type revenue due to broader formulation versatility across emulsion and gel bases, while powder formulations retain margin advantages in mineral makeup subcategories. Pigments compete through opacity control in color cosmetics, whereas liquid dyes penetrate hair care applications where dispersion uniformity determines performance.
EU REACH restrictions and the EU Green Deal framework restrict synthetic azo dyes and mandate biodegradability disclosures, redirecting procurement toward ECHA-registered botanical alternatives. FDA color additive regulations in the United States require batch certification for coal-tar derivatives while exempting most mineral and plant-derived pigments, creating divergent compliance pathways. India's BIS standards for herbal cosmetics and CDSCO safety thresholds for heavy-metal content shape domestic manufacturing protocols. Stakeholders must monitor regulatory divergence between jurisdictions when designing unified product portfolios and certification strategies.
Market Dynamics
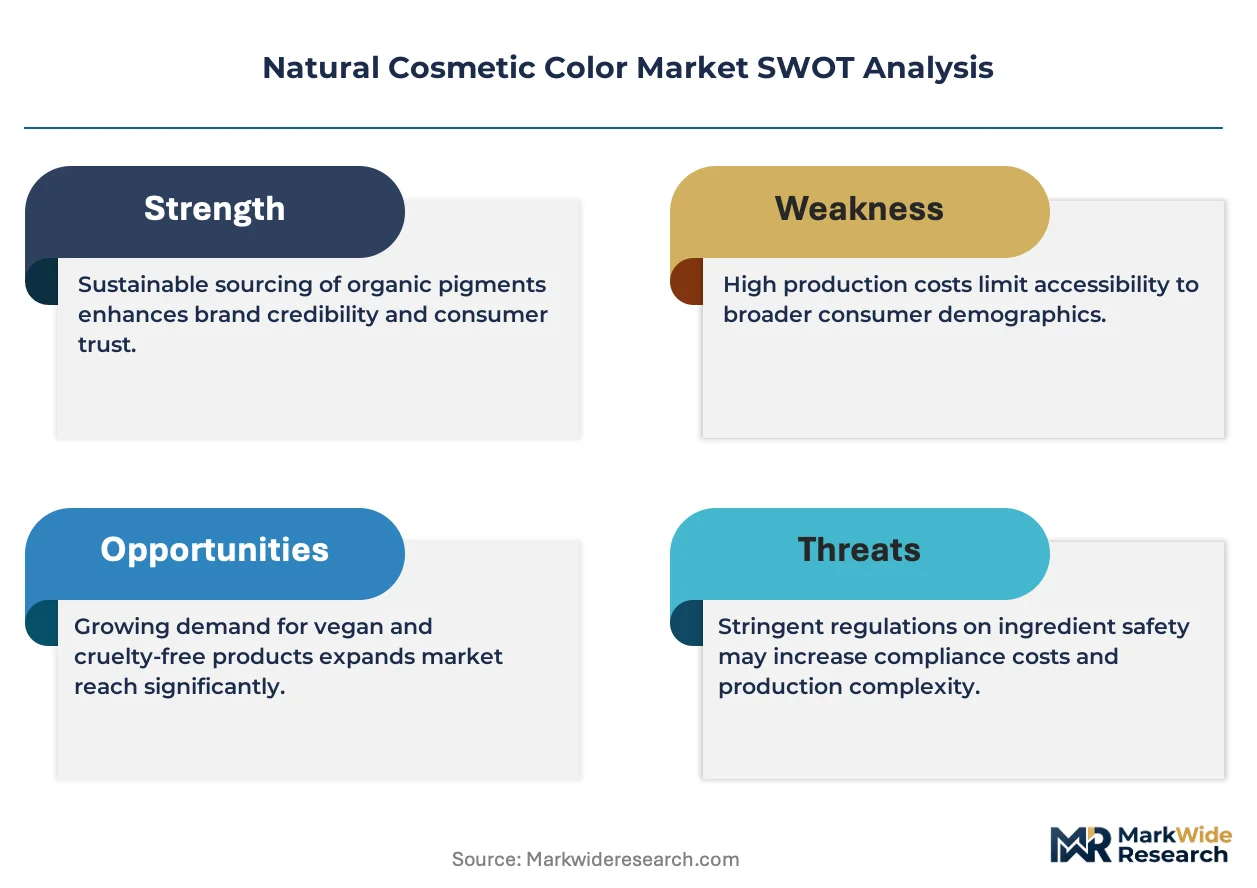
REACH and the EU Green Deal are compressing formulation timelines for cosmetic manufacturers, forcing rapid substitution of azo dyes with ECHA-registered botanical alternatives before 2030 phase-out deadlines.
Growth Catalysts
- EU Green Deal biodegradability mandates:Formulators redirect R&D budgets toward plant-derived chromophores to preempt regulatory non-compliance.
- Clean beauty brand procurement:Skincare labels with Naturkosmetik certification command premium shelf placement, pulling supply chain investment toward verified botanical extraction.
- Supercritical CO2 extraction:This solvent-free processing technology preserves heat-sensitive pigment integrity, expanding application scope into lip and eye formulations.
Market Restraints
- Botanical raw material cost volatility:Climate stress on turmeric and annatto harvests in Gujarat and Maharashtra creates input price instability.
- Extraction capacity concentration:Limited supercritical CO2 infrastructure clusters in Western Europe, creating geographic supply bottlenecks.
- Color stability technical ceiling:Mineral-derived pigments face oxidation degradation in emulsion bases, restricting formulation versatility versus synthetic alternatives.
Strategic Opportunities
- German retail channel premiumization:DM-drogerie and Douglas are expanding dedicated naturkosmetik floor space, creating direct-to-shelf pathways for certified suppliers.
- Hair care liquid dye penetration:Aqueous botanical extracts displace coal-tar derivatives in salon-grade colorants where dispersion uniformity drives performance.
- BIS herbal cosmetic standards:India's domestic certification framework is creating export-ready manufacturing hubs for South Asian and Middle Eastern markets.
Industry Challenges
- Chromatographic analysis skill scarcity:Formulation labs lack sufficient analytical chemists to validate batch-to-batch pigment consistency in botanical extracts.
- Naturkosmetik certification timeline compression:German BDIH and COSMOS approval cycles extend 18-24 months, delaying product launch windows.
- Legacy ERP integration friction:Batch-level traceability requirements for ECHA registration clash with existing cosmetic manufacturing software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Cosmetic Color Market |
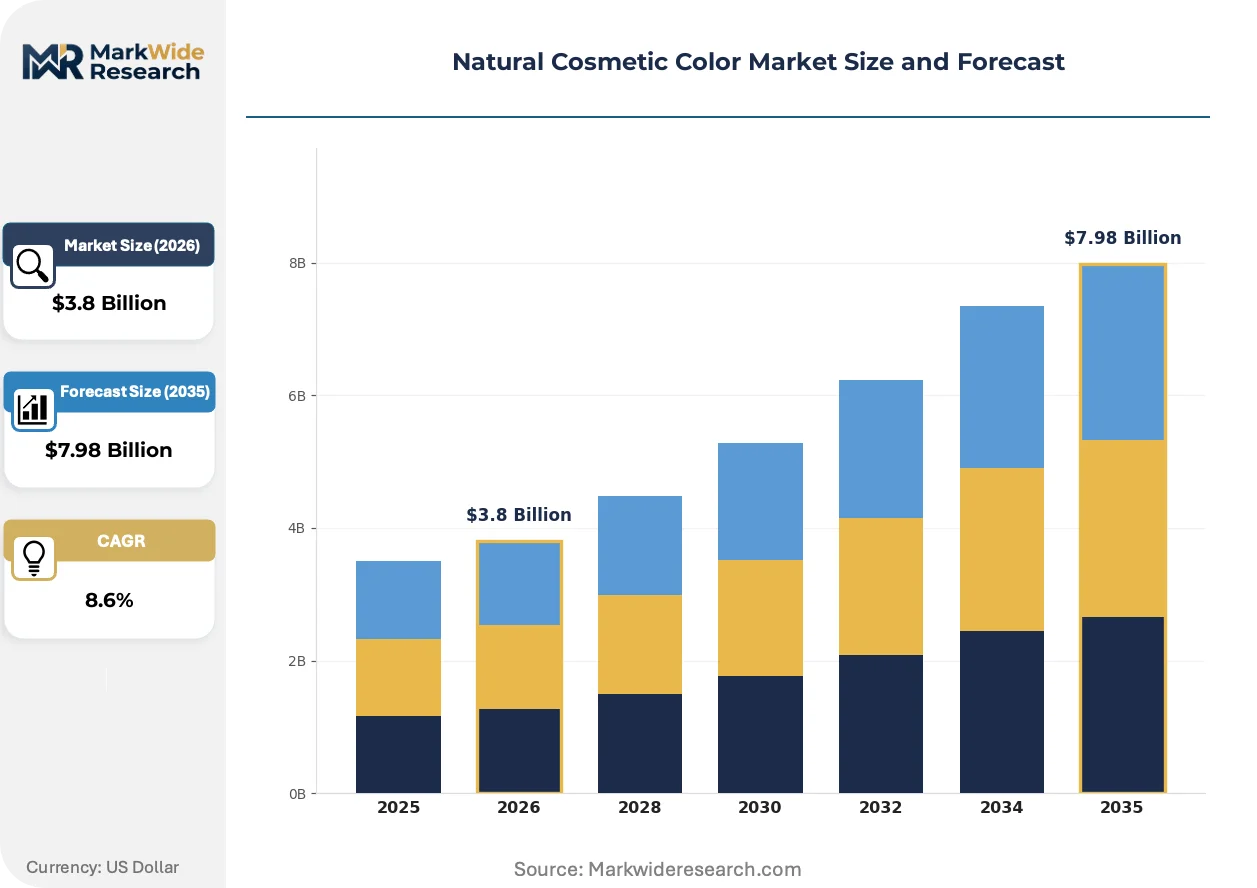
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colorants, Pigments, Dyes, Extracts Application: Skincare, Makeup, Hair Care, Personal Care Formulation Type: Powder, Liquid, Emulsion, Gel Source: Botanical, Mineral, Organic, Synthetic |
| Companies Covered | Sensient Cosmetic Technologies, Sun Chemical, Koel Colours Private Limited, Clariant, Givaudan, Symrise, L’Oréal, BASF SE, Burt's Bees, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Cosmetic Color Market Strategic Shifts
Digital color matching platforms are compressing formulation iteration cycles while regulatory disclosure requirements force transparency infrastructure investment across the value chain.
Supercritical CO2 extraction with inline spectroscopic monitoring is virtualizing quality control protocols for botanical pigment batches. Clean beauty formulators in Germany and France are adopting these systems at pilot scale within 18-month implementation windows. This technology is virtualizing the traditional wet-chemistry validation workflow, collapsing third-party lab dependency and accelerating batch release timelines.
REACH Annex XVII restrictions on synthetic azo dyes are mandating full supply chain reconfiguration for color cosmetic manufacturers. Industrial consequence includes mandatory ECHA registration dossiers for all imported botanical colorants above one-tonne annual volume. Hair care applications face the steepest compliance burden, with German and Dutch formulators consolidating supplier bases to pre-registered extraction facilities.
Certification-driven procurement now dominates buyer evaluation criteria for natural cosmetic color. DM-drogerie and Sephora Europe are displacing conventional tender processes with pre-qualified naturkosmetik supplier pools. This pattern concentrates most visibly in German-speaking markets, where BDIH and COSMOS labels determine listing eligibility.
Natural Cosmetic Color Market Segmentation
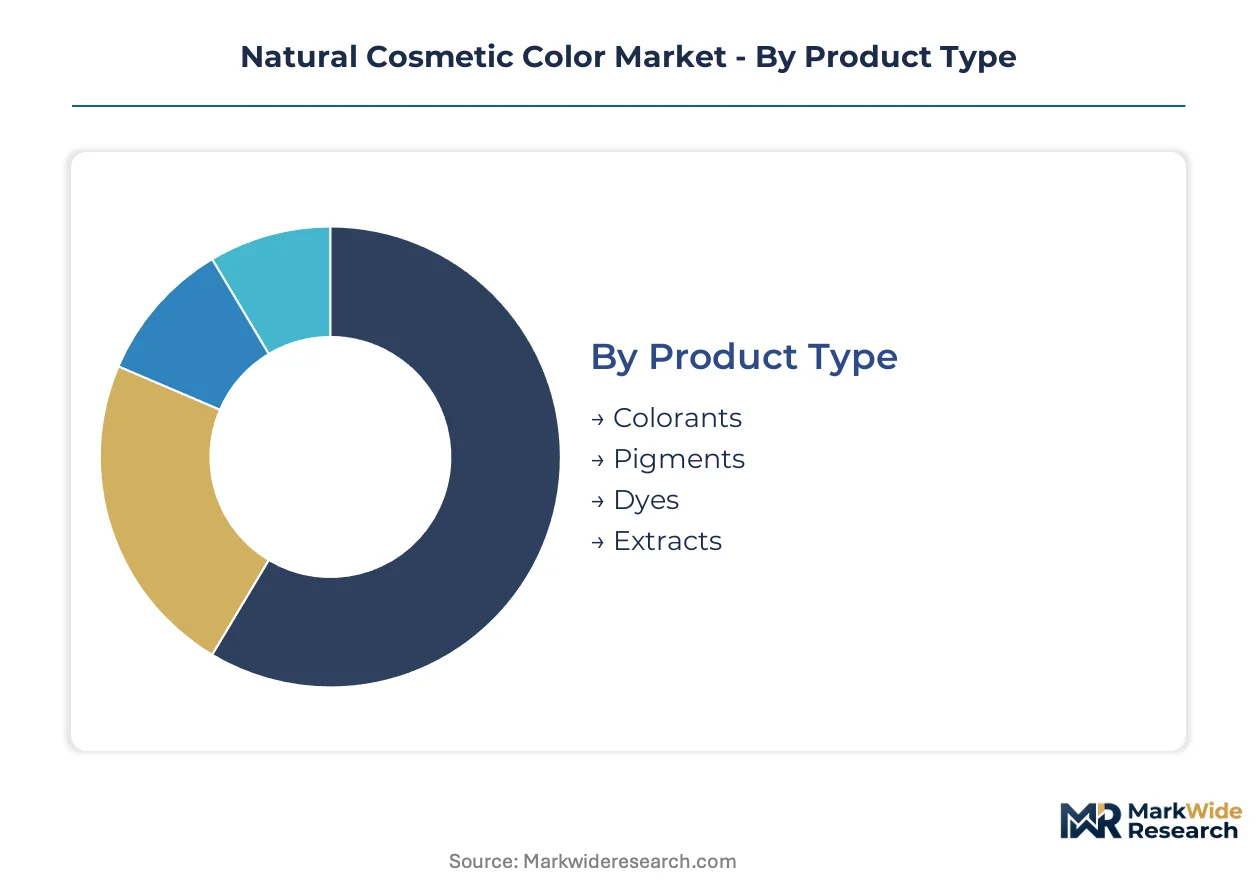
Natural cosmetic color segmentation reveals how formulation requirements and regulatory constraints fragment procurement strategies across the value chain. Buyers optimize around extraction method stability, end-use performance thresholds, and certification compliance rather than commodity pricing alone.
Product Type:
Mature segments dominate revenue concentration while emerging categories capture premium positioning through technical differentiation.
- Colorants:Broad-spectrum tinting agents spanning lipophilic and hydrophilic bases, processed through aqueous or supercritical CO2 extraction to preserve chromophore integrity. Demand concentrates in German Naturkosmetik-certified skincare lines where ECHA-registered alternatives command shelf placement premiums over synthetic azo dyes.
- Extracts:Concentrated botanical preparations from turmeric, annatto, and beetroot delivering standardized pigment loads. German DM-drogerie and Douglas retail channels are pulling supply chain investment toward verified extraction facilities as BDIH certification becomes a listing prerequisite.
- Pigments:Mineral-derived opacity controllers for color cosmetics.
- Dyes:Soluble chromophores for aqueous hair care applications.
Colorants handle the majority of throughput; extracts are climbing the fastest on share.
Application:
End-use performance requirements create divergent procurement specifications across cosmetic categories.
- Skincare:Emulsion-compatible botanical tints for tinted moisturizers and sun care where photostability determines formulation acceptance. Clean beauty brands with Naturkosmetik certification represent the steepest expansion trajectory as EU Green Deal biodegradability mandates compress substitution timelines.
- Hair Care:Aqueous liquid dyes requiring dispersion uniformity in oxidative and direct colorant systems. REACH Annex XVII restrictions on coal-tar derivatives are forcing German and Dutch formulators to consolidate supplier bases around pre-registered botanical extraction facilities.
- Makeup:Pressed powder and liquid lip formulations demanding oxidation-resistant mineral pigments.
- Personal Care:Lower-concentration tints for body care and hygiene products.
Skincare commands the dominant revenue position; hair care is gaining share fastest through salon-grade displacement of synthetic derivatives.
Formulation Type:
Physical state determines extraction infrastructure requirements and stability testing protocols.
- Powder:Dry mineral and botanical pigments for pressed makeup and loose mineral foundations, processed through jet milling to achieve sub-micron particle distribution. Margin advantages concentrate in mineral makeup subcategories where opacity control drives premium positioning.
- Liquid:Aqueous and oil-dispersed colorants for fluid foundations and hair dyes. Supercritical CO2 extraction with inline spectroscopic monitoring is collapsing third-party lab dependency for German and French formulators adopting pilot-scale systems.
- Emulsion:Oil-in-water or water-in-oil dispersed pigments for creams and lotions.
- Gel:Hydrocolloid-stabilized colorants for transparent and semi-transparent products.
Powder formulations retain margin leadership; liquid systems are expanding most quickly through hair care and fluid foundation demand.
Source:
Raw material origin governs regulatory pathway complexity and certification eligibility.
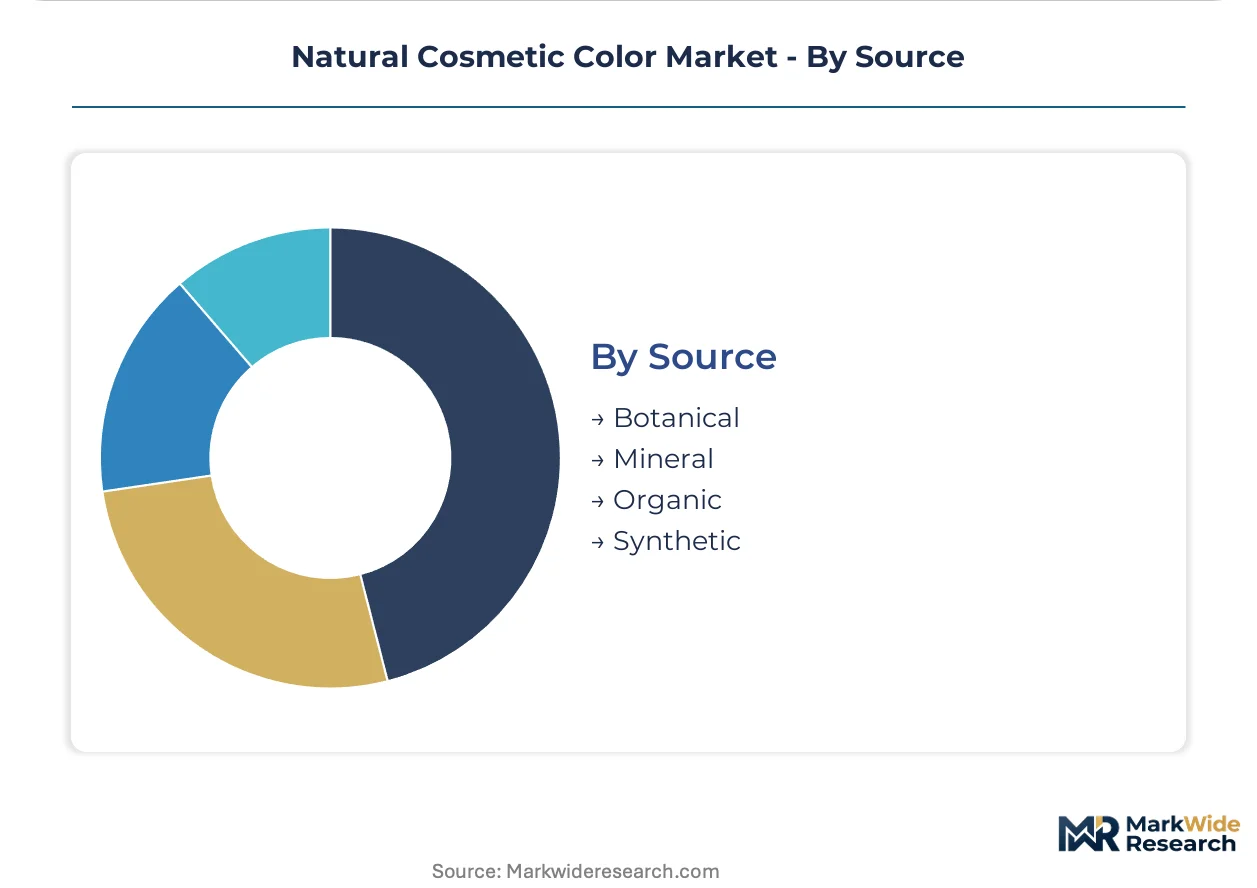
- Botanical:Plant-derived pigments from turmeric, annatto, spirulina, and anthocyanin sources, subject to climate volatility in Gujarat and Maharashtra growing regions. FDA exemption from batch certification for most plant-derived pigments creates divergent compliance advantages versus coal-tar derivatives.
- Mineral:Iron oxides, titanium dioxide, and mica processed for cosmetic-grade purity. Oxidation degradation in emulsion bases restricts formulation versatility, limiting penetration into liquid skincare applications where synthetic alternatives retain technical superiority.
- Organic:Certified organic botanical sources meeting COSMOS or USDA organic standards.
- Synthetic:Chemically manufactured colorants facing REACH and EU Green Deal phase-out pressures.
Botanical sources carry the dominant volume position; mineral alternatives are advancing fastest through makeup applications requiring opacity control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA registration requirements under REACH Annex XVII are compressing formulation timelines across European cosmetics manufacturing, redirecting procurement toward pre-registered botanical extraction facilities.
Germany
DM-drogerie and Douglas retail channels are expanding dedicated Naturkosmetik floor space, pulling supply chain investment toward BDIH-certified suppliers. The EU Green Deal biodegradability mandates force rapid azo dye substitution before 2030 deadlines. Frankfurt and Hamburg harbor clusters concentrate ECHA-registered import logistics for botanical colorants.
United States
FDA batch certification exemptions for mineral and plant-derived pigments create divergent compliance advantages versus coal-tar derivatives. Clean beauty brand procurement from Sephora and Ulta Beauty channels drives formulation budget reallocation. New Jersey and California formulation labs dominate domestic emulsion testing capacity for natural color stability.
India
BIS herbal cosmetic standards and CDSCO heavy-metal thresholds shape export-ready manufacturing protocols for South Asian markets. Expanded supercritical CO2 extraction capacity in Gujarat and Maharashtra rewrites regional supply dynamics. Ahmedabad and Mumbai industrial corridors anchor integrated pigment sourcing from turmeric and annatto cooperatives.
France
ANSM cosmetic safety notifications align with REACH disclosure requirements for botanical chromophore imports. Paris-based clean beauty formulators pilot inline spectroscopic monitoring for batch release acceleration. Lyon and Grasse clusters specialize in aqueous extract standardization for lip and eye formulation applications.
Netherlands
Dutch formulators consolidate supplier bases around pre-registered extraction facilities to manage REACH Annex XVII hair care compliance burdens. Rotterdam port infrastructure handles bulk mineral pigment refining for EU distribution. Eindhoven region R&D centers focus on oxidation-resistant mineral pigment encapsulation technologies.
Natural Cosmetic Color Market Competitive Environment
Capability concentration sits with specialized extraction technology providers; scale advantage sits with diversified chemical conglomerates. The vendor base stratifies across three tiers: integrated pigment multinationals, regional extraction specialists, and clean beauty brand captives. Strategic archetypes include ECHA-registered botanical suppliers, mineral-derived opacity controllers, and aqueous dye dispersion formulators. Dominant competitive moves encompass backward integration into raw material cooperatives and certification-driven supplier pool pre-qualification.
Among integrated pigment multinationals, Sensient Cosmetic Technologies exemplifies the botanical extraction archetype through its positioning in regional turmeric and annatto sourcing networks. Sun Chemical anchors the mineral-derived stability tier with its Mumbai-based R&D infrastructure. Koel Colours Private Limited occupies the indigenous supply chain specialist position for iron oxide and carmine alternatives across South Asian markets. These three entities represent distinct capability vectors: integrated agricultural sourcing, dedicated mineral processing R&D, and regional certification compliance.
| Leading Market Players |
|---|
| Sensient Cosmetic Technologies |
| Sun Chemical |
| Koel Colours Private Limited |
| Clariant |
| Givaudan |
| Symrise |
| L'Oréal |
| BASF SE |
| Burt's Bees |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors transmit cost volatility from botanical extraction hubs in Gujarat through to German Naturkosmetik-certified formulators, compressing margins at each transfer point while amplifying price differentiation between ECHA-registered and non-registered supply tiers.
Pricing Analysis
Price spreads between Western European and Indian-sourced botanical colorants reflect certification overhead and logistics premiums rather than raw pigment value alone. Three-tier pricing structure across premium, standard, and economy levels separates BDIH-certified extracts from conventional botanical grades and unverified mineral alternatives. Pricing pressure stems from climate-induced turmeric and annatto harvest volatility in Maharashtra. Small clean beauty brands exhibit highest price sensitivity; multinational skincare labels with dedicated naturkosmetik lines absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
EU REACH Annex XVII export-control restrictions on synthetic azo dyes redirect flows toward pre-registered Indian and French extraction facilities, compressing compliant supplier pools. Geographic concentration centers on India for turmeric and annatto botanicals, Germany for ECHA-registered import logistics, and the Netherlands for mineral pigment refining. Raw material dependencies include climate-vulnerable spice harvests, supercritical CO2 processing equipment, and cosmetic-grade mineral ore. Single-source vulnerability concentrates in limited supercritical extraction infrastructure. Distribution runs through DM-drogerie and Douglas retail channels for certified finished goods, with bulk botanicals moving via Rotterdam port consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: ECHA registration dossiers and BDIH certification cycles create switching costs that lock in incumbent supplier relationships and delay competitive entry.
For Market Incumbents: Insulate market position through backward integration into turmeric and annatto cooperatives in Gujarat and Maharashtra, securing captive supply against climate volatility. Expand dedicated supercritical CO2 extraction capacity in Western Europe to preempt geographic bottlenecks. Prioritize COSMOS certification investment to maintain listing eligibility at Sephora Europe and DM-drogerie channels. For New Entrants and Emerging Players: Mid-tier hair care formulators in the Netherlands and Belgium represent the most penetrable entry point, as REACH Annex XVII compliance burdens force consolidation of incumbent supplier bases and create service gaps. Target aqueous liquid dye dispersion for salon-grade applications where batch-to-batch consistency requirements favor agile analytical capabilities over scale. Lead with digital color matching platforms to compress formulation iteration cycles for smaller brands. For Investors and Strategic Acquirers: REACH 2030 azo dye phase-out deadlines reshape the acquisition landscape toward ECHA-registered extraction specialists with established botanical chromophore dossiers. Position for five-to-ten year holding periods as certification infrastructure becomes the primary value determinant. Monitor BDIH and COSMOS approval timeline compression as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Cooperatives | Captive supply of turmeric and annatto from Gujarat insulates against climate-driven input volatility. |
| Supercritical CO2 Capacity Expansion | Dedicated extraction infrastructure in Western Europe collapses third-party lab dependency for German formulators. |
| BDIH/COSMOS Certification Investment | Pre-qualified supplier status unlocks DM-drogerie and Douglas floor space expansion programs. |
| Digital Color Matching Platform Deployment | Inline spectroscopic monitoring accelerates batch release timelines for clean beauty brands. |
| Long-term Supply Agreement with Retail Channels | Direct-to-shelf pathways at Sephora Europe displace conventional tender processes for certified colorants. |
Study Parameters
Operator-level perspectives from cosmetic formulation chemists, BDIH certification auditors, retail category buyers at DM-drogerie and Douglas, and supercritical extraction facility engineers anchored the qualitative base. Secondary validation drew from ECHA registration dossiers, EU Green Deal biodegradability mandate disclosures, BIS herbal cosmetic standards documentation, and customs trade data for botanical pigment flows. Bottom-up volume estimates from extraction facility throughput triangulated against top-down cosmetic manufacturer procurement surveys.
Scenario-bracketing around regulatory phase-out timelines and climate stress models shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application category, formulation state, and raw material source origin. CAGRs derived from slope-log regression against normalized extraction capacity expansion curves, with explicit inputs for ECHA registration approval rates and supercritical CO2 equipment installation pipelines.
Macroeconomic conditions sit as an overlay; deviation in euro-rupee exchange rates and EU carbon border adjustment implementation would shift the trajectory. Forecasts embed assumptions regarding REACH enforcement consistency and BDIH certification timeline stability. Material shifts in EU Green Deal biodegradability mandate acceleration or Indian spice harvest disruption severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
BB Cream Market
Cosmetics & Skincare
Indonesia Skin Care Products Market
Cosmetics & Skincare
Halal Cosmetic Products Market
Cosmetics & Skincare
Eye Makeup Market
Cosmetics & Skincare
GCC Halal Cosmetics Market
Cosmetics & Skincare
Natural Baby Skin Care Products Market
Cosmetics & Skincare
Israel Cosmetics Products Market
Cosmetics & Skincare
Essential Oil Soap Market
Cosmetics & Skincare
Cosmetics Private Label and Contract Manufacturing Market
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
Period Balm Market
Cosmetics & Skincare
Eye Shadow Stick Market
Cosmetics & Skincare
Marine Hyaluronic Water Cream Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Professional Scalp Care Products Market