
 Hip Flask Market | 2026-2036
Hip Flask Market Size, Share, and Industry Trends Forecast 2026-2036
Hip Flask Market Foresight
Personalized engraving services and direct-to-consumer customization platforms is decoupling hardware sales from traditional retail margins. Stanley PMI leverages its vacuum-insulation heritage to anchor premium positioning in outdoor channels. SWIG Hip Flasks specializes in monogrammed and bespoke designs that command higher per-unit economics. Leatherology competes through vertically controlled leathercraft operations that sustain consistent hide quality and finishing standards.
A hip flask is a small, curved vessel designed for portable beverage containment, typically fabricated from 18/8 stainless steel with welded seams and captive lids to prevent leakage during transport. Wall thickness ranges from 0.5mm to 1.2mm depending on capacity, with electropolished interiors meeting food-contact safety requirements for alcohol storage. Stainless steel dominates material value pools due to durability perceptions and thermal neutrality, while personalized design variants capture expanding margin as consumers seek individualized gifting options. Online retail channels are displacing specialty store traffic for initial discovery, though gift shops retain conversion strength for occasion-driven purchases.
The U.S. Food and Drug Administration governs food-contact substance compliance for metallic beverage containers, while the European Union's REACH framework restricts hazardous substances in surface coatings and leather tanning agents. California Proposition 65 disclosure requirements shape labeling obligations for products containing trace lead content in decorative alloys. Stakeholders must monitor evolving state-level restrictions on portable alcohol containers in public spaces and adapt distribution strategies accordingly.
Market Dynamics
Direct-to-consumer engraving platforms are fragmenting retail control over margin capture, while stainless steel raw material volatility and REACH compliance costs compress mid-tier producer economics.
Growth Catalysts
- Outdoor recreation expansion:Camping and hiking participation in the United States sustains premium flask demand through gift-giving occasions and personal equipment upgrades.
- REACH framework evolution:The European Union's tightening restrictions on surface coatings and tanning agents push compliant producers toward premium positioning with certified supply chains.
- Laser engraving automation:Fiber laser systems reduce per-unit personalization costs, enabling mass customization at direct-to-consumer price points previously reserved for batch production.
Market Restraints
- Stainless steel price volatility:Nickel and chromium input cost swings squeeze 0.5mm-0.8mm wall thickness segments where material constitutes 35-45% of landed cost.
- Electropolishing capacity concentration:Food-contact finishing expertise clusters in Zhejiang province and North Rhine-Westphalia, creating geographic supply risk for non-integrated brands.
- Reusable bottle substitution:Vacuum-insulated vessels from outdoor equipment manufacturers capture portable beverage occasions with temperature retention advantages.
Strategic Opportunities
- Indian wedding gifting culture:Custom-engraved flasks for groomsmen parties remain underpenetrated versus traditional silver vessels, presenting white space for stainless steel alternatives.
- California Proposition 65 compliance:Lead-content disclosure requirements favor electropolished 18/8 grades over decorative alloys, rewarding producers with certified testing protocols.
- Social commerce integration:TikTok Shop and Instagram Checkout enable discovery-to-purchase compression for occasion-driven buyers, bypassing specialty retail markup layers.
Industry Challenges
- Electropolishing technician scarcity:Food-contact surface finishing requires specialized certification that outpaces vocational training pipeline output in both Asian and European manufacturing hubs.
- Multi-jurisdiction labeling complexity:Simultaneous FDA, REACH, and state-level compliance necessitates SKU proliferation that strains inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hip Flask Market |
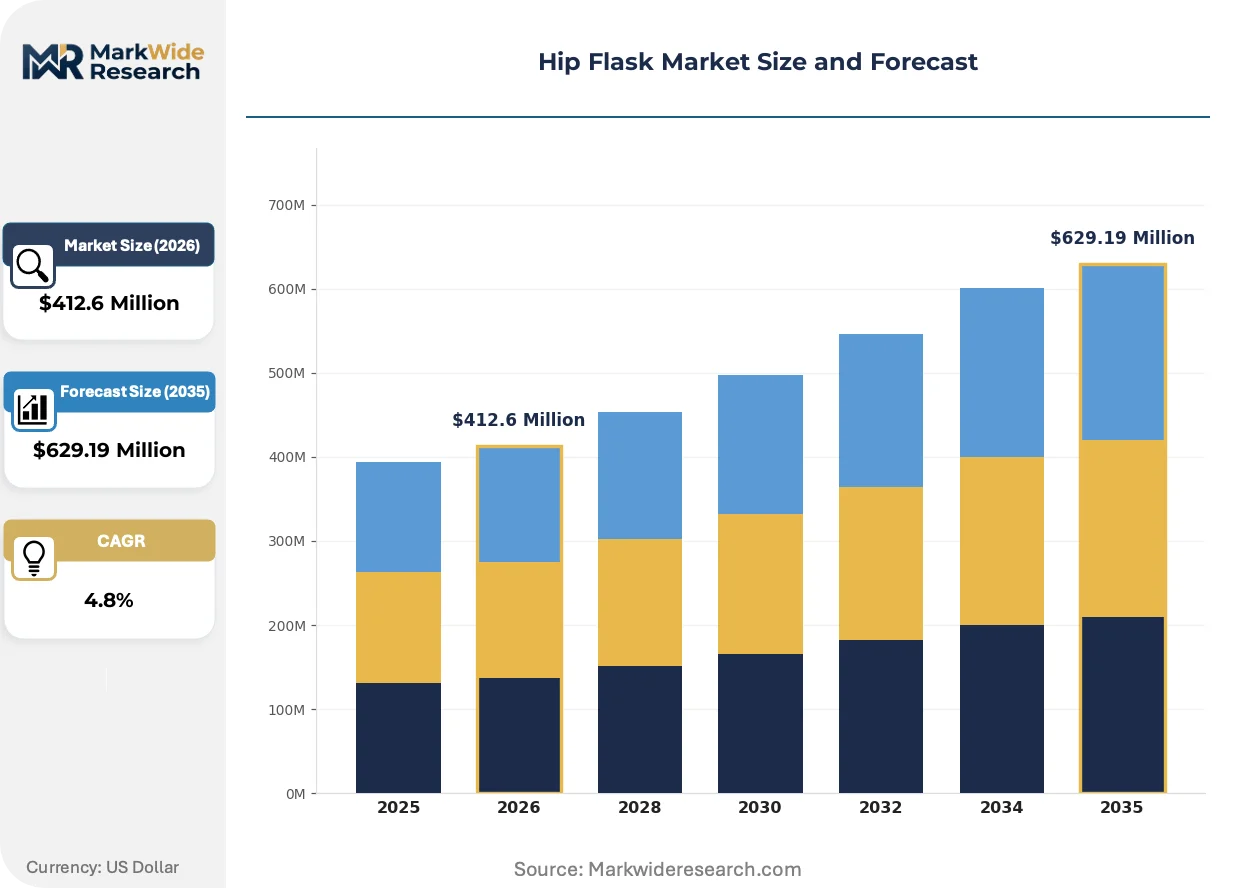
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Stainless Steel, Glass, Plastic, Leather Capacity: 2 oz, 4 oz, 6 oz, 8 oz Design: Classic, Personalized, Modern, Vintage Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Gift Shops |
| Companies Covered | Snow Peak Co., Ltd., Leatherology, Stanley PMI, Klean Kanteen, Visol Products, GSI Outdoors, Maxam, Marlborough of England, SWIG Hip Flasks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hip Flask Market Shifts & Advancements
Digital fabrication and regulatory precision are converging to reshape how hip flasks are designed, certified, and delivered to end buyers.
Fiber laser engraving systems are rewriting personalization economics by collapsing setup times from hours to minutes. Outdoor enthusiasts and wedding planners now expect monogrammed flasks at mass-market price points. This capability compression is eroding the traditional premium that specialty engravers commanded for bespoke work.
The European Chemicals Agency's enforcement of REACH candidate list updates is tightening compliance windows for surface coatings and leather tanning agents. Producers must reformulate finishes or source certified alternatives to maintain EU market access. Stainless steel electropolishing houses in Germany and Italy are investing in closed-loop chemical recovery to preempt authorization restrictions.
Social commerce discovery is displacing specialty store foot traffic for initial product awareness. TikTok Shop and Instagram Checkout capture occasion-driven buyers—wedding parties, graduation gifts, camping trip preparations—who previously browsed airport retailers or outdoor equipment stores. The United States and United Kingdom exhibit the fastest channel migration, with gift-giving seasons showing particular platform concentration.
Hip Flask Market Segmentation
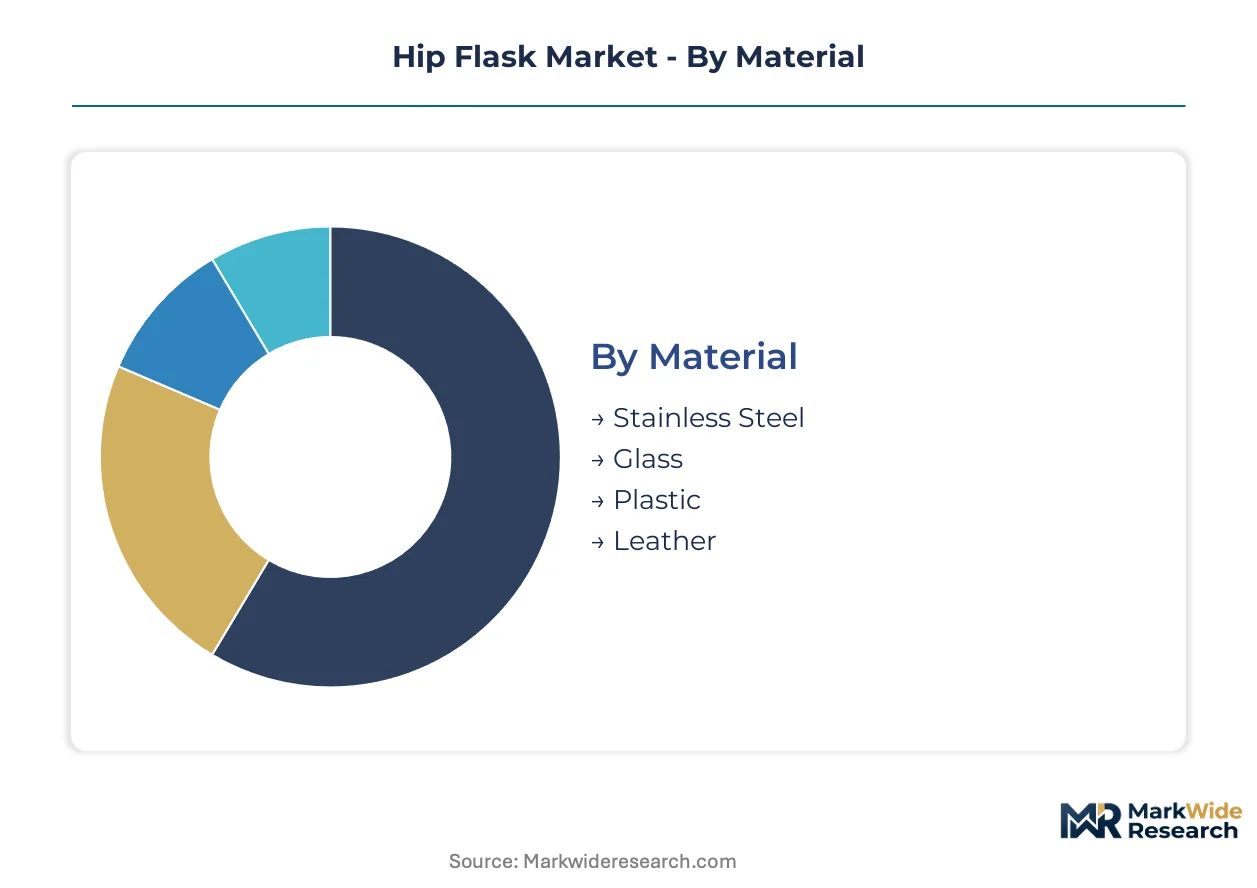
Hip flask manufacturers navigate divergent cost structures across material grades and capacity tiers. Segmentation reveals where capital deployment yields margin protection versus commodity exposure.
Material:
Electropolishing equipment and REACH-compliant finishing lines demand the heaviest upfront investment, favoring integrated producers over assembly-only brands.
- Stainless Steel:18/8 grade with welded seams and captive lids dominates food-contact applications. Camping and hiking enthusiasts in the United States sustain premium demand through equipment upgrades and gift-giving occasions.
- Glass:Borosilicate construction appeals to flavor-purity advocates but carries breakage risk during outdoor transport. Boutique distilleries in Germany and Italy specify glass for tasting kit collaborations.
- Plastic:Copolyester variants serve price-sensitive casual users and festival environments where loss tolerance exceeds durability requirements.
- Leather:Full-grain wrapping requires vertically controlled tanning operations to meet ECHA surface coating restrictions.
Stainless steel absorbs the bulk of installed capacity; leather is expanding most quickly on personalization premiums.
Capacity:
Tooling costs scale nonlinearly with vessel dimensions, compressing margins on mid-range formats where volume expectations clash with setup amortization.
- 2 oz:Pocket-concealed dimensions suit discrete transport in formal attire. Wedding planners in the United Kingdom specify 2 oz for groomsmen party favors.
- 4 oz:Balanced portability and serving volume anchors mainstream outdoor retail assortments.
- 6 oz:Extended trip capacity targets multi-day hikers in the United States who prioritize weight-to-volume efficiency.
- 8 oz:Maximum single-vessel capacity serves group sharing scenarios but faces substitution from vacuum-insulated bottles.
4 oz formats command the broadest distribution footprint; 2 oz climbs the fastest on gifting platform concentration.
Design:
Margin stratification follows customization depth, with automated engraving collapsing the traditional premium hierarchy between stock and bespoke finishes.
- Classic:Curved rectangular profiles with polished or brushed exteriors retain wholesale channel dominance. Specialty stores in France and Switzerland maintain classic assortment depth for heritage positioning.
- Personalized:Fiber laser engraving enables monogrammed output at direct-to-consumer price points previously reserved for batch production.
- Modern:Minimalist geometry and matte PVD coatings attract urban consumers through Instagram Checkout discovery.
- Vintage:Antiqued patinas and hammered textures serve collectors and period reenactment communities.
Classic designs retain the largest production volume allocation; personalized variants gain share fastest as social commerce compresses discovery-to-purchase cycles.
Distribution Channel:
Working capital requirements vary sharply across channels, with online retail demanding inventory flexibility while gift shops impose seasonal concentration risk.
- Online Retail:Direct-to-consumer platforms bypass specialty store markup layers. TikTok Shop and Instagram Checkout capture occasion-driven buyers in the United States and United Kingdom.
- Specialty Stores:Outdoor equipment retailers and airport duty-free operators sustain premium positioning through tactile evaluation.
- Supermarkets:Mass-market placement targets impulse purchase occasions with simplified packaging and reduced SKU depth.
- Gift Shops:Occasion-driven conversion strength persists for graduation and retirement ceremonies despite foot traffic erosion.
Online retail captures the steepest volume trajectory; gift shops retain the highest per-transaction value despite declining traffic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in eastern China and northern Italy while consumption concentrates in the United States and Western Europe. This geographic split shapes margin capture patterns across the value chain.
United States
Camping participation and craft spirits culture sustain premium flask demand through gift-giving occasions and personal equipment upgrades. FDA food-contact substance regulations govern metallic beverage container compliance, with California Proposition 65 imposing additional lead-content disclosure requirements. Seattle-based outdoor equipment retailers anchor distribution networks serving Pacific Northwest hiking corridors.
Germany
Boutique distillery collaborations and heritage positioning in specialty stores drive stainless steel and glass flask adoption. ECHA enforcement of REACH candidate list updates tightens compliance windows for surface coatings and leather tanning agents. Electropolishing houses in North Rhine-Westphalia invest in closed-loop chemical recovery systems to maintain EU market access.
United Kingdom
Wedding gifting traditions and groomsmen party customs sustain demand for personalized 2 oz formats. Trading Standards Institute oversight aligns with EU REACH framework for imported goods. Sheffield metalworking heritage supports precision welding operations for captive-lid stainless steel vessels.
China
Electropolishing capacity concentration in Zhejiang province supplies food-contact finishing for export-oriented brands. SAMR food-contact material standards and GB stainless steel specifications shape domestic production compliance. Yiwu wholesale markets channel mass-market copolyester variants to price-sensitive festival and casual use segments.
India
Custom-engraved flasks for groomsmen parties present white space against traditional silver vessel gifting at weddings. BIS certification requirements for food-contact metals create compliance barriers for unbranded imports. Mumbai and Delhi-NCR leatherworking clusters develop full-grain wrapping capabilities for premium export orders.
Hip Flask Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure. Integrated stainless steel fabricators with captive electropolishing lines capture margin on food-contact compliance, while assembly-only brands rely on contract finishing in Zhejiang or North Rhine-Westphalia. Three archetypes dominate: heritage outdoor equipment manufacturers extending thermal-vessel expertise, vertically controlled leathercraft specialists, and direct-to-consumer personalization platforms. Capacity expansion and laser engraving automation constitute the primary competitive vectors, with compliance certification serving as a secondary differentiator in EU and US markets.
Among heritage-positioned outdoor brands, Stanley PMI and GSI Outdoors exemplify the thermal-technology extension archetype, leveraging vacuum-insulation heritage into adjacent portable beverage categories. Leatherology occupies a position within the vertically controlled craft tier, with its name signaling captive leather operations. SWIG Hip Flasks anchors the personalization-specialist segment, with its name indicating direct-to-consumer bespoke positioning. These three representations illustrate how competitive advantage fragments across material expertise, regulatory compliance, and customization capability rather than concentrating in scale alone.
| Leading Market Players |
|---|
| Snow Peak Co., Ltd. |
| Leatherology |
| Stanley PMI |
| Klean Kanteen |
| Visol Products |
| GSI Outdoors |
| Maxam |
| Marlborough of England |
| SWIG Hip Flasks |
| Others |
Supply & Pricing Matrix
Fiber laser engraving automation is collapsing personalization cost curves while concentrating margin capture among producers with in-house electropolishing capabilities, simultaneously reshaping competitive economics and supplier tier consolidation across the hip flask value chain.
Pricing Analysis
Margin tightening in mid-tier 0.5mm-0.8mm wall thickness segments reflects nickel and chromium input cost volatility that constitutes 35-45% of landed cost. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and customization depth, with FDA-compliant electropolished 18/8 grades commanding sustained premiums over decorative alloys. Cost compression accelerates in copolyester festival variants as Yiwu wholesale channels displace branded distribution. Price-sensitive casual users in mass-market supermarket placements exhibit highest elasticity, while wedding planners and outdoor enthusiasts demonstrate lowest sensitivity to per-unit premiums.
Supply Chain Analysis
Electropolishing technician scarcity in Zhejiang province and North Rhine-Westphalia constrains food-contact finishing capacity expansion despite export demand growth. Manufacturing gravity centers on China for stainless steel fabrication, Germany for REACH-compliant surface treatment, and India for emerging leather wrapping operations. Raw material dependencies draw from nickel-chromium alloy feedstock, full-grain hide supplies, and borosilicate glass for boutique distillery collaborations. Single-source vulnerability concentrates in electropolishing houses with ECHA-certified closed-loop chemical recovery systems. Distribution runs through direct-to-consumer platforms, outdoor equipment retailers, and airport duty-free operators with divergent working capital profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hip flask market is becoming a vertical-integration race, with captive electropolishing lines and laser engraving automation serving as the decisive upstream and downstream levers separating margin-protected producers from assembly-only brands.
For Market Incumbents: Deepen control over food-contact finishing capacity through backward integration into electropolishing operations or long-term offtake agreements with Zhejiang and North Rhine-Westphalia houses. Incumbents must simultaneously defend against vacuum-insulated bottle substitution from outdoor equipment manufacturers by anchoring premium positioning in gift-giving occasions where thermal retention offers limited advantage.
For New Entrants and Emerging Players: Launch via TikTok Shop and Instagram Checkout to compress discovery-to-purchase cycles for occasion-driven buyers in the United States and United Kingdom. White space concentrates in Indian wedding gifting culture, where custom-engraved stainless steel alternatives remain underpenetrated versus traditional silver vessels for groomsmen parties.
For Investors and Strategic Acquirers: Exit pathways concentrate in direct-to-consumer personalization platforms with automated engraving capabilities and integrated electropolishing compliance. Long-term viability hinges on regulatory certification moats rather than scale alone. Watch for ECHA REACH candidate list enforcement tightening as the inflection signal that rewards certified supply chain investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser Engraving Automation Investment | Fiber laser systems collapse personalization costs from hours to minutes for mass customization economics. |
| Electropolishing Capacity Expansion | Captive food-contact finishing lines in Zhejiang or North Rhine-Westphalia secure FDA and REACH compliance margins. |
| Direct-to-Consumer Platform Launch | TikTok Shop and Instagram Checkout bypass specialty retail markup layers for occasion-driven discovery. |
| REACH-Compliant Supply Chain Certification | ECHA surface coating restrictions favor producers with closed-loop chemical recovery and certified tanning agents. |
| Indian Wedding Market Entry | Custom-engraved groomsmen alternatives penetrate white space against traditional silver vessel gifting culture. |
Research Methodology
Multi-period observation of camping participation rates, laser engraving equipment installations, and REACH enforcement patterns anchored the trend analysis, supplemented by interviews with stainless steel fabricators, electropolishing house operators, wedding planners, outdoor equipment buyers, and specialty store merchandisers. Secondary validation drew from FDA food-contact substance filings, ECHA candidate list updates, U.S. Forest Service recreation statistics, and customs trade data for 18/8 stainless steel vessel imports. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Segment-weighting across material grades, capacity tiers, design categories, and distribution channels structured the analytical framework across the projection horizon. CAGRs were derived from installed base growth, replacement cycle analysis, and per-capita equipment upgrade rates. Industry-specific forecast inputs incorporated fiber laser adoption curves, ECHA authorization timelines, and social commerce penetration data for occasion-driven purchase occasions.
Nickel price volatility, ECHA regulatory tightening, and vacuum-insulated bottle substitution acceleration are the dominant revision risks that could compress demand elasticity or redirect portable beverage occasions. Forecasts reflect assumptions about sustained outdoor recreation participation and stable alloy input costs. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
High-End Baijiu Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
Europe Craft Spirits Market
Alcoholic Beverages
Beer Processing Market
Alcoholic Beverages
Kegs Market
Alcoholic Beverages
Canned Cocktails Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
North America Craft Beer Market
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
Japan Alcohol E-Commerce Market
Alcoholic Beverages
Malt Beverages Market
Alcoholic Beverages
Gin and Tonic Tea Market
Alcoholic Beverages
Champagne Market
Alcoholic Beverages
Hard Tea Market