
 Cider and Perry Market | 2026-2036
Cider and Perry Market Size, Share, and Industry Trends Forecast 2026-2036
Cider and Perry Market Analysis
Multi-source apple procurement is recalibrating supply economics for mid-sized producers. Heineken N.V. leverages its integrated European orchard network to secure varietal consistency across seasonal harvests. C&C Group PLC anchors its cost position through long-term contracts with Irish and British growers. Thatchers Cider differentiates via estate-grown fruit from its Somerset orchards, reducing third-party dependency.
Cider and perry denote fermented beverages produced from apple juice and pear juice respectively, typically achieving alcohol content between 1.2% and 8.5% ABV through controlled yeast fermentation of fruit sugars. The category serves both refreshment-oriented casual consumption and gastronomic pairing occasions across on-trade and off-trade channels. Hard cider occupies the dominant revenue position within product type segmentation, while canned formats within packaging type are gaining fastest as brewers target outdoor and festival occasions. Supermarkets within distribution channel still capture the largest volume flows, though margin pools are deepening in specialty stores where single-varietal and barrel-aged expressions command price premiums.
FDA labeling requirements in the United States mandate alcohol content disclosure and allergen statements for imported cider, while EU Regulation 1169/2011 governs nutritional labeling and ingredient transparency across member states. The United Kingdom's Alcohol Duty Reform shifts taxation toward strength-based bands, incentivizing producers to manage ABV targets precisely. Stakeholders must monitor how evolving low-and-no-alcohol thresholds in national tax codes reshape permissible formulations and competitive positioning.
Market Dynamics
Strength-based excise bands in the United Kingdom are forcing producers to recalibrate ABV targets across entire product portfolios. This regulatory compression is reshaping formulation priorities from premium positioning toward precise alcohol management.
Growth Catalysts
- United Kingdom Alcohol Duty Reform:Strength-based taxation tiers incentivize sub-3.5% ABV innovation, opening session-format volume pools previously constrained by flat-rate structures.
- Carbon labeling mandates in France:Retailers now require emissions disclosure, accelerating orchard-to-bottle traceability investments that differentiate craft producers in export channels.
- West Country orchard heritage:Traditional production credentials in Somerset and Herefordshire attract premium buyers seeking provenance-authenticated products for gastronomic pairing occasions.
Market Restraints
- Apple input cost volatility:Dessert and culinary fruit prices fluctuate with agricultural commodity cycles, squeezing margins for producers lacking estate-grown supply.
- Concentrated southern hemisphere supply:Bulk concentrate imports from Argentina and Chile create dependency on shipping lane reliability and currency exposure.
- Technical limitation in low-alcohol fermentation:Yeast strain performance below 2.5% ABV produces inconsistent flavor profiles, constraining product development pipelines.
Strategic Opportunities
- Underpenetrated German market:Per capita cider consumption remains one-fifth of United Kingdom levels, presenting white space for English and Irish producers with established brand equity.
- Outdoor festival channel expansion:Canned format penetration at music and sporting events captures incremental occasion-based consumption outside traditional pub and supermarket routes.
- EU Green Deal agricultural incentives:Orchard restoration grants for biodiversity corridors reduce establishment costs for heritage varietal plantings with carbon sequestration credentials.
Industry Challenges
- Master cider maker talent scarcity:Traditional orchard management and wild fermentation expertise is concentrating among aging practitioners in England's West Country, constraining craft scaling.
- Organic certification timeline compression:Three-year conversion periods for orchard land limit rapid response to retailer sustainability mandates, locking out producers from premium shelf placements.
- Legacy cooperage integration:Barrel-aged expression programs require capital-intensive oak sourcing and cellaring infrastructure that conflicts with working capital efficiency targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cider and Perry Market |
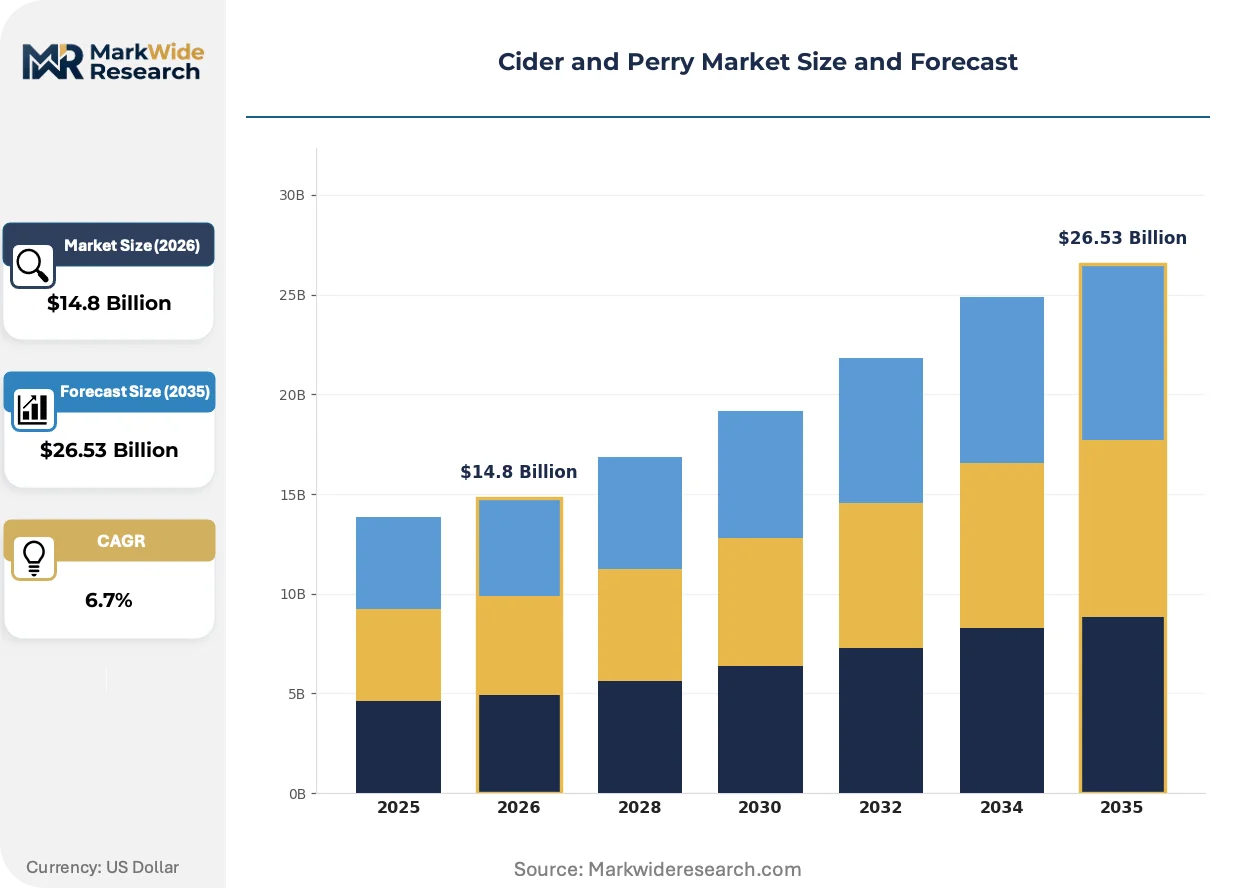
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Cider, Soft Cider, Perry, Sparkling Cider Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Flavor Profile: Dry, Sweet, Fruity, Spiced Packaging Type: Bottles, Cans, Kegs, Tetra Packs |
| Companies Covered | Heineken N.V., Asahi Group Holdings, C&C Group PLC, Thatchers Cider, Westons Cider, AB InBev, Carlsberg Breweries A/S, Kopparbergs Bryggeri AB, The Boston Beer Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cider and Perry Market Emerging Trajectories
Controlled fermentation technologies and packaging format diversification are compressing traditional production cycles. These shifts are enabling new occasion-based positioning while regulatory transparency requirements reshape competitive differentiation.
Precision temperature-controlled fermentation is electrifying quality consistency across seasonal harvest variation. Mid-sized producers in Somerset and Herefordshire are adopting sensor-networked tanks to manage wild yeast populations. This technology is electrifying the ability to replicate flavor profiles year-to-year, reducing reliance on blending expertise concentrated among veteran cider makers.
United Kingdom Alcohol Duty Reform implementation is restructuring portfolio architecture across the category. Producers must now optimize ABV bands to minimize tax liability rather than maximize sensory impact. Sub-3.5% ABV expressions are receiving disproportionate innovation investment, particularly for supermarket private label contracts where price elasticity is highest.
Festival and outdoor occasion consumption is displacing traditional on-trade pub occasions for volume growth. Younger demographics in Bristol, Manchester, and London are purchasing canned formats at music events and sporting fixtures. This behavioral rotation is most visible in summer trading periods, where off-premise convenience channels capture margin previously retained by licensed premises.
Cider and Perry Market Segmentation
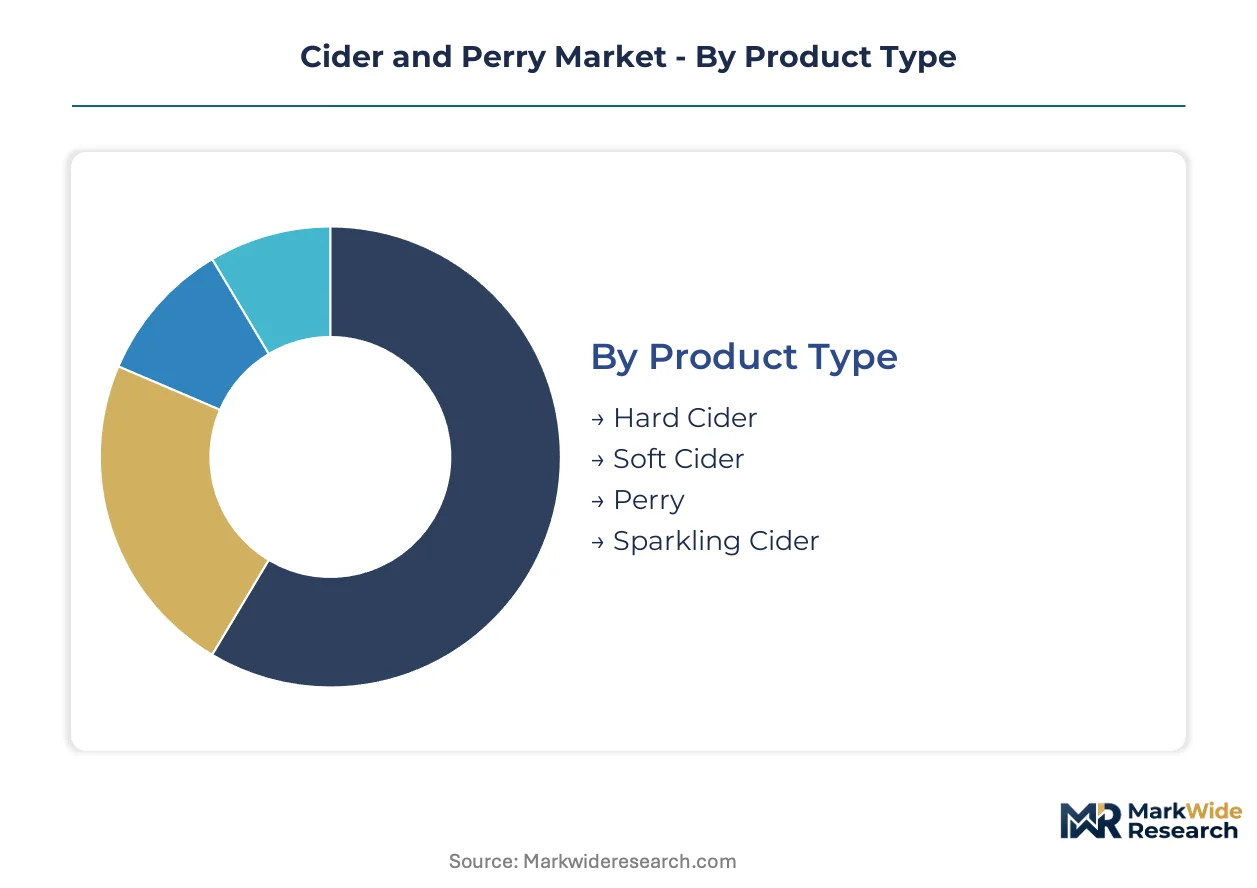
Segmentation in cider and perry reveals how supply-side capabilities align with occasion-based demand. Orchard estate scale, fermentation infrastructure, and packaging investments determine which producers can serve specific channel and format requirements.
Product Type:
Supply concentration among West Country orchard estates favors producers with captive apple supply for higher-ABV fermentation programs.
- Hard Cider:Fermented to 4-8.5% ABV using cider-specific bittersweet and bittersharp apple varieties. Demand concentrates in England's on-trade pubs and gastropubs where ABV-based excise tiers under United Kingdom Alcohol Duty Reform incentivize precise alcohol management.
- Soft Cider:Non-alcoholic or sub-0.5% ABV expressions produced through arrested fermentation or dealcoholization. Growth accelerates in supermarket channels where health-conscious consumers seek sessionable alternatives without duty liability.
- Perry:Traditional pear juice fermentation yielding delicate, tannic profiles distinct from apple-based products. Production clusters in Herefordshire and Gloucestershire where perry pear orchards retain heritage varietal stock.
- Sparkling Cider:Carbonated expressions achieving effervescence through bottle conditioning or forced carbonation. Premium positioning targets gastronomic pairing occasions in Bristol and London restaurant channels.
Hard Cider absorbs the bulk of installed capacity; Soft Cider is expanding most quickly.
Distribution Channel:
Margin structure varies sharply across channels, with specialty stores capturing disproportionate value per liter despite lower volume throughput.
- Supermarkets:High-volume, low-margin route commanding largest absolute sales but pressuring producers through private-label contract terms and slotting fee structures.
- Online Retail:Direct-to-consumer and third-party marketplace sales enabling subscription models and limited-release allocations. Fastest channel expansion as producers bypass traditional wholesale markups.
- Specialty Stores:Independent off-licenses and farm shops supporting premium pricing for single-varietal and barrel-aged expressions. Concentrated demand in Somerset and Herefordshire tourism corridors.
- Convenience Stores:Impulse-purchase oriented with space constraints favoring multi-pack cans and recognized brand names over craft introductions.
Supermarkets dominate volume flows; Online Retail posts the steepest expansion trajectory.
Flavor Profile:
Consumer palate evolution is fragmenting production runs, requiring smaller batch sizes that favor craft scale over industrial efficiency.
- Dry:Residual sugar below 10g/L emphasizing tannin structure and acidity for gastronomic pairing. Demand concentrates in London and Bristol on-trade where sommelier-driven cider programs compete with wine lists.
- Sweet:Higher residual sugar appealing to entry-level consumers and traditional West Country pub drinkers. Volume leadership in working-class on-trade occasions across Somerset and Devon.
- Fruity:Adjunct-infused expressions incorporating berry, stone fruit, or tropical flavors. Fastest-growing profile among younger demographics at festival and outdoor occasions.
- Spiced:Seasonal winter variants with cinnamon, nutmeg, or ginger additions. Concentrated demand in fourth-quarter retail cycles and Christmas market channels.
Dry expressions command premium shelf positioning; Fruity profiles are gaining share fastest.
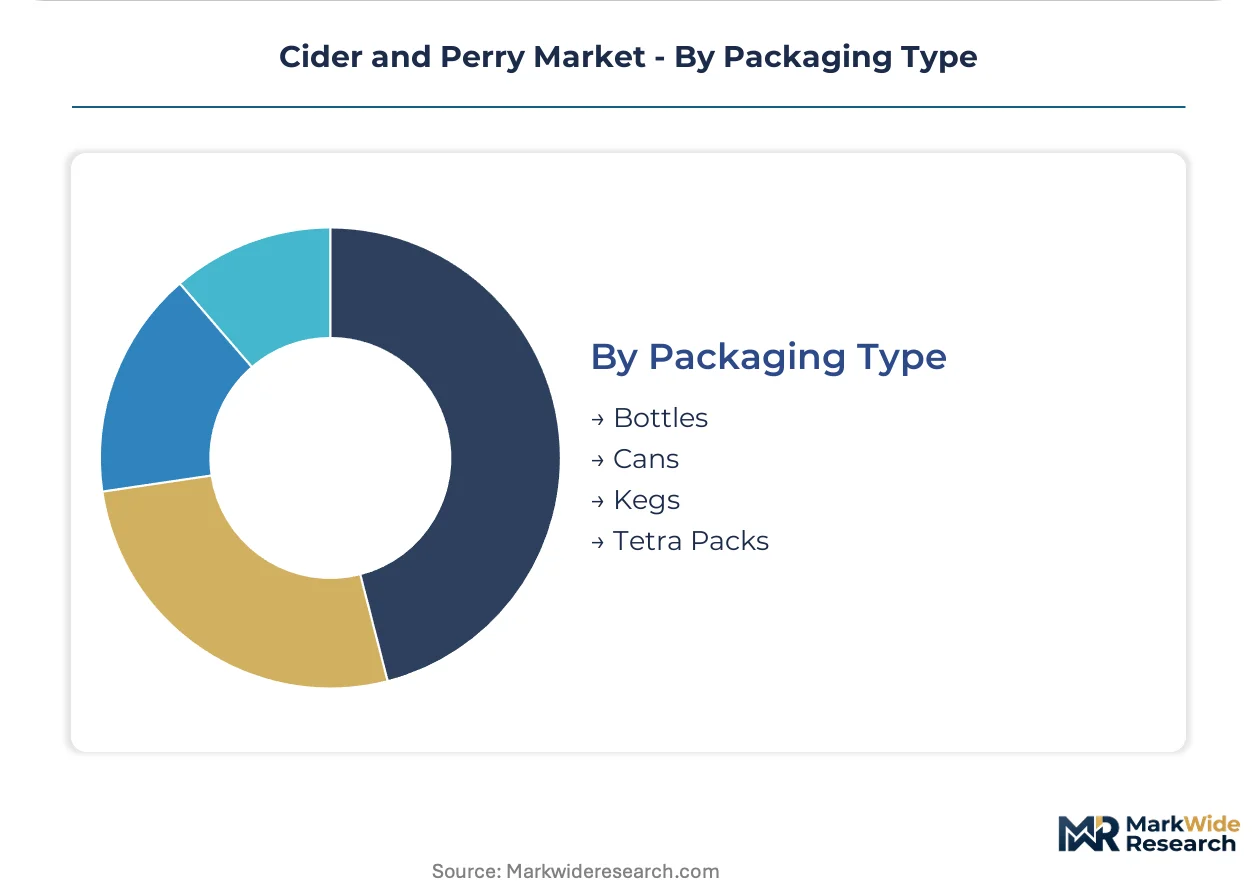
Packaging Type:
Capital equipment requirements for canning versus bottling lines are reshaping producer investment priorities and outsourcing decisions.
- Bottles:Traditional 500ml and 750ml glass formats dominating off-trade premium positioning. Higher per-unit logistics costs constrain distribution radius for small producers.
- Cans:Aluminum formats capturing outdoor and festival occasion growth with lighter weight and lower breakage risk. Fastest format expansion as producers target music event and sporting fixture channels.
- Kegs:Stainless steel and PET kegs serving on-trade draft programs with superior margin capture versus packaged goods. Concentrated demand in Bristol, Manchester, and London craft beer bars.
- Tetra Packs:Aseptic carton formats for value-oriented retail and export markets with extended shelf stability. Limited penetration in domestic United Kingdom premium channels.
Bottles retain the largest installed packaging base; Cans are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
English cider apple orchards in Somerset and Herefordshire anchor the industry's geographic concentration. These West Country estates supply heritage bittersweet varieties that define premium positioning across export channels.
United Kingdom
Session-format consumption in Bristol and London pubs drives demand for sub-3.5% ABV expressions. The Alcohol Duty Reform shifts taxation toward strength-based bands, pressuring precise ABV management. Somerset's Thatchers Cider estate exemplifies vertical orchard control that reduces third-party fruit dependency.
France
Gastronomic pairing occasions in Paris and Lyon restaurants elevate dry tannic profiles for wine-list integration. Carbon labeling mandates under EU Green Deal implementation require emissions disclosure from orchard to bottle. Brittany's traditional cider producers invest in traceability infrastructure to access premium retail placements.
United States
Outdoor festival consumption in Portland and Seattle accelerates canned format penetration among younger demographics. FDA labeling requirements mandate alcohol content disclosure and allergen statements for imported products. Michigan's Great Lakes orchard region develops cold-hardy varietal programs for climate resilience.
Germany
Per capita consumption at one-fifth of United Kingdom levels presents expansion white space for English and Irish exporters. EU Regulation 1169/2011 governs nutritional labeling and ingredient transparency across member states. Bavaria's beverage distributors trial English craft ciders in metropolitan Munich channels.
Australia
Seasonal summer trading periods concentrate demand in Sydney and Melbourne outdoor venues. The country's national food standards regulator mandates additive disclosure for fruit wine classifications. Tasmania's cool-climate orchards supply aromatic varieties for sparkling expression programs targeting Asian export markets.
Cider and Perry Market Vendor Landscape
Portfolio diversification dominates the current landscape as producers recalibrate ABV targets across entire product ranges. The vendor base concentrates among integrated beverage conglomerates, mid-sized estate producers, and regional craft specialists. Three archetypes define competitive positioning: multinational brewers leveraging distribution scale, orchard-estate producers emphasizing provenance credentials, and contract-dependent craft operators seeking channel differentiation. M&A activity and strategic partnerships reshape category ownership as alcohol duty reforms alter profitability thresholds.
Among multinational brewers, Heineken N.V. and Carlsberg Breweries A/S occupy positions defined by integrated European orchard networks and cross-category beverage portfolios. Within the estate-producer tier, Thatchers Cider exemplifies vertical orchard control through Somerset-grown fruit supply. C&C Group PLC represents the contract-anchored model securing cost position via long-term Irish and British grower agreements.
| Leading Market Players |
|---|
| Heineken N.V. |
| Asahi Group Holdings |
| C&C Group PLC |
| Thatchers Cider |
| Westons Cider |
| AB InBev |
| Carlsberg Breweries A/S |
| Kopparbergs Bryggeri AB |
| The Boston Beer Company, Inc. |
| Others |
Supply Flow & Price Mechanics
Master cider maker concentration in England's West Country compresses labor supply for traditional fermentation expertise, widening spreads between estate-grown premium tiers and contract-dependent economy positioning as orchard wages outpace supermarket private-label returns.
Pricing Analysis
Warranty-style provenance guarantees differentiate premium estate tiers from unbundled contract-sourced economy lines. Three-tier pricing structure across premium, standard, and economy levels reflects ABV band optimization under United Kingdom Alcohol Duty Reform, estate orchard certification, and barrel-aging program investment. Pricing pressure stems from apple input cost volatility squeezing mid-sized producers without captive supply. Supermarket private-label buyers exhibit highest price sensitivity; London gastropub sommeliers show lowest sensitivity for single-varietal expressions.
Supply Chain Analysis
Bittersweet apple supply rests on English West Country orchards, Irish contract growers, and Argentine bulk concentrate exporters. Heritage varietal propagation, yeast strain cultivation, and oak cooperage sourcing constitute critical input dependencies. Single-source vulnerability concentrates in aging master cider maker expertise for wild fermentation programs. Distribution runs through integrated brewer networks, independent wholesalers, and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master cider maker scarcity constrains craft scaling capacity, propping premium-tier pricing as estate producers defend orchard-controlled supply positions against contract-dependent competitors.
For Market Incumbents: Anticipate ABV band compression under United Kingdom Alcohol Duty Reform by accelerating sub-3.5% session format innovation pipelines. Secure backward integration into heritage varietal propagation programs to reduce Argentine concentrate dependency. Channel control through direct-to-consumer subscription models defends margin against supermarket private-label erosion.
For New Entrants and Emerging Players: Capture German market white space where per capita consumption trails United Kingdom levels by four-fifths, leveraging English craft credentials in Munich metropolitan trial programs. Festival and outdoor occasion channels present penetrable entry points through canned format specialization, bypassing entrenched on-trade pub relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated estate producers given carbon labeling mandate acceleration across EU export channels. Five-to-ten year viability favors Somerset and Herefordshire orchard holdings with biodiversity corridor certification. Watch United Kingdom Alcohol Duty Reform threshold adjustments as volume inflection signal for session-format portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Varietal Orchard Expansion | EU Green Deal restoration grants reduce establishment costs for carbon-sequestering biodiversity corridors in Somerset. |
| Sub-3.5% ABV Portfolio Recalibration | United Kingdom Alcohol Duty Reform strength-based bands minimize tax liability in highest-volume supermarket contracts. |
| Carbon Labeling Traceability Investment | French retailer mandates require orchard-to-bottle emissions disclosure for premium shelf placement access. |
| Festival Channel Canned Format Penetration | Outdoor music and sporting events capture occasion-based consumption outside traditional licensed premises routes. |
| Direct-to-Consumer Subscription Launch | Bypassing wholesale markups deepens margin capture for limited-release single-varietal and barrel-aged expressions. |
Methodological Framework
Independent corroboration across primary orchard estate interviews, cider maker guild consultations, and regulatory filing reviews underwrites the qualitative findings. Discussions with Somerset and Herefordshire production directors, Bristol and London on-trade buyers, supermarket category managers, and EU agricultural policy specialists combined with United Kingdom HMRC excise data, French DGCCRF labeling enforcement records, and Irish Bord Bia export statistics. Bottom-up volume triangulation against top-down value estimates validates segmentation outputs.
Comparable historical reference periods anchored the projection framework across the analysis window. Modeling incorporated product type, distribution channel, packaging format, and regional regulatory cluster dimensions. CAGRs derived from trend extrapolation adjusted for duty reform impacts and orchard capacity constraints. Forecast inputs included ABV band optimization patterns and carbon labeling compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to United Kingdom Alcohol Duty Reform threshold revisions and climate-driven apple harvest variability. Projections reflect documented assumptions regarding excise band stability and EU Green Deal agricultural incentive continuity. A small set of triggers—duty tier adjustments, master cider maker attrition rates, and French carbon disclosure enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Grain Alcohol Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Beer Filter System Market
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Italy Alcohol E-Commerce Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
Still Wine Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Irish Whiskey Market
Alcoholic Beverages
North America Mezcal Market
Alcoholic Beverages
Asia-Pacific Alcohol E-Commerce Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
N-Hexyl Alcohol Market