
 Global Twister Winder Market | 2026-2036
Global Twister Winder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Twister Winder Market Intelligence
Asian textile machinery production is consolidating as regional supply chains deepen local content requirements. Rieter leverages its Swiss engineering heritage to sustain premium positioning in electronic control systems for high-speed twisting operations. Lohia Group anchors the Indian market through extensive manufacturing scale in Surat, while Savio India Limited competes on aftermarket service density across Tamil Nadu and Maharashtra textile belts.
A twister winder is a rotating spindle machine that applies controlled twist to continuous filament or staple fiber yarns, typically operating at surface speeds between 8,000 and 15,000 meters per minute to produce plied or cable-twisted constructions for downstream weaving and knitting. The device serves the essential purpose of consolidating multiple strands into uniform, torque-balanced yarn packages that meet tensile and abrasion specifications for industrial and apparel fabrics. Automatic twister systems now dominate capital expenditure flows as mills prioritize labor reduction and lot traceability, while programmable twisters represent the fastest-growing technology tier where recipe-driven changeovers justify premium pricing. Electronic control architectures are displacing mechanical drive systems in new installations, though pneumatic operation retains cost advantages in mid-volume rope making and composite fabrication niches.
EU machinery safety directives and CE marking requirements shape export eligibility for Indian and Chinese original equipment manufacturers serving European textile producers. India's BIS certification and China's GB standards for textile machinery create parallel compliance tracks that influence product architecture decisions at Himson Engineering and Galan Textile Machinery. Stakeholders must monitor how carbon border adjustment mechanisms and emerging digital product passport rules recalibrate total cost of ownership calculations for twister winder investments across major sourcing regions.
Market Dynamics
Energy efficiency mandates under EU Ecodesign and parallel frameworks in India and China are compressing replacement cycles toward programmable and automatic twister winder architectures, reshaping capital allocation across integrated textile clusters.
Growth Catalysts
- EU Ecodesign Directive:Energy labeling and minimum efficiency standards for industrial motors are accelerating retirement of mechanical drive systems in European spinning operations.
- Yarn producers in Vietnam:Regional capacity expansion in filament and staple fiber production is absorbing new twister winder installations for export-oriented textile manufacturing.
- Electronic control architectures:Recipe-driven changeover capabilities are reducing lot transition times and enabling traceability compliance for premium apparel supply chains.
Market Restraints
- Copper and rare earth magnet costs:Volatility in permanent magnet materials for high-efficiency spindle motors compresses margin structures for mid-tier equipment builders.
- Surat machinery cluster concentration:Geographic concentration of Indian domestic supply creates vulnerability to regional logistics disruptions and input cost synchronization.
- Pneumatic system substitution ceiling:Compressed air infrastructure limitations in older mill facilities cap upgrade paths for certain rope-making and composite fabrication applications.
Strategic Opportunities
- Bangladesh textile manufacturing:Underpenetrated automatic twister installation base presents first-mover advantage for programmable system vendors establishing local service presence.
- Carbon border adjustment mechanisms:Emerging EU CBAM rules on embedded emissions in imported textiles are incentivizing energy-efficient machinery investments in exporting countries.
- Digital product passport integration:Convergence of IoT-enabled twister winders with blockchain traceability platforms opens premium pricing for lot-verified yarn production.
Industry Challenges
- Mechatronics technician scarcity:Shortage of skilled personnel capable of servicing electronic control systems and servo drive diagnostics limits aftermarket service expansion.
- Legacy mechanical system integration:Retrofitting programmable controls onto existing pneumatic and mechanical twister frames creates compatibility failures and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Twister Winder Market |
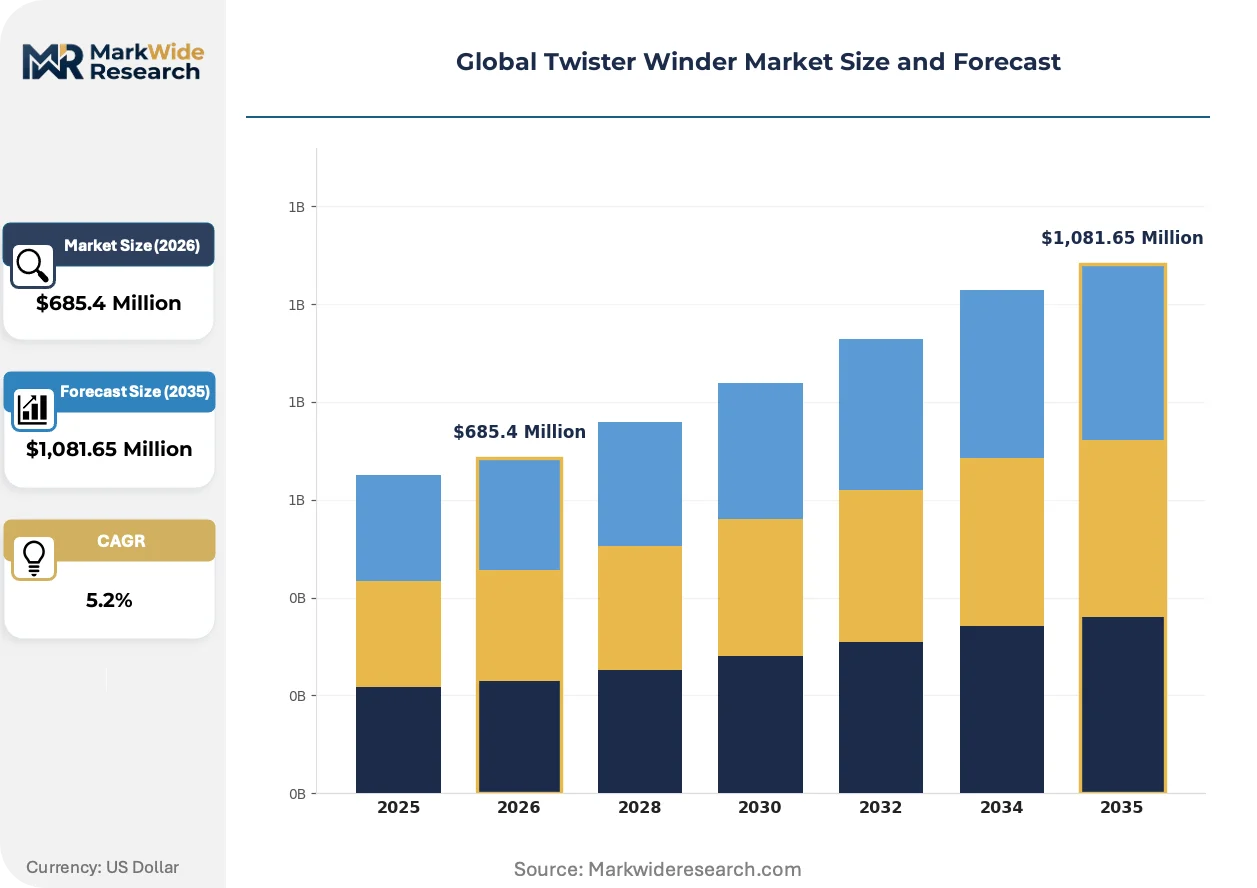
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Twister, Semi-Automatic Twister, Manual Twister, Programmable Twister End User Industry: Textile Manufacturing, Wire & Cable Production, Rope Making, Composite Fabrication Technology: Electronic Control, Pneumatic Operation, Hydraulic Mechanism, Mechanical Drive Distribution Channel: Direct Sales, Distributors, Online Marketplaces, Industrial Equipment Dealers |
| Companies Covered | Lohia Group, Rieter, Jeyaletshmi Machine Works, Himson Engineering Pvt. Ltd, Savio India Limited, SIMA S.R.L., Meera Industries Limited, Galan Textile Machinery, S.L., Jaylaxmi Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Twister Winder Market Strategic Shifts & Innovations
Electronic architectures are displacing mechanical drive trains across new installations, while regulatory pressure on energy intensity and labor costs accelerates automation adoption in clustered textile geographies.
Servo-controlled spindle systems with integrated torque feedback are automating tension regulation across varying yarn counts and twist coefficients. Large integrated mills in the Yangtze River Delta are deploying these systems at scale for synthetic filament processing. This automation is compressing the skilled operator headcount required per production line while tightening twist uniformity tolerances for technical textile applications.
China's GB standards for textile machinery energy efficiency are mandating variable frequency drive adoption and standby power limits for new equipment registrations. Domestic manufacturers in Jiangsu and Zhejiang provinces are redesigning power electronics to meet these thresholds. The directive most affects mid-volume producers seeking export eligibility into regulated European markets, forcing architecture decisions at the design stage.
Integrated mills are consolidating procurement authority toward direct relationships with machinery builders, bypassing traditional distributor networks for twister winder acquisitions. Tamil Nadu and Maharashtra textile belts demonstrate this pattern most clearly, where scale buyers negotiate lifecycle service contracts alongside equipment purchases. The shift favors domestic Indian builders with dense field service presence over import-reliant distribution channels.
Global Twister Winder Market Segmentation
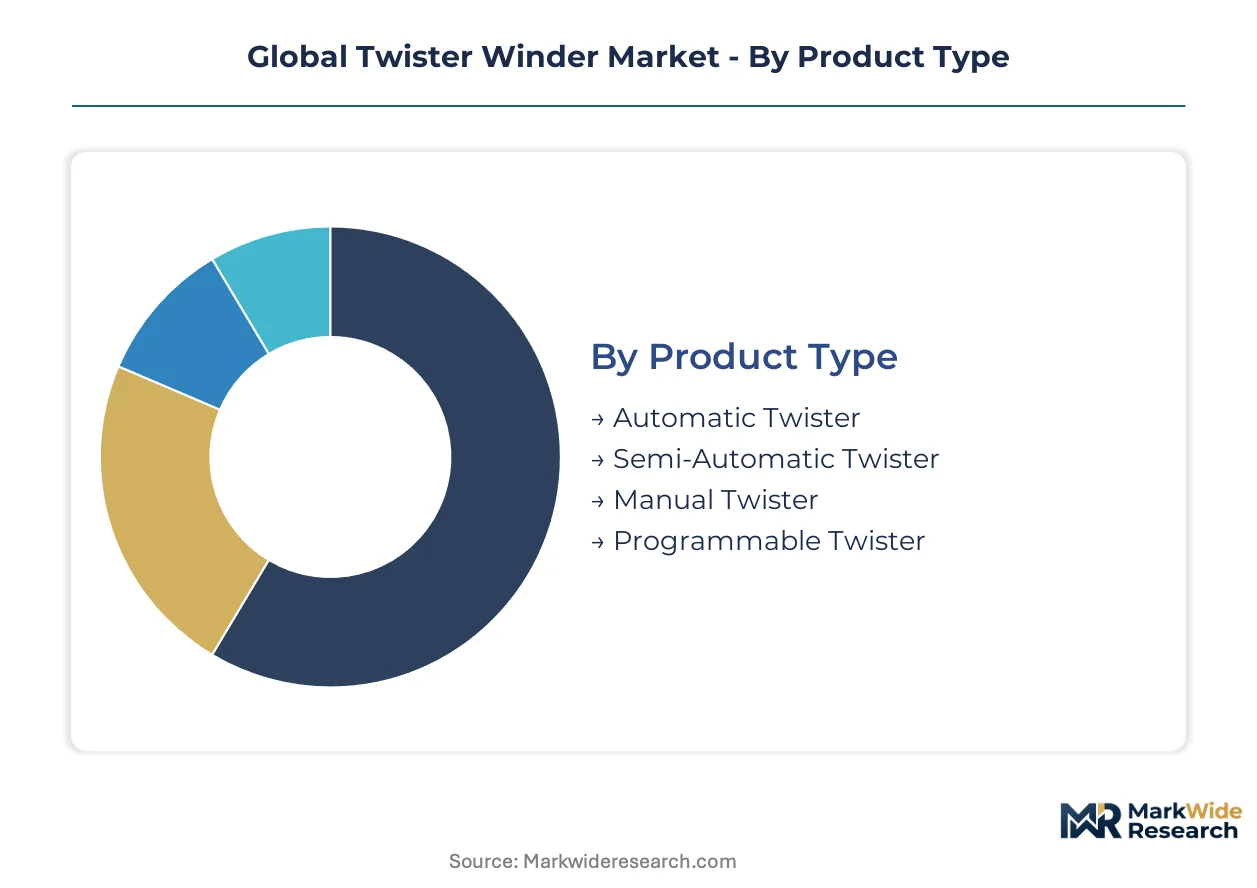
Twister winder procurement patterns diverge sharply across automation tiers and downstream applications. Mills in clustered textile geographies prioritize capital equipment that compresses labor headcount while satisfying energy efficiency mandates.
Product Type:
Upgrade cycles favor architectures that reduce mechanical complexity and enable recipe-driven operation.
- Automatic Twister:Servo-controlled spindle systems with integrated tension feedback dominate capital expenditure flows at large integrated mills. Yangtze River Delta synthetic filament processors deploy these at scale for technical textile applications requiring tight twist uniformity tolerances.
- Programmable Twister:Recipe-driven changeover capabilities justify premium pricing where lot traceability compliance commands supply chain premiums. Bangladesh and Vietnam textile manufacturers absorb these systems fastest as they retrofit for EU export eligibility.
- Semi-Automatic Twister:Mid-tier Indian mills in Surat and Coimbatore favor these for batch flexibility without full automation capital burden.
- Manual Twister:Artisan rope makers and small composite fabricators retain these for low-volume specialty constructions.
Volume placements concentrate in Automatic Twister configurations; the faster expansion belongs to Programmable Twister systems.
End User Industry:
Application-specific torque and abrasion requirements dictate spindle speed and package build specifications.
- Textile Manufacturing:Integrated yarn-to-fabric operations in Tamil Nadu and Maharashtra source twister winders directly from domestic machinery builders. EU Ecodesign Directive compliance now filters equipment selection for European market access.
- Wire & Cable Production:Continuous filament stranding for electrical conductors demands precision tension control across varying conductor gauges.
- Rope Making:Pneumatic systems retain cost advantages in mid-volume marine and industrial cordage facilities with existing compressed air infrastructure.
- Composite Fabrication:Carbon fiber and glass fiber twisting for aerospace prepregs requires cleanroom-compatible electronic architectures.
Textile Manufacturing absorbs the dominant equipment flow; Composite Fabrication climbs fastest on technical materials demand.
Technology:
Energy intensity regulations are compressing the viable lifespan of legacy drive systems.
- Electronic Control:Variable frequency drives with standby power management meet China's GB standards for textile machinery energy efficiency. Jiangsu and Zhejiang manufacturers redesign power electronics to secure export eligibility into regulated European markets.
- Pneumatic Operation:Compressed air systems face upgrade ceiling constraints in older mill facilities lacking infrastructure capacity.
- Hydraulic Mechanism:Heavy-duty rope and cable applications retain these for high-torque twisting of thick strand constructions.
- Mechanical Drive:Retirement accelerates as EU minimum efficiency standards for industrial motors render these uneconomical to maintain.
Electronic Control captures the majority of new installations; Mechanical Drive contracts most sharply under regulatory pressure.
Distribution Channel:
Procurement authority consolidation favors direct manufacturer relationships over intermediated channels.
- Direct Sales:Scale buyers negotiate lifecycle service contracts alongside equipment purchases, bypassing traditional distributor networks. Savio India and Lohia Group leverage dense field service presence in Surat and Coimbatore to capture this shift.
- Distributors:Regional equipment dealers retain relevance for mid-tier mills seeking financing arrangements and local commissioning support.
- Online Marketplaces:Spare parts and consumables procurement migrates to digital platforms for standardized components.
- Industrial Equipment Dealers:Used machinery and refurbishment channels serve cost-constrained entrants in Bangladesh and Vietnam.
Direct Sales commands the largest transaction value; Online Marketplaces expand most rapidly for aftermarket parts fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cotton and synthetic fiber processing clusters in South Asia and East Asia drive twister winder procurement intensity. Germany and Switzerland anchor European machinery engineering exports. Vietnam and Bangladesh absorb capacity expansion from relocated textile manufacturing.
China
Synthetic filament processors in Jiangsu and Zhejiang provinces deploy servo-controlled spindle systems at scale. MIIT enforces GB standards for textile machinery energy efficiency through variable frequency drive mandates. The Yangtze River Delta hosts integrated mills sourcing twister winders directly from domestic machinery builders.
India
Tamil Nadu and Maharashtra textile belts prioritize automatic twister architectures for labor reduction. BIS certification requirements shape product architecture decisions for equipment serving domestic and export markets. Surat machinery cluster concentration creates geographic vulnerability to logistics disruptions despite manufacturing scale advantages.
Germany
EU Ecodesign Directive minimum efficiency standards for industrial motors accelerate retirement of mechanical drive systems. CE marking requirements filter export eligibility for Indian and Chinese original equipment manufacturers. Engineering heritage sustains premium positioning in electronic control systems for high-speed twisting operations.
Vietnam
Regional yarn producers expand filament and staple fiber output for export-oriented textile manufacturing. Energy efficiency frameworks parallel to EU Ecodesign compress replacement cycles toward programmable architectures. Ho Chi Minh City and Hanoi corridors absorb new twister winder installations as integrated textile clusters deepen.
Bangladesh
Underpenetrated automatic twister installation base presents first-mover positioning for programmable system vendors. Carbon border adjustment mechanisms incentivize energy-efficient machinery investments for EU export eligibility. Dhaka and Chittagong manufacturing zones retrofit facilities for lot traceability compliance in premium apparel supply chains.
Global Twister Winder Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue electronic control specialization and aftermarket service density. The vendor base organizes around three archetypes: Swiss-engineered premium control specialists, Indian-scale domestic manufacturers with dense field presence, and European niche fabricators serving technical textile applications. Consolidation pressure favors direct manufacturer relationships over distributor intermediation. Competitive moves concentrate on lifecycle service contract bundling and geographic expansion through local commissioning partnerships.
Within the premium-tier vector, Rieter exemplifies Swiss-engineered heritage in electronic control architectures. Lohia Group and Savio India Limited anchor the Indian market through Surat-based manufacturing scale and Tamil Nadu service density respectively. Himson Engineering and Galan Textile Machinery occupy positions shaped by BIS certification and CE marking compliance requirements.
| Leading Market Players |
|---|
| Lohia Group |
| Rieter |
| Jeyaletshmi Machine Works |
| Himson Engineering Pvt. Ltd |
| Savio India Limited |
| SIMA S.R.L. |
| Meera Industries Limited |
| Galan Textile Machinery, S.L. |
| Jaylaxmi Industries |
| Others |
Cost & Logistics Intelligence
Permanent magnet materials for high-efficiency spindle motors flow from Chinese rare earth processors through Jiangsu and Zhejiang manufacturers into tiered equipment pricing. Copper winding costs and servo drive electronics compress margin structures at the mid-tier, pushing buyers toward lifecycle service contracts that bundle commissioning and aftermarket support.
Pricing Analysis
Warranty and field service bundling separates premium Swiss-engineered systems from unbundled Indian domestic offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—CE-marked and BIS-certified equipment commands service-inclusive premiums. Cost compression in mid-tier pneumatic retrofits is intensifying because copper and rare earth volatility erodes builder margins. Small Bangladeshi mills exhibit highest price sensitivity; large Yangtze River Delta synthetic processors prioritize energy efficiency compliance over upfront capital.
Supply Chain Analysis
Spindle motor production rests on Chinese rare earth magnet processors, German precision bearing manufacturers, and Japanese servo drive specialists. Power electronics, precision mechanical components, and control system subassemblies feed from these concentrated upstream nodes. Single-source vulnerability in permanent magnet supply creates exposure to export restriction shocks. Distribution runs through direct manufacturer relationships at scale buyers, with regional equipment dealers retaining relevance for mid-tier financing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
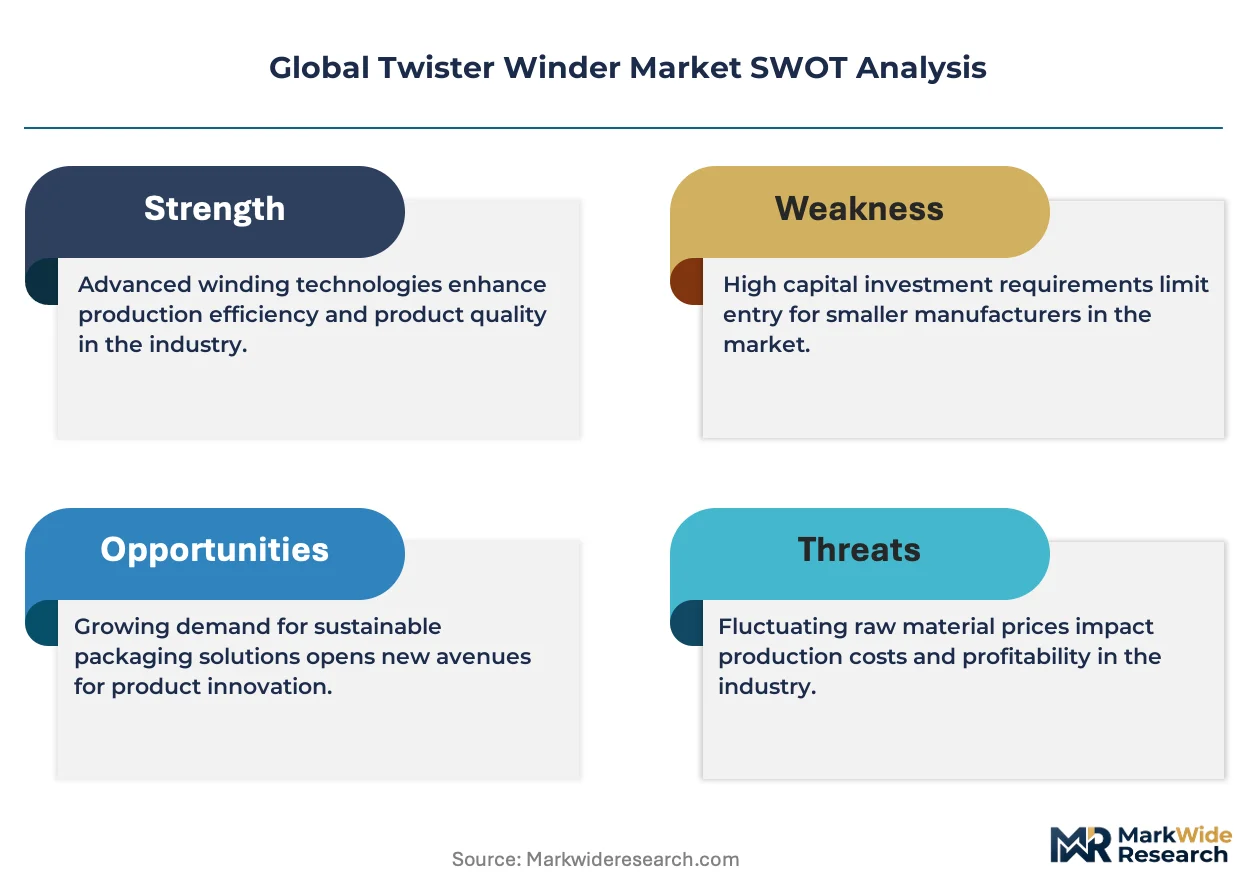
EU Ecodesign Directive energy efficiency mandates erect a compliance moat that favors incumbent electronic control specialists over mechanical legacy players. This cost-of-compliance barrier rewards early certification investment and locks out late entrants lacking capital for architecture redesign.
For Market Incumbents: Cement market position through backward integration into servo drive and power electronics manufacturing, capturing margin from volatile copper and rare earth supply chains. Expand field service density in Tamil Nadu and Maharashtra textile belts to lock in direct procurement relationships. Electronic control technician scarcity threatens aftermarket expansion; prioritize mechatronics training partnerships with regional technical institutes.
For New Entrants and Emerging Players: Enter via Bangladesh's underpenetrated automatic twister installation base, where programmable system demand outpaces established service presence. Target Dhaka and Chittagong manufacturing zones with EU export eligibility retrofit packages. Local commissioning partnerships with existing industrial equipment dealers provide lowest-friction go-to-market access.
For Investors and Strategic Acquirers: Carbon border adjustment mechanism implementation in EU textile imports is the leading indicator that energy-efficient machinery investments will accelerate in exporting countries. Long-term viability centers on electronic control specialization with dense aftermarket service networks. Acquirers should target Indian domestic builders with BIS certification and established Surat manufacturing scale. Watch for MIIT enforcement actions on GB standards as signal of Chinese export eligibility tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captures margin from volatile rare earth and copper supply chains in Jiangsu manufacturing clusters. |
| Lifecycle Service Contract Bundling | Locks in direct procurement relationships with Tamil Nadu and Maharashtra scale buyers. |
| Mechatronics Training Partnerships | Addresses technician scarcity limiting electronic control system aftermarket expansion. |
| EU Ecodesign Compliance Certification | Secures export eligibility into regulated European textile markets for Indian and Chinese OEMs. |
| Local Commissioning Partnerships | Enables market entry into Bangladesh and Vietnam through established industrial equipment dealer networks. |
Research Approach
Document review covered customs and trade data for textile machinery imports, BIS certification registries, and EU Ecodesign Directive implementation guidance, complemented by interviews with plant engineers at integrated yarn-to-fabric mills, aftermarket service heads at domestic machinery builders, OEM procurement teams at synthetic filament processors, and maintenance directors at rope and cable manufacturers. Secondary validation drew from MIIT GB standards documentation, SEC filings of listed textile machinery producers, and Jiangsu and Zhejiang provincial industrial output statistics. Bottom-up equipment installation tracking and top-down regional textile capacity analysis were triangulated to construct market estimates.
Segment-level outputs across the projection horizon reflect modeled splits by automation tier, end-use application, control technology architecture, and distribution channel structure. CAGRs were derived from regression analysis against textile capacity expansion rates, regulatory mandate implementation timelines, and energy efficiency retrofit penetration curves. Synthetic filament processing intensity in the Yangtze River Delta and labor cost trajectories in South Asian textile belts served as primary demand-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt rare earth export restrictions or accelerated EU carbon border adjustment enforcement. Projections reflect assumptions on regulatory implementation pace and equipment replacement cycle compression. Rare earth supply shocks, mechatronics technician training pipeline failures, and EU digital product passport rule acceleration warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Europe Tempered Glass Cutting Machine Market
Industrial Equipment
Bellows Vacuum Suction Cup Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Spot Curing System Market
Industrial Equipment
Global Integrated Drive Systems Market
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Camera Tripods Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Global Strain Wave Gearing Devices Market
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Global Pneumatic Actuators Market