
 North America Nanofiber Market | 2026-2036
North America Nanofiber Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nanofiber Market Analytics
A shortage of electrospinning process engineers is redrawing competitive boundaries across the North America Nanofiber Market. 3M Company leverages its deep polymer science heritage to sustain filtration product leadership in industrial air handling. DuPont anchors high-performance nanofiber development through in-house polymerization and membrane integration capabilities. Donaldson Company, Inc. dominates aftermarket filter channels with extensive distribution networks serving engine and industrial OEMs.
North America nanofibers are synthetic or naturally derived fibers with diameters below 100 nanometers, typically produced through electrospinning, phase separation, or template synthesis to achieve extreme surface-area-to-volume ratios and tunable pore structures. These properties enable selective barrier functions, controlled release kinetics, and enhanced mechanical performance in filtration media, medical devices, and energy components. Electrospun nanofibers occupy the largest production volume share due to mature equipment supply chains and broad material compatibility across thermoplastic and bioresorbable polymers. Energy storage applications are expanding fastest as solid-state battery developers adopt nanofiber separators to improve ionic conductivity and thermal stability. Composite nanofibers command premium positioning where multi-layer functionality justifies higher processing complexity in aerospace and defense procurement.
FDA 510(k) clearance requirements for nanofiber-based wound dressings and EPA National Ambient Air Quality Standards for fine particulate filtration are shaping product development roadmaps and capital allocation decisions. The U.S. Occupational Safety and Health Administration maintains exposure limits for synthetic nanomaterials that influence manufacturing site selection and worker protection investments. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California and New York that could reshape end-of-life obligations for nanofiber-containing products.
Market Dynamics
Electrospinning equipment scarcity is compressing production capacity expansion timelines across the North America Nanofiber Market, forcing manufacturers to prioritize high-margin medical and defense contracts over commoditized filtration volumes.
Growth Catalysts
- EPA National Ambient Air Quality Standards:Tightening fine particulate limits in the United States mandate higher-efficiency filtration media in industrial air handling and automotive applications.
- Solid-state battery separator adoption:Energy storage developers in the U.S. Great Lakes corridor are integrating nanofiber membranes to improve ionic conductivity and thermal runaway resistance.
- FDA 510(k) pathway maturation:Streamlined material clearance for nanofiber wound dressings accelerates commercialization timelines for medical device startups in Minnesota and Massachusetts.
Market Restraints
- Specialized polymer feedstock concentration:High-purity fluoropolymers and bioresorbable polyesters rely on limited domestic suppliers, exposing processors to price volatility and allocation constraints.
- Electrospinning throughput ceilings:Batch processing limitations restrict scalable manufacturing for high-volume automotive filtration contracts competing against meltblown alternatives.
- OSHA synthetic nanomaterial exposure limits:Worker protection investments and facility ventilation upgrades add capital intensity to greenfield site selection in California and New York.
Strategic Opportunities
- Canadian filtration infrastructure renewal:Provincial mining and oil sands operators in Alberta are retrofitting dust collection systems, creating demand for nanofiber cartridge replacements.
- Multi-modal drug delivery platforms:Convergence of electrospun scaffolds with bioprinting enables localized therapeutic release for orthopedic and ophthalmic applications.
- Extended producer responsibility frameworks:California and New York state-level mandates for end-of-life product accountability favor nanofiber designs with documented recyclability pathways.
Industry Challenges
- Electrospinning process engineer deficit:Universities produce fewer than fifty specialized graduates annually across the United States and Canada, constraining R&D velocity and scale-up execution.
- FDA biocompatibility validation timelines:Implantable nanofiber devices face eighteen-to-thirty-six-month clearance cycles that compress early-mover advantage windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nanofiber Market |
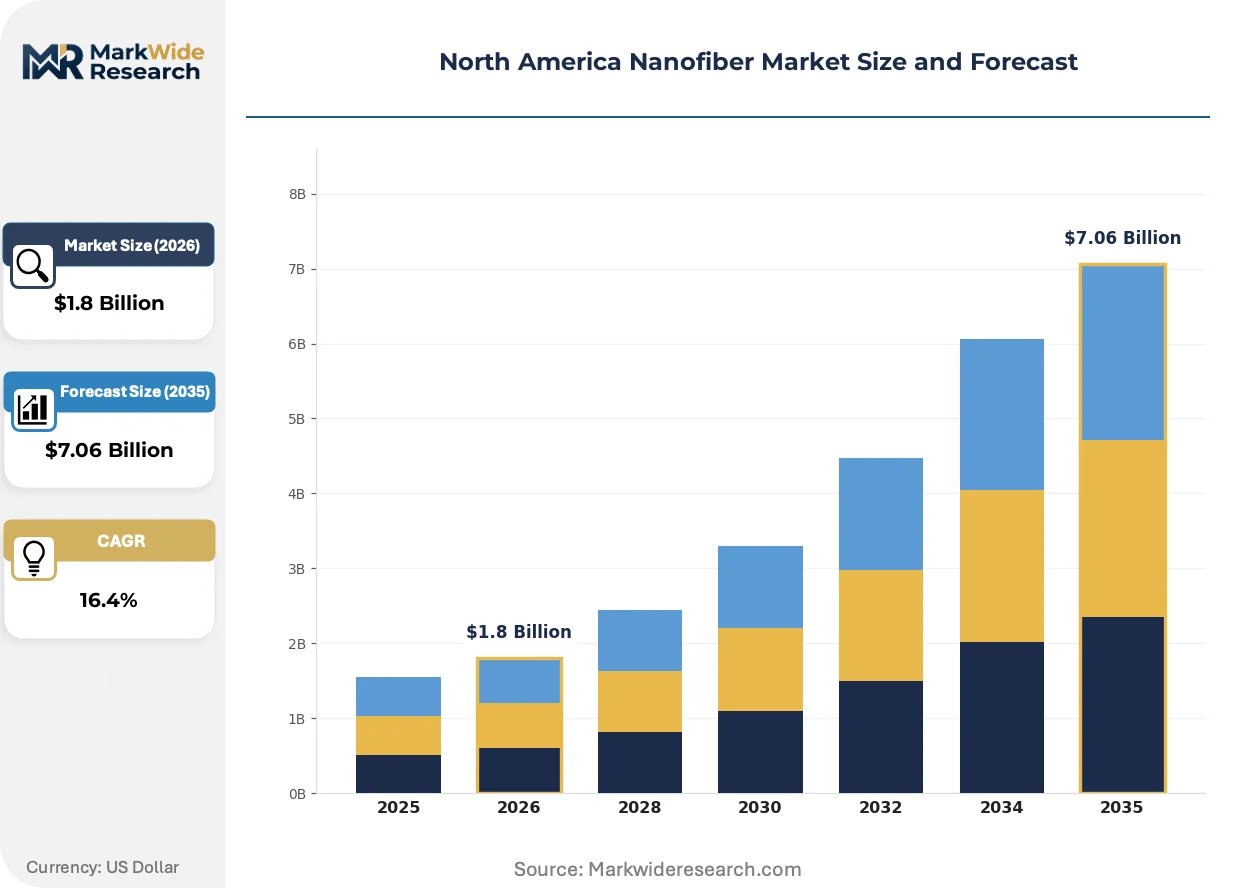
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrospun Nanofibers, Composite Nanofibers, Nanofibrous Membranes, Biodegradable Nanofibers End User: Textiles, Healthcare, Filter Manufacturing, Packaging Application: Drug Delivery, Air Filtration, Wound Care, Energy Storage Technology: Electrospinning, Phase Separation, Template Synthesis, Solvent Casting |
| Companies Covered | Mitsubishi Chemical Corporation, 3M Company, eSpin Technologies, Ahlstrom, DuPont, Hollingsworth & Vose, Donaldson Company, Inc., Asahi Kasei Corporation, TORAY INDUSTRIES, INC., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nanofiber Market Evolving Landscape
Production technology divergence is fragmenting competitive positioning between precision medical specialists and high-throughput industrial processors. Three developments are restructuring investment priorities across the value chain.
Core-shell electrospinning is bifurcating the medical nanofiber segment. This architecture embeds active pharmaceutical ingredients within protective polymer sheaths for controlled release kinetics. Wound care manufacturers in Massachusetts and Minnesota are adopting the technology to differentiate against commodity hydrogel dressings. The capability gap is compressing margins for single-material electrospun products while rewarding multi-layer formulation expertise.
REACH-aligned substance restrictions in the European Union are creating compliance spillover effects for North American exporters. ECHA candidate list updates on persistent organic pollutants now influence polymer selection decisions in U.S. filtration plants serving multinational automotive OEMs. Minnesota-based membrane producers are reformulating fluoropolymer blends to maintain EU market access without duplicating domestic product lines.
Consolidated procurement by integrated healthcare networks is displacing fragmented distributor relationships. IDN supply chain directors in Texas and Florida now mandate nanofiber wound dressing suppliers deliver vendor-managed inventory with consumption-based replenishment. This behavioral shift favors processors with ERP integration capabilities and penalizes smaller manufacturers dependent on independent medical-surgical distributors.
North America Nanofiber Market Segmentation
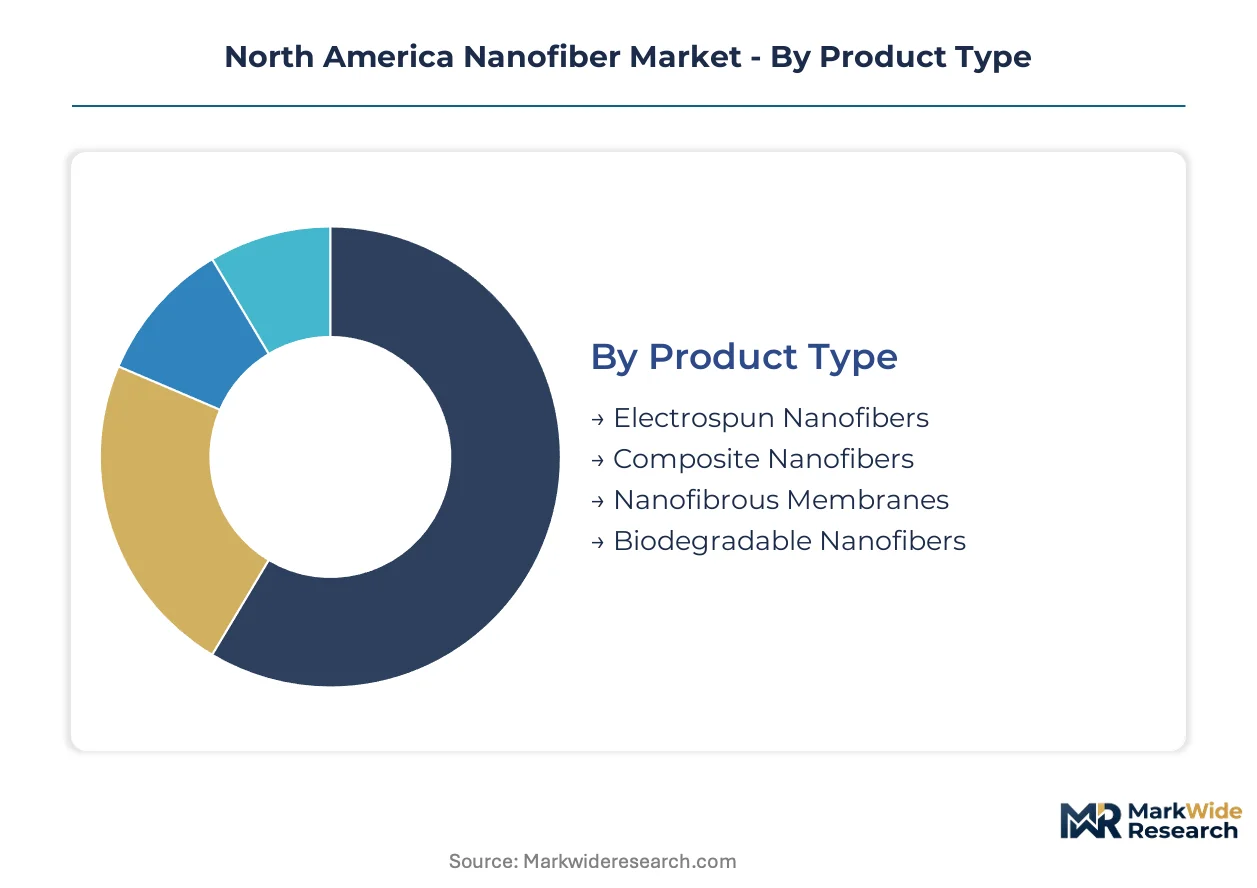
Segmentation in the North America Nanofiber Market reveals how distinct technical specifications map to discrete procurement channels. Medical device OEMs, industrial filtration contractors, and automotive battery developers each source through specialized distributor networks with divergent certification requirements.
Product Type:
Channel concentration varies sharply across product categories, with medical-grade materials flowing through FDA-authorized distributors while industrial volumes move via direct mill relationships.
- Electrospun Nanofibers:Produced through high-voltage polymer jetting to achieve diameters below 100 nanometers with exceptional surface-area-to-volume ratios. Demand concentrates in Minnesota and Massachusetts medical device clusters where wound care manufacturers require FDA 510(k)-compliant supply chains with batch-level traceability. Electrospinning equipment scarcity limits qualified supplier pools, compressing margins for commoditized grades while premium medical variants command sustained pricing power.
- Composite Nanofibers:Multi-layer architectures combining distinct polymer phases for simultaneous mechanical strength and functional performance. Aerospace and defense procurement in Texas and California drives specification intensity, with prime contractors mandating AS9100-certified production lines and documented fiber-matrix interface characterization. The segment rewards processors with in-house polymerization capabilities that eliminate feedstock variability.
- Nanofibrous Membranes:Self-supporting sheet structures with tunable pore distributions for selective barrier applications.
- Biodegradable Nanofibers:Bioresorbable polyesters and natural polymers engineered for temporary implant functions.
By volume, Electrospun Nanofibers leads. By growth pace, Composite Nanofibers is gaining share fastest.
End User:
Cost tier stratification separates commodity textile applications from premium healthcare procurement, with filtration occupying the intermediate value band.
- Healthcare:Implantable devices, wound dressings, and drug delivery platforms requiring FDA material master files and ISO 10993 biocompatibility testing. Massachusetts and Minnesota device manufacturers concentrate demand for electrospun scaffolds with validated degradation profiles, with procurement committees prioritizing suppliers offering vendor-managed inventory and consignment stocking.
- Filter Manufacturing:Industrial air handling, automotive cabin air, and HVAC applications governed by EPA National Ambient Air Quality Standards. The U.S. Great Lakes corridor hosts dense clusters of pleated media converters serving engine OEMs and commercial building operators, with Donaldson and Parker Hannifin maintaining captive nanofiber coating capacity for aftermarket distribution.
- Textiles:Functional apparel and protective clothing integrating nanofiber layers for moisture management or chemical resistance.
- Packaging:Active and intelligent barrier films for food and pharmaceutical shelf-life extension.
Healthcare commands the highest unit margins. Filter Manufacturing generates the largest absolute volume.
Application:
Application maturity spans from established air filtration deployments to emerging solid-state battery separator qualification programs.
- Air Filtration:High-efficiency particulate arresting media for industrial dust collection, commercial HVAC, and automotive cabin systems. Alberta mining operators and U.S. Great Lakes automotive plants drive replacement demand, with EPA fine particulate standards tightening efficiency specifications and accelerating nanofiber substitution for meltblown alternatives in critical environments.
- Wound Care:Advanced dressings leveraging nanofiber scaffolds for exudate management and moist healing environments. IDN supply chain consolidation in Texas and Florida is displacing independent distributor relationships, with hospital procurement directors mandating ERP-integrated suppliers capable of consumption-based replenishment and compliance documentation.
- Drug Delivery:Localized therapeutic release through core-shell fiber architectures or electrospun depot formulations.
- Energy Storage:Separator membranes for lithium-ion and solid-state batteries requiring thermal runaway resistance and optimized ionic conductivity.
Air Filtration maintains installed base dominance. Energy Storage exhibits the steepest expansion trajectory.
Technology:
Technology selection determines throughput scalability, material compatibility, and capital intensity, with electrospinning occupying the volume leadership position despite batch processing constraints.
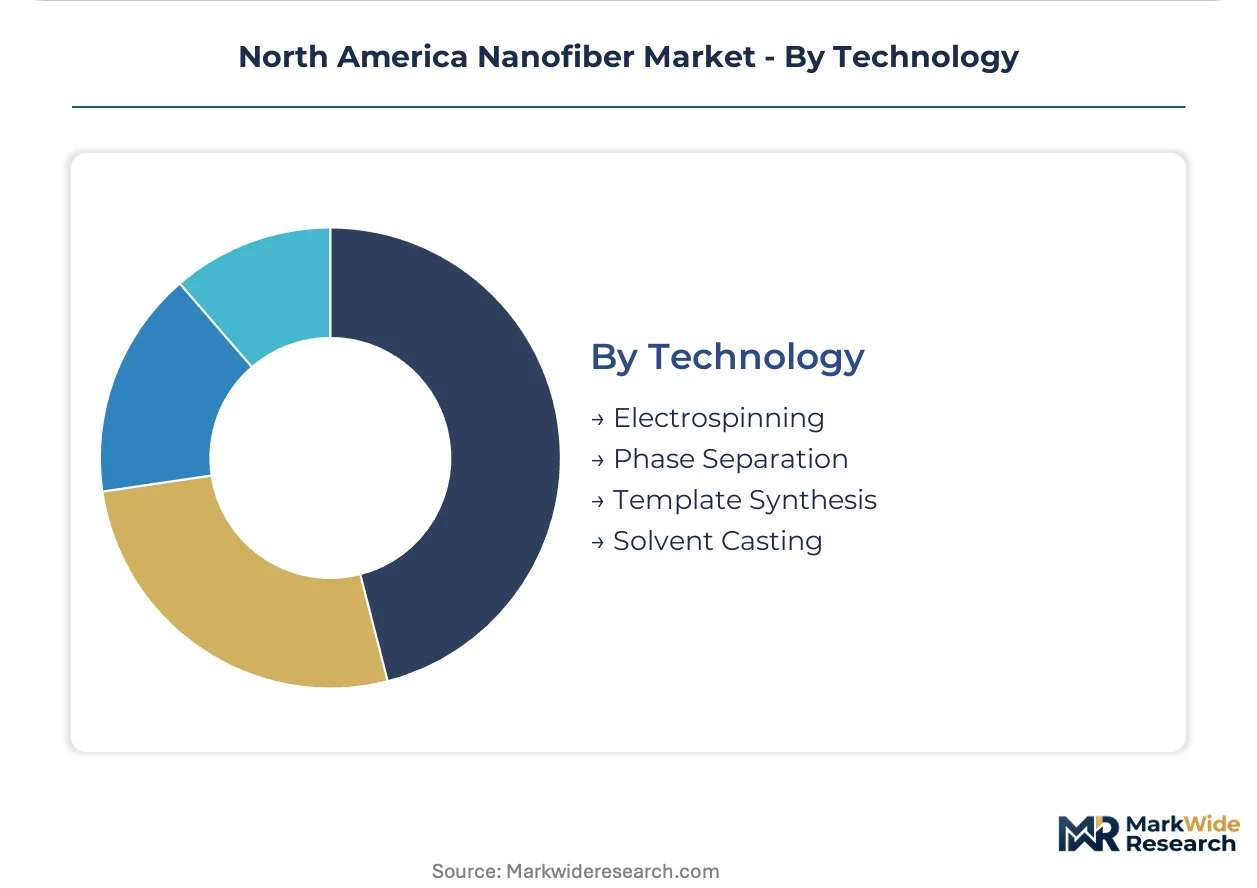
- Electrospinning:Mature high-voltage fiber formation with broad polymer compatibility spanning fluoropolymers, polyurethanes, and bioresorbable polyesters. The technology anchors North American production infrastructure, though throughput ceilings below meltblown alternatives restrict penetration in high-volume automotive contracts where cost-per-square-meter dominates procurement criteria.
- Phase Separation:Thermally induced polymer demixing for porous fiber structures without electrical equipment requirements.
- Template Synthesis:Hard or soft templating for precise diameter control in specialty optical and sensing applications.
- Solvent Casting:Solution-based film formation with subsequent mechanical drawing to achieve nanoscale features.
Electrospinning leads by installed capacity. Phase Separation offers the most direct path to throughput expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America. The United States dominates medical-grade nanofiber procurement through FDA-cleared supply chains, while Canada concentrates demand in industrial filtration for resource extraction, and Mexico emerges as a nearshoring location for electrospinning equipment assembly serving U.S. medical device OEMs.
United States
The U.S. absorbs the majority of North American nanofiber volume through dual filtration and healthcare procurement channels. EPA National Ambient Air Quality Standards for fine particulate matter mandate efficiency upgrades across industrial air handling systems in manufacturing belts. Minnesota and Massachusetts host dense medical device clusters where wound care manufacturers require FDA 510(k)-compliant electrospun scaffolds with validated degradation profiles.
Canada
Canadian demand concentrates in Alberta mining operations and oil sands processing facilities retrofitting dust collection infrastructure. Provincial environmental regulations in Alberta and British Columbia tighten particulate emissions standards for extractive industries. Toronto and Montreal anchor polymer research capabilities that feed cross-border supply relationships with U.S. Great Lakes filtration manufacturers.
Mexico
Mexico functions as a manufacturing assembly node for electrospinning equipment components destined for U.S. medical device markets. Federal environmental regulations under SEMARNAT align with U.S. OSHA exposure limits for synthetic nanomaterials, facilitating integrated North American production networks. Baja California and Chihuahua host maquiladora operations supplying precision polymer processing hardware to Minnesota and Massachusetts device clusters.
North America Nanofiber Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America Nanofiber Market. DuPont and 3M Company leverage captive polymerization and membrane integration capabilities to defend filtration product leadership, while mid-scale processors compete on FDA clearance velocity and niche application expertise. The competitive terrain separates into three archetypes: diversified materials conglomerates with backward integration into polymer feedstocks, electrospinning specialists with equipment-agnostic formulation platforms, and membrane converters with captive coating capacity for aftermarket distribution. Dominant competitive moves include strategic partnerships for solid-state battery separator qualification and selective capacity expansion in FDA-registered medical device corridors.
Among diversified materials conglomerates, DuPont and 3M Company exemplify the integrated-leader archetype through in-house control over fluoropolymer supply chains and membrane lamination technologies. Donaldson Company, Inc. occupies a distinct position within the membrane-converter tier, anchoring aftermarket filtration channels through extensive distribution networks serving engine and industrial OEMs. These three companies collectively represent the competitive poles around which mid-scale specialists and regional electrospinning processors organize their market positioning.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| 3M Company |
| eSpin Technologies |
| Ahlstrom |
| DuPont |
| Hollingsworth & Vose |
| Donaldson Company, Inc. |
| Asahi Kasei Corporation |
| TORAY INDUSTRIES, INC. |
| Others |
Value Network & Pricing Analysis
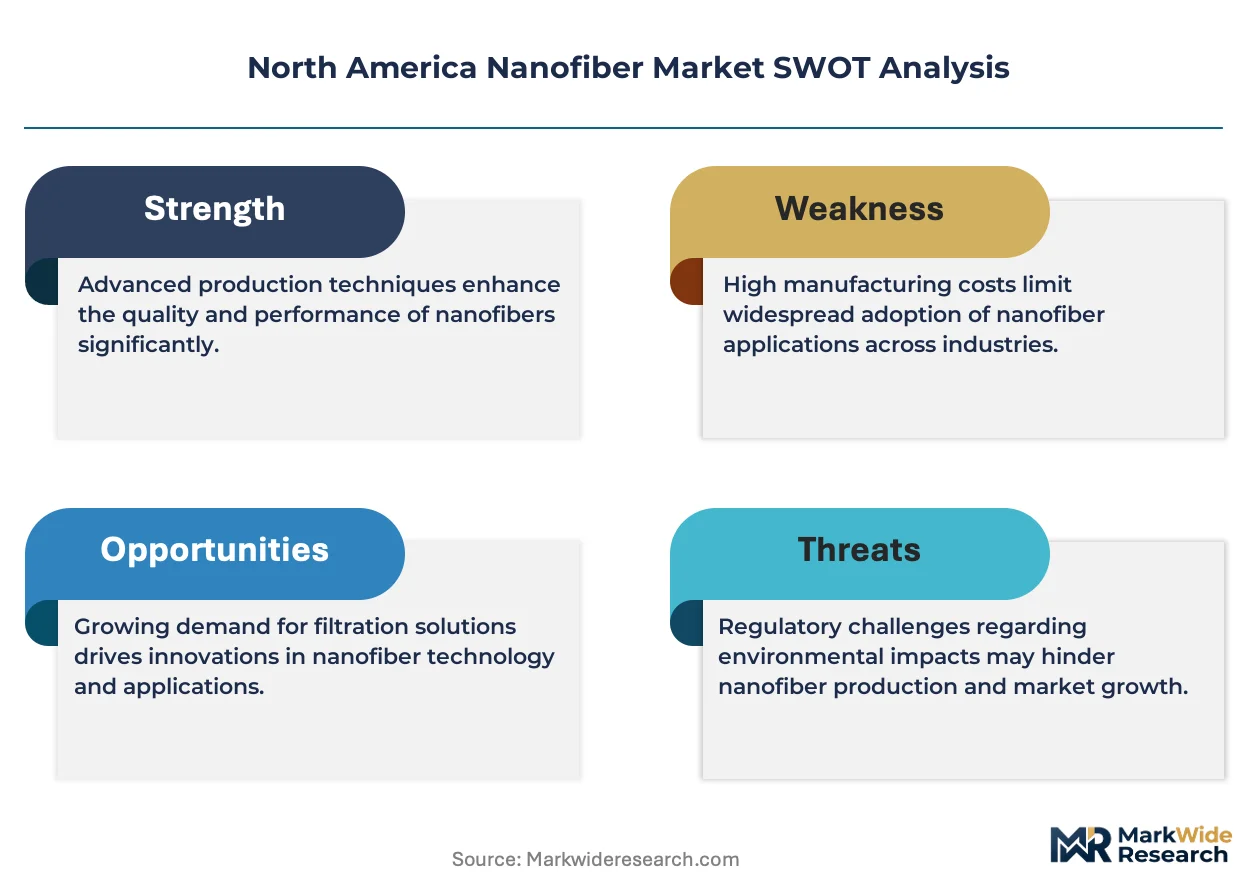
FDA 510(k) clearance requirements and EPA filtration efficiency certifications simultaneously gate supplier qualification and stratify price tiers across the North America Nanofiber Market, compressing margins for uncertified processors while rewarding validated manufacturers with sustained pricing power in medical and industrial procurement channels.
Pricing Analysis
Long-term offtake contracts dominate medical-grade nanofiber procurement, with Massachusetts and Minnesota device manufacturers locking multi-year supply agreements for FDA-cleared electrospun scaffolds. Price differentiation rests on ISO 10993 biocompatibility tier and batch-level traceability certification, with premium medical variants commanding substantial markups over industrial filtration grades. Cost compression in commodity filtration tiers is intensifying because meltblown alternatives compete aggressively on cost-per-square-meter, squeezing electrospun processors lacking differentiation. Filter Manufacturing buyers exhibit highest price sensitivity due to volume scale and specification standardization, while Healthcare procurement committees prioritize certification reliability over unit cost.
Supply Chain Analysis
Strategic stockpiling of high-purity fluoropolymers and bioresorbable polyesters characterizes inventory strategy among qualified nanofiber processors, buffering against allocation constraints from limited domestic feedstock suppliers. Supply concentrates in the United States, Canada, and Germany for specialized polymer feedstocks, with electrospinning equipment assembly increasingly anchored in Mexico's Baja California corridor. Raw material dependencies draw from fluoropolymer resin producers, medical-grade solvent suppliers, and precision voltage control hardware manufacturers. Single-source vulnerability in electrospinning process engineering talent constrains scale-up velocity across the value chain. Distribution runs through FDA-authorized distributors for medical grades and direct mill relationships for industrial filtration volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Nanofiber Market functions as a service-attach opportunity where vendor-managed inventory and consignment stocking arrangements expand faster than base material sales, particularly within consolidated healthcare network procurement.
For Market Incumbents: Compound defensive positioning by deepening backward integration into fluoropolymer feedstock production and expanding captive electrospinning capacity in FDA-registered Minnesota and Massachusetts corridors. Certification investment in AS9100 aerospace standards and EPA-compliant filtration efficiency tiers protects margin structure against emerging membrane converters with aftermarket distribution reach. Channel control through ERP-integrated vendor-managed inventory relationships with Texas and Florida IDN supply chain directors locks out smaller competitors dependent on independent medical-surgical distributors. For New Entrants and Emerging Players: Anchor in Alberta mining filtration retrofit demand and solid-state battery separator qualification programs as the most penetrable white-space targets. Canadian provincial dust collection infrastructure renewal offers lower competitive density than U.S. Great Lakes automotive contracts dominated by established membrane converters. A go-to-market angle emphasizing documented recyclability pathways aligns with California and New York extended producer responsibility frameworks, differentiating against legacy suppliers without end-of-life accountability. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-grade electrospinning capacity as FDA 510(k) clearance timelines and specialized equipment scarcity elevate barriers to organic scale-up. Long-term viability favors acquisition targets with validated polymer formulation platforms and existing FDA material master files rather than equipment-agnostic toll processors. The signal to watch is electrospinning process engineer hiring velocity at Minnesota and Massachusetts device clusters as a leading indicator of R&D pipeline conversion rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Feedstock | Captive supply of high-purity resins insulates DuPont and 3M from allocation volatility and price spikes. |
| FDA 510(k) Clearance Investment | Streamlined material master files accelerate commercialization timelines for Massachusetts wound care startups. |
| Vendor-Managed Inventory Partnerships | ERP-integrated replenishment contracts with Texas IDNs displace fragmented distributor relationships. |
| AS9100 Aerospace Certification | Prime contractor qualification unlocks Texas and California defense procurement for composite nanofiber processors. |
| Solid-State Battery Separator Qualification | U.S. Great Lakes energy storage developers adopt nanofiber membranes for thermal runaway resistance. |
Research Methodology
The analysis maps electrospun nanofibers, composite architectures, nanofibrous membranes, and biodegradable variants, each validated through primary interviews with electrospinning process engineers, FDA regulatory affairs specialists, hospital procurement committee members, and industrial filtration plant managers, combined with secondary triangulation against EPA National Ambient Air Quality Standard filings, FDA 510(k) clearance databases, OSHA synthetic nanomaterial exposure guidelines, and SEC 10-K disclosures from listed materials conglomerates, with bottom-up production capacity estimates cross-checked against top-down end-use demand aggregation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeled by product type, end user, application, and technology platform alongside geographic production cluster and certification tier. CAGRs were derived from fitted growth curves applied to base-year market sizing, with inputs including electrospinning equipment installation rates, EPA fine particulate standard compliance deadlines, and solid-state battery separator adoption curves from U.S. Great Lakes energy storage developers.
Material uncertainties — electrospinning throughput ceiling breakthroughs, FDA biocompatibility validation timeline compression, and state-level extended producer responsibility mandate acceleration — sit outside the modeled envelope, with forecasts reflecting assumptions about sustained polymer feedstock availability and specialized engineering talent pipeline constraints. Practitioners should keep alternative scenarios live as OSHA synthetic nanomaterial exposure limit revisions and REACH-aligned substance restriction spillovers evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Renewable Carbon Fibers Market
Fibers
Global Basalt Fiber Market
Fibers
Acoustical Fiber Board Market
Fibers
Vinylon Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Fiberglass Cloth Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
Asia-Pacific Nanofiber Market
Fibers
Fiberglass Resin Market
Fibers
Precision Fiber Molding Market
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market
Fibers
Polytetrahydrofuran Market
Fibers
North America Carbon Fiber Market
Fibers
Sisal Market
Fibers
Global Metal Fiber Market
Fibers
E-Glass Fiber Market