
 Gin Market | 2026-2036
Gin Market Size, Share, and Industry Trends Forecast 2026-2036
Gin Market Intelligence
Regulation (EU) 2019/787, which defines spirit drink categories, is realigning the cost-of-entry calculus for craft distillers across Europe. Diageo plc leverages its extensive distribution network to introduce artisanal brands alongside its established labels. Pernod Ricard SA competes by acquiring and scaling high-growth craft gin producers. William Grant & Sons Limited sustains its premium position through brand heritage and controlled production.
Gin is a distilled spirit deriving its predominant flavor from juniper berries, produced by redistilling a neutral agricultural spirit with botanicals to a minimum of 40% ABV. While the London Dry product type remains the traditional volume leader, New Western styles are expanding the market with innovative flavor profiles. Demand for citrus and floral gins is particularly high, driven by cocktail culture and seasonal marketing from distillers.
Standards of identity are governed by national and regional bodies, including the TTB in the United States and the EU's Spirit Drinks Regulation. These regulations dictate minimum alcohol content, permissible additives, and labeling terms like 'London Dry,' which directly influences market access. Producers must now decide whether to innovate within established geographical indications and product definitions or to create new categories entirely.
Market Dynamics
The central tension shaping the gin market is the divergence between distillers adhering to traditional, geographically protected standards like London Dry and those pursuing innovation through terroir-driven production using hyper-local botanicals, creating distinct market pathways.
Growth Catalysts
- Cocktail Culture Expansion:Demand from the on-trade sector, especially high-end cocktail bars in cities like London and New York, stimulates growth for premium gins with unique flavor profiles suited for creative mixology.
- Regulatory Modernization:Revisions to spirit drink definitions, such as Regulation (EU) 2019/787, provide clearer legal frameworks for distillers to innovate, encouraging new product development within and outside of traditional categories.
- Small-Batch Distillation:Advances in smaller-scale distillation equipment lower the cost-of-entry for craft producers, enabling hyper-local and experimental gin production that caters to niche consumer tastes for unique provenance.
Market Restraints
- Botanical Supply Volatility:The price and availability of core botanicals, particularly high-quality juniper berries from specific European regions, are subject to climate-related harvest inconsistencies, creating input cost instability for distillers.
- Geographical Indication Rigidity:Strict EU and other regulations governing terms like 'London Dry Gin' can inhibit flavor innovation, forcing producers to choose between using a protected, high-value term and differentiating their product.
- Competition from Other Spirits:The rising popularity of premium vodkas, tequilas, and especially low- and no-alcohol spirit alternatives presents a significant substitution threat, competing for the same consumer occasions and shelf space.
Strategic Opportunities
- Asia-Pacific Market Entry:Countries like Japan and Australia display growing interest in craft gin, offering opportunities for distillers to introduce Western styles or create new products utilizing local botanicals such as yuzu or lemon myrtle.
- Gin in Ready-to-Drink (RTD) Formats:Developing premium, canned gin-based cocktails addresses consumer demand for convenience without sacrificing quality, opening a significant channel beyond traditional on-trade service and home cocktail mixing.
- Direct-to-Consumer (DTC) Sales:E-commerce platforms and distillery-led clubs allow producers to bypass traditional distribution systems in markets like the US, enabling direct brand engagement and higher profit margins.
Industry Challenges
- Navigating Multi-Market Labeling:Adhering to disparate labeling requirements from bodies like the TTB in the United States and EU regulators for alcohol content, allergens, and origin claims creates significant administrative overhead for exporters.
- Distribution Network Access:Small craft distillers face substantial barriers in securing placement within consolidated distribution networks, which are often controlled by large beverage alcohol wholesalers, limiting their market reach.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gin Market |
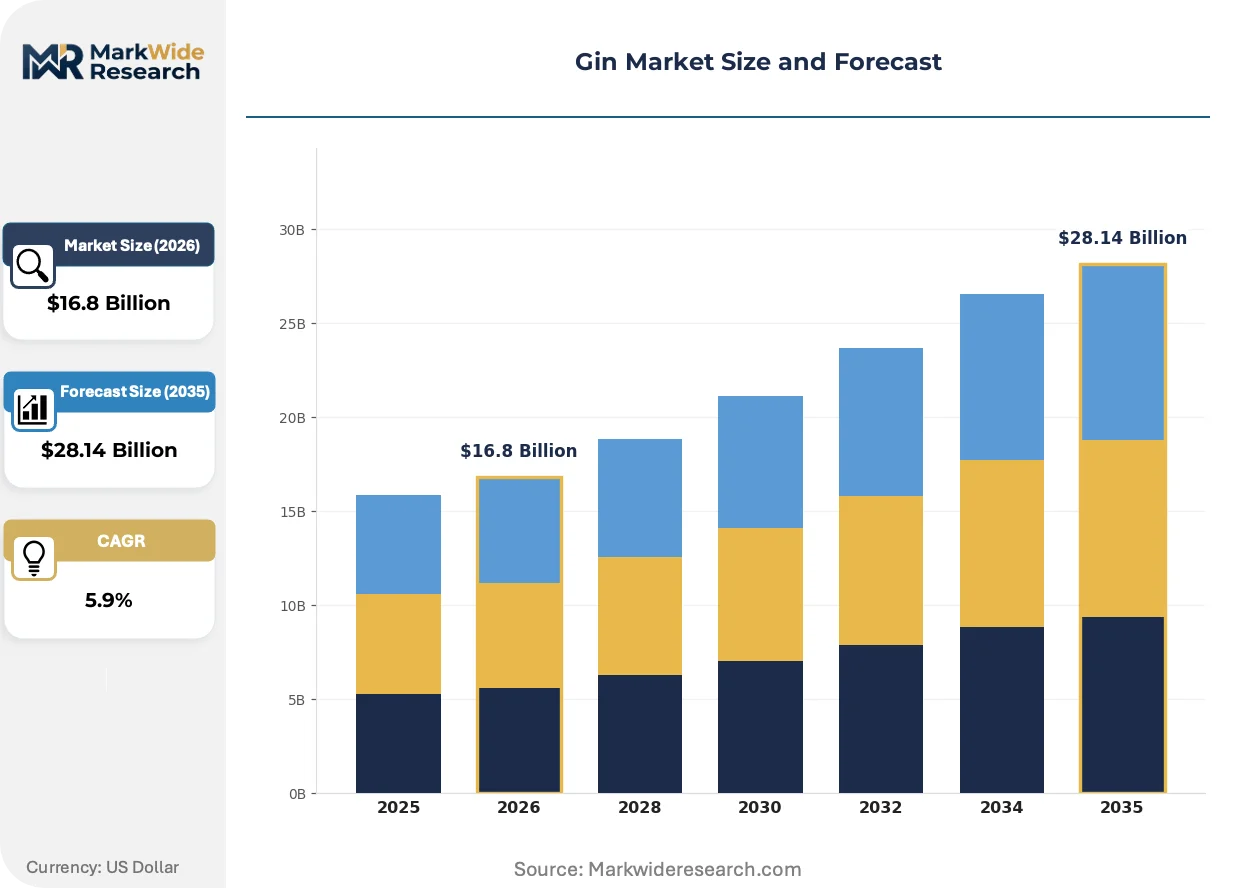
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $28.14 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: London Dry, Plymouth, Old Tom, Genever, New Western Flavor Profile: Citrus, Floral, Spiced, Herbal, Fruity, Woody Distribution Channel: On-Trade, Off-Trade, E-Commerce, Duty-Free, Direct-to-Consumer Customer Type: Bars, Restaurants, Retail Chains, Specialty Stores, Event Organizers |
| Companies Covered | William Grant & Sons Limited, Suntory Holdings Limited, Diageo plc, Ginebra San Miguel S.A., Sazerac Company Inc, Pernod Ricard SA, Davide Campari-Milano N.V., Lucas Bols N.V., Bacardi Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gin Market Strategic Shifts & Innovations
The gin market's evolution is defined by a fragmentation of flavor and origin. This shift moves production focus from standardized industrial styles toward hyper-local expressions of terroir, botanical diversity, and innovative distillation methods that challenge traditional definitions.
Botanical Terroir and Local Sourcing
A prominent trend is the emphasis on provenance, with distillers crafting gins that reflect a specific geographical identity. This involves sourcing botanicals from a distillery's immediate surroundings to create a unique sense of place, or 'terroir', in the final spirit. This hyper-local approach directly counters the placeless nature of mass-market gins and appeals to consumers seeking authenticity and a connection to the product's origin. The movement is particularly strong in the UK, Australia, and the United States.
Vacuum Distillation for Flavor Preservation
Vacuum distillation, also known as cold distillation, allows for the extraction of delicate flavors from botanicals at lower temperatures, preserving their fresh and vibrant character. Craft and premium distillers are increasingly adopting this technique to create distinctive citrus and floral gins that are difficult to produce with traditional pot stills. This technology is decentralizing flavor creation away from heat-based methods, enabling a wider spectrum of aromatic profiles.
Rise of Savory and Umami Profiles
Moving beyond the dominant floral and citrus notes, a new wave of gin features savory, earthy, and umami flavors. Distillers are experimenting with unconventional botanicals like mushrooms, seaweed, olives, and various herbs to create spirits intended for culinary pairings and savory cocktails like the Martini. This trend is expanding gin's role from a pre-dinner aperitif to a spirit that can be paired throughout a meal, particularly visible in gastronomically focused markets like Spain.
Gin Market Segmentation
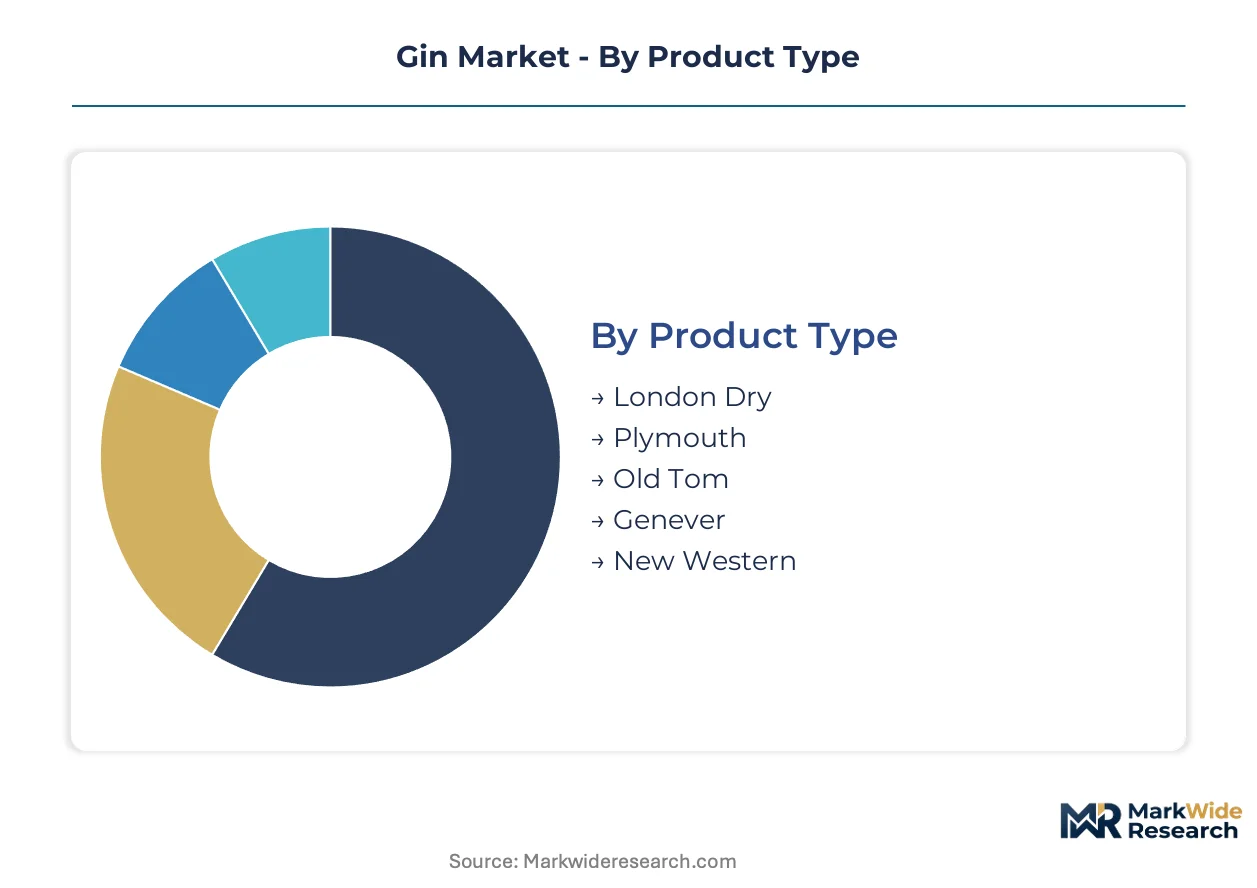
The gin market's segmentation reflects the spirit's diverse production methods, evolving flavor trends, and varied consumer access points. Understanding these distinct categories provides distillers with strategic insights into product development, market positioning, and targeted distribution efforts.
Product Type:
The gin market classifies product types based on distillation methods and historical specifications, influencing both production costs and consumer expectations.
- London Dry:This category designates gin produced by redistilling a neutral agricultural spirit in traditional stills with all natural botanical flavorings added during distillation. It must have a minimum of 37.5% ABV and no added artificial ingredients or sweeteners post-distillation. Demand remains strong in established European markets like the UK and Spain, driven by its classic profile for cocktails.
- Plymouth:A geographically protected gin style, Plymouth gin must be distilled specifically in Plymouth, England, using a single pot still process. It features a slightly sweeter and earthier profile than London Dry, appealing to consumers seeking historical authenticity and a softer juniper character.
- Old Tom:This gin style represents a sweeter variant, typically achieved through the addition of sugar or licorice post-distillation, bridging the gap between historical Genever and modern London Dry. Its resurgence caters to classic cocktail enthusiasts and mixologists exploring historical recipes.
- Genever:The Dutch precursor to gin, Genever is a malt wine-based spirit distilled with juniper and other botanicals, offering a richer, often savory profile. This traditional spirit maintains a niche following in its native Netherlands and among connoisseurs globally.
- New Western:This style emphasizes botanical innovation beyond juniper, allowing other flavors to come to the forefront while still maintaining a juniper presence. Often produced using small-batch distillation, these gins cater to cocktail culture expansion in urban centers like New York, seeking unique flavor profiles for mixology.
London Dry leads on scale; New Western leads on momentum.
Flavor Profile:
Consumer preferences for gin are increasingly segmented by the dominant aromatic notes and intended application, driving innovation in botanical selection.
- Citrus:These gins feature prominent notes of lemon, orange, grapefruit, or lime, often achieved through vacuum distillation to preserve delicate fruit essences. High demand from the on-trade sector for refreshing cocktail bases drives this segment, particularly in warmer climates and during seasonal marketing campaigns.
- Floral:Characterized by botanicals like rose, lavender, or elderflower, these gins offer fragrant and delicate profiles. This segment appeals to consumers seeking lighter, aromatic spirits for sophisticated cocktails and seasonal promotions in European markets.
- Spiced:Gins in this category incorporate warming botanicals such as cardamom, cinnamon, or black pepper, delivering complex and often robust flavor experiences. These are favored in colder months or for specific cocktail recipes that benefit from a spicy kick.
- Herbal:Featuring botanicals like rosemary, thyme, or basil, herbal gins provide earthy, often savory undertones, appealing to those seeking more complex and less traditional flavor profiles. This profile is gaining traction in gastronomy-focused regions like Spain.
- Fruity:Incorporating berries, stone fruits, or tropical fruits, fruity gins offer a sweet and often vibrant taste, expanding gin's appeal to a broader consumer base. This segment often targets new gin drinkers and those seeking sweeter cocktail options.
- Woody:Gins with woody notes, often derived from botanicals like cedar, sandalwood, or aged barrels, provide deep, resonant flavors. This niche profile appeals to connoisseurs looking for spirits with complexity and a unique mouthfeel.
Citrus gins demonstrate widespread appeal; savory and umami profiles are capturing emerging consumer interest.
Distribution Channel:
The pathways for gin to reach consumers vary significantly, reflecting different purchasing behaviors and market access strategies across geographies.
- On-Trade:This channel encompasses sales through bars, restaurants, hotels, and nightclubs, where premium and craft gins thrive due to their suitability for cocktails. Demand from high-end establishments in major cities significantly influences brand visibility and consumer perception.
- Off-Trade:Sales occur through retail outlets such as supermarkets, liquor stores, and convenience stores, representing the largest volume channel for mass-market and mid-tier gins. This channel relies on strong brand recognition and competitive pricing to attract consumers for at-home consumption.
- E-Commerce:Online platforms and distillery-led clubs facilitate direct sales to consumers, bypassing traditional distribution networks. This channel offers distillers higher margins and direct engagement, particularly for craft producers targeting niche markets in the US and UK.
- Duty-Free:This channel serves international travelers at airports and ports, offering premium and travel-exclusive gin expressions. It provides a platform for brand exposure to a global audience and often features unique packaging or limited editions.
- Direct-to-Consumer:Distilleries sell directly to consumers via their own websites, physical cellar doors, or exclusive clubs, fostering brand loyalty and providing unique experiences. This model is particularly effective for small-batch and artisanal producers seeking to control their brand narrative.
On-Trade remains a volume driver; E-Commerce is expanding rapidly through direct consumer engagement.
Customer Type:
The diverse consumer base for gin is categorized by the primary purchasing entity and its operational scale, each presenting unique demands and opportunities.
- Bars:High-volume cocktail bars and specialist gin establishments are crucial for trend-setting and premium brand adoption, especially in urban centers. These venues stimulate demand for unique flavor profiles and artisanal products suited for creative mixology.
- Restaurants:Fine dining and casual eateries purchase gin for cocktail programs and as an accompaniment to culinary experiences, often seeking gins with specific botanical profiles for food pairing. The focus here is on quality and consistency for a discerning clientele.
- Retail Chains:These large-scale outlets, including supermarkets and liquor stores, represent significant volume sales for both established and emerging gin brands. Strategic shelf placement and promotional activities within these chains drive mass-market consumption across Europe.
- Specialty Stores:Independent liquor stores and dedicated gin shops cater to connoisseurs and enthusiasts, stocking a wide range of craft, rare, and premium gins. These stores provide expert advice and foster a community around unique spirit offerings.
- Event Organizers:Companies managing festivals, concerts, and private functions procure gin in bulk for diverse consumer groups, often requiring versatile and widely recognized brands. This segment focuses on efficient supply and popular appeal for large-scale service.
Retail Chains account for substantial market volume; Specialty Stores cultivate brand loyalty among discerning consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of artisanal distillers and sophisticated mixology talent anchors gin market expansion across several key global regions. These regions demonstrate strong consumer demand for both traditional and innovative gin styles, supported by evolving regulatory frameworks and vibrant on-trade sectors.
United Kingdom
Strong consumer demand for premium and craft gins drives market growth, particularly in the on-trade sector. The UK's national food and beverage regulations ensure product quality and labeling standards for local distillers. London remains a global hub for cocktail culture, stimulating innovation in gin profiles and consumption trends.
Spain
Spain exhibits high per-capita gin intake, with a strong preference for herbal and savory profiles in gastronomy-focused settings. European Union Regulation 2019/787 influences spirit drink definitions and market access for Spanish producers. Major cities like Barcelona and Madrid are central to gin consumption, especially within the restaurant and bar scene.
Australia
Growing interest in craft gin and local botanicals fuels product development, catering to a discerning consumer base. Australia's national food standards body oversees labeling and ingredient declarations for alcoholic beverages. The vibrant craft distilling scene in cities such as Melbourne and Sydney drives innovation in New Western gin styles.
Japan
Premiumization and a growing appreciation for Western spirits drive demand for craft gin, often incorporating local botanicals like yuzu. The Ministry of Economy, Trade and Industry (METI) supports the development of local alcoholic beverage industries. Tokyo's sophisticated bar scene actively promotes unique gin expressions and cocktail pairings.
Germany
The German market shows consistent demand for both classic London Dry and emerging craft gins, driven by a mature spirits consumption culture. National alcohol regulations align with broader EU standards, impacting production and distribution. Urban centers like Berlin and Hamburg are experiencing a rise in specialist gin bars and artisanal distilleries.
Gin Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the gin market, creating a tiered competitive structure. The industry features global spirits powerhouses alongside numerous small-batch craft producers. Strategic archetypes include large-scale brand builders, niche artisanal innovators, and regional heritage brands. Dominant competitive moves involve portfolio diversification through acquisitions and extensive distribution network leverage.
Global spirits conglomerates such as Diageo plc and Pernod Ricard SA leverage extensive distribution networks to introduce artisanal brands alongside their established labels. William Grant & Sons Limited occupies a position as a premium heritage brand, sustaining its market presence through brand legacy and controlled production. These companies exemplify the blend of scale and targeted brand management defining the market.
| Leading Market Players |
|---|
| William Grant & Sons Limited |
| Suntory Holdings Limited |
| Diageo plc |
| Ginebra San Miguel S.A. |
| Sazerac Company Inc |
| Pernod Ricard SA |
| Davide Campari-Milano N.V. |
| Lucas Bols N.V. |
| Bacardi Limited |
| Others |
Cost & Logistics Intelligence
Small-batch distillation advancements simultaneously reshape cost economics and supply concentration across the gin market. These innovations enable craft producers to enter with lower capital outlays, fostering a fragmented supply landscape.
Pricing Analysis
Premium-mid-economy pricing differentiation defines the gin market, reflecting quality and brand heritage. Price differentiation stems from botanical sourcing, distillation method, and geographical indication. Pricing pressure in the mass-market segment arises from intense competition from other spirits and low-alcohol alternatives. On-trade buyers and connoisseurs exhibit lower price sensitivity, prioritizing unique flavor profiles and provenance.
Supply Chain Analysis
Regional distribution centers and consolidated wholesale networks manage the movement of finished gin products. Geographic supply draws from major producing regions like the UK, Spain, and the Netherlands. Raw material dependencies center on high-quality juniper berries and delicate botanicals such as citrus and elderflower. Supply chain risk includes botanical supply volatility from climate-related harvest inconsistencies. Distribution runs through established on-trade and off-trade channels, with e-commerce expanding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gin market represents a late-cycle quality story, with consumer demand increasingly shifting toward premium craft specifications. This emphasizes authenticity and unique flavor profiles over mass-produced volumes.
For Market Incumbents: To counter the threat of niche craft distillers and low-alcohol alternatives, established incumbents must diversify their portfolios through strategic acquisitions. Leveraging extensive distribution networks introduces artisanal brands alongside established labels, expanding market reach. Investment in sustainable botanical sourcing reduces input cost volatility, ensuring consistent product quality. Strengthening brand heritage through controlled production maintains premium positioning.
For New Entrants and Emerging Players: High-end cocktail bars serve as critical channel partners for new gin brands, offering visibility and consumer validation. Target underpenetrated Asia-Pacific markets with unique local botanical expressions, such as yuzu or lemon myrtle. A direct-to-consumer sales model fosters brand loyalty and higher profit margins, bypassing traditional distribution gatekeepers. Focusing on vacuum distillation techniques can create distinctive flavor profiles.
For Investors and Strategic Acquirers: Valuations sit cheapest among smaller craft distillers demonstrating strong regional identity and unique botanical sourcing. Long-term viability hinges on brands that effectively balance traditional gin standards with innovative flavor creation for global appeal. Acquisition targets should possess robust direct-to-consumer capabilities and intellectual property in novel distillation methods. The signal to watch is sustained growth in premium craft gin sales within emerging markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Acquiring high-growth craft gin producers expands market share and caters to evolving consumer tastes. |
| Direct-to-Consumer Expansion | Building e-commerce platforms enhances brand engagement and secures higher profit margins for distillers. |
| Asia-Pacific Market Entry | Introducing Western styles or local botanical gins taps into significant new consumer bases like Japan. |
| Sustainable Botanical Sourcing | Securing resilient supply chains for juniper and other botanicals mitigates climate-related input risks. |
| Innovation in Distillation Techniques | Adopting methods like vacuum distillation enables unique flavor profiles, differentiating products in a crowded market. |
Research Approach
Bottom-up on-trade and off-trade consumption modeling reconciled against top-down distiller production volumes forms the analytical core of this study. Primary interviews with distillers, bar owners, retail buyers, and botanical suppliers provided qualitative insights. Secondary validation drew from EU Spirit Drinks Regulation documents, TTB guidelines, industry association reports, and specialized trade publications. This triangulation ensures robust data integrity and comprehensive market understanding.
Historical trendline analysis established foundational growth patterns across the modeling period for the gin market. The quantitative framework segmented the market by product type, flavor profile, distribution channel, and customer type. Compound annual growth rates were derived from a blend of historical performance, market drivers, and expert projections. Key forecast inputs include consumer spending on premium spirits and the expansion of global cocktail culture.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory changes, climate impact on botanicals, and shifts in consumer preferences. The forecast reflects documented assumptions about market dynamics and innovation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
Still Wine Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Pub Cellar Equipment Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
Rum Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
US Wine Cooler Market
Alcoholic Beverages
South Korea Tequila Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Mezcal Market