
 Power by the Hour (PBH) Market | 2026-2036
Power by the Hour (PBH) Market Size, Share, and Industry Trends Forecast 2026-2036
Power by the Hour (PBH) Market Analysis
Consolidation among low-cost carriers and regional airline alliances is realigning how engine maintenance contracts get negotiated and awarded. GE Aviation leverages its digital thread capabilities to lock in long-term PBH agreements with fleet operators. Rolls-Royce plc anchors its market position through TotalCare contracts that bundle predictive maintenance with spare parts logistics. Pratt & Whitney competes on narrowbody engine programs where hourly cost guarantees attract budget-conscious airlines.
Power by the Hour denotes a contractual framework where equipment owners pay fixed rates per operating hour for maintenance, repair, and overhaul coverage rather than bearing variable costs directly. These agreements typically specify minimum utilization thresholds, escalation clauses tied to flight cycles, and guaranteed turnaround times for shop visits. The service type dimension spans maintenance, repair, overhaul, and support functions, with overhaul work commanding the deepest technical expertise and highest margin pools. Within offerings, full-service contracts dominate among flag carriers seeking balance-sheet predictability, while modular services gain traction with hybrid operators cherry-picking specific workscopes. Technology segments reveal predictive maintenance and data analytics as the fastest-expanding categories, as sensor-enabled engines generate real-time performance telemetry that reshapes risk pricing.
The FAA mandates continuous airworthiness management under Part 121 and Part 135 operations, compelling operators to document every maintenance event through certified channels. EASA's Part-M and Part-145 frameworks impose equivalent rigor across European-registered fleets, creating regulatory moats around approved PBH providers. The EU AI Act introduces emerging compliance obligations for automated diagnostic systems that recommend maintenance interventions. Stakeholders must monitor how aviation authorities integrate algorithmic transparency requirements into existing airworthiness protocols.
Market Dynamics
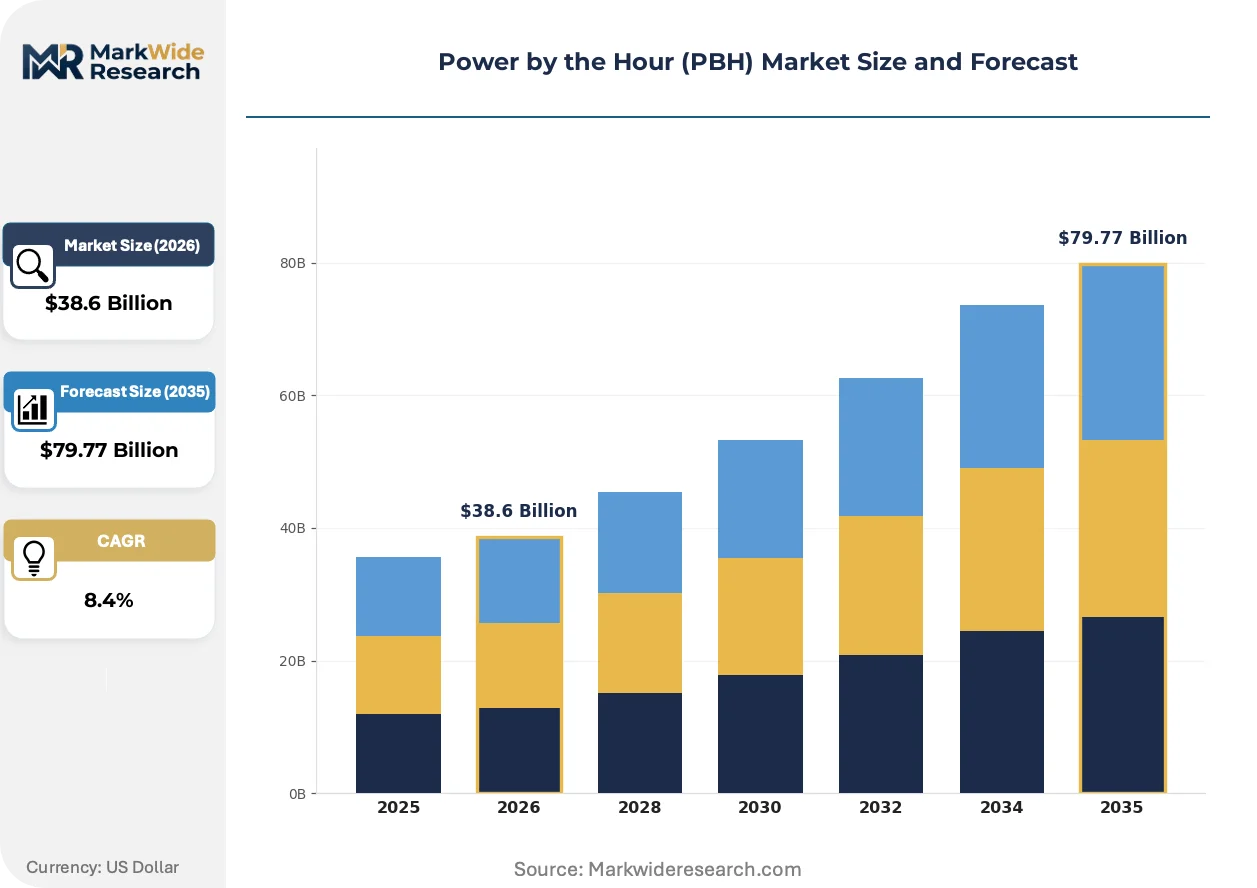
The Power by the Hour market is undergoing a fundamental restructuring as commercial airlines abandon asset-heavy balance sheets in favor of operational expenditure models, with digital predictive maintenance systems now determining contract pricing and risk allocation between operators and service providers.
Growth Catalysts
- FAA Part 121 Mandates:Continuous airworthiness documentation requirements compel US carriers toward certified PBH providers with established compliance infrastructure.
- Sensor Telemetry Proliferation:Real-time engine performance data streams enable usage-based risk pricing that aligns maintenance costs with actual flight hours.
- Asia-Pacific Fleet Expansion:Low-cost carriers in India and Southeast Asia drive contract volumes as they prioritize capital flexibility over engine ownership.
Market Restraints
- Spare Parts Supply Concentration:OEM-controlled inventories in the United States and United Kingdom create bottlenecks during surge demand periods.
- Specialized Technician Scarcity:Narrowbody and widebody engine certification requirements limit qualified labor pools in emerging aviation markets.
- EU AI Act Compliance Burden:Automated diagnostic systems face emerging transparency obligations that extend certification timelines for predictive maintenance algorithms.
Strategic Opportunities
- Indian Aviation Liberalization:The country's PLI scheme for aircraft maintenance infrastructure attracts PBH providers seeking greenfield MRO partnerships.
- Blockchain-Enabled Parts Provenance:Distributed ledger technology converges with IoT tracking to create auditable maintenance histories that reduce fraud exposure.
- Sustainable Aviation Fuel Mandates:EASA and FAA pathways for SAF integration create retrofit service contracts tied to engine modification programs.
Industry Challenges
- Legacy Fleet Data Integration:Older engine platforms lack native sensor suites, forcing expensive hardware retrofits to enable predictive maintenance coverage.
- Multi-OEM Contract Complexity:Airlines operating mixed fleets face fragmented PBH negotiations across GE, Rolls-Royce, and Pratt & Whitney service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power by the Hour (PBH) Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Overhaul, Support Offering: Full Service, Modular Service, Customized Solution, Standard Package End User: Aerospace, Automotive, Marine, Industrial Equipment Technology: IoT, Predictive Maintenance, Data Analytics, Cloud Computing |
| Companies Covered | GE Aviation, Rolls-Royce plc, MTU Aero Engines AG, Lufthansa Technik, Pratt & Whitney, AFI KLM E&M, AAR, Textron Inc., Honeywell Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power by the Hour (PBH) Market Emerging Trajectories
Digital thread architectures and regulatory data mandates are converging to transform how engine maintenance risk gets priced, transferred, and executed across commercial aviation networks.
Digital twin technology is rewriting contract structures in the PBH ecosystem. These virtual engine replicas simulate component degradation across flight cycles, enabling carriers to negotiate hour-by-hour pricing rather than block-rate agreements. Full-service contract adopters leverage twin outputs to compress shop visit forecasting errors. The technology is compressing traditional maintenance planning horizons from quarterly to weekly cycles.
REACH chemical compliance and the EU AI Act are tightening documentation requirements for automated maintenance recommendations. European-registered fleets must now maintain algorithmic audit trails for any diagnostic system influencing airworthiness decisions. MRO providers are responding by embedding compliance checkpoints directly into predictive analytics workflows before recommendations reach flight operations teams.
Airline procurement teams are unbundling traditional full-service PBH agreements into modular workscope packages. Hybrid operators now cherry-pick line maintenance, heavy overhaul, and logistics support from competing providers rather than accepting bundled offerings. This pattern is most visible among low-cost carriers in the United States and India seeking granular cost transparency across engine lifecycle stages.
Power by the Hour (PBH) Market Segmentation
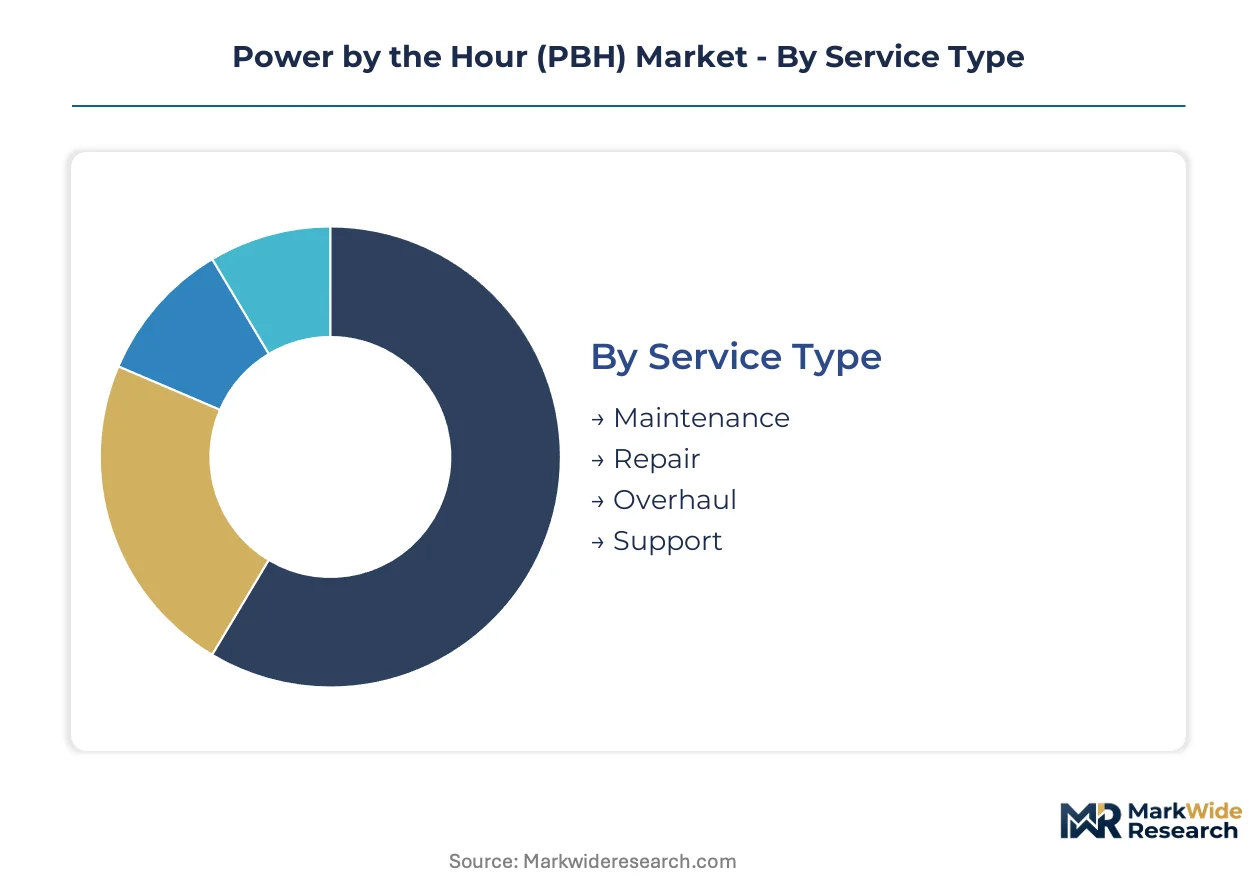
PBH contract structures fragment across four dimensions that determine risk allocation, pricing models, and vendor selection criteria. Each segmentation axis reveals distinct competitive dynamics between OEM-controlled service networks and independent MRO providers.
Service Type:
Supply concentration in OEM spare parts inventories shapes how airlines procure each service tier, with heavy overhaul work gravitating toward manufacturer-authorized facilities.
- Maintenance:Routine inspections and component replacements performed at line stations between flight cycles. US-based low-cost carriers concentrate demand here as they minimize ground time and prioritize quick-turn capabilities at hub airports.
- Repair:Corrective interventions addressing unscheduled component failures or damage events. European flag carriers drive contract volumes under EASA Part-145 requirements that mandate certified repair station networks with documented traceability.
- Overhaul:Complete engine disassembly, inspection, and reassembly to restore airworthiness margins.
- Support:Logistics, technical documentation, and engineering advisory functions.
Today's leader: Maintenance. Tomorrow's challenger: Overhaul.
Offering:
Cost tier differentiation separates premium full-service contracts from stripped-down modular alternatives, with hybrid operators fragmenting demand across multiple vendors.
- Full Service:Comprehensive coverage bundling all maintenance, repair, and logistics functions under fixed hourly rates. US legacy carriers dominate adoption, seeking balance-sheet predictability and risk transfer to OEM service arms.
- Modular Service:Unbundled workscope packages allowing operators to cherry-pick specific functions. Indian low-cost carriers concentrate demand here, mixing line maintenance from independents with heavy overhaul from OEM networks.
- Customized Solution:Tailored contracts negotiated for unique fleet configurations or operational profiles.
- Standard Package:Pre-defined service tiers with limited flexibility and competitive pricing.
Today's anchor: Full Service. Tomorrow's disruptor: Modular Service.
End User:
Application-specific regulatory requirements and asset utilization patterns reshape contract terms across vertical markets, with aerospace commanding premium pricing and technical complexity.
- Aerospace:Commercial aviation, business jets, and military platforms requiring continuous airworthiness certification. FAA Part 121 and EASA Part-M frameworks drive demand toward approved PBH providers with established compliance infrastructure.
- Automotive:Fleet vehicle maintenance programs and powertrain service contracts. German commercial vehicle operators concentrate adoption where uptime guarantees outweigh capital ownership economics.
- Marine:Ship propulsion systems and auxiliary equipment operating under IMO environmental standards.
- Industrial Equipment:Heavy machinery, power generation assets, and manufacturing systems.
Today's volume center: Aerospace. Tomorrow's expansion frontier: Automotive.
Technology:
Margin structures diverge sharply between commoditized connectivity infrastructure and proprietary analytics platforms that command pricing premiums through predictive accuracy.
- IoT:Sensor networks and connectivity hardware enabling real-time equipment monitoring. US and European OEMs control supply through proprietary data protocols that lock operators into exclusive service networks.
- Predictive Maintenance:Algorithmic failure forecasting and remaining-useful-life estimation. EU AI Act compliance requirements are extending certification timelines for automated diagnostic systems, creating regulatory moats around established providers.
- Data Analytics:Performance benchmarking and operational optimization tools.
- Cloud Computing:Scalable infrastructure for data storage and distributed processing.
Today's differentiator: Predictive Maintenance. Tomorrow's infrastructure layer: Cloud Computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation maintenance engineers and certified airworthiness inspectors concentrate disproportionately in the United States, Germany, and the United Kingdom, anchoring PBH contract origination and technical oversight capacity.
United States
Major fleet operators including American Airlines and Delta Air Lines drive contract volumes through their hub-and-spoke maintenance networks. FAA Part 121 mandates compel continuous airworthiness documentation that pushes carriers toward certified PBH providers. Dallas-Fort Worth and Atlanta anchor concentrated MRO activity where GE Aviation and Pratt & Whitney maintain extensive service facilities.
United Kingdom
Rolls-Royce plc anchors engine manufacturing and service origination from its Derby headquarters, generating downstream PBH contract flows. EASA Part-145 frameworks impose certified repair station requirements that filter market access to approved providers. London Gatwick and East Midlands Airport clusters host specialized engine overhaul facilities serving European-registered fleets.
Germany
Lufthansa Technik and MTU Aero Engines AG concentrate technical expertise and spare parts logistics in Munich and Hamburg maintenance hubs. REACH chemical compliance and EU AI Act transparency obligations extend certification timelines for predictive maintenance algorithms. The country's dual vocational training system supplies qualified turbine technicians that independent MROs struggle to replicate.
India
IndiGo and SpiceJet prioritize capital flexibility over engine ownership, driving modular PBH adoption among low-cost carriers. The government's PLI scheme for aircraft maintenance infrastructure attracts greenfield MRO partnerships with foreign service providers. Hyderabad and Bengaluru emerging as aviation manufacturing clusters where domestic MRO capacity expansion reduces dependency on Singapore and Dubai transit hubs.
United Arab Emirates
Emirates and Etihad Airways operate superjumbo fleets that generate concentrated heavy overhaul demand. The country's civil aviation regulator mandates equivalent documentation rigor to EASA frameworks, creating regulatory alignment with European contract standards. Dubai South and Al Ain host dedicated engine service centers where OEM-controlled spare parts inventories minimize turnaround time variability.
Power by the Hour (PBH) Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that concentrates technical authority in original equipment manufacturers. The vendor base stratifies into three tiers: OEM-captive service arms controlling proprietary data protocols, airline-affiliated MRO divisions leveraging fleet proximity, and independent providers competing on turnaround speed. Strategic moves center on predictive maintenance algorithm development and geographic expansion into Indian and Southeast Asian aviation growth corridors.
Within the OEM-captive tier, GE Aviation, Rolls-Royce plc, and Pratt & Whitney exemplify divergent contract philosophies. GE Aviation represents the digital-first archetype through sensor-telemetry integration that reshapes risk pricing. Rolls-Royce plc anchors the full-service bundling model where TotalCare contracts transfer operational risk from airline balance sheets. Pratt & Whitney occupies the narrowbody specialization position where hourly cost guarantees attract capital-constrained operators. MTU Aero Engines AG and Lufthansa Technik sit within the independent MRO tier, competing on technical flexibility rather than exclusive parts access.
| Leading Market Players |
|---|
| GE Aviation |
| Rolls-Royce plc |
| MTU Aero Engines AG |
| Lufthansa Technik |
| Pratt & Whitney |
| AFI KLM E&M |
| AAR |
| Textron Inc. |
| Honeywell Aerospace |
| Others |
Supply Flow & Price Mechanics
Full-service contract premiums diverge sharply from modular service rates as risk transfer depth and OEM data exclusivity reshape both pricing floors and spare parts sourcing patterns. This bifurcation concentrates pricing power with GE Aviation, Rolls-Royce plc, and Pratt & Whitney in the United States and United Kingdom, where proprietary sensor telemetry locks operators into captive service networks.
Pricing Analysis
Capacity additions in India are reshaping price floors for line maintenance services as domestic MRO infrastructure expands under the PLI scheme. Pricing stratifies across premium full-service bundles, standard modular packages, and economy-tier spot repairs, with certification level under EASA Part-145 and FAA Part 121 frameworks commanding substantial premiums. Cost compression in modular services is intensifying because low-cost carriers unbundle workscopes to force vendor competition. Budget-conscious airlines in India and Southeast Asia exhibit highest price sensitivity, while US legacy carriers prioritize balance-sheet predictability over hourly rate minimization.
Supply Chain Analysis
India's PLI scheme for aircraft maintenance infrastructure is reshaping sourcing patterns by mandating domestic-content thresholds for foreign MRO partnerships. Spare parts supply concentrates in the United States, United Kingdom, and Germany, where OEM-controlled inventories of turbine blades, high-pressure compressor disks, and full authority digital engine control units create structural dependencies. Single-source vulnerability runs through proprietary data protocols that prevent third-party predictive analytics access. Distribution runs through hub-and-spoke logistics networks anchored at Dallas-Fort Worth, Derby, and Munich.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Power by the Hour market represents a late-cycle quality story as commercial airlines prioritize predictive maintenance accuracy over lowest-bid procurement, with EASA and FAA airworthiness mandates elevating certified provider premiums.
For Market Incumbents: Anchor predictive maintenance algorithm development against emerging independent MROs leveraging open-architecture data platforms. Deepen backward integration into sensor hardware production to preserve proprietary telemetry lock-in. Defend against modular service fragmentation by embedding EU AI Act compliance checkpoints directly into diagnostic workflows before recommendations reach airline operations teams. For New Entrants and Emerging Players: Begin with line maintenance contracts at Indian low-cost carriers where PLI scheme subsidies reduce facility establishment costs. Target hybrid operators seeking granular cost transparency across unbundled engine lifecycle stages. Pursue greenfield MRO partnerships in Hyderabad and Bengaluru aviation clusters as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where independent MROs lack proprietary data protocols to compete with OEM-captive service arms. Five-to-ten-year viability favors providers with established EASA Part-145 and FAA Part 121 certification infrastructure. Acquisition targets include mid-scale independents with turbine technician training pipelines. Watch for algorithmic transparency rulemaking from EASA as the inflection signal for predictive maintenance certification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Algorithm Development | Rolls-Royce TotalCare contracts leverage digital twin outputs to compress shop visit forecasting errors. |
| Domestic MRO Capacity Expansion | India's PLI scheme attracts GE Aviation partnerships that reduce carrier dependency on Singapore transit hubs. |
| EU AI Act Compliance Integration | EASA-mandated algorithmic audit trails extend certification timelines for automated diagnostic systems. |
| Modular Service Unbundling | IndiGo cherry-picks line maintenance from independents while sourcing heavy overhaul from OEM networks. |
| Blockchain-Enabled Parts Provenance | Distributed ledger convergence with IoT tracking creates auditable maintenance histories under FAA documentation mandates. |
Methodological Framework
Bottom-up fleet operator modeling reconciled against top-down OEM service contract tracking forms the analytical core of this study. Primary interviews with airline procurement directors, MRO facility managers, FAA airworthiness inspectors, and EASA certification engineers combined with secondary validation from FAA airworthiness directive filings, EASA Part-145 repair station databases, and customs trade data for engine component flows. Triangulation across these sources ensures supply-side capacity estimates align with demand-side contract origination patterns.
Input-output matrices map engine flight hour generation to maintenance event frequency across service type, offering, and technology segmentation dimensions throughout the forecast period. CAGRs derive from installed base expansion rates, fleet utilization assumptions, and contract penetration curves. Industry-specific forecast inputs include sensor telemetry adoption curves and EASA algorithmic transparency rulemaking timelines.
Several conditions sit outside the modeled scope, including military aviation maintenance programs, business jet fractional ownership structures, and emerging urban air mobility platforms. Forecasts reflect documented assumptions regarding fleet retirement schedules and sustainable aviation fuel retrofit pathways. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive & Transportation
Global V2X Market
Automotive & Transportation
Mountain Bike Suspension Market
Automotive & Transportation
Motorcycle Shock Absorbers Market
Automotive & Transportation
Europe Customs Brokerage Market
Automotive & Transportation
North America Automotive Parts Aluminum Die Casting Market
Automotive & Transportation
Global Green Vehicles Market
Automotive & Transportation
Japan Automotive Sunroof Market
Automotive & Transportation
Argentina Automotive Composites Market
Automotive & Transportation
Global SUV Market
Automotive & Transportation
Automotive Torsion Bar Market
Automotive & Transportation
Electric and Hybrid Vehicles Driveline Market
Automotive & Transportation
North America Passenger Vehicles Lubricants Market
Automotive & Transportation
Oman Used Car Market
Automotive & Transportation
Bike Fenders Market
Automotive & Transportation
South America Freight and Logistics Market
Automotive & Transportation
E-Cargo Bike Market