
 Lipstick Molding Machines Market | 2026-2036
Lipstick Molding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Lipstick Molding Machines Market Outlook
Contract manufacturers is reorganizing procurement priorities across the lipstick molding machine supply base as beauty brands outsource production to flexible third-party operators. Citus Kalix leverages its European engineering heritage to dominate precision servo-electric lines for high-SKU cosmetic brands. Shanghai GIENI Industry Co., Ltd. anchors the mid-market with integrated filling-and-molding systems engineered for China's export cosmetics sector. Coesia competes through its packaging machinery conglomerate structure, extending aftermarket service networks that lock in multi-year client contracts across Southern Europe.
Lipstick molding machines are precision thermoplastic forming systems that heat, inject, and cool wax-based cosmetic formulations into aluminum or plastic bullet shapes at cycle speeds typically ranging from 40 to 120 pieces per minute; their primary commercial purpose is to deliver dimensional repeatability and surface finish consistency required for premium cosmetic packaging. Automatic systems command the largest installed base due to labor cost pressures in high-volume cosmetic manufacturing, though semi-automatic units represent the fastest-growing configuration among startup cosmetic brands and small-batch clean-beauty formulators seeking flexible tooling changeovers. Injection molding technology leads equipment value flows given its compatibility with multi-cavity tooling and temperature-sensitive wax alloys, while compression molding retains stable demand in pharmaceutical-grade lipstick applications where cross-contamination protocols favor simpler mechanical architectures.
FDA cosmetic facility registration rules and EU REACH chemical safety standards jointly shape machine material specifications, compelling builders to certify all polymer-contact surfaces for heavy-metal exclusion and batch traceability. China's SAMR equipment safety codes and GB standards for food-contact machinery add compliance layers for exporters serving dual-use cosmetic and pharmaceutical clients. ISO 9001 quality management and CE marking remain baseline market access requirements, though emerging ESG disclosure mandates in Europe are beginning to influence buyer RFP scoring for energy consumption and scrap-rate metrics. Stakeholders must weigh regional certification roadmaps against modular upgrade paths when committing to five-to-seven-year machine lifecycles.
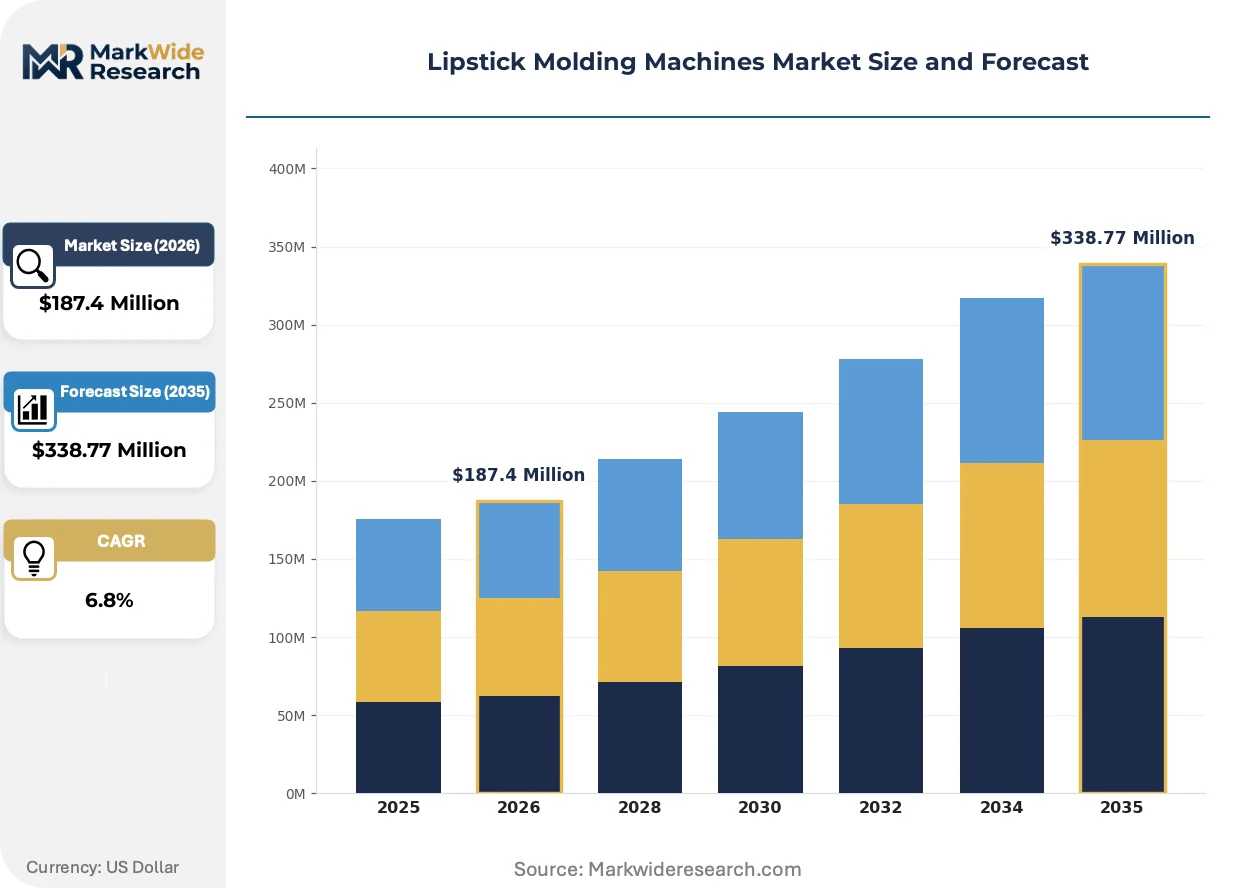
Market Dynamics
Contract manufacturers now drive procurement volumes faster than captive cosmetic brands, reordering supplier relationships and compressing equipment specification cycles across the lipstick molding machine supply base.
Growth Catalysts
- EU REACH chemical safety mandates:Heavy-metal exclusion protocols for polymer-contact surfaces are forcing equipment upgrades across European cosmetic manufacturing facilities.
- Clean-beauty formulators:Small-batch cosmetic startups require flexible tooling changeovers that semi-automatic configurations deliver.
- Yangtze River Delta clustering:Export-oriented cosmetic factories in China concentrate demand for integrated filling-and-molding systems.
Market Restraints
- Stainless-steel input costs:Servo-electric architectures compliant with RoHS specifications face raw material price volatility.
- Single-source servo drive suppliers:Precision motion control components concentrate in German and Japanese industrial automation vendors.
- Pharmaceutical-grade compression molding:Simpler mechanical architectures limit cycle speed improvements versus injection alternatives.
Strategic Opportunities
- India's PLI scheme for manufacturing:Cosmetics production incentives create virgin territory for mid-market equipment deployment.
- AI-enabled predictive maintenance:Machine learning convergence with servo-electric diagnostics opens aftermarket revenue streams.
- Saudi Arabia's SFDA cosmetic regulations:New halal certification requirements for beauty products drive equipment replacement cycles.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA facility registration, CE marking, and China's SAMR GB standard compliance extend go-to-market cycles.
- Legacy pneumatic system integration:Retrofitting older plants with servo-electric architectures demands specialized controls engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipstick Molding Machines Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Custom Application: Cosmetic Manufacturing, Personal Care, Pharmaceutical, Food Industry End User: Cosmetic Brands, Contract Manufacturers, Retail Chains, Startups Technology: Injection Molding, Compression Molding, Extrusion, Blow Molding |
| Companies Covered | Citus Kalix, Cosmatic Srl, Micmachinery.co.,Ltd, Eugeng International Company, Shanghai GIENI Industry Co., Ltd., Changzhou Mic Machinery Co., LTD, Coesia, Wenzhou Zhonghuan Packaging Machinery Company, Ri.Way Enterprise Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipstick Molding Machines Market Strategic Shifts
Servo-electric motion control architectures are displacing pneumatic systems across precision cosmetic manufacturing, while regulatory disclosure mandates and procurement model fragmentation reshape how buyers evaluate equipment lifecycles.
Servo-electric drive technology is fragmenting competitive positioning in high-speed lipstick molding. These systems replace compressed-air actuators with precision ball-screw and linear motor configurations, enabling closed-loop temperature control within 0.5°C variance. Mid-market contract manufacturers in Italy and South Korea are adopting retrofit kits at accelerated paces. The technology is fragmenting the historical dominance of integrated OEM systems, enabling component-level upgrades that extend legacy machine lifecycles.
EU CSRD sustainability disclosure rules are mandating energy consumption and scrap-rate reporting across cosmetic manufacturing equipment. Machine builders must now embed power metering and material tracking capabilities as standard features rather than premium options. Southern European packaging machinery suppliers face the steepest compliance curves, with Spanish and Portuguese contract manufacturers demanding certified ESG data streams for their own Scope 3 reporting obligations.
Beauty brands are unbundling after-sales service contracts from initial equipment purchases, treating maintenance and spare parts as separate procurement categories. This behavior compresses OEM margins on installation revenue while opening independent service provider channels. The shift is most visible among North American clean-beauty formulators with limited in-house engineering staff, who prefer outcome-based uptime guarantees over traditional warranty structures.
Lipstick Molding Machines Market Segmentation
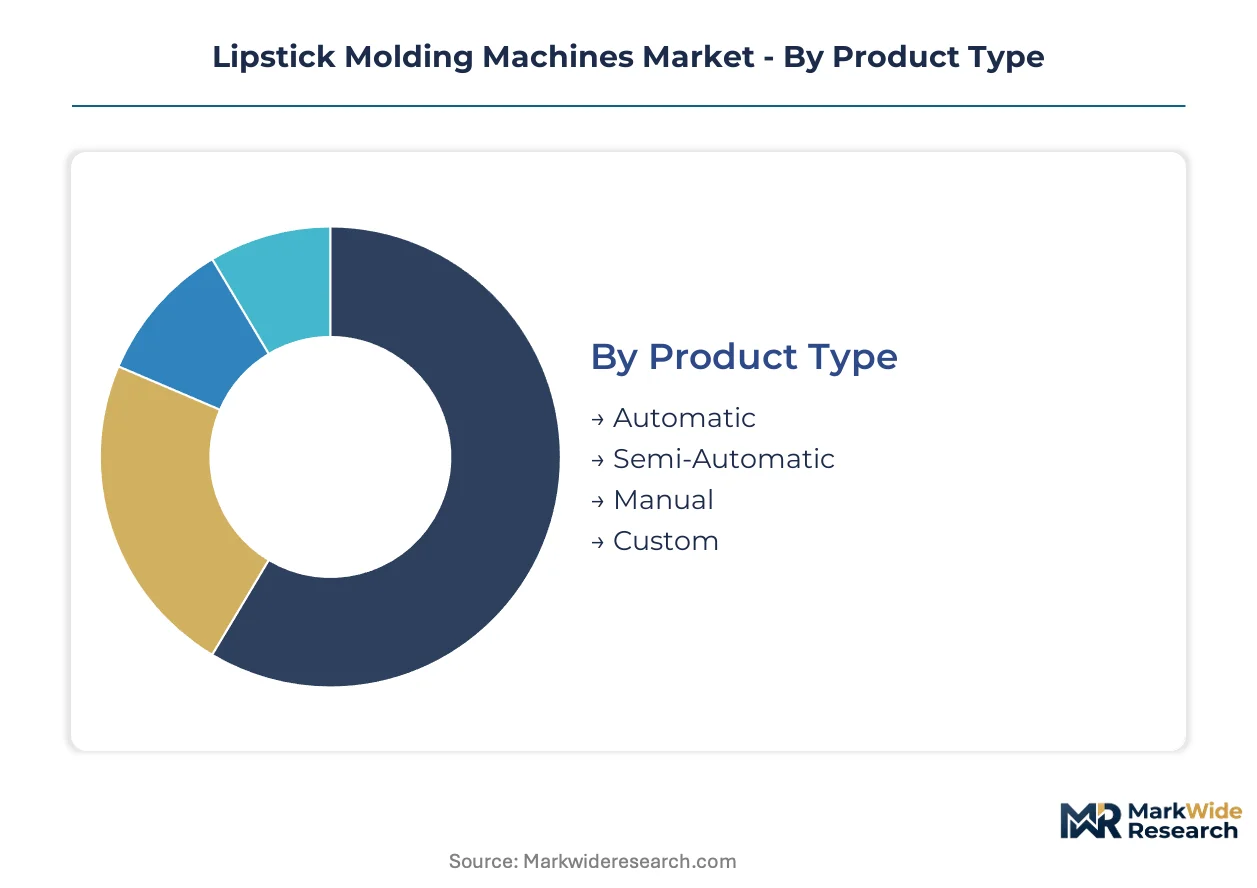
Channel mix varies sharply across lipstick molding machine segments. Automatic systems flow primarily through integrated OEM-direct relationships, while semi-automatic and manual configurations distribute through regional machinery dealers and used-equipment brokers serving budget-constrained buyers.
Product Type:
Channel concentration diverges by automation tier: automatic systems move through direct OEM sales forces and long-term lease arrangements, whereas semi-automatic and manual units distribute via machinery trading houses and regional equipment dealers.
- Automatic:These systems integrate servo-electric drives with multi-cavity tooling architectures, achieving cycle speeds of 80-120 pieces per minute through closed-loop thermal management. Demand concentrates among high-volume contract manufacturers in China's Yangtze River Delta, where labor cost pressures and export volume requirements justify capital-intensive procurement. REACH and RoHS compliance specifications in Europe further filter procurement toward certified automatic platforms with stainless-steel contact surfaces.
- Semi-Automatic:Hybrid architectures combine pneumatic actuation with manual loading stations, enabling tooling changeovers in under 15 minutes. Clean-beauty startups in North America and small-batch formulators across South Korea drive procurement, prioritizing flexibility over throughput. These buyers typically source through regional distributors offering bundled training and spare parts packages rather than direct OEM relationships.
- Manual:Simple mechanical presses with heated molds serve artisan cosmetic producers and vocational training facilities. Procurement flows through secondary equipment markets and used-machinery platforms.
- Custom:Engineered-to-order systems accommodate proprietary bullet geometries or pharmaceutical-grade containment requirements. Sales cycle through specialized application engineering teams.
Automatic systems dominate installed base. Semi-automatic configurations are climbing the fastest as contract manufacturers seek portfolio flexibility.
Application:
Margin profiles separate sharply across end-use applications, with pharmaceutical-grade installations commanding premium pricing against standard cosmetic manufacturing equipment.
- Cosmetic Manufacturing:High-volume production of color cosmetics for mass and prestige brands. Equipment specifications prioritize surface finish consistency and rapid color changeover. Demand clusters among export-oriented factories in China and contract manufacturers serving European luxury houses.
- Personal Care:Lip balm and therapeutic stick formulations with lower pigmentation requirements. FDA facility registration rules shape material specifications for US-bound production.
- Pharmaceutical:Medical-grade lip care and API delivery systems requiring validated batch documentation and cross-contamination protocols. Compression molding architectures retain preference here for simpler mechanical validation. EU MDR and US FDA cGMP standards drive equipment replacement cycles.
- Food Industry:Edible-grade decorative products and confectionery applications. China's GB food-contact machinery standards and EU EFSA compliance requirements constrain supplier qualification.
Cosmetic manufacturing commands revenue concentration. Pharmaceutical applications are where margin expansion concentrates.
End User:
Procurement authority is migrating from captive cosmetic brands toward third-party operators, restructuring how equipment vendors configure sales coverage and service networks.
- Cosmetic Brands:Multinational beauty houses with in-house manufacturing assets. Procurement emphasizes brand-differentiated bullet geometries and proprietary mold designs. These buyers source through centralized capital equipment committees with multi-year depreciation horizons.
- Contract Manufacturers:Third-party operators serving multiple beauty brands under white-label arrangements. Equipment specifications prioritize rapid format changeover and multi-SKU flexibility. These buyers now represent the dominant procurement volume, sourcing through competitive tender processes and demanding outcome-based service contracts.
- Retail Chains:Private-label cosmetic programs at drugstore and mass-market retailers. Procurement focuses on cost minimization and supply security.
- Startups:Clean-beauty and indie cosmetic brands with limited production scale. These buyers favor lease-to-own arrangements and refurbished semi-automatic equipment.
Contract manufacturers dominate order flow. Startups are gaining share fastest as venture-backed cosmetic brands proliferate.
Technology:
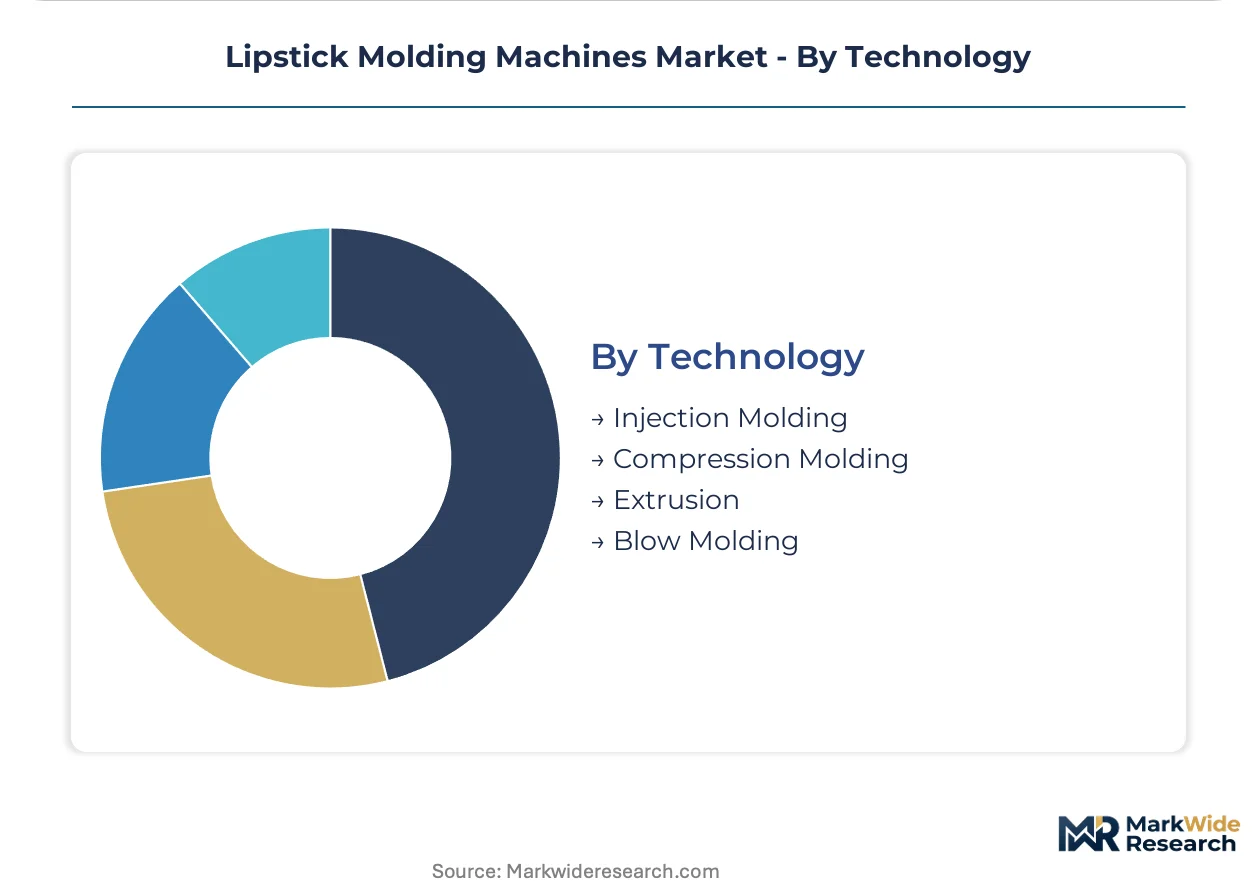
Technology selection locks in downstream operating economics, with injection molding enabling multi-cavity scaling that compression architectures cannot match.
- Injection Molding:Precision thermoplastic forming through heated barrel and screw mechanisms, compatible with complex multi-cavity tooling. Temperature-sensitive wax alloys and high-pigmentation formulations process reliably. European OEMs and Chinese system integrators lead equipment supply.
- Compression Molding:Direct mechanical pressing of pre-measured material charges. Simpler architectures suit pharmaceutical applications where validation documentation and mechanical reliability outweigh speed requirements.
- Extrusion:Continuous profile forming for stick-format products with uniform cross-sections. Limited penetration in shaped-bullet applications.
- Blow Molding:Hollow-form capability for specialized packaging integration. Niche deployment in novelty and promotional cosmetic formats.
Injection molding dominates value flows. Compression molding retains stable demand in regulated pharmaceutical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturers now concentrate procurement authority across four distinct national markets, each shaped by divergent regulatory compliance burdens and industrial cluster geometries. Equipment vendors must navigate FDA registration timelines in North America, REACH material mandates in Europe, and SAMR certification layers in China while serving fragmented demand from third-party operators.
China
Export-oriented cosmetic factories in the Yangtze River Delta drive automatic system procurement at 80-120 pieces per minute. SAMR equipment safety codes and GB standards for food-contact machinery impose dual compliance layers on machinery serving pharmaceutical-cosmetic clients. Domestic suppliers cluster in Shanghai and Jiangsu province, where integrated filling-and-molding systems dominate procurement for white-label production.
United States
Clean-beauty startups across California and New York favor semi-automatic configurations with sub-15-minute tooling changeovers. FDA cosmetic facility registration rules shape material specifications for polymer-contact surfaces in heavy-metal exclusion protocols. Contract manufacturers in the Northeast and Pacific Northwest unbundle after-sales service contracts from equipment purchases, compressing OEM installation margins.
Germany
Precision servo-electric lines command premium positioning among high-SKU cosmetic brands with proprietary bullet geometries. REACH chemical safety standards and RoHS specifications push builders toward stainless-steel architectures with certified batch traceability. Engineering-intensive suppliers concentrate in Baden-Württemberg and Bavaria, where multi-year client contracts lock in aftermarket service networks.
Italy
Mid-market contract manufacturers adopt servo-electric retrofit kits at accelerated paces, fragmenting historical integrated OEM dominance. EU CSRD sustainability disclosure rules mandate energy consumption and scrap-rate reporting capabilities as standard equipment features. Packaging machinery suppliers in Emilia-Romagna and Lombardy face steep compliance curves for certified ESG data streams.
South Korea
Small-batch formulators drive semi-automatic procurement through regional distributors offering bundled training packages. MFDS cosmetic safety regulations align equipment specifications with pharmaceutical-grade containment requirements. Machinery trading houses in Seoul and Gyeonggi-do province serve flexible production needs from venture-backed beauty brands.
Lipstick Molding Machines Market Competitive Environment
Player mix skews toward European precision engineering specialists and Chinese integrated system fabricators, creating a bifurcated structure with limited mid-market consolidation. The competitive terrain separates into three strategic archetypes: servo-electric precision OEMs serving luxury cosmetic houses, mid-market filling-and-molding integrators targeting export manufacturers, and packaging conglomerates extending aftermarket service networks. Dominant competitive moves include geographic expansion through regional distributor partnerships and technology licensing agreements for retrofit kit distribution.
Within the European engineering heritage tier, Citus Kalix represents precision servo-electric specialization for high-SKU brands, while Coesia S.p.A. exemplifies packaging machinery conglomerate structure with multi-year service contract lock-in. Shanghai GIENI Industry Co., Ltd. anchors the Chinese integrated system segment, occupying a position among Yangtze River Delta suppliers serving export-oriented cosmetic factories with combined filling-and-molding architectures.
| Leading Market Players |
|---|
| Citus Kalix |
| Cosmatic Srl |
| Micmachinery.co.,Ltd |
| Eugeng International Company |
| Shanghai GIENI Industry Co., Ltd. |
| Changzhou Mic Machinery Co., LTD |
| Coesia |
| Wenzhou Zhonghuan Packaging Machinery Company |
| Ri.Way Enterprise Company |
| Others |
Value Chain & Pricing Dynamics
Twelve-to-sixteen-week lead times for German servo drive components concentrate pricing power among integrated OEMs serving REACH-compliant European facilities, while contract manufacturers in China's Yangtze River Delta exploit shorter domestic sourcing loops to compress procurement costs. Inventory buffers of 45-60 days for stainless-steel contact surfaces amplify working capital requirements across servo-electric architectures, filtering buyer access toward capitalized operators.
Pricing Analysis
Servo-electric generation systems command 40-60% premiums over pneumatic legacy lines, with next-generation AI-enabled predictive maintenance modules layering additional cost tiers atop base configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling intensity. Pricing pressure stems from contract manufacturers unbundling service contracts and sourcing refurbished semi-automatic units through trading houses. Clean-beauty startups exhibit highest price sensitivity, while pharmaceutical-grade buyers prioritize validated batch documentation over unit economics.
Supply Chain Analysis
Germany and Japan anchor precision motion control component fabrication, with Taiwan and South Korea feeding specialized servo motor and linear encoder supply. Stainless-steel billet, high-grade aluminum for mold cavities, and temperature-resistant polymer seals constitute critical input dependencies. Single-source vulnerability concentrates in German ball-screw suppliers serving sub-0.5°C thermal variance specifications. Distribution runs through integrated OEM direct sales for automatic systems, while regional machinery dealers and used-equipment brokers handle semi-automatic and manual configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority migration from captive cosmetic brands toward third-party contract manufacturers concentrates buyer power, fragmenting historical OEM-customer relationships and compressing specification cycles across equipment categories.
For Market Incumbents: Secure multi-year aftermarket service contracts with outcome-based uptime guarantees to lock in revenue streams as contract manufacturers unbundle initial equipment purchases from maintenance procurement. Deepen backward integration into servo drive component supply through licensing agreements with Japanese automation vendors, mitigating single-source vulnerability exposure. Prioritize CE marking and REACH certification investment as baseline market access requirements stiffen across European procurement committees. For New Entrants and Emerging Players: CE marking fast-track programs for mid-market servo-electric retrofit kits open white-space penetration among Italian and South Korean contract manufacturers seeking legacy machine lifecycle extension. Target India's PLI scheme beneficiary factories with lease-to-own semi-automatic configurations, exploiting virgin territory absence of entrenched supplier relationships. Pursue outcome-based service contracting as primary go-to-market angle, differentiating from incumbent warranty structures through guaranteed uptime performance. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fragmented mid-market positioning among Yangtze River Delta integrators invites roll-up opportunity as export volume requirements scale. Acquisition target archetype: regional filling-and-molding system fabricators with established SAMR certification pathways and existing relationships with white-label cosmetic exporters. Watch contract manufacturer procurement volume share crossing threshold dominance as inflection signal for equipment specification standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Retrofit Kit Distribution | Extends legacy machine lifecycles for mid-market Italian contract manufacturers facing CSRD compliance deadlines. |
| REACH-Certified Stainless-Steel Architecture Investment | Locks in European market access as ECHA heavy-metal exclusion protocols tighten polymer-contact surface requirements. |
| AI-Enabled Predictive Maintenance Platform Launch | Opens recurring revenue streams through ML convergence with servo-electric diagnostic capabilities. |
| India PLI Scheme Geographic Expansion | Captures virgin territory demand as cosmetics production incentives attract contract manufacturing investment. |
| Outcome-Based Service Contract Unbundling | Aligns with North American clean-beauty formulator preference for uptime guarantees over traditional warranties. |
Study Parameters
The analysis maps automatic, semi-automatic, manual, and custom system sub-sectors, each validated through equipment procurement directors at contract manufacturers, plant engineers at captive cosmetic brand facilities, aftermarket service heads at packaging machinery conglomerates, and regulatory affairs leads navigating multi-jurisdiction certification timelines. Primary interview insights combined with secondary validation from SAMR equipment safety filings, ECHA REACH substance registrations, FDA cosmetic facility registration databases, and ISO 9001 certification records. Bottom-up unit shipment estimates triangulated against top-down value chain analysis across the projection horizon.
Consistency checks validated volume and value outputs against external benchmarks including customs/trade data for machinery imports, SEC filings from packaging equipment conglomerates, and regional industrial cluster production surveys. Segmentation dimensions modeled encompass automation tier, application category, end-user archetype, and technology type across the analysis window. CAGRs derived from fitted growth curves incorporating equipment replacement cycle timing, regulatory compliance deadline clustering, and contract manufacturer procurement volume trajectories. Industry-specific forecast inputs include servo-electric adoption rates and clean-beauty startup formation velocity.
Decision-makers should treat outputs as directional under assumptions of sustained contract manufacturer procurement dominance and stable REACH/RoHS regulatory frameworks; material deviation in buyer consolidation patterns or ESG disclosure mandate acceleration would warrant model refresh. Recalibration cycles align with material shifts in EU CSRD implementation timelines and India's PLI scheme beneficiary expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Bottle Blowing Machine Market
Packaging Machinery
Blind Box Machine Market
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Global Filling Machines Market
Packaging Machinery
Packaging Conveyors Market
Packaging Machinery
Beverage Can Seamers Market
Packaging Machinery
Capsule Filling Machines Market
Packaging Machinery
Hardgel Liquid Capsule Filling Machines Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Granule Filling Machine Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Vertical Bagging Machine Market
Packaging Machinery
Extrusion Press Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Deblistering Machines Market