
 Plastic Extrusion Equipment Market | 2026-2036
Plastic Extrusion Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Extrusion Equipment Market Insights
Packaging converters are rotating toward sheet and film extrusion lines as e-commerce cold-chain requirements tighten. Davis-Standard leverages its North American installed base to sustain aftermarket service revenue. KraussMaffei anchors European demand through integrated downstream systems for medical-grade films. JWELL competes aggressively on twin-screw configurations for Asia-Pacific polymer compounders.
Plastic extrusion equipment encompasses machines that melt, homogenize, and force thermoplastic polymers through a shaped die at pressures typically ranging from 1,000 to 5,000 psi, producing continuous profiles with uniform cross-sections for industrial fabrication. Twin-screw extruders command premium positioning where reactive processing and devolatilization determine output quality, while single-screw variants dominate high-volume pipe and profile applications where cost efficiency governs procurement. Film extrusion lines for flexible packaging absorb the fastest capacity additions, and PVC profile systems face margin compression from regulatory substitution pressures in construction end uses.
EU REACH restrictions on phthalate plasticizers and the EU Green Deal's recycled content mandates are compelling equipment retrofits across European polymer processors. FDA food-contact regulations and EPA emissions standards shape US equipment specifications for packaging and construction applications respectively. Stakeholders must monitor how polymer recycling targets in multiple jurisdictions will redirect R&D spending toward devolatilization and filtration subsystems.
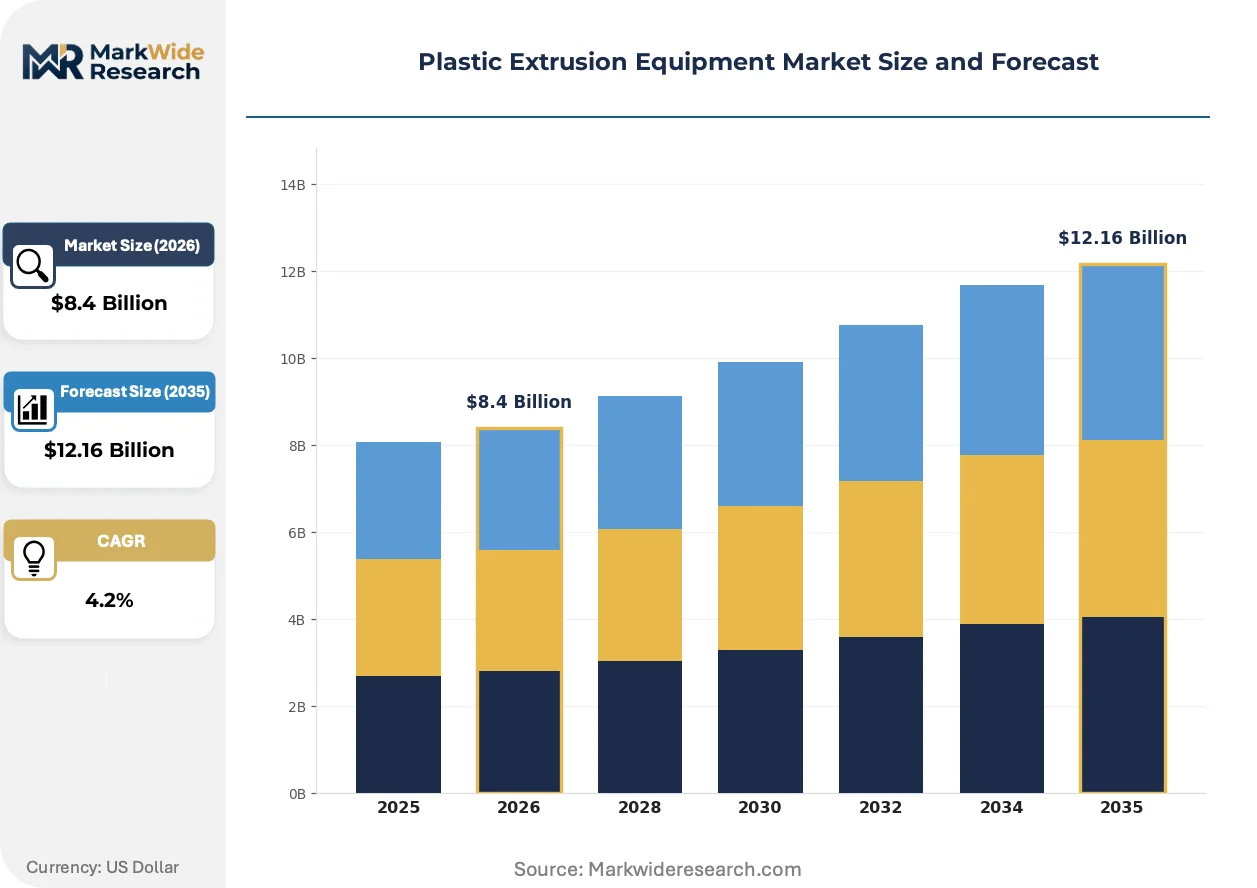
Market Dynamics
EU Green Deal mandates on recycled polymer content are forcing packaging converters toward co-extrusion retrofits, while machinery suppliers in Germany's Stuttgart-Munich belt absorb concentrated order flows for high-throughput film lines.
Growth Catalysts
- REACH recycled content mandates:EU processors must integrate post-consumer feedstocks, accelerating capital deployment toward devolatilization-capable twin-screw systems for rPET and rPP compounding.
- E-commerce cold-chain expansion:Food and pharmaceutical logistics operators in North America and Asia-Pacific are commissioning multi-layer barrier film extrusion lines to meet temperature integrity requirements.
- Medical-grade film demand:Sterile packaging for biologics and infusion devices is pulling integrated downstream systems with inline quality control and cleanroom compatibility.
Market Restraints
- Specialized screw and barrel alloys:Wear-resistant bimetallic linings for abrasive recycled polymers carry 40-60% cost premiums over standard nitrided steel, compressing margins for mid-tier processors.
- German machinery concentration:Critical extruder component supply clusters around Stuttgart, Munich, and Hannover, creating geographic single-point vulnerability for non-European buyers.
- Phthalate substitution friction:REACH restrictions on legacy plasticizers in PVC profiles are forcing construction end-users toward alternative polymers before extrusion lines depreciate.
Strategic Opportunities
- Southeast Asian polymer compounders:Indonesia, Vietnam, and Thailand lack domestic high-torque twin-screw capacity for engineering resin production, creating import substitution openings for equipment suppliers.
- Chemical recycling integration:Pyrolysis oil and solvolysis output streams require extrusion systems with advanced devolatilization and filtration, a white space distinct from mechanical recycling retrofits.
- Digital twin deployment:Real-time process simulation linked to predictive maintenance contracts is displacing traditional break-fix service models among North American packaging converters.
Industry Challenges
- Control systems integration:Legacy single-screw lines lack OPC-UA connectivity and edge computing architecture, forcing costly parallel automation overlays rather than native Industry 4.0 platforms.
- Devolatilization engineering talent:The specialized skill set for designing vacuum venting stages and surface-renewal devolatilizers for recycled polymers concentrates among a small cohort of German and Austrian specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Extrusion Equipment Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Screw Extruders, Twin-Screw Extruders, Multi-Screw Extruders, Special Purpose Extruders Application: Pipes, Sheets, Films, Profiles Material: Polyethylene, Polypropylene, PVC, Polystyrene End User: Packaging, Automotive, Construction, Consumer Goods |
| Companies Covered | Bausano, Davis-Standard, Coperion, JWELL, JSW, Leistritz Extrusionstechnik, Milacron, Battenfeld-Cincinnati, KraussMaffei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Extrusion Equipment Market Trends and Innovations
Extrusion technology is pivoting toward circular-economy compatibility, with equipment architecture rewiring around contamination tolerance, energy recovery, and inline rheological control rather than virgin-resin optimization.
Direct-drive torque motor technology is displacing conventional gearbox-driven extruder configurations. Medical packaging manufacturers in Switzerland and southern Germany are adopting these systems for their elimination of lubricant contamination risk and precise screw speed control. The technology is displacing gearbox-reliant designs in cleanroom-critical applications where oil seal failure carries batch rejection costs.
EU F-Gas Regulation phase-down schedules are compressing availability of HFC-based cooling for extrusion calibration units. Processors are retrofitting adiabatic cooling towers and CO2 transcritical systems, with Italian and Spanish pipe extruders facing the steepest compliance timelines due to aging infrastructure bases. The regulation is forcing chiller replacement cycles that would otherwise extend another 5-7 years.
Converters are unbundling aftermarket service contracts from original equipment purchases. North American packaging groups now procure spare parts and technical support through independent distributors rather than captive manufacturer networks, with the shift most advanced among multi-site film processors in the US Midwest seeking parts standardization across mixed-vendor fleets.
Plastic Extrusion Equipment Market Segmentation
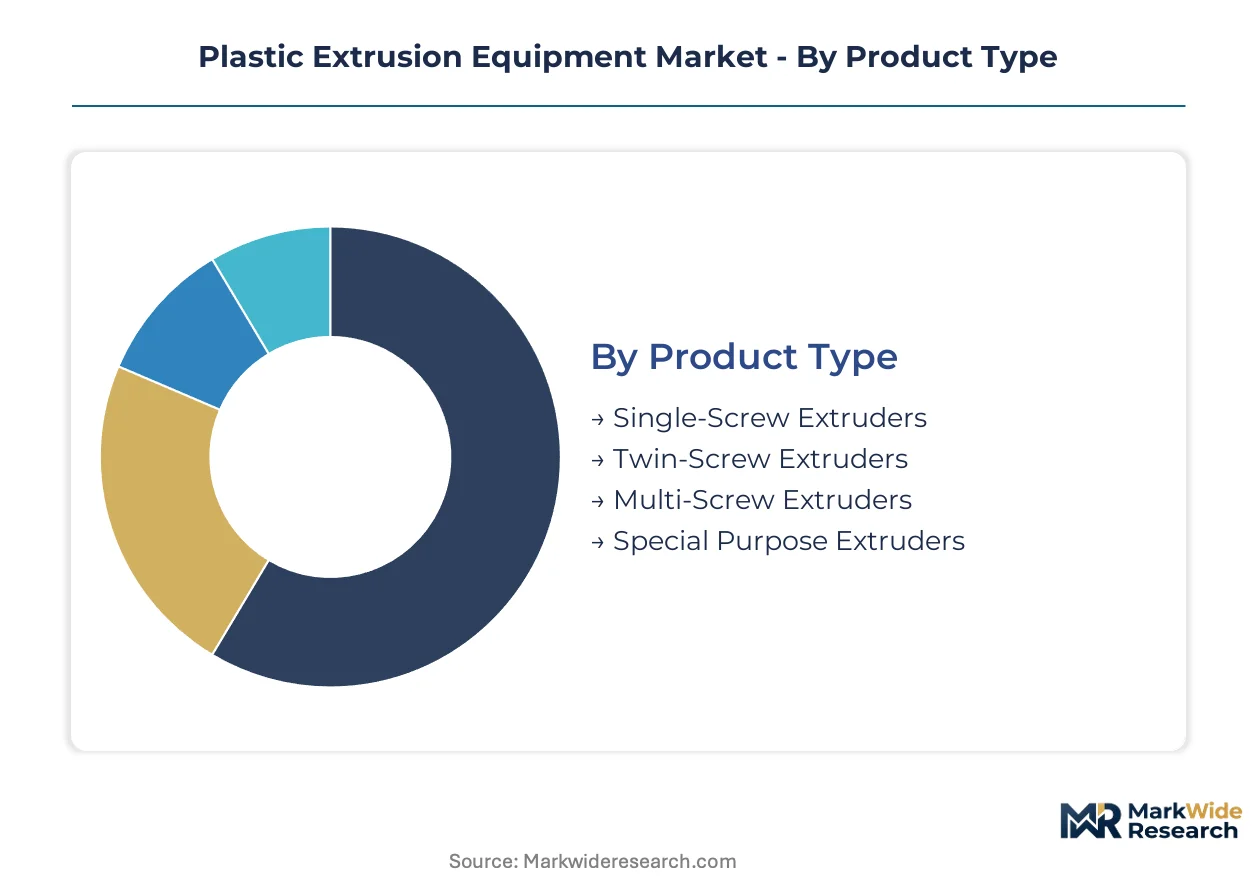
Equipment segmentation in plastic extrusion reveals divergent procurement patterns between processors serving regulated export markets and those feeding domestic construction cycles. Technical specifications vary sharply across polymer families and end-use compliance requirements.
Product Type:
German and Austrian OEMs dominate twin-screw and multi-screw exports, while single-screw production clusters in China and India for regional consumption.
- Single-Screw Extruders:These machines employ one rotating screw within a heated barrel to convey, melt, and pressurize thermoplastic polymers for continuous profile production. Construction pipe processors in India and Brazil source these systems domestically, though abrasive recycled feedstocks accelerate wear-part replacement cycles.
- Twin-Screw Extruders:Intermeshing co-rotating or counter-rotating screws enable intensive mixing, devolatilization, and reactive processing for engineering compounds. Medical film manufacturers in Switzerland and Germany specify these for cleanroom-compatible sterile packaging lines.
- Multi-Screw Extruders:Three or more screws handle highly filled or shear-sensitive formulations.
- Special Purpose Extruders:Planetary roller and disk extruders serve niche PVC dry-blend and silicone applications.
Single-screw systems command the established base. The steepest expansion runs through twin-screw configurations for recycling and compounding.
Application:
Film lines absorb the heaviest capital deployment in export-oriented packaging hubs, while pipe extrusion tracks regional infrastructure budgets.
- Pipes:Solid-wall and corrugated extrusion systems produce pressure-rated water, gas, and drainage conduit. Indian and Chinese municipal water programs sustain regional order volumes despite margin pressure from commodity resin volatility.
- Films:Blown and cast film lines generate flexible packaging substrates with controlled barrier properties. Southeast Asian cold-chain logistics operators commission multi-layer co-extrusion systems to meet pharmaceutical temperature integrity standards.
- Sheets:Thermoforming feedstock for food trays and automotive interior panels.
- Profiles:Window frames, decking, and construction trim face substitution pressure from aluminum and fiber cement.
Pipe extrusion retains the largest installed base. Film applications are climbing the fastest on e-commerce packaging demand.
Material:
Polyolefin processing equipment ships globally, while PVC systems concentrate in regions with less stringent plasticizer regulation.
- Polyethylene:LDPE and LLDPE film extrusion dominates flexible packaging capacity additions. Indonesian and Vietnamese converters favor Chinese-built blown film lines for cost-sensitive shopper bag and stretch wrap production.
- Polypropylene:Biaxially oriented PP lines serve snack food and tobacco packaging with high clarity and barrier performance. Thai and Malaysian processors upgrade to European cast film systems for regional export compliance.
- PVC:Profile and pipe extrusion faces REACH-driven substitution in European construction.
- Polystyrene:Foam sheet extrusion for food service encounters single-use bans across multiple jurisdictions.
Polyethylene equipment holds the dominant share. Polypropylene systems are gaining share fastest on medical and food packaging specifications.
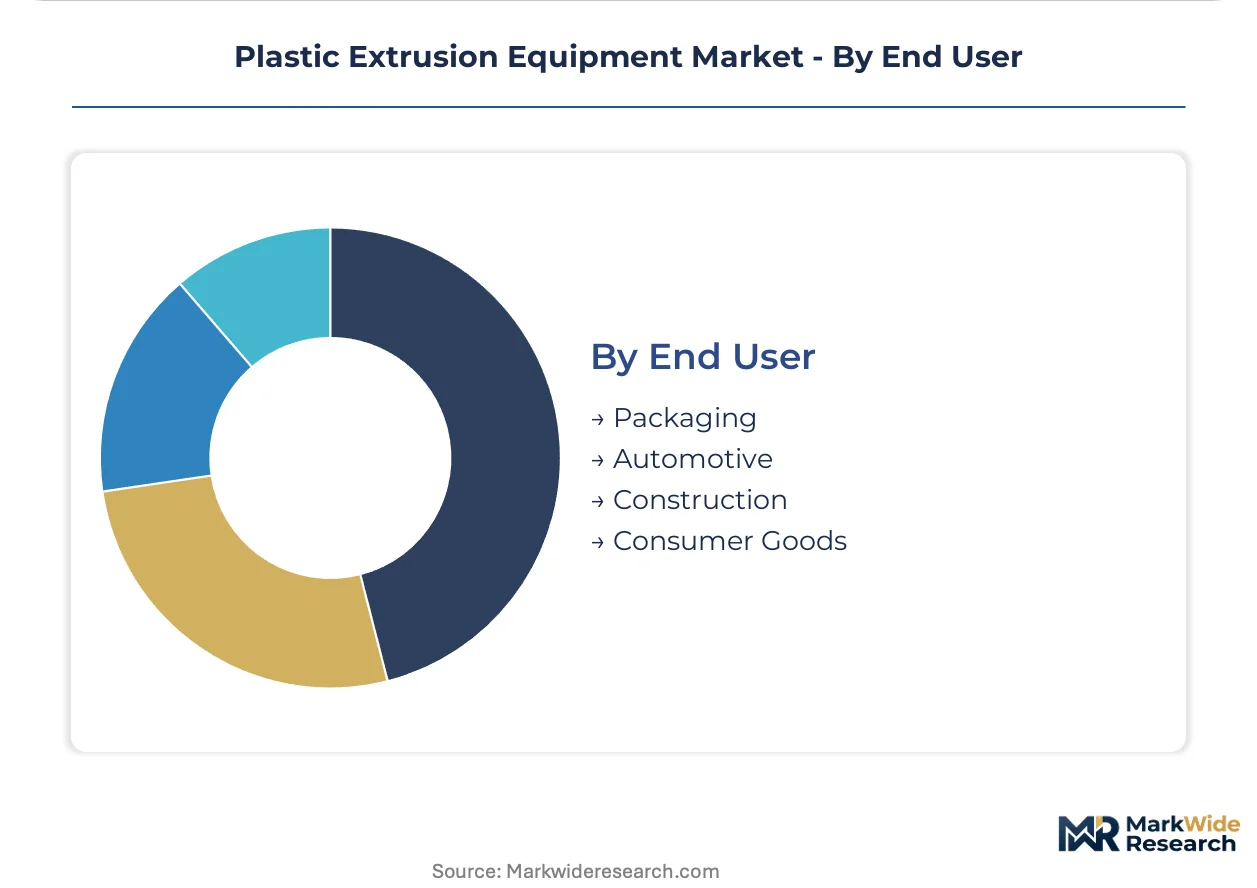
End User:
Packaging converters drive premium equipment imports, while construction and automotive procurement favors localized supply chains.
- Packaging:Film and sheet extrusion for food, pharmaceutical, and industrial flexible packaging. North American multi-site processors standardize on Davis-Standard and Windmöller & Hölscher systems for aftermarket parts interoperability.
- Construction:Pipe, profile, and geomembrane extrusion tracks public infrastructure cycles. Turkish and Egyptian window profile manufacturers source Italian PVC line technology for export to African markets.
- Automotive:Underhood tubing, interior trim, and EV battery compartment sealing profiles.
- Consumer Goods:Appliance housings and furniture components.
Packaging commands the highest equipment specification tiers. Construction maintains the broadest geographic footprint despite regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway network underwrites Central European machinery distribution, connecting Stuttgart's component foundries to Black Sea ports and enabling just-in-time delivery of precision extruder barrels to processors across the continent.
Germany
EU Green Deal recycled content mandates are redirecting capital toward co-extrusion retrofits for flexible packaging converters. ECHA REACH compliance deadlines on phthalate plasticizers are accelerating PVC profile line obsolescence in construction applications. The Stuttgart-Munich machinery belt concentrates high-throughput film line production, with component suppliers clustered around Hannover for gearbox and drive systems.
United States
EPA emissions standards for extrusion calibration cooling are forcing chiller replacement cycles among Midwestern pipe processors. FDA food-contact regulations are shaping medical-grade film line specifications for pharmaceutical packaging converters. The Ohio River Valley petrochemical corridor feeds raw material proximity advantages to regional equipment distributors serving Indiana and Illinois processors.
China
MIIT dual carbon goals are pressuring polymer processors toward energy-efficient twin-screw retrofits for recycled compound production. GB standards on food-contact plastics are tightening film line specifications for export-oriented packaging hubs. The Yangtze River Delta manufacturing cluster around Shanghai anchors domestic blown film line production for Southeast Asian export markets.
India
PLI scheme incentives for specialty chemicals are stimulating engineering resin compounding capacity additions requiring high-torque extrusion systems. BIS certification requirements for potable water pipes are upgrading specifications for municipal infrastructure procurement. The Gujarat petrochemical corridor near Vadodara concentrates domestic single-screw extruder fabrication for construction pipe applications.
Japan
METI carbon neutrality roadmaps are accelerating heat recovery retrofits on legacy film extrusion lines. PMDA medical device packaging regulations are driving cleanroom-compatible sterile film line demand from Osaka pharmaceutical clusters. The Nagoya automotive supply basin sustains precision profile extrusion equipment orders for EV battery sealing applications.
Plastic Extrusion Equipment Market Competitive Landscape
Concentration sits with integrated system suppliers commanding aftermarket service networks and proprietary screw design expertise. The vendor base stratifies across three tiers: premium European OEMs with captive downstream integration capabilities, mid-market Asian fabricators competing on twin-screw configuration flexibility, and regional specialists serving localized pipe and profile demand. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into devolatilization subsystems for chemical recycling feedstocks.
Within the European integrated-system tier, Davis-Standard and KraussMaffei exemplify machinery suppliers anchoring aftermarket revenue through North American and regional installed base density respectively. JWELL occupies a position among Asia-Pacific scale-oriented fabricators targeting polymer compounders with configurable twin-screw platforms. These three entities represent divergent geographic anchoring strategies rather than direct product competition, with each archetype capturing distinct procurement decision criteria around service proximity, specification flexibility, or capital efficiency.
| Leading Market Players |
|---|
| Bausano |
| Davis-Standard |
| Coperion |
| JWELL |
| JSW |
| Leistritz Extrusionstechnik |
| Milacron |
| Battenfeld-Cincinnati |
| KraussMaffei |
| Others |
Pricing and Supply Chain Analysis
Recycled polymer feedstock substitution for virgin resins is compressing equipment pricing tiers while redrawing supply geography toward German and Austrian devolatilization specialists. This input shift simultaneously elevates demand for wear-resistant bimetallic components and concentrates bargaining power among Stuttgart-Munich belt foundries capable of producing abrasion-tolerant extruder barrels.
Pricing Analysis
Volume-discount tiering structures separate premium European OEMs from mid-market Asian fabricators and regional pipe specialists. Pricing stratifies across premium, standard, and economy tiers based on screw configuration complexity and aftermarket service bundling. Cost compression in the standard tier is intensifying because Indonesian and Vietnamese converters are consolidating procurement across multi-site film operations. Construction pipe processors in India and Brazil exhibit the highest price sensitivity, while Swiss medical packaging manufacturers prioritize specification compliance over capital outlay.
Supply Chain Analysis
Rhine-Main-Danube waterway transit underwrites Central European machinery distribution, connecting component foundries to Black Sea ports and enabling just-in-time barrel delivery. Manufacturing concentrates in Germany, China, and Italy for finished extrusion systems, with critical gearbox and drive subsystems sourcing from Hannover-area suppliers. Supply chain risk centers on single-source vulnerability for specialized devolatilization engineering talent concentrated among German and Austrian specialists. Distribution runs through captive manufacturer networks in Europe and independent aftermarket distributors in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
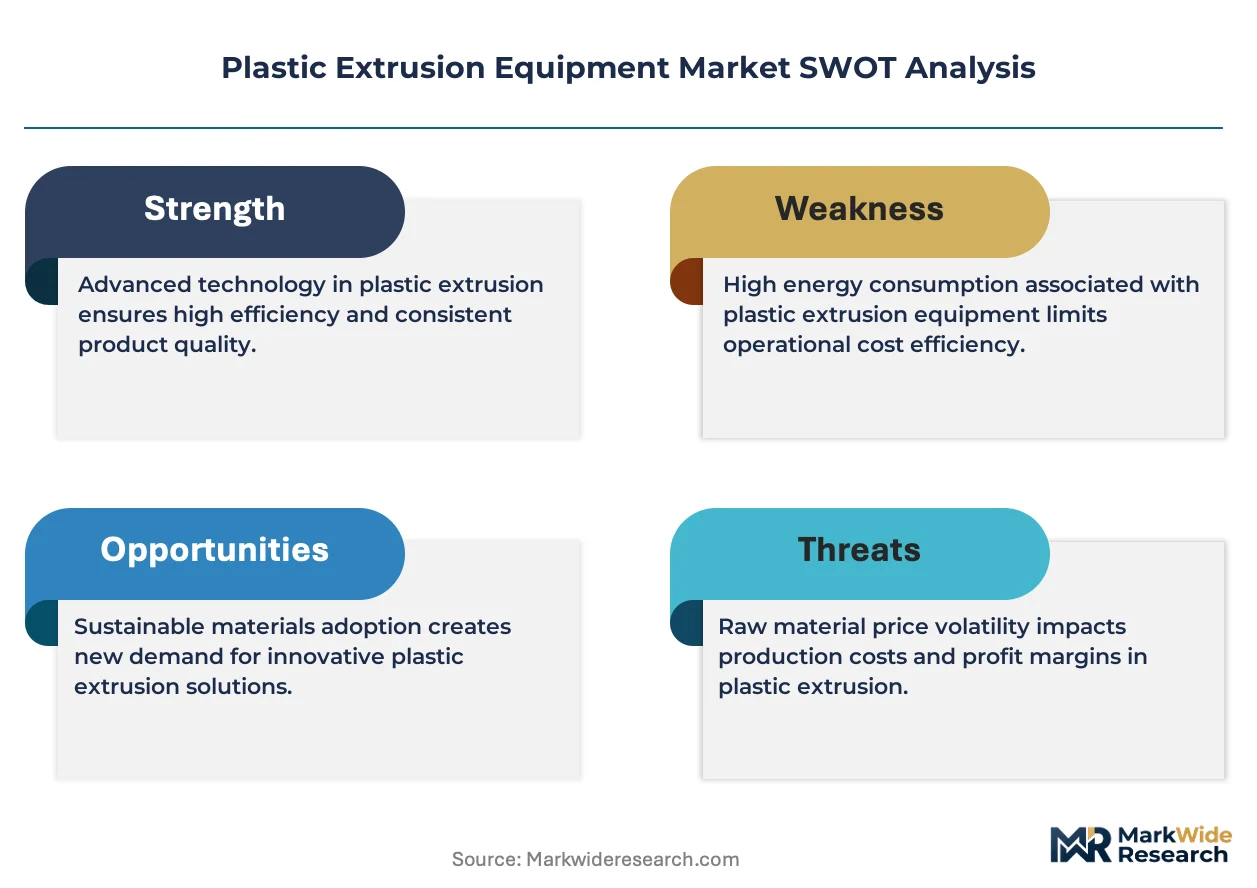
Plastic extrusion equipment sits in early-cycle expansion as EU Green Deal recycled content mandates force wholesale co-extrusion retrofits across European packaging converters. This regulatory tailwind is accelerating capital deployment timelines that would otherwise extend across normal replacement cycles.
For Market Incumbents: Compound aftermarket revenue density through predictive maintenance contracts linked to digital twin deployments, countering independent distributor encroachment in North America. Deepen captive supply of wear-resistant bimetallic barrel linings to defend margin position against Chinese twin-screw entrants. Prioritize devolatilization subsystem R&D to capture chemical recycling integration demand before specialty engineering talent scarcity hardens. For New Entrants and Emerging Players: Aftermarket service fragmentation among multi-site North American film processors offers white-space entry through standardized spare parts interoperability across mixed-vendor fleets. Target Indonesia, Vietnam, and Thailand for high-torque twin-screw configurations, where domestic engineering resin compounding capacity remains underdeveloped. Pursue joint-venture routes with established European screw designers to circumvent talent concentration barriers. For Investors and Strategic Acquirers: The market sits at a regulatory-upgrade phase that favors equipment suppliers with integrated downstream system capabilities and cleanroom-compatible product credentials. Long-term viability over the next decade hinges on circular-economy technology positioning rather than virgin-resin optimization scale. Monitor EU F-Gas Regulation compliance timelines for extrusion calibration cooling as an inflection signal for accelerated chiller replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bimetallic Barrel Production | Captive supply of wear-resistant linings defends margin compression from recycled polymer abrasion. |
| Digital Twin Platform Deployment | Real-time process simulation displaces break-fix service models among Midwestern packaging converters. |
| Chemical Recycling Feedstock Partnership | Pyrolysis oil and solvolysis streams require advanced devolatilization engineering distinct from mechanical retrofits. |
| Southeast Asian Distribution Partnership | Indonesian and Vietnamese compounders lack domestic high-torque twin-screw capacity for engineering resin production. |
| Cleanroom-Compatible System Certification | PMDA and FDA sterile packaging regulations pull integrated downstream systems with inline quality control. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, machinery export statistics, SEC filings from listed equipment suppliers, and EU regulatory implementation timelines. Bottom-up equipment shipment tracking and top-down polymer processing capacity modeling were triangulated against capital expenditure disclosures from packaging converter earnings reports.
Sensitivity analysis tested forecast robustness across recycled polymer adoption speed scenarios and regional regulatory enforcement variance throughout the projection horizon. Segmentation dimensions modeled include extruder configuration type, application end-use, processed polymer family, and geographic production cluster. CAGRs were derived from equipment shipment run-rates and replacement cycle compression factors. Industry-specific inputs incorporated EU Green Deal compliance deadlines, MIIT dual carbon goal implementation trajectories, and FDA food-contact regulatory update schedules.
Underlying assumptions cover REACH recycled content mandate adherence timelines and Southeast Asian infrastructure investment continuity, with deviation risk concentrated in German machinery belt supply disruptions and chemical recycling technology commercialization delays. Revision becomes warranted when EU F-Gas Regulation phase-down schedules accelerate beyond baseline chiller replacement assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Deblistering Machines Market
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Tissue Paper Embosser Machine Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Vertical Bagging Machine Market
Packaging Machinery
Capsule Filling Machines Market
Packaging Machinery
Cup Fill and Seal Machine Market
Packaging Machinery
In-Line Thermoforming Machine Market
Packaging Machinery
Automatic Filling Machine Market
Packaging Machinery
Injection Blow Molding Machine Market
Packaging Machinery
Bottle Capping Machines Market
Packaging Machinery
Stacking Machine Market
Packaging Machinery
Vertical Injection Molding Machine Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Granule Filling Machine Market
Packaging Machinery
Toilet Roll Converting Lines Market