
 New Zealand Cybersecurity Market | 2026-2036
New Zealand Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Cybersecurity Market Foresight
Buyer concentration across New Zealand's enterprise landscape is decoupling from traditional patterns as mid-sized financial institutions and healthcare providers fragment procurement across specialized vendors rather than consolidating with single providers. PwC Cybersecurity & Privacy Solutions leverages its audit heritage to anchor premium advisory engagements with the largest domestic banks. Kordia Limited competes through its telecommunications-backed infrastructure control, while CyberCX specializes in incident response capabilities that address the country's shortage of certified forensic specialists.
New Zealand cybersecurity encompasses the technologies, services, and governance frameworks designed to protect digital assets, networks, and data from unauthorized access, disruption, or exfiltration, with core functional parameters including encryption protocols, intrusion detection thresholds, and zero-trust architecture implementation. Its primary commercial purpose is to enable organizational continuity and regulatory compliance in an environment of escalating automated threat campaigns. Managed Security Services commands the largest share of service-type expenditure as organizations outsource round-the-clock monitoring to address domestic talent scarcity. Cloud-based deployment is expanding fastest among SMEs migrating from legacy on-premises infrastructure, while hybrid configurations dominate among government agencies balancing sovereignty requirements with scalability needs.
The Privacy Act 2020 and the Office of the Privacy Commissioner shape demand through mandatory breach notification timelines that compress response windows and elevate insurance requirements. The Government Communications Security Bureau's Critical Infrastructure Directive further tightens product standards for designated operators in energy and telecommunications. Stakeholders must monitor how Wellington's evolving procurement frameworks for sovereign cloud certification will redistribute competitive advantage among local and offshore service providers.
Market Dynamics
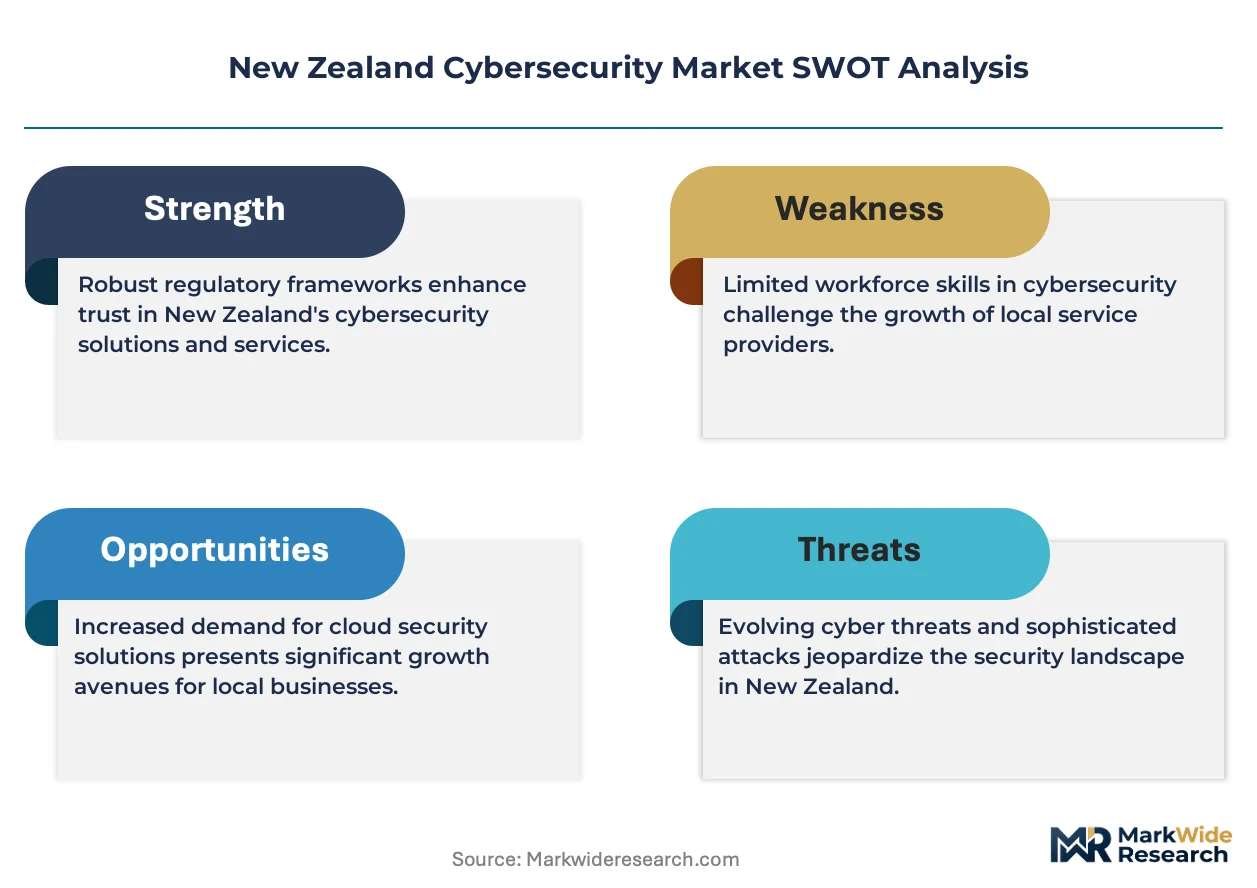
The Privacy Act 2020 compresses breach response windows to 72 hours, forcing organizations to automate detection workflows and outsource forensic capabilities they cannot staff internally. This regulatory velocity is concentrating procurement power among managed security service providers with domestic incident response presence.
Growth Catalysts
- Mandatory notification timelines:The Privacy Act 2020 and Office of the Privacy Commissioner require rapid breach disclosure, compelling financial institutions and healthcare providers to invest in real-time monitoring infrastructure.
- Critical Infrastructure Directive:The Government Communications Security Bureau tightens product standards for energy and telecommunications operators, mandating sovereign-certified security controls.
- Auckland cloud concentration:Enterprise headquarters and hyperscale infrastructure nodes cluster in Auckland, creating localized demand density for managed detection and response services.
Market Restraints
- Domestic talent scarcity:Certified forensic specialists and security architects command premium compensation, inflating service delivery costs beyond mid-sized organization budgets.
- Offshore vendor dependence:Cloud security tooling and threat intelligence feeds rely predominantly on Australian and US-headquartered platforms, creating foreign exchange exposure and data sovereignty friction.
- Legacy infrastructure debt:Government agencies and regional banks maintain hybrid environments where zero-trust architecture integration requires expensive parallel system operation.
Strategic Opportunities
- Wellington sovereign cloud certification:Evolving procurement frameworks for government cloud accreditation will redistribute competitive advantage toward providers with domestic data residency guarantees.
- Healthcare provider digitization:District health boards migrating patient records to cloud platforms require specialized health data protection services currently undersupplied in the domestic market.
- Convergence of AI and behavioral analytics:Automated threat hunting tools integrated with user entity behavior analytics open new service tiers for mid-market financial services firms.
Industry Challenges
- Forensic certification bottlenecks:The domestic shortage of GIAC-certified incident responders extends mean-time-to-containment for sophisticated intrusions beyond acceptable risk thresholds.
- Interoperability complexity:Security operations centers struggle to correlate alerts across fragmented toolchains deployed during rapid cloud migrations, creating visibility gaps adversaries exploit.
- Board-level security literacy:Non-technical directors demand simplified risk metrics that obscure operational realities, complicating resource allocation for security teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Cybersecurity Market |
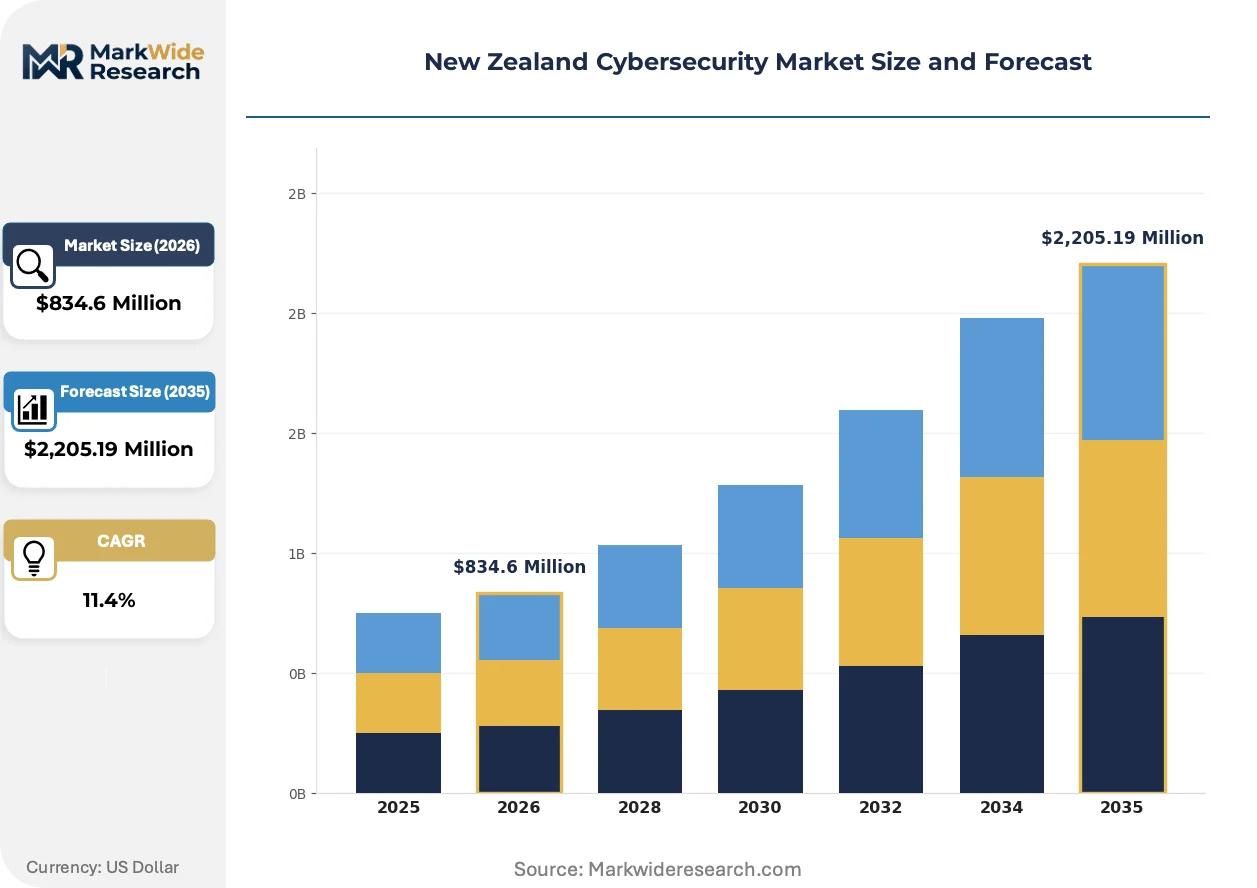
| Market Size in 2026 | $834.6 Million |
| Market Size in 2035 | $2,205.19 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Managed Security Services, Risk Assessment, Incident Response Industry Vertical: Healthcare, Financial Services, Government, Education Deployment: On-premises, Cloud-based, Hybrid, Community Cloud End User: SMEs, Large Enterprises, Government Agencies, Non-profit Organizations |
| Companies Covered | PwC Cybersecurity & Privacy Solutions, Accenture Security, Factosecure, Datacom Group Ltd., Kordia Limited, CyberCX, KPMG Cybersecurity Advisory, Kaon Security, Deloitte Cyber Risk Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Cybersecurity Market Shifts & Advancements
Zero-trust architecture is displacing perimeter-based security models as the dominant design paradigm, with implementation patterns diverging sharply between cloud-native enterprises and legacy-dependent institutions. Three developments are compressing competitive timelines and reshaping vendor positioning.
Secure access service edge technology is decentralizing network security enforcement from centralized data centers to distributed cloud edges. Mid-sized financial institutions are adopting SASE at the fastest pace among domestic verticals, compressing procurement cycles for traditional firewall and VPN vendors. This architecture is decentralizing the market power of telecommunications-backed security providers who previously controlled last-mile infrastructure.
The Government Communications Security Bureau's Critical Infrastructure Directive mandates baseline security controls for designated operators in energy and telecommunications. Industrial consequence includes mandatory supply chain attestation for software vendors serving these sectors. Energy distribution utilities face the steepest compliance burden, accelerating their migration to sovereign-certified managed security services.
Security service unbundling is fragmenting historically consolidated procurement relationships. Large domestic banks are separating advisory, implementation, and managed detection contracts across specialized vendors rather than consolidating with single providers. This pattern is most visible in Auckland's enterprise corridor, where procurement teams now evaluate forensic response capabilities independently from broader managed services.
New Zealand Cybersecurity Market Segmentation
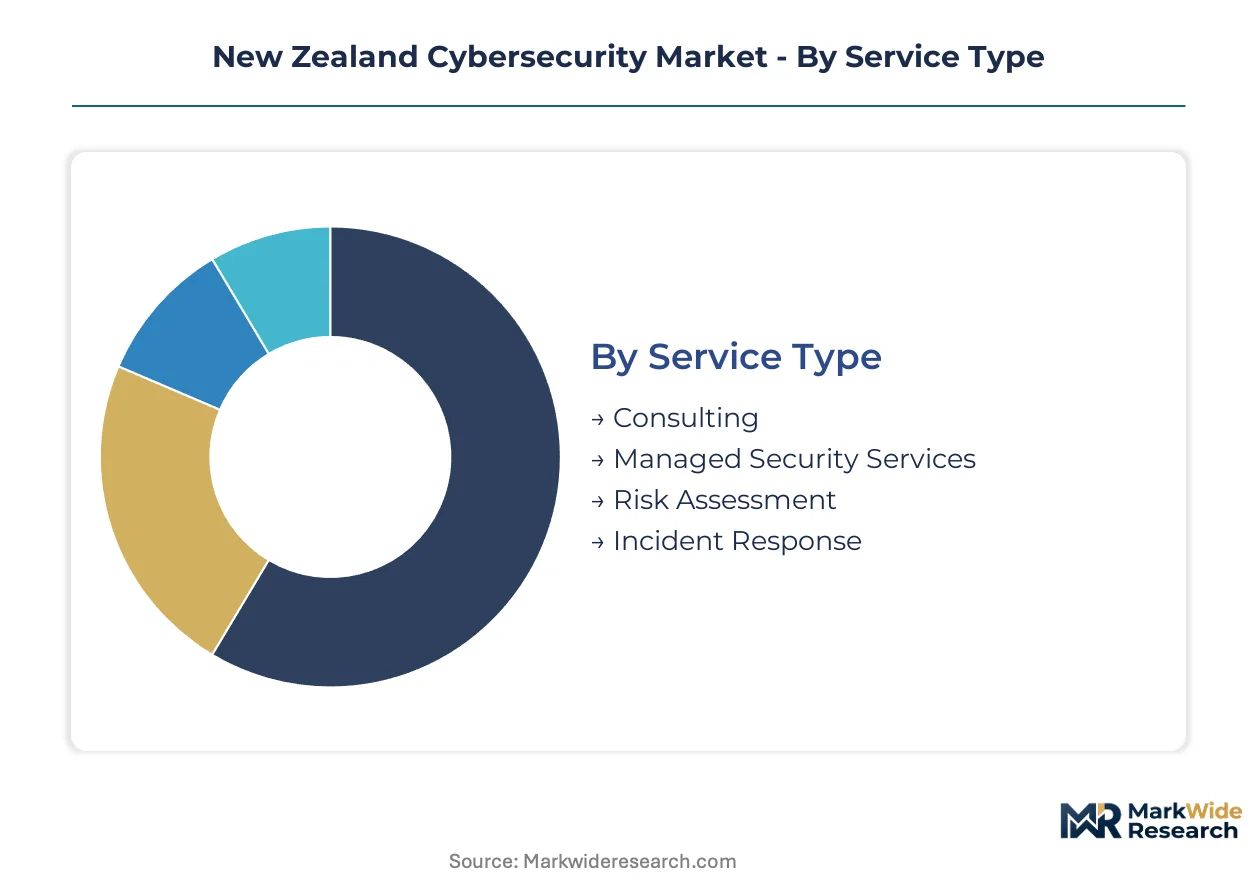
New Zealand's cybersecurity market fragments across service delivery models, regulatory exposure profiles, and infrastructure maturity levels. Procurement patterns diverge sharply between Auckland-based financial institutions with cloud-native architectures and Wellington government agencies navigating sovereign data requirements.
Service Type:
Supply concentration among domestic providers varies dramatically by capability depth, with telecommunications-backed infrastructure operators controlling network-layer services while boutique firms capture forensic specialties.
- Managed Security Services:Round-the-clock monitoring, threat detection, and response operations delivered through security operations centers. Auckland's enterprise corridor generates the densest demand as mid-sized banks outsource functions they cannot staff internally due to certified analyst scarcity.
- Incident Response:Forensic investigation, containment, and recovery services activated post-breach. The Privacy Act 2020's 72-hour notification window compresses procurement timelines for domestic providers with GIAC-certified specialists, creating acute supply bottlenecks during widespread campaigns.
- Consulting:Strategic advisory on security architecture, governance frameworks, and compliance roadmaps.
- Risk Assessment:Vulnerability scanning, penetration testing, and control maturity evaluations against industry benchmarks.
Managed Security Services absorbs the bulk of installed capacity; Incident Response is expanding most quickly.
Industry Vertical:
Regulatory velocity and digitization maturity create divergent spending profiles across sectors, with mandatory notification regimes and critical infrastructure designations redistributing procurement priorities.
- Financial Services:Banks, insurers, and payment processors confronting sophisticated fraud automation and open banking API exposure. Wellington's regulatory proximity drives compliance-heavy procurement patterns among domestic systemically important institutions.
- Government:Central agencies, district health boards, and crown entities navigating the Government Communications Security Bureau's Critical Infrastructure Directive. Sovereign cloud certification requirements concentrate demand among providers with domestic data residency guarantees.
- Healthcare:District health boards and primary care networks migrating patient records to cloud platforms.
- Education:Universities and polytechnics managing research data protection and remote learning infrastructure.
Financial Services commands the largest share of premium advisory expenditure; Government is climbing the fastest as sovereign cloud mandates accelerate.
Deployment:
Legacy infrastructure debt and data sovereignty requirements fragment adoption patterns, with hybrid configurations dominating among established institutions while cloud-native models attract newer market entrants.
- Cloud-based:Fully outsourced security infrastructure delivered through hyperscale platforms. SMEs across Auckland's commercial districts adopt this model fastest to bypass capital constraints and talent scarcity.
- Hybrid:Integrated on-premises and cloud security controls with unified policy enforcement. Government agencies and regional banks maintain this architecture to balance sovereignty requirements against scalability needs, requiring expensive parallel system operation during transition periods.
- On-premises:Self-managed security appliances and software within organizational data centers.
- Community Cloud:Shared infrastructure serving specific sectors with common compliance requirements.
Hybrid deployments retain the majority of legacy infrastructure expenditure; Cloud-based is gaining share fastest among mid-market entrants.
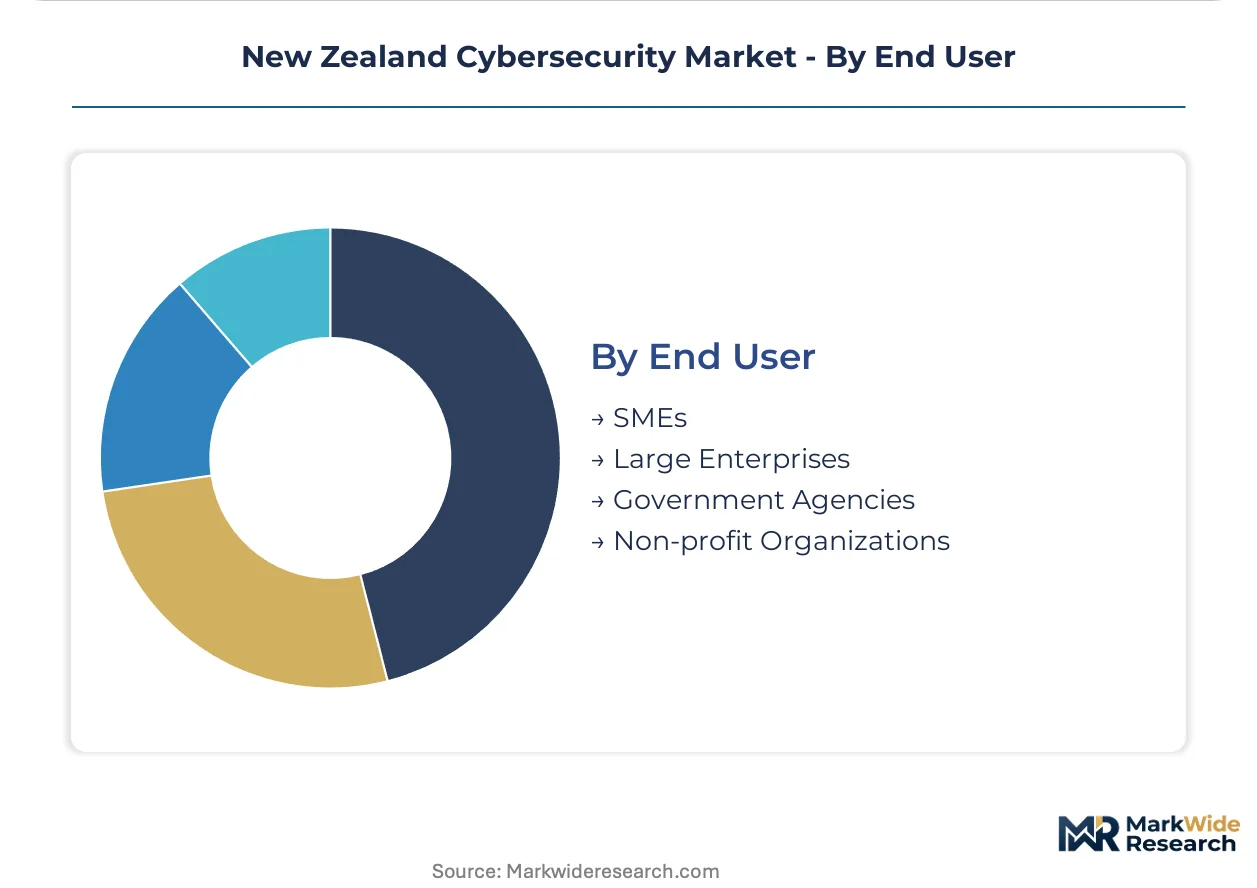
End User:
Organizational scale determines procurement sophistication, with large enterprises fragmenting contracts across specialized vendors while smaller entities consolidate with single providers.
- Large Enterprises:Domestic banks, telecommunications operators, and energy utilities with dedicated security functions. These organizations unbundle advisory, implementation, and managed detection contracts across specialized Auckland-based vendors rather than consolidating with single providers.
- SMEs:Mid-sized professional services firms, manufacturing operations, and retail chains with limited internal security expertise. Managed Security Services providers capture this segment through standardized packages addressing the Privacy Act 2020's baseline requirements.
- Government Agencies:Central and local government bodies with sovereign certification mandates.
- Non-profit Organizations:Charitable and social service providers with constrained technology budgets.
Large Enterprises absorb the bulk of specialized forensic and advisory expenditure; SMEs represent the steepest expansion trajectory as regulatory compliance extends downstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise cybersecurity procurement concentrates in Auckland's commercial corridor where hyperscale cloud nodes and financial institution headquarters cluster, while Wellington's government precinct drives sovereign-certified demand through regulatory proximity.
Auckland
Domestic banks and telecommunications operators anchor demand for managed detection and response services. The Privacy Act 2020's 72-hour notification window compresses procurement cycles for incident response capabilities. Auckland's enterprise corridor generates the densest vendor fragmentation as large institutions unbundle advisory, implementation, and managed services contracts across specialized providers.
Wellington
Central government agencies and crown entities navigate the Government Communications Security Bureau's Critical Infrastructure Directive. Sovereign cloud certification requirements concentrate procurement among providers with domestic data residency guarantees. Wellington's procurement frameworks for government cloud accreditation redistribute competitive advantage toward local service providers.
Canterbury
District health boards migrating patient records to cloud platforms require specialized health data protection services. The Privacy Act 2020 mandates notification requirements that compel healthcare providers to strengthen data governance frameworks. Christchurch's health technology cluster experiences acute supply bottlenecks for certified forensic specialists during widespread campaigns.
Waikato
Regional manufacturing operations and agricultural technology firms adopt standardized managed security packages. Mid-sized enterprises with limited internal security expertise outsource round-the-clock monitoring to address domestic talent scarcity. Hamilton's commercial districts represent the steepest SME expansion trajectory as regulatory compliance extends downstream.
New Zealand Cybersecurity Market Competitive Landscape
Established professional services networks occupy the standard tier; emerging cloud-native specialists pursue managed detection automation. The market exhibits tiered fragmentation where audit-heritage consultancies anchor premium advisory engagements while telecommunications-backed infrastructure operators control network-layer services. Three archetypes dominate: audit-anchored advisory firms, infrastructure-control specialists, and forensic-response boutiques. Competitive moves concentrate on unbundling historically consolidated contracts and securing sovereign cloud certification credentials.
Within the audit-heritage tier, PwC Cybersecurity & Privacy Solutions and KPMG Cybersecurity Advisory exemplify firms leveraging assurance backgrounds to anchor risk advisory relationships with systemically important financial institutions. Kordia Limited occupies a position among telecommunications-backed operators whose infrastructure control confers advantages in network-layer security delivery. CyberCX represents the incident-response specialist archetype, sitting within a segment where certified forensic capabilities command premium positioning.
| Leading Market Players |
|---|
| PwC Cybersecurity & Privacy Solutions |
| Accenture Security |
| Factosecure |
| Datacom Group Ltd. |
| Kordia Limited |
| CyberCX |
| KPMG Cybersecurity Advisory |
| Kaon Security |
| Deloitte Cyber Risk Services |
| Others |
Supply & Pricing Matrix
Certified forensic analyst scarcity in Auckland and Wellington feeds directly into pricing-tier spreads across New Zealand's cybersecurity market. Labor-cost differentials between GIAC-certified incident responders and standard security operations analysts create three distinct service bands that vendors exploit to segment procurement budgets.
Pricing Analysis
Volume concentrates in standardized managed security subscriptions while margins accrue to boutique incident response retainers. Three-tier pricing structure across premium advisory, managed detection, and economy monitoring levels separates PwC-led risk consulting from telecommunications-backed network services and offshore SaaS tooling. Price differentiation hinges on certification density and domestic data residency guarantees. Cost compression in mid-market managed services is intensifying because Australian platform vendors are undercutting local providers on subscription rates. SMEs exhibit highest price sensitivity; systemically important banks show lowest, prioritizing response-time guarantees over per-hour economics.
Supply Chain Analysis
Dual-sourcing requirements embedded in the Privacy Act 2020 and Government Communications Security Bureau directives compel buyers to qualify multiple incident response providers, fragmenting contract concentration. Technology sourcing draws from the United States, Australia, and Singapore for cloud security platforms, threat intelligence feeds, and forensic tooling. Raw material dependencies include proprietary detection algorithms, sovereign-certified data center capacity, and GIAC-certified labor pipelines. Single-source vulnerability persists in threat intelligence aggregation where global feeds concentrate through Palo Alto and CrowdStrike nodes. Distribution runs through direct enterprise sales for advisory services and channel partners for standardized monitoring packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand cybersecurity represents a consolidation play where regulatory compliance burdens and talent scarcity will force sub-scale managed service providers into strategic exits. The Privacy Act 2020's 72-hour notification window acts as the primary pressure eliminating players without domestic forensic presence.
For Market Incumbents: To counter unbundling by Auckland-based banks separating advisory from managed detection contracts, anchor premium positioning through sovereign cloud certification investment and exclusive GIAC training pipelines. Secure Wellington government accreditation before procurement frameworks harden around domestic data residency requirements. Control channel access by embedding incident response retainers into multi-year managed security agreements. For New Entrants and Emerging Players: The gap between premium forensic retainers and economy SaaS monitoring creates entry space for mid-market providers bundling automated detection with basic response capabilities. Target Waikato manufacturing clusters and Canterbury health networks where regulatory compliance is extending downstream but specialist supply remains thin. Pursue channel partnerships with Datacom and Kordia to bypass direct sales infrastructure buildout. For Investors and Strategic Acquirers: The window for entry favors incident-response boutiques with certified specialist depth over generalized managed service platforms. Long-term viability hinges on Wellington sovereign cloud accreditation as government procurement tilts toward domestic data guarantees. Watch the Government Communications Security Bureau's evolving critical infrastructure designation list as the inflection signal for accelerated compliance spending.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Wellington procurement frameworks redistribute advantage toward providers with domestic data residency guarantees. |
| GIAC Training Pipeline Investment | Auckland banks and government agencies prioritize vendors with certified forensic specialists onshore. |
| Incident Response Retainer Packaging | Privacy Act 2020 compression of notification windows elevates premium positioning for guaranteed response times. |
| Healthcare Data Protection Specialization | Canterbury district health boards migrating patient records require specialized services currently undersupplied domestically. |
| Automated Threat Hunting Integration | Mid-market financial services firms in Auckland adopt AI-behavioral analytics bundles fastest among domestic verticals. |
Research Methodology
Regulatory filings from the Office of the Privacy Commissioner, Government Communications Security Bureau directives, and Auckland commercial tenancy databases formed the secondary backbone for demand sizing. Primary interviews with CISOs at domestic banks, procurement leads at district health boards, channel managers at telecommunications operators, and compliance officers at energy utilities were combined with this secondary validation. Bottom-up triangulation across service-type expenditure and top-down reconciliation against national IT spending benchmarks anchored volume estimates.
Historical trendline analysis across managed security services, incident response, and advisory expenditure established baseline growth patterns. Segmentation modeling incorporated service delivery model, regulatory exposure profile, deployment architecture, and organizational scale dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted projections of Privacy Act compliance spending and critical infrastructure designation expansion. Industry-specific inputs included certified analyst pipeline data from domestic training providers and hyperscaler capex disclosures for Auckland cloud node expansion.
Inputs from Privacy Commissioner breach notification statistics and GCSB procurement frameworks were available through the study window; gaps in real-time SME security spending introduce uncertainty bands around mid-market penetration assumptions. Deviation in Wellington sovereign cloud accreditation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Colombia Cybersecurity Market
Cybersecurity
North America Digital Forensics Market
Cybersecurity
Denmark Cybersecurity Market
Cybersecurity
Homomorphic Encryption Market
Cybersecurity
Advanced Malware Detection (AMD) Market
Cybersecurity
Latin America Cybersecurity Market
Cybersecurity
Canada Ransomware Protection Market
Cybersecurity
Belgium Cybersecurity Market
Cybersecurity
Thailand Cybersecurity Market
Cybersecurity
Nordics Cybersecurity Market
Cybersecurity
Europe IoT Security Market
Cybersecurity
Global Quantum Cryptography Solutions Market
Cybersecurity
Botnet Detection Market
Cybersecurity
Singapore Cybersecurity Market
Cybersecurity
Global IoT Digital Forensics Market
Cybersecurity
Digital Security Market