
 Germany Endpoint Detection and Response Market | 2026-2036
Germany Endpoint Detection and Response Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Endpoint Detection and Response Market Insights
Agent-light architecture is reorganizing how German enterprises evaluate endpoint protection. CrowdStrike Holdings leverages its cloud-native platform to dominate managed detection workloads across Mittelstand manufacturers. Microsoft Corporation anchors enterprise accounts through deep Entra ID integration. Palo Alto Networks competes with Cortex XDR bundling that extends firewall relationships into endpoint coverage.
Endpoint Detection and Response denotes a cybersecurity technology that continuously monitors endpoint devices through kernel-level telemetry collection, behavioral heuristics, and automated threat remediation to neutralize advanced persistent threats before lateral movement occurs. The system ingests process execution chains, DNS requests, and file system mutations to build probabilistic attack timelines for security operations centers. Cloud-based deployment is capturing the fastest expansion as German firms retire on-premises security stacks, while AI-powered behavioral analysis concentrates margin pools through reduced false-positive overhead. Financial institutions represent the most demanding end-user segment, driving premium pricing for managed threat-hunting services.
BaFin's MaRisk cyber-resilience requirements and the BSI IT-Grundschutz framework shape product certification pathways, forcing vendors to attain Common Criteria evaluation or lose federal procurement eligibility. The EU NIS2 Directive tightens incident-reporting windows to twenty-four hours, accelerating automated response module adoption. Stakeholders must monitor BSI's forthcoming cloud-security certification criteria to anticipate compliance-driven refresh cycles.
Market Dynamics
BaFin's MaRisk cyber-resilience mandates are forcing German financial institutions into accelerated EDR refresh cycles, compressing procurement timelines from thirty-six to eighteen months and privileging vendors with pre-certified Common Criteria evaluations.
Growth Catalysts
- BSI IT-Grundschutz framework:Federal procurement rules now require Common Criteria certification for endpoint security tools, creating a regulatory pull that eliminates uncertified vendors from public-sector tenders.
- EU NIS2 Directive:Twenty-four-hour incident-reporting windows mandate automated response modules, driving replacement of legacy signature-based antivirus across critical infrastructure operators.
- Cloud migration:Bavarian technology firms are retiring on-premises security stacks, creating disproportionate demand for cloud-native EDR architectures that scale without hardware refresh cycles.
Market Restraints
- Certification timeline friction:Common Criteria evaluation cycles extend fourteen to eighteen months, delaying product launches and freezing vendor R&D roadmaps during assessment periods.
- Skill concentration in urban centers:Qualified security operations analysts cluster in Munich, Berlin, and Hamburg, leaving Mittelstand manufacturers in rural Baden-Württemberg and Lower Saxony chronically understaffed.
- Legacy endpoint agent entrenchment:Established antivirus contracts with multi-year renewal clauses create switching costs that delay EDR adoption in cost-sensitive municipal and healthcare sectors.
Strategic Opportunities
- Managed detection and response services:Mid-sized manufacturers in the Ruhr industrial belt lack internal SOC capacity, creating white space for outsourced threat-hunting subscriptions priced per endpoint.
- Operational technology convergence:Industrial control systems in automotive and chemical plants require EDR extensions onto PLC and SCADA networks, a segment currently underserved by IT-centric vendors.
- BSI cloud-security certification:Pending federal criteria for SaaS security tools will trigger compliance-driven procurement waves among insurers and federal contractors seeking pre-approval.
Industry Challenges
- Kernel-level telemetry expertise:Vendors struggle to recruit driver developers capable of building stable Windows and Linux kernel modules that capture process execution without blue-screen failures.
- False-positive calibration:Behavioral heuristics tuned for financial services generate excessive alerts when deployed in manufacturing environments with non-standard legacy applications, eroding SOC trust.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Endpoint Detection and Response Market |
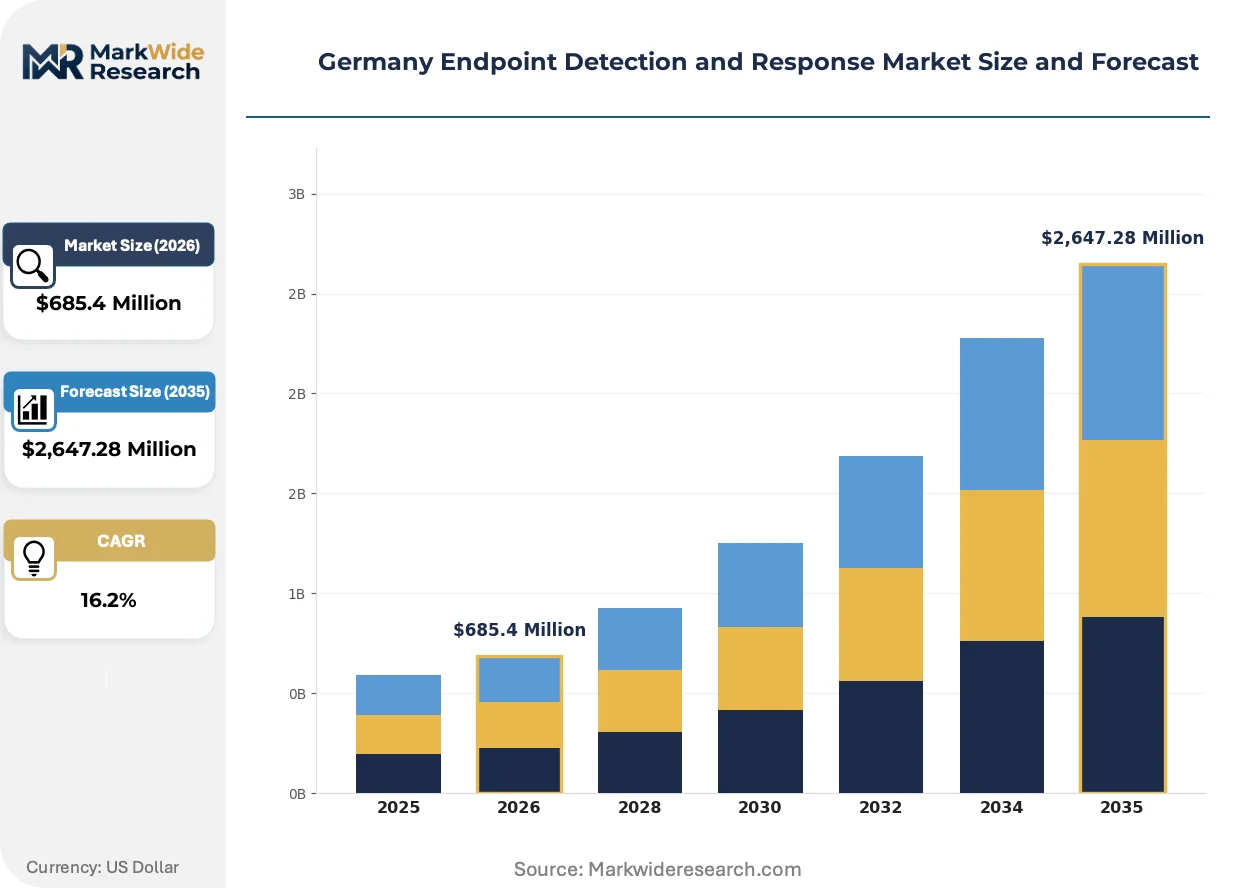
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,647.28 Million |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services End User: SMEs, Large Enterprises, Government Organizations, Financial Institutions Technology: AI-Powered, Behavioral Analysis, Threat Intelligence, Automated Response Service Type: Incident Response, Threat Hunting, Security Monitoring, Vulnerability Management |
| Companies Covered | CrowdStrike Holdings, Microsoft Corporation, Palo Alto Networks, Trend Micro, Fortinet, Cisco Systems, Check Point Software Technologies, G Data CyberDefense, SentinelOne, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Endpoint Detection and Response Market Trends and Innovations
Agent-light architecture is restructuring competitive positioning by reducing endpoint resource consumption and enabling deployment on embedded industrial systems previously considered too constrained for continuous monitoring.
Extended detection and response platforms are decomposing the traditional perimeter by ingesting firewall, identity, and cloud workload telemetry alongside endpoint data. German automotive suppliers with complex multi-site manufacturing networks are adopting these consolidated stacks fastest. The convergence is compressing standalone EDR vendor margins as customers demand bundled pricing across security layers.
The EU NIS2 Directive tightens incident-reporting obligations to twenty-four hours for critical infrastructure operators. German energy utilities and transport providers must now deploy automated containment playbooks that execute without human approval. Financial institutions represent the most advanced adopters, having pre-positioned response modules to meet BaFin's existing operational resilience requirements.
Subscription-based procurement is displacing perpetual licensing across Mittelstand manufacturers who prefer operational expenditure treatment and bundled threat-intelligence updates. Value-added resellers in Frankfurt and Stuttgart are capturing margin by wrapping managed detection services around platform licenses. The shift is most visible among precision engineering firms with limited internal security staff who outsource tier-one alert triage entirely.
Germany Endpoint Detection and Response Market Segmentation
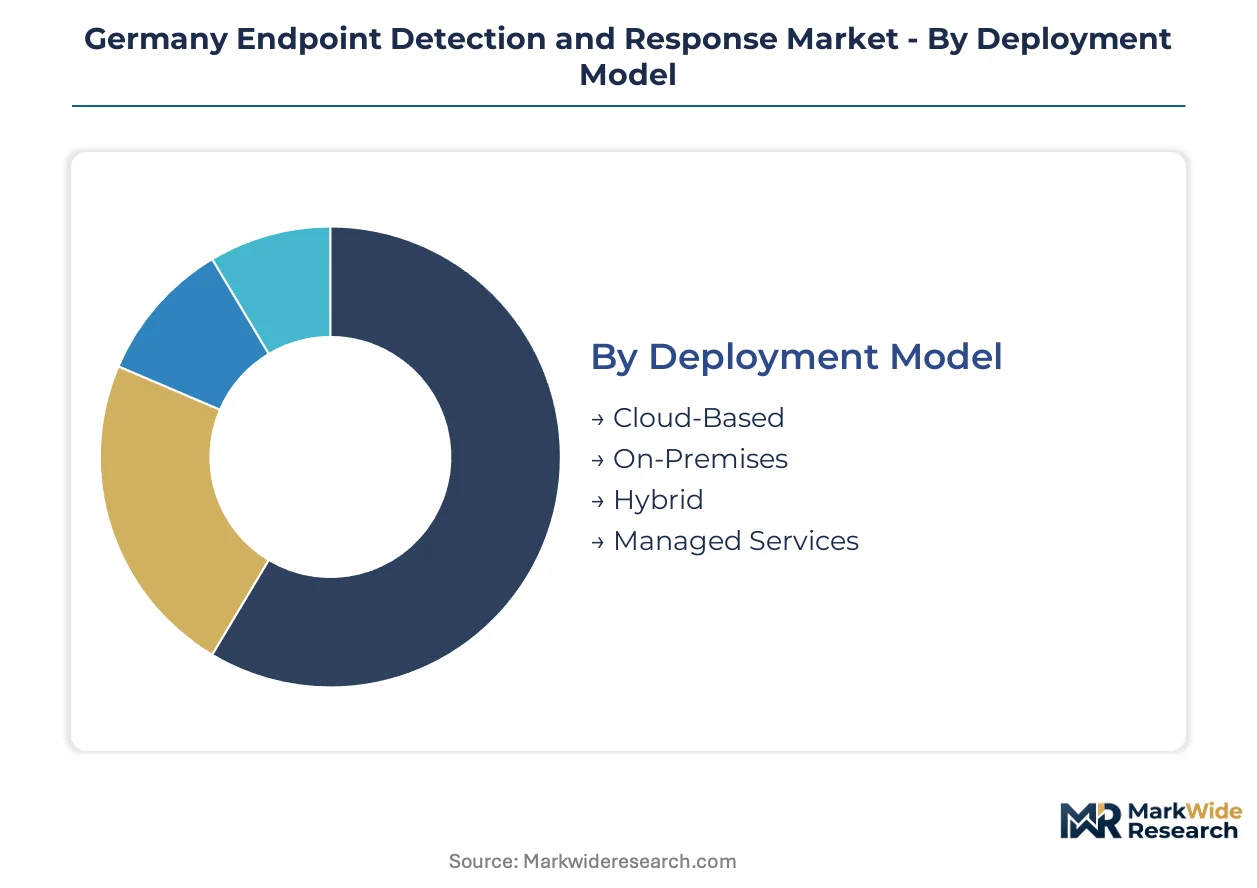
German EDR procurement patterns diverge sharply across deployment models and end-user sophistication, with regulatory compliance tiers creating natural segmentation boundaries. Understanding these divisions reveals where vendors can command premium pricing versus where standardized solutions dominate.
Deployment Model:
BaFin's MaRisk mandates and BSI IT-Grundschutz certification requirements create divergent deployment preferences across regulated and unregulated sectors.
- Cloud-Based:Cloud-native architectures eliminate hardware refresh cycles and scale elastically for Bavarian technology firms retiring legacy stacks. Mittelstand manufacturers in the Ruhr industrial belt favor this model to convert capital expenditure into operational expenditure while receiving continuous threat-intelligence updates.
- On-Premises:Air-gapped installations persist in defense contractors and classified federal facilities where data sovereignty concerns override cloud convenience. These deployments require dedicated infrastructure teams and carry longer procurement cycles due to extended security clearance protocols.
- Hybrid:Split architectures allow financial institutions to retain sensitive transaction data on-premises while pushing lower-sensitivity workloads to certified cloud environments. This model satisfies both operational resilience requirements and cost optimization pressures.
- Managed Services:Outsourced detection and response addresses chronic analyst shortages in rural Baden-Württemberg and Lower Saxony manufacturing zones. Third-party SOCs deliver 24/7 coverage that understaffed internal teams cannot replicate.
Established volume favors On-Premises; emerging adoption favors Cloud-Based.
End User:
Security maturity and procurement sophistication create tiered demand patterns across German organizational types.
- SMEs:Resource-constrained mid-sized manufacturers prioritize bundled managed services over platform investments. These organizations lack dedicated security staff and rely on value-added resellers in Frankfurt and Stuttgart for outsourced tier-one alert triage.
- Large Enterprises:Complex multi-site automotive suppliers with distributed manufacturing networks require consolidated XDR stacks that ingest firewall, identity, and cloud workload telemetry alongside endpoint data. Procurement teams negotiate enterprise-wide pricing with deep integration requirements.
- Government Organizations:Federal and state agencies mandate Common Criteria certification as a baseline eligibility filter, freezing out vendors without completed evaluations. Procurement timelines extend to accommodate mandatory security assessments.
- Financial Institutions:Banks and insurers operate under the strictest regulatory pressure, with BaFin operational resilience requirements forcing eighteen-month refresh cycles. These organizations command premium pricing for automated response modules and managed threat-hunting services.
Revenue concentration sits with Financial Institutions; volume expansion is climbing the fastest among SMEs.
Technology:
Detection sophistication determines margin capture, with AI-powered solutions commanding pricing premiums over signature-based alternatives.
- AI-Powered:Machine learning models reduce false-positive overhead and enable predictive threat identification before lateral movement occurs. German energy utilities deploy these systems to meet EU NIS2 Directive automated containment requirements.
- Behavioral Analysis:Heuristic engines tuned for financial services generate excessive alerts when deployed in manufacturing environments with non-standard legacy applications, requiring careful calibration for industrial settings.
- Threat Intelligence:Real-time indicator feeds from federal BSI sources and commercial providers enable proactive blocking of known adversary infrastructure.
- Automated Response:Pre-positioned containment playbooks execute without human approval, satisfying twenty-four-hour incident-reporting windows for critical infrastructure operators.
Margin pools concentrate in AI-Powered; compliance-driven refresh cycles favor Automated Response.
Service Type:
Delivery complexity separates commoditized monitoring from high-value specialized offerings.
- Incident Response:Retainer-based emergency services provide guaranteed response times during active breaches. German automotive suppliers maintain these contracts to minimize production downtime from ransomware events.
- Threat Hunting:Proactive human-led investigations uncover advanced persistent threats that automated systems miss. Financial institutions in Frankfurt represent the primary demand center for these premium services.
- Security Monitoring:Continuous SOC operations deliver baseline visibility without specialized investigative depth.
- Vulnerability Management:Systematic exposure assessment and patching coordination reduces attack surface across heterogeneous endpoint fleets.
Current revenue weighting favors Security Monitoring; steepest expansion trajectory belongs to Threat Hunting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German EDR vendors export managed detection services to neighboring economies while importing specialized kernel telemetry expertise from Israel and the United States. This exchange pattern concentrates high-value platform development in Munich and Berlin while sourcing advanced behavioral analytics capabilities externally.
Bavaria
Munich's technology corridor drives cloud-native EDR adoption as software firms retire legacy on-premises stacks. BSI IT-Grundschutz certification requirements shape procurement decisions for federal contractors headquartered in the region. Ingolstadt's automotive suppliers deploy agent-light architectures across manufacturing networks to monitor industrial control systems.
North Rhine-Westphalia
Ruhr industrial belt manufacturers outsource security operations to managed detection providers due to chronic analyst shortages. EU NIS2 Directive compliance deadlines accelerate automated response module procurement among energy utilities in Essen and Dortmund. Düsseldorf's insurance sector commands premium pricing for threat-hunting subscriptions.
Baden-Württemberg
Precision engineering firms in Stuttgart and rural manufacturing zones favor subscription-based EDR procurement to convert capital expenditure into operational expenditure. BaFin operational resilience requirements extend to captive finance arms of automotive groups headquartered in the region. Heilbronn's Mittelstand clusters rely on value-added resellers for tier-one alert triage.
Hesse
Frankfurt's financial institutions operate under the strictest regulatory pressure, with eighteen-month refresh cycles mandated by BaFin cyber-resilience rules. The city anchors demand for automated containment playbooks and managed threat-hunting services. Wiesbaden's federal agencies require Common Criteria certification as a baseline eligibility filter for endpoint security tenders.
Berlin-Brandenburg
Startup density in Berlin drives experimentation with extended detection and response platforms that consolidate firewall, identity, and cloud workload telemetry. Potsdam's public-sector research institutes pilot AI-powered behavioral analysis for predictive threat identification. The region's cybersecurity talent concentration supports vendor R&D operations and kernel-level telemetry development.
Germany Endpoint Detection and Response Market Competitive Landscape
Listed leaders compete with private specialists across certification timelines and managed service delivery. Consolidation pressures favor vendors with completed Common Criteria evaluations, while fragmentation persists in the mid-market where regional value-added resellers wrap localization services around imported platforms. Three archetypes dominate: cloud-native platform providers with kernel-level telemetry expertise, legacy security vendors extending firewall relationships into endpoint coverage, and managed detection specialists serving analyst-constrained manufacturers. M&A activity targets Israeli behavioral analytics boutiques, and strategic partnerships with German systems integrators accelerate federal procurement access.
Within the cloud-native tier, CrowdStrike Holdings and SentinelOne exemplify architectures that reduce endpoint resource consumption for industrial deployments. Microsoft Corporation anchors enterprise accounts through identity platform integration, while Palo Alto Networks occupies a position extending network security relationships into consolidated XDR stacks. G Data CyberDefense represents the regional specialist archetype, leveraging BSI proximity for certification velocity and public-sector eligibility.
| Leading Market Players |
|---|
| CrowdStrike Holdings |
| Microsoft Corporation |
| Palo Alto Networks |
| Trend Micro |
| Fortinet |
| Cisco Systems |
| Check Point Software Technologies |
| G Data CyberDefense |
| SentinelOne |
| Others |
Pricing and Supply Chain Analysis
Cloud-native agent architectures replacing on-premises security stacks simultaneously redistribute procurement geography toward Bavarian technology corridors and compress pricing premiums for legacy hardware-dependent vendors. German Mittelstand manufacturers now source endpoint protection through subscription models that eliminate capital expenditure treatment, forcing established antivirus suppliers into margin erosion.
Pricing Analysis
Industrial OEM buyers anchor a subscription-based pricing structure where SaaS-tiered models dominate procurement conversations. Three-tier pricing separates BaFin-mandated financial services deployments from standard enterprise bundles and economy-tier SME offerings. Price differentiation rests on Common Criteria certification grade and managed detection service bundling. Cost compression in the economy tier is intensifying because value-added resellers absorb tier-one alert triage. Municipal healthcare sectors exhibit highest price sensitivity; Frankfurt financial institutions show least.
Supply Chain Analysis
Inventory cycles for kernel telemetry modules extend fourteen to eighteen months due to Common Criteria evaluation timelines. Supply concentrates in Israel, the United States, and Germany for behavioral analytics engines and driver development expertise. Raw material dependencies include Windows kernel development kits, Linux driver frameworks, and cloud infrastructure APIs. Single-source vulnerability sits with Israeli boutiques specializing in heuristic tuning. Distribution runs through Frankfurt and Stuttgart value-added resellers serving Mittelstand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German EDR procurement is consolidating around BaFin-regulated financial institutions and cloud-migrating Bavarian technology firms, shifting buyer power toward sophisticated procurement teams with certification requirements.
For Market Incumbents: Fortify federal procurement eligibility by accelerating BSI IT-Grundschutz certification timelines before pending cloud-security criteria publish. Deepen vertical integration into managed detection services to capture margin from Ruhr industrial belt manufacturers lacking internal SOC capacity. Kernel-level telemetry expertise scarcity in Berlin-Brandenburg threatens platform stability. For New Entrants and Emerging Players: Lead with agent-light architectures targeting Ingolstadt automotive suppliers monitoring PLC and SCADA networks. Operational technology convergence in chemical plants represents the most penetrable segment. Partner with Düsseldorf insurance sector resellers for threat-hunting subscription distribution. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Israeli behavioral analytics boutiques holding heuristic calibration IP. Five-to-ten-year viability hinges on automated response module adoption among EU NIS2 Directive critical infrastructure operators. Monitor BSI cloud-security certification publication as inflection signal for compliance-driven procurement waves.| Strategic Initiative | Industry Significance |
|---|---|
| Common Criteria Certification Acceleration | Pre-positions vendors for BSI federal procurement eligibility before cloud criteria publish. |
| Managed Detection Service Launch | Captures recurring revenue from Ruhr belt manufacturers with chronic analyst shortages. |
| Operational Technology Extension | Opens PLC and SCADA coverage in automotive plants underserved by IT-centric vendors. |
| Kernel Telemetry Talent Acquisition | Secures scarce driver developers in Berlin-Brandenburg for platform stability. |
| Value-Added Reseller Partnership | Penetrates Stuttgart Mittelstand clusters through localized tier-one alert triage. |
Research Methodology
The analysis maps cloud-native, on-premises, hybrid, and managed service deployment models, each validated through CISO interviews, SOC operations directors, federal procurement officers, and value-added reseller principals. Primary fieldwork combined with BSI certification records, BaFin regulatory filings, hyperscaler capex disclosures, and customs data on security software imports. Bottom-up endpoint deployment estimates triangulated against top-down IT security spending benchmarks.
Consistency checks validated volume and value outputs against external procurement databases and federal tender records. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical regulatory intensity, integration complexity, and regional technology adoption patterns. CAGRs derived from elasticity-adjusted replacement cycle analysis. Forecast inputs incorporated BaFin refresh cycle mandates and EU NIS2 Directive compliance deadlines.
The analysis sits within stated boundaries; outcomes outside BSI certification timeline assumptions or cloud migration velocity parameters would require recalibration. Forecasts reflect documented assumptions about regulatory enforcement intensity and vendor certification completion rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Cyber Security in Energy Market
Cybersecurity
Hungary Cybersecurity Market
Cybersecurity
CDN Security Market
Cybersecurity
Global File Integrity Monitoring Market
Cybersecurity
Global Automated Breach and Attack Simulation (BAS) Market
Cybersecurity
Global Information Security Consulting Market
Cybersecurity
Oman Cybersecurity Market
Cybersecurity
Cloud-Based Database Security Market
Cybersecurity
Secure Socket Layer (SSL) Certification Market
Cybersecurity
Enterprise Mobility Security Market
Cybersecurity
Nigeria Cybersecurity Market
Cybersecurity
Global Managed Detection and Response (MDR) Market
Cybersecurity
Asia Pacific IoT Security Market
Cybersecurity
Mexico Cybersecurity Market
Cybersecurity
Cloud Security in Banking Market
Cybersecurity
France Cybersecurity Market