
 Global Deep Packet Inspection (DPI) Market | 2026-2036
Global Deep Packet Inspection (DPI) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Deep Packet Inspection (DPI) Market Foresight
Platform licensing revenue is tilting from perpetual hardware sales toward subscription-based cloud deployments across the DPI landscape. Cisco Systems leverages its installed base of routing equipment to bundle DPI modules at the network edge. Palo Alto Networks differentiates through tight integration of DPI with next-generation firewall policy engines. Juniper Networks anchors its position in carrier-grade environments where throughput demands exceed 400 Gbps per node.
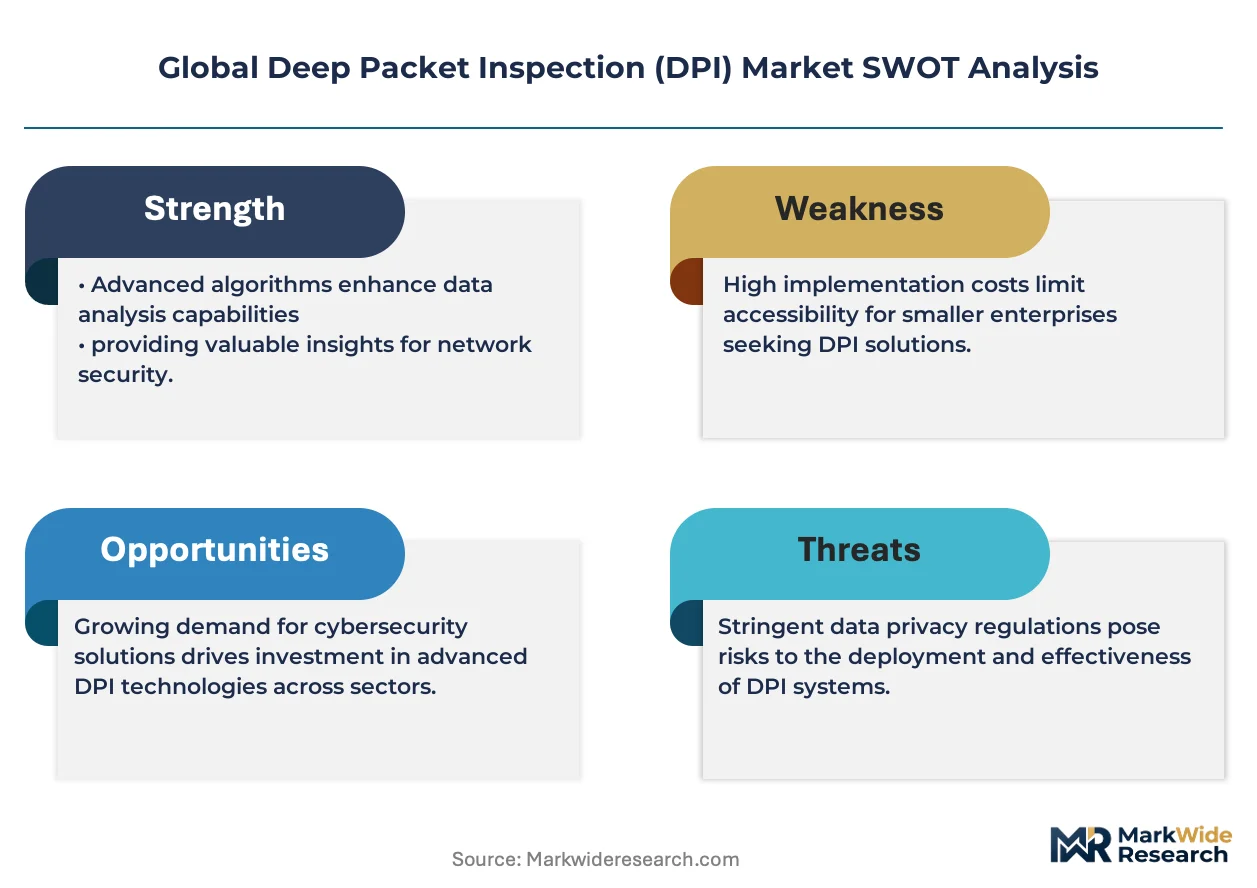
Deep packet inspection constitutes a network traffic analysis methodology that examines both header and payload data at the application layer, operating at line rates up to 800 Gbps through specialized ASIC and FPGA hardware acceleration. Its primary commercial purpose centers on identifying protocols, detecting malware signatures, and enforcing quality-of-service policies in real time. Cloud-based deployment now captures the fastest expansion as enterprises abandon capex-heavy appliance models, while network security solutions command the dominant margin pool due to persistent threat escalation. Internet service providers represent the most mature application vertical, whereas government agencies exhibit the steepest procurement acceleration driven by sovereign data protection mandates.
The Federal Communications Commission shapes US carrier obligations through net neutrality enforcement and lawful intercept requirements, while the European Telecommunications Standards Institute mandates DPI interoperability benchmarks under its cybersecurity certification frameworks. China's Ministry of Industry and Information Technology imposes domestic encryption inspection standards that foreign vendors must satisfy for network equipment approval. Stakeholders must monitor divergence between Western encryption-backdoor debates and Asian data-sovereignty regimes, as this regulatory fragmentation will determine which product architectures achieve scalable deployment.

Market Dynamics
The migration from on-premises appliances to cloud-native DPI architectures constitutes the dominant structural force reshaping competitive positioning across telecommunications and enterprise security sectors.
Growth Catalysts
- 5G Network Rollouts:Telecommunications carriers in Germany and South Korea are deploying carrier-grade DPI at network edges to manage quality-of-service enforcement and slice isolation.
- EU AI Act Compliance:European data centers face mandatory infrastructure upgrades for automated traffic classification and audit logging of AI-driven network decisions.
- Industrial Automation Demand:German manufacturing clusters are procuring DPI solutions for critical infrastructure protection against targeted intrusion attempts.
Market Restraints
- ASIC Supply Concentration:Taiwan-based foundries control advanced semiconductor fabrication for 800 Gbps packet processing engines, creating single-source vulnerability.
- Encryption Proliferation:TLS 1.3 and QUIC protocol adoption limits payload visibility, forcing vendors toward resource-intensive TLS inspection architectures.
- GDPR Inspection Friction:European privacy regulators impose strict proportionality tests on DPI deployment depth, constraining lawful intercept scope.
Strategic Opportunities
- India Digital Infrastructure:TRAI mandates for network security compliance create procurement windows for DPI vendors serving BharatNet and 5G spectrum holders.
- Zero Trust Convergence:Integration of DPI telemetry with identity-aware proxies enables microsegmentation policy enforcement in financial services environments.
- Managed Security Services:Channel partners in Brazil and Mexico are bundling DPI-as-a-service for mid-market enterprises lacking internal security operations centers.
Industry Challenges
- Embedded Systems Expertise Scarcity:Vendors struggle to recruit firmware engineers capable of optimizing FPGA bitstreams for sub-microsecond packet classification latency.
- Multi-Vendor Interoperability:Integration with legacy MPLS cores and SD-WAN overlays demands custom protocol adaptation layers that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Deep Packet Inspection (DPI) Market |
| Market Size in 2026 | $32.4 Billion |
| Market Size in 2035 | $110.46 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtualized Solution Type: Network Security, Traffic Management, Data Analytics, Application Monitoring, Compliance Enforcement Application: Internet Service Providers, Content Delivery Networks, Data Centers, Enterprise Networks, Government Agencies End User Industry: Telecommunications, Financial Services, Education, Media & Entertainment, Public Sector |
| Companies Covered | Cisco Systems, Palo Alto Networks, Juniper Networks, Sandvine, Huawei Technologies, Check Point Software Technologies, NETSCOUT Systems, Allot Communications, Enea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Deep Packet Inspection (DPI) Market Shifts & Advancements
Three convergent developments are compressing traditional hardware refresh cycles and redistributing value capture toward software-defined inspection layers and sovereign cloud architectures.
Hardware-accelerated DPI is hybridizing with containerized software stacks to enable elastic traffic processing across distributed edge locations. Telecommunications operators in Japan and Australia are piloting Kubernetes-orchestrated inspection pods that scale horizontally during peak demand windows. This architecture is compressing capital deployment timelines from multi-year appliance procurement to monthly subscription commitments.
The EU AI Act mandates algorithmic transparency for automated network traffic decisions, forcing vendors to implement explainable classification models. Industrial consequence includes mandatory documentation of training data provenance and decision boundary logging. German automotive and chemical manufacturers are most affected, with procurement teams now requiring AI audit trails as standard contract terms.
Enterprise buyers are unbundling after-sales support from perpetual license agreements, preferring outcome-based service level commitments tied to threat detection accuracy metrics. Systems integrators in Singapore and the United Arab Emirates are capturing margin by offering guaranteed mean-time-to-detection contracts. This pattern is most visible in financial services verticals where regulatory scrutiny of security operations center performance intensifies.
Global Deep Packet Inspection (DPI) Market Segmentation
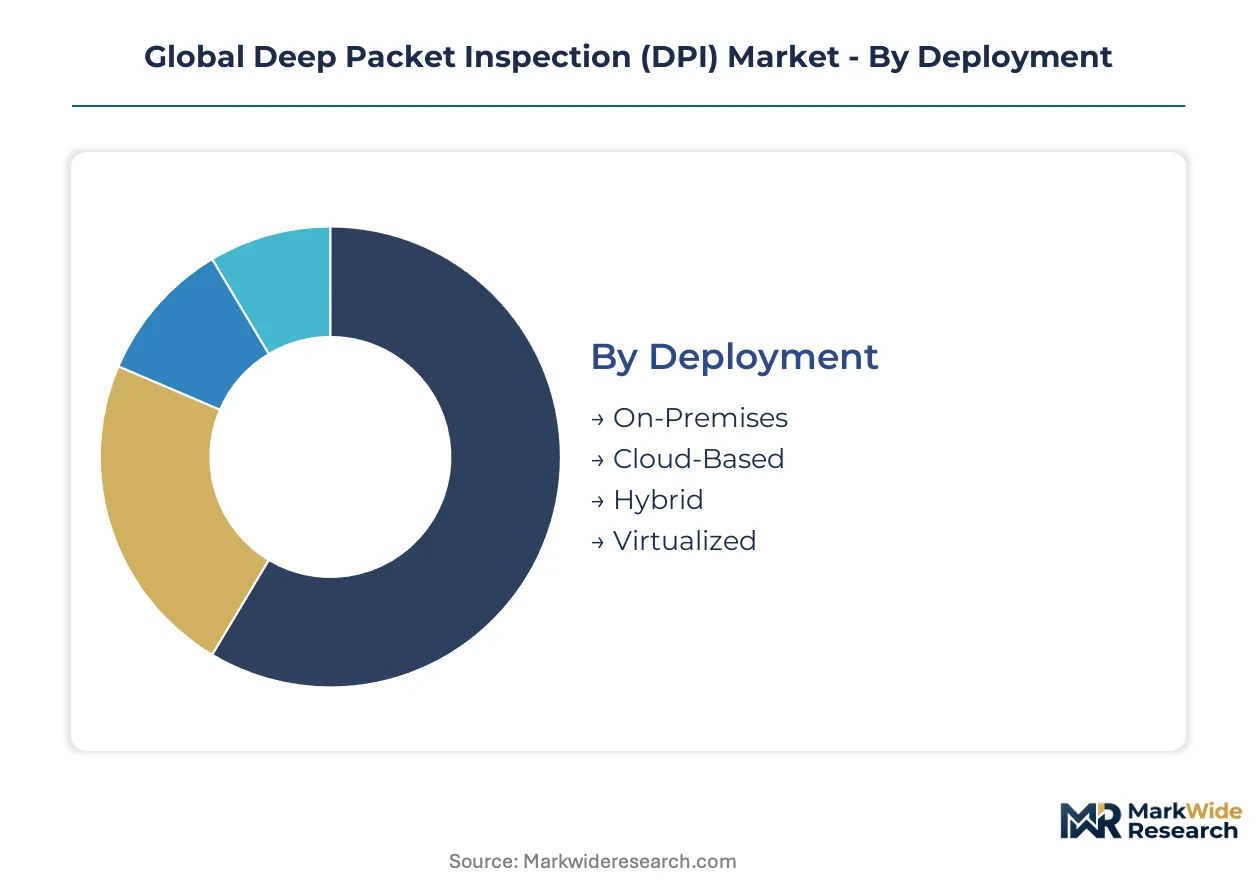
DPI procurement patterns diverge sharply across deployment models and buyer sophistication levels. Solution architecture choices determine whether vendors capture recurring service revenue or one-time hardware margins.
Deployment:
After-sales service intensity varies dramatically by deployment topology, with cloud-native architectures demanding continuous telemetry tuning and on-premises installations requiring periodic firmware validation cycles.
- Cloud-Based:Containerized inspection pods orchestrate through Kubernetes clusters, enabling horizontal scaling during traffic spikes. German automotive manufacturers and Australian telecommunications operators are migrating fastest to this model to eliminate datacenter capex commitments.
- On-Premises:Dedicated appliance deployments with ASIC-accelerated processing remain preferred where sub-microsecond latency is non-negotiable. South Korean carriers maintain substantial on-premises footprints for 5G network slicing enforcement.
- Hybrid:Split architectures process sensitive payloads locally while routing bulk analytics to sovereign cloud instances.
- Virtualized:Software-defined instances running on commodity x86 servers serve mid-market enterprises with moderate throughput requirements.
On-Premises holds the largest share; momentum sits with Cloud-Based.
Solution Type:
Margin concentration follows threat escalation severity, with security-adjacent functions commanding premium pricing over operational optimization tools.
- Network Security:Malware signature detection and intrusion prevention systems integrate with SIEM platforms for correlated threat response. Financial services institutions in Singapore and the United Arab Emirates mandate these capabilities for regulatory compliance.
- Traffic Management:Quality-of-service enforcement and bandwidth shaping prioritize latency-sensitive applications. Telecommunications carriers deploy these solutions at 5G network edges to guarantee slice isolation.
- Data Analytics:Behavioral pattern extraction from packet flows supports capacity planning and anomaly detection.
- Application Monitoring:Layer-7 visibility identifies shadow IT and unsanctioned cloud service consumption.
- Compliance Enforcement:Automated logging and audit trail generation satisfy GDPR and EU AI Act documentation requirements.
Network Security generates the dominant margin pool; Data Analytics is climbing the fastest as AI-driven classification demands intensify.
Application:
Procurement sophistication scales with infrastructure criticality, with carrier-grade deployments demanding carrier-grade throughput guarantees unavailable to enterprise buyers.
- Internet Service Providers:Mature vertical with established procurement frameworks and standardized interoperability testing. Brazilian and Mexican operators are refreshing edge infrastructure to support fiber expansion.
- Government Agencies:Sovereign data protection mandates accelerate procurement across defense and intelligence sectors. Steepest expansion trajectory reflects classified network segmentation requirements.
- Content Delivery Networks:Edge cache nodes deploy lightweight inspection to optimize cache hit ratios.
- Data Centers:East-west traffic visibility prevents lateral movement in multi-tenant environments.
- Enterprise Networks:Distributed office footprints drive demand for consolidated policy management consoles.
Internet Service Providers represent the most mature application; Government Agencies exhibit the steepest procurement acceleration.
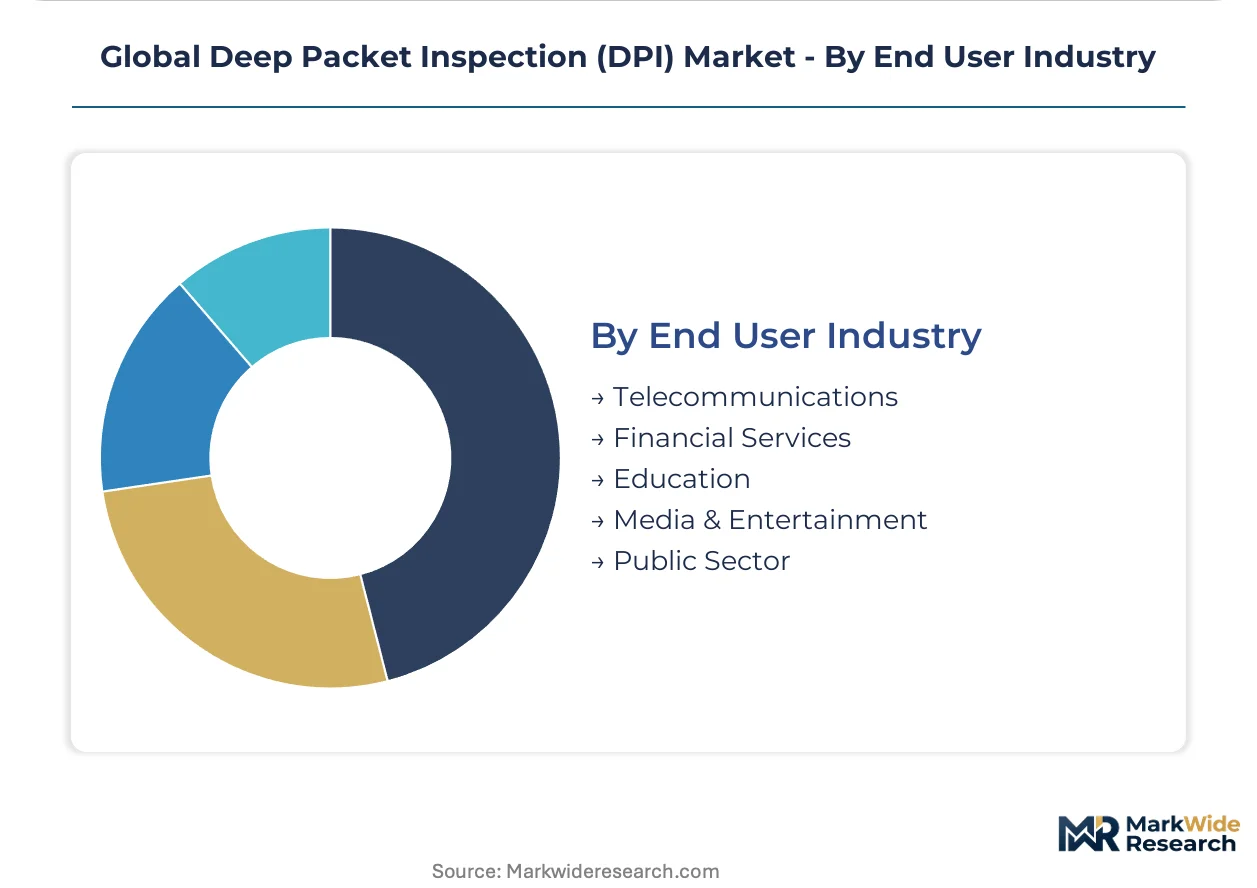
End User Industry:
Customer concentration patterns reflect regulatory exposure and infrastructure digitization maturity across vertical sectors.
- Telecommunications:5G rollout timelines dictate procurement cadence, with German and South Korean carriers leading edge deployment density. This vertical anchors absolute revenue volume through multi-year framework agreements.
- Financial Services:Zero trust architecture mandates drive integration with identity-aware proxies. Singaporean banks and UAE wealth managers specify guaranteed mean-time-to-detection contracts.
- Public Sector:Critical infrastructure protection programs fund inspection deployment at utility and transportation networks.
- Media & Entertainment:Content piracy enforcement and digital rights management integration shape solution requirements.
- Education:Campus network visibility supports acceptable use policy enforcement with limited budget elasticity.
Telecommunications commands absolute revenue volume; Financial Services is gaining share fastest through outcome-based contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation clusters deploy DPI for critical infrastructure protection, while South Korean carriers prioritize 5G network slicing enforcement—a consumption-mix differential that separates European security-driven procurement from Asian throughput-centric deployment patterns.
United States
FCC net neutrality rulings and lawful intercept mandates drive carrier-grade infrastructure refresh cycles. The Federal Communications Commission enforces interoperability benchmarks that shape vendor qualification protocols. Silicon Valley security operations centers and Wall Street financial services clusters in New York anchor enterprise demand for zero-trust-integrated inspection.
Germany
Automotive and chemical manufacturers in Baden-Württemberg and North Rhine-Westphalia mandate AI audit trails for automated traffic classification. EU AI Act compliance deadlines force infrastructure upgrades across Frankfurt and Munich data center corridors. Industrial automation clusters along the Rhine-Ruhr axis sustain procurement of sub-microsecond latency inspection engines.
South Korea
Seoul Capital Area carriers deploy 800 Gbps nodes for 5G standalone network slicing isolation. The national telecommunications regulator mandates domestic encryption inspection standards for equipment approval. Busan-Ulsan maritime logistics hubs and Daegu-Gyeongbuk manufacturing belts drive edge-computing inspection pod deployment.
India
TRAI network security compliance rules create procurement windows for BharatNet fiber expansion and 5G spectrum holders. The Telecom Regulatory Authority of India imposes data localization requirements that favor sovereign cloud inspection architectures. Mumbai financial services institutions and Bangalore technology campuses anchor enterprise adoption of managed security service bundles.
Japan
Tokyo-Yokohama telecommunications operators pilot Kubernetes-orchestrated inspection pods for elastic traffic scaling. METI cybersecurity frameworks mandate critical infrastructure protection standards for utility and transportation networks. Osaka-Kobe manufacturing clusters and Nagoya automotive hubs integrate DPI with operational technology security stacks.
Global Deep Packet Inspection (DPI) Market Competitive Landscape
Capability concentration sits with specialized semiconductor-accelerated vendors; scale advantage sits with integrated networking equipment suppliers. The market structures around three tiers: carrier-grade throughput specialists, enterprise security platform providers, and cloud-native software vendors. Dominant competitive moves include strategic bundling of inspection modules with adjacent networking infrastructure and geographic expansion through channel partner ecosystems in emerging digital infrastructure markets.
Within the carrier-grade tier, Cisco Systems and Juniper Networks occupy positions defined by installed base leverage and framework agreement anchoring. Palo Alto Networks exemplifies the enterprise security platform archetype, sitting within a positioning that emphasizes policy engine integration. Huawei Technologies represents the vertically integrated challenger model, though its market access varies by jurisdiction.
| Leading Market Players |
|---|
| Cisco Systems |
| Palo Alto Networks |
| Juniper Networks |
| Sandvine |
| Huawei Technologies |
| Check Point Software Technologies |
| NETSCOUT Systems |
| Allot Communications |
| Enea |
| Others |
Supply & Pricing Matrix
The Taiwan Strait maritime corridor anchors semiconductor logistics costs for 800 Gbps packet processing engines, concentrating supply-side pricing power among foundry operators while forcing DPI vendors toward subscription models that buffer hardware margin volatility.
Pricing Analysis
Long-term framework agreements dominate carrier-grade procurement, with telecommunications operators in Germany and South Korea locking in multi-year commitments for ASIC-accelerated appliances. Pricing stratifies across premium carrier-grade, standard enterprise, and economy virtualized tiers based on throughput guarantees and latency specifications. Cost compression in the economy tier intensifies as cloud-native alternatives displace capex-heavy deployments. Mid-market enterprises exhibit highest price sensitivity; sovereign cloud providers show lowest.
Supply Chain Analysis
US export controls on advanced semiconductor manufacturing equipment constrain wafer fabrication capacity expansion for packet processing ASICs, limiting supply elasticity. Taiwan, South Korea, and the United States anchor advanced logic chip production. Raw material dependencies span silicon wafers, high-purity neon gas, and specialized photoresist chemistries. Single-source vulnerability concentrates at Taiwan-based foundries. Distribution runs through authorized channel partners serving carrier and enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DPI market sits in early-cycle expansion as 5G standalone deployments and EU AI Act compliance deadlines accelerate infrastructure refresh timelines beyond historical replacement cadences.
For Market Incumbents: Harden carrier-grade positioning through captive supply arrangements for 800 Gbps ASIC capacity, insulating against Taiwan foundry allocation constraints. Deepen framework agreement anchoring with German and South Korean telecommunications operators before cloud-native alternatives mature. Prioritize FPGA firmware engineering recruitment to address sub-microsecond latency optimization scarcity.
For New Entrants and Emerging Players: Build out sovereign cloud inspection architectures targeting Indian TRAI compliance mandates and BharatNet fiber expansion procurement windows. The mid-market enterprise segment in Brazil and Mexico offers lowest competitive density for DPI-as-a-service bundles. Partner with managed security service providers to bypass direct sales force requirements.
For Investors and Strategic Acquirers: Containerized software vendors with Kubernetes-native inspection stacks represent the highest-conviction acquisition archetype for platform consolidation plays. Long-term viability hinges on elastic scaling capabilities displacing hardware-bound competitors. Watch for TRAI enforcement acceleration in India as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Supply Agreement | Captive wafer capacity at Taiwan foundries secures 800 Gbps throughput guarantees for carrier bids. |
| Kubernetes-Native Platform Launch | Containerized inspection pods enable horizontal scaling for Australian and Japanese telecommunications pilots. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation unlocks German automotive and chemical manufacturer procurement. |
| Channel Partner Expansion | Local MSSP relationships in Brazil and Mexico accelerate mid-market enterprise penetration without direct sales investment. |
| Zero Trust Architecture Integration | SIEM platform partnerships with Singaporean banks enable outcome-based threat detection contracting. |
Research Methodology
The analysis maps cloud-native, on-premises, hybrid, and virtualized deployment topologies, each validated through telecommunications procurement officers, enterprise CISOs, carrier network architects, and semiconductor supply chain managers. Primary fieldwork combined structured interviews with secondary triangulation across FCC filings, ETSI cybersecurity certification databases, TRAI regulatory circulars, and hyperscaler capex disclosures. Bottom-up segment sizing and top-down macro anchoring converged through iterative reconciliation.
Assumptions held 5G rollout timelines, EU AI Act enforcement schedules, and encryption protocol adoption curves within baseline trajectories across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution type, application vertical, end-user industry, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to infrastructure investment cycles and compliance deadline clustering. Forecast inputs incorporated foundry capacity expansion schedules and sovereign data protection mandate proliferation rates.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by cloud hyperscalers would shift outcomes. Material shifts in Taiwan Strait logistics availability or EU AI Act enforcement severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Europe Digital Forensics Market
Cybersecurity
Vietnam Cybersecurity Market
Cybersecurity
Global Patch Management Market
Cybersecurity
Greece Cybersecurity Market
Cybersecurity
Canada Ransomware Protection Market
Cybersecurity
Mexico Cybersecurity Market
Cybersecurity
Denmark Cybersecurity Market
Cybersecurity
Endpoint Protection Platforms (EPP) Market
Cybersecurity
Belgium Cybersecurity Market
Cybersecurity
Bangladesh Cybersecurity Market
Cybersecurity
Network Traffic Analysis Solutions Market
Cybersecurity
Cloud Access Security Broker Market
Cybersecurity
Retail Cybersecurity Market
Cybersecurity
Germany Ransomware Protection Market
Cybersecurity
Cloud Endpoint Protection Market
Cybersecurity
Wireless Network Security Market