
 Global Network Security Firewall Market | 2026-2036
Global Network Security Firewall Market Size, Share, and Industry Trends Forecast 2026-2036
Global Network Security Firewall Market Foresight
Managed firewall services revenue is rewriting margin economics across the vendor landscape. Palo Alto Networks leverages cloud-native architecture to capture recurring subscription streams. Fortinet anchors its position through proprietary ASIC design that compresses hardware costs. Check Point Software Technologies differentiates via consolidated security platform bundling that reduces enterprise procurement complexity.
A network security firewall inspects traffic against rule-based policies using stateful inspection, deep packet inspection, or proxy-based filtering to enforce access control between trusted and untrusted network zones. The device or software processes packets at Layer 3 through Layer 7 of the OSI model, with throughput measured in gigabits per second and latency tolerance often sub-millisecond for financial trading environments. Next-generation firewall deployments now dominate product type discussions as application-aware inspection replaces port-based rules. Cloud-based deployment configurations expand fastest among segments, though on-premise installations retain stubborn presence in regulated data center protection applications where data residency requirements apply.
FCC guidelines shape telecommunications infrastructure security mandates in the United States, while the EU AI Act and GDPR impose algorithmic transparency and data handling standards on automated threat detection systems deployed across Europe. NIS2 Directive compliance deadlines force critical infrastructure operators to upgrade perimeter defenses or face operational continuity penalties. Stakeholders must monitor how fragmented national encryption policies affect cross-border firewall rule synchronization before committing to centralized security management architectures.
Market Dynamics
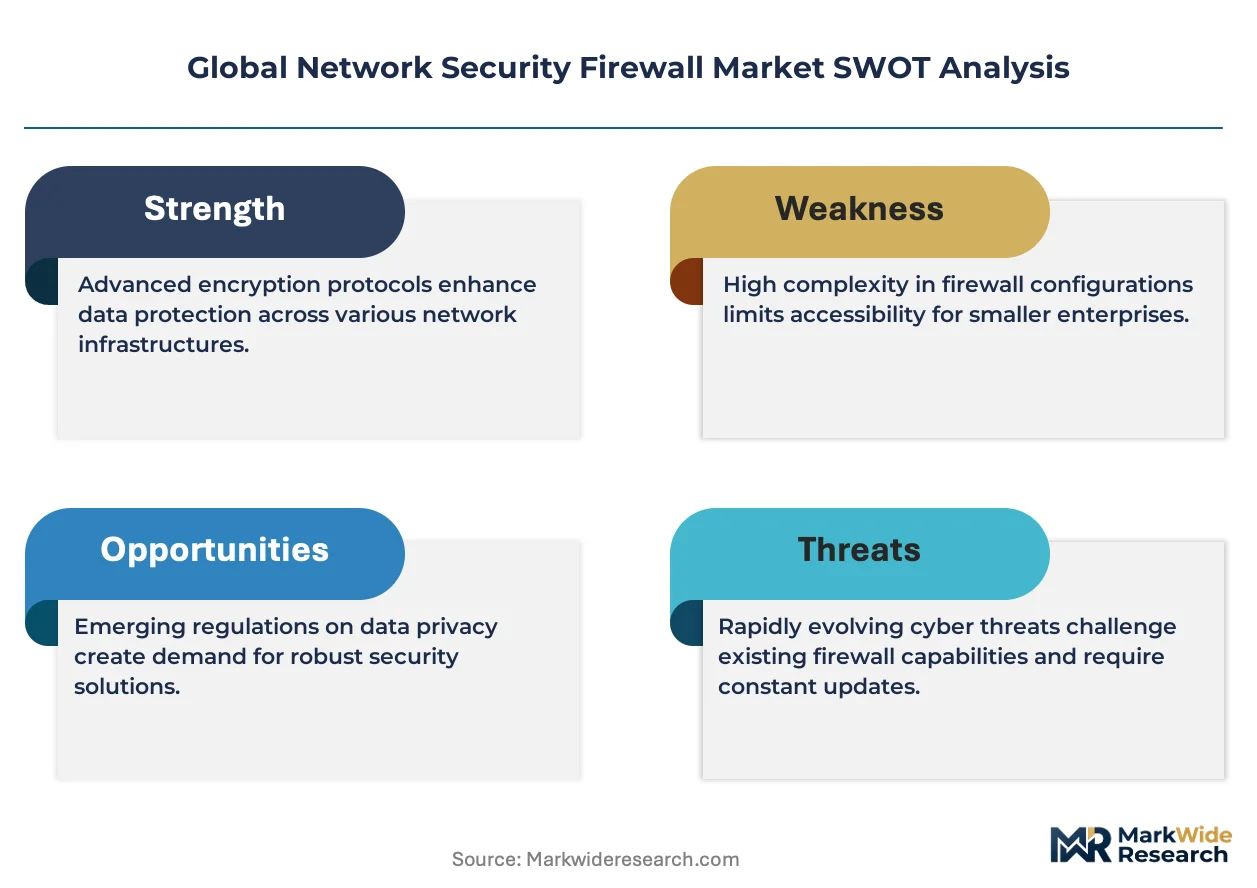
The migration from port-based to application-aware inspection is compressing hardware refresh cycles while expanding software-defined perimeter architectures across enterprise data centers.
Growth Catalysts
- EU NIS2 Directive:Critical infrastructure operators in Germany and France face mandated perimeter defense upgrades by compliance deadlines, forcing immediate procurement of next-generation inspection platforms.
- 5G core network buildouts:India's telecom infrastructure expansion requires scalable session border controllers with embedded firewall functions to secure subscriber traffic at network edge nodes.
- Deep packet inspection:Financial trading venues in the United States deploy sub-millisecond latency firewalls to protect high-frequency transaction rails without throughput degradation.
Market Restraints
- Proprietary ASIC dependency:Custom silicon design cycles stretch 18-24 months, constraining vendor ability to match software-defined competitor feature velocity.
- Encryption policy fragmentation:Divergent national requirements for traffic inspection across France, Germany, and India complicate centralized security policy orchestration.
- Cloud-native substitution:Containerized microsegmentation and service mesh architectures displace traditional perimeter appliances in greenfield Kubernetes deployments.
Strategic Opportunities
- Sovereign cloud mandates:Germany's Gaia-X framework and India's MeghRaj initiative create captive demand for data-resident firewall deployments in government cloud zones.
- Zero trust convergence:Integration of software-defined wide area networking with identity-aware proxy architectures opens unified vendor stack opportunities in enterprise branch transformation.
- Managed security services:Mid-market enterprises in the United States outsource firewall operations to specialized providers, shifting revenue from perpetual licenses to recurring monitoring contracts.
Industry Challenges
- Threat intelligence analyst scarcity:Vendors and enterprises compete for personnel capable of tuning behavioral detection rules against advanced persistent threat signatures.
- Legacy mainframe integration:Financial institutions in the United States struggle to overlay modern inspection policies atop decades-old transaction processing networks without service interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Network Security Firewall Market |
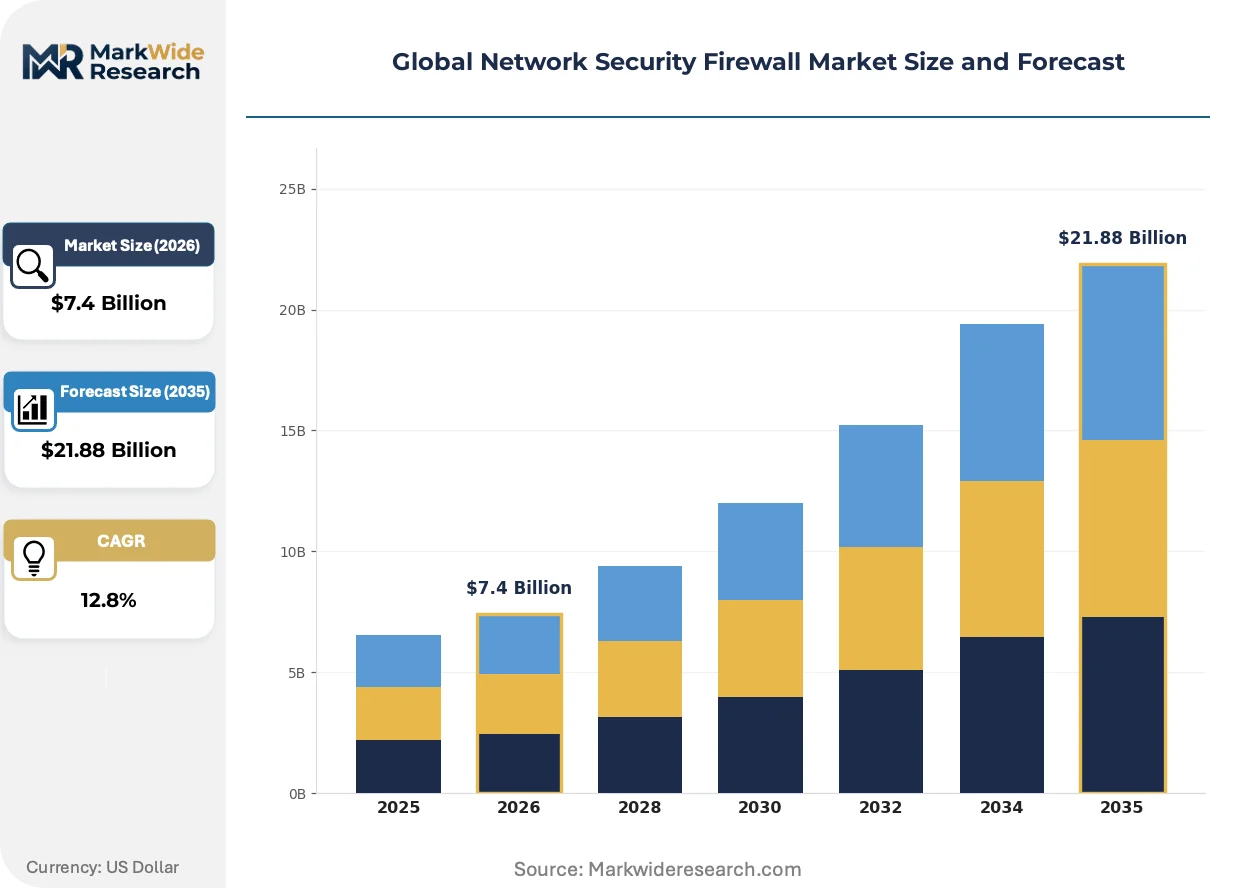
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $21.88 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid Cloud, Managed Firewall, Virtual Firewall Product Type: Stateful Inspection, Next-Generation Firewall, Proxy Firewall, Unified Threat Management, Application Layer Firewall Application: Enterprise Security, Data Center Protection, Government Infrastructure, Telecommunications, Educational Institutions End User: Financial Institutions, E-Commerce Firms, Cloud Service Providers, IT Service Companies, Research Organizations |
| Companies Covered | Palo Alto Networks, Fortinet, Cisco Systems, Check Point Software Technologies, Juniper Networks, SonicWall, WatchGuard Technologies, Barracuda Networks, Sophos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Network Security Firewall Market Shifts & Advancements
Firewall architecture is bifurcating between cloud-native distributed enforcement and hardened on-premise appliances, with inspection logic migrating upward in the software stack.
Artificial intelligence-driven behavioral analysis is collapsing the distinction between signature-based and anomaly detection methods in next-generation platforms. Large financial institutions in the United States deploy self-tuning engines that reduce false-positive rates without human rule maintenance. This compression of detection paradigms enables single-vendor consolidation of previously separate intrusion prevention and firewall budgets.
The EU AI Act imposes algorithmic transparency requirements on automated threat detection systems deployed across European critical infrastructure. Operators must document decision logic for machine-learning classification of malicious traffic patterns. German energy utilities and French healthcare networks are re-engineering inspection pipelines to maintain audit trails for regulatory examination.
Consumption-based licensing models are displacing perpetual appliance purchases among mid-market enterprises. United States healthcare systems and Indian e-commerce platforms prefer throughput-metered subscriptions that scale with cloud workload expansion. This shift transfers capital expenditure risk to vendors while accelerating replacement cycles for hardware-bound competitors.
Global Network Security Firewall Market Segmentation
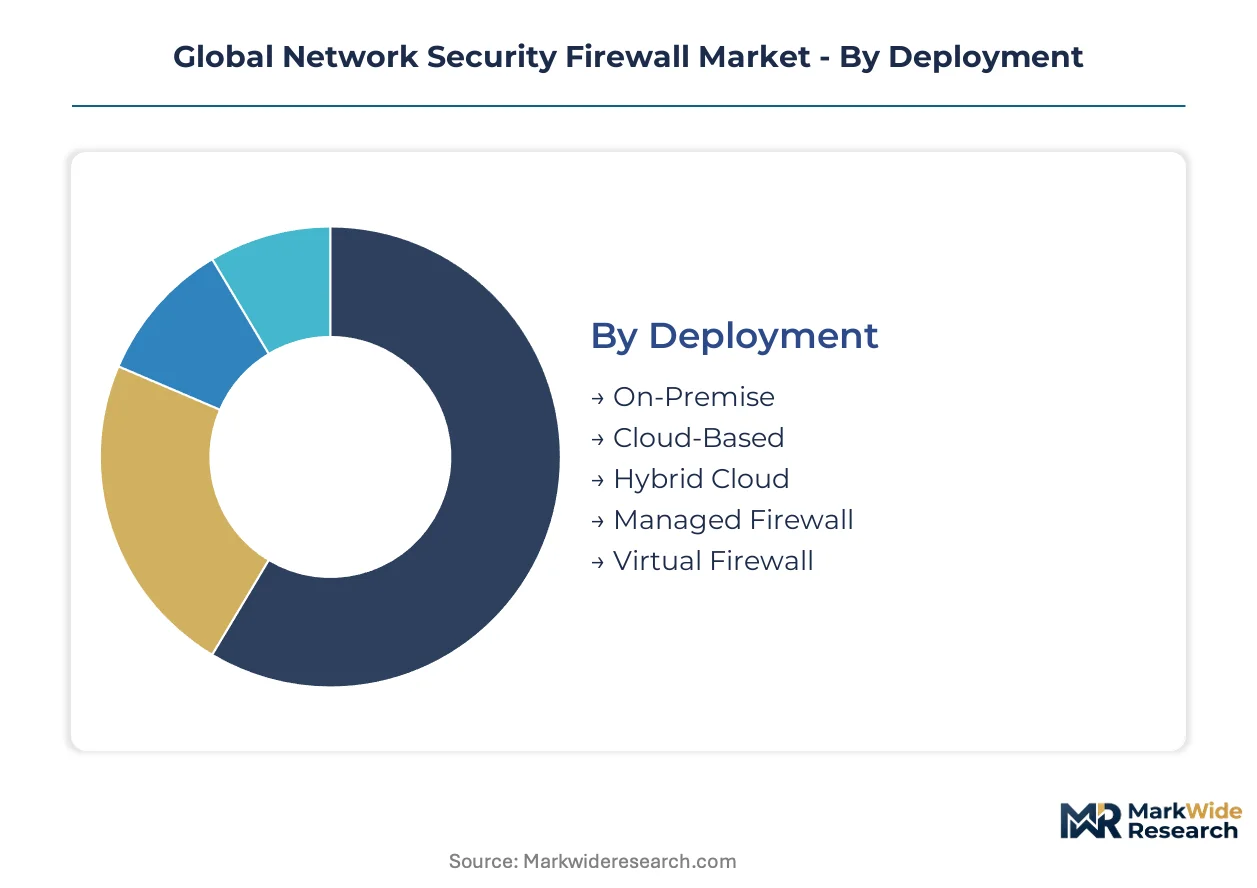
Firewall procurement patterns diverge sharply across deployment architectures and buyer sophistication levels. Segmentation reveals where hardware refresh cycles compress against software-defined substitution, and which verticals absorb premium inspection capabilities.
Deployment:
Cost tier differentiation separates capital-intensive appliance buyers from operational-expenditure cloud adopters.
- Cloud-Based:Elastic throughput scaling matches consumption to actual traffic volumes without stranded capacity. United States healthcare systems and Indian e-commerce platforms prefer throughput-metered subscriptions that transfer capital expenditure risk to vendors.
- Managed Firewall:Specialized providers assume operational burden for rule tuning, threat feed integration, and compliance reporting. Mid-market enterprises in the United States outsource firewall operations, shifting revenue from perpetual licenses to recurring monitoring contracts.
- On-Premise:Regulated data centers in Germany retain hardware appliances where data residency requirements apply.
- Hybrid Cloud:Split enforcement across private infrastructure and public cloud zones.
- Virtual Firewall:Software instances deployable on commodity compute without dedicated hardware.
On-Premise holds installed capacity. Cloud-Based is rotating up the share rankings.
Product Type:
Application sophistication determines whether port-based rules suffice or deep packet inspection becomes mandatory.
- Next-Generation Firewall:Application-aware inspection replaces port-based rules with identity-contextualized policy enforcement. Large financial institutions in the United States deploy self-tuning engines that reduce false-positive rates without human rule maintenance.
- Stateful Inspection:Connection-tracking logic at Layer 3-4 remains embedded in high-throughput telecommunications infrastructure. India's 5G core network buildouts require scalable session border controllers with embedded firewall functions.
- Proxy Firewall:Terminates connections at the application layer for content filtering.
- Unified Threat Management:Consolidated appliance bundling reduces procurement complexity for resource-constrained buyers.
- Application Layer Firewall:Granular control over specific protocols and content types.
Stateful Inspection maintains legacy dominance. Next-Generation Firewall commands the steepest expansion trajectory.
Application:
Volume concentration tracks where perimeter defense upgrades face regulatory compulsion versus discretionary security spending.
- Government Infrastructure:Sovereign cloud mandates in Germany's Gaia-X framework and India's MeghRaj initiative create captive demand for data-resident firewall deployments. Operators face mandated perimeter defense upgrades under EU NIS2 Directive compliance deadlines.
- Telecommunications:Subscriber traffic volumes at network edge nodes demand sub-millisecond latency enforcement. India's telecom infrastructure expansion requires scalable session border controllers with embedded firewall functions.
- Enterprise Security:Branch office transformation drives software-defined wide area networking integration.
- Data Center Protection:East-west traffic microsegmentation within facility boundaries.
- Educational Institutions:Budget-constrained procurement favoring consolidated security platforms.
Enterprise Security holds broadest deployment base. Government Infrastructure is gaining share fastest.
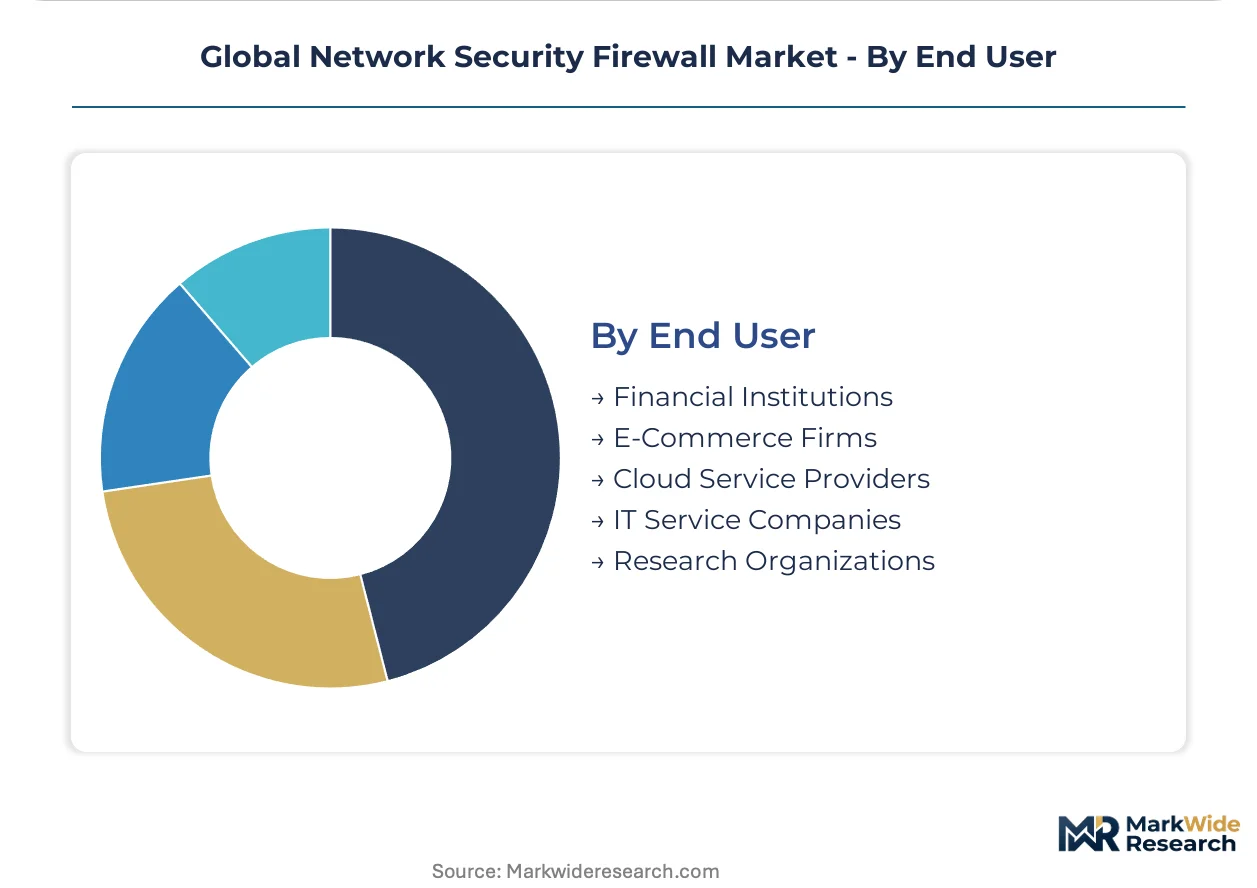
End User:
Customer type dictates whether procurement centers on compliance documentation, transaction velocity protection, or multi-tenant scalability.
- Financial Institutions:Deep packet inspection protects high-frequency transaction rails without throughput degradation. United States trading venues deploy sub-millisecond latency firewalls, though legacy mainframe integration complicates modern policy overlay.
- Cloud Service Providers:Multi-tenant architectures demand tenant-isolated enforcement with centralized orchestration. Consumption-based licensing models displace perpetual appliance purchases among hyperscale operators.
- E-Commerce Firms:Seasonal traffic spikes favor elastic scaling configurations.
- IT Service Companies:Managed security services bundling for downstream clients.
- Research Organizations:Academic pricing tiers and open-source integration requirements.
Financial Institutions anchor premium pricing tiers. Cloud Service Providers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Germany demonstrate the sharpest price elasticity contrasts, with Indian telecom operators prioritizing throughput-per-dollar metrics while German critical infrastructure operators absorb premium pricing for compliance-certified appliances. The United States sits at the midpoint, trading off latency performance against operational expenditure flexibility.
United States
Financial trading venues in New York and Chicago drive sub-millisecond latency requirements for high-frequency transaction protection. FCC guidelines shape telecommunications infrastructure security mandates nationwide. Silicon Valley cloud service providers are expanding consumption-based firewall licensing to match elastic workload scaling.
Germany
Energy utilities and automotive manufacturers face mandated perimeter defense upgrades under EU NIS2 Directive compliance deadlines. The Gaia-X sovereign cloud framework creates captive demand for data-resident firewall deployments in government cloud zones. Industrial clusters in Bavaria and Baden-Württemberg are re-engineering inspection pipelines to maintain AI Act audit trails.
India
Telecom infrastructure expansion requires scalable session border controllers with embedded firewall functions at network edge nodes. The MeghRaj government cloud initiative generates sovereign deployment requirements for public sector data centers. Bangalore and Hyderabad technology corridors are absorbing cloud-native firewall instances for e-commerce platform protection.
France
Healthcare networks and nuclear energy operators confront EU AI Act algorithmic transparency requirements for automated threat detection systems. ANSM and CNIL oversight extends to machine-learning classification audit trails in critical infrastructure. Paris and Lyon financial districts are consolidating previously separate intrusion prevention and firewall budgets under single-vendor platforms.
United Kingdom
Enterprise branch transformation drives software-defined wide area networking integration with identity-aware proxy architectures. Post-Brexit regulatory divergence from EU NIS2 creates procurement uncertainty for multinational infrastructure operators. London's financial services cluster maintains premium pricing tolerance for legacy mainframe overlay protection without service interruption.
Global Network Security Firewall Market Competitive Landscape
Capability concentration sits with specialized ASIC designers; scale advantage sits with cloud-native platform vendors. The market structures around three tiers: integrated security platform providers, hardware-optimized appliance manufacturers, and managed security service operators. Strategic moves center on subscription revenue migration and sovereign cloud certification acquisition.
Within the integrated platform tier, Palo Alto Networks and Check Point Software Technologies exemplify consolidated security bundling that reduces enterprise procurement complexity. Fortinet anchors the hardware-optimized tier through proprietary silicon design that compresses appliance costs. These three vendors represent contrasting paths to recurring revenue capture across cloud-native and on-premise deployment configurations.
| Leading Market Players |
|---|
| Palo Alto Networks |
| Fortinet |
| Cisco Systems |
| Check Point Software Technologies |
| Juniper Networks |
| SonicWall |
| WatchGuard Technologies |
| Barracuda Networks |
| Sophos |
| Others |
Supply & Pricing Matrix
Undercapacity in proprietary ASIC fabrication facilities across Taiwan and South Korea is compressing hardware vendor margins while amplifying pricing power for cloud-native software providers. This utilization asymmetry forces appliance manufacturers toward longer order backlogs and premium pricing for silicon-constrained next-generation platforms, while subscription-based vendors capture elastic demand without physical supply constraints.
Pricing Analysis
Managed security service contracts and recurring subscription tiers now generate the majority of lifetime customer value across firewall deployments. Consumption-based SaaS licensing dominates cloud-based configurations, with throughput-metered subscriptions scaling elastically against actual traffic volumes. Price differentiation rests on certification grade for EU NIS2 compliance and sovereign cloud data residency attestation. Pricing pressure stems from containerized microsegmentation substitutes displacing perimeter appliances in Kubernetes environments. Mid-market enterprises in India exhibit the sharpest price sensitivity, while German critical infrastructure operators absorb premium appliance costs for compliance-certified hardware.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for firewall hardware manufacturers. Proprietary ASIC fabrication concentrates in Taiwan and South Korea, with final assembly distributed across Malaysia and Mexico. Raw material dependencies span silicon wafers, specialized memory components, and precision thermal management subsystems. Single-source vulnerability in advanced semiconductor lithography equipment feeds from Dutch and Japanese supplier concentration. Distribution runs through authorized value-added resellers and direct hyperscale cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firewall procurement is shifting toward platform-economics logic as vendor consolidation and API interoperability reshape enterprise security stack decisions. The convergence of zero-trust architecture with software-defined networking is creating ecosystem lock-in effects that favor integrated platform providers over point-product specialists.
For Market Incumbents: Build switching-cost moats through deep API integration with identity providers and SIEM platforms. Fortify recurring revenue streams by embedding threat intelligence feeds into subscription tiers that resist unbundling. Cloud-native substitution from containerized service meshes represents the primary displacement threat. Vertical integration into proprietary silicon design preserves hardware margin compression capability against software-defined competitors. For New Entrants and Emerging Players: Pursue sovereign cloud certification gaps in India and Germany where data residency mandates create procurement friction for incumbent global vendors. Target mid-market managed security services in the United States where operational outsourcing appetite exceeds vendor consolidation. The most penetrable white-space sits in AI-driven behavioral detection engines that reduce false-positive rates without rule-maintenance overhead. A channel-centric go-to-market through specialized MSSP partnerships accelerates customer acquisition without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native platform vendors with demonstrated subscription revenue conversion and API ecosystem density. Long-term viability across the analysis window favors vendors capturing zero-trust architecture convergence rather than hardware-bound appliance manufacturers facing silicon cycle constraints. Acquisition target archetypes include behavioral analytics specialists with EU AI Act audit-trail capabilities and sovereign cloud certification holders in Gaia-X or MeghRaj frameworks. The signal to watch is containerized microsegmentation adoption rates in financial services Kubernetes deployments as a proxy for perimeter appliance displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified vendor stacks reduce procurement complexity for NIS2 compliance across German energy utilities. |
| Sovereign Cloud Certification | Gaia-X and MeghRaj attestation unlocks captive demand in government infrastructure segments. |
| Managed Security Service Expansion | Recurring monitoring contracts shift revenue from perpetual licenses among US mid-market enterprises. |
| AI-Driven Behavioral Analytics | Self-tuning engines collapse detection paradigms and consolidate intrusion prevention budgets. |
| ASIC Design Investment | Proprietary silicon compression preserves hardware margins against software-defined competitor velocity. |
Research Methodology
Operator-level perspectives from CISOs, network security architects, MSSP operations directors, and critical infrastructure compliance officers anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, hyperscaler capex disclosures, EU regulatory bulletins, and telecommunications infrastructure procurement records. Bottom-up deployment volume estimates triangulated against top-down security spending surveys across financial services, healthcare, and government verticals.
Scenario bracketing around encryption policy fragmentation and sovereign cloud mandate timing shaped the analytical framework. Segmentation dimensions modeled include deployment architecture, product type sophistication, application vertical, and end-user scale tier across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating 5G core buildout schedules and NIS2 compliance deadline clustering. AI Act audit-trail requirements and containerized microsegmentation substitution rates served as industry-specific forecast inputs.
Sensitivities concentrate around EU regulatory deadline delays, ASIC fabrication capacity expansion, and cloud-native substitution acceleration in financial services Kubernetes environments. Forecasts reflect documented assumptions regarding sovereign cloud procurement mandate enforcement and threat intelligence analyst labor market tightness. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Singapore Cybersecurity Market
Cybersecurity
Global Patch Management Market
Cybersecurity
Global Serverless Security Market
Cybersecurity
Hong Kong Cybersecurity Market
Cybersecurity
Micro-Segmentation Solutions Market
Cybersecurity
Network Sandboxing Market
Cybersecurity
Global Ddos Protection Market
Cybersecurity
Netherlands Cybersecurity Market
Cybersecurity
Data Protection Market
Cybersecurity
Australia Cybersecurity Market
Cybersecurity
Global Automated Breach and Attack Simulation (BAS) Market
Cybersecurity
Asia Pacific Cybersecurity Market
Cybersecurity
Endpoint Protection Platforms (EPP) Market
Cybersecurity
China Ransomware Protection Market
Cybersecurity
North America Digital Forensics Market
Cybersecurity
Peru Cybersecurity Market