
 Global Process Safety Services Market | 2026-2036
Global Process Safety Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Process Safety Services Market Foresight
Software-defined safety monitoring is broadening what process safety services encompass beyond traditional audits and inspections. Bureau Veritas leverages its global laboratory network to anchor compliance verification across hazardous installations. Honeywell International sustains technology leadership through integrated control system platforms that merge process automation with safety instrumented systems. ABB competes by extending digital twin capabilities into real-time safety performance optimization for chemical and energy clients.
Process safety services encompass systematic engineering and management practices designed to prevent uncontrolled releases of hazardous materials or energy in industrial operations, incorporating safety integrity level calculations, layer of protection analysis, and functional safety assessments per IEC 61511 standards. These services protect personnel, assets, and surrounding communities while ensuring operational continuity in high-consequence facilities. Risk assessment services command premium pricing due to specialized expertise requirements and liability exposure, while compliance management shows accelerating growth as regulatory complexity deepens across multiple jurisdictions. Chemical manufacturing and oil and gas exploration represent the most mature verticals with established procurement patterns, whereas pharmaceutical production offers expanding margin pools driven by sterile process containment demands and evolving FDA process validation guidelines.
OSHA's Process Safety Management standard and EPA's Risk Management Program shape baseline service demand across United States facilities, while the EU's Seveso III Directive and ATEX frameworks mandate comparable rigor for European operators. IEC 61508 and IEC 61511 functional safety standards create technical compliance thresholds that determine market access for service providers and technology vendors. Stakeholders must monitor how emerging hydrogen economy infrastructure and carbon capture installations extend safety service requirements into novel process chemistries and pressure regimes.
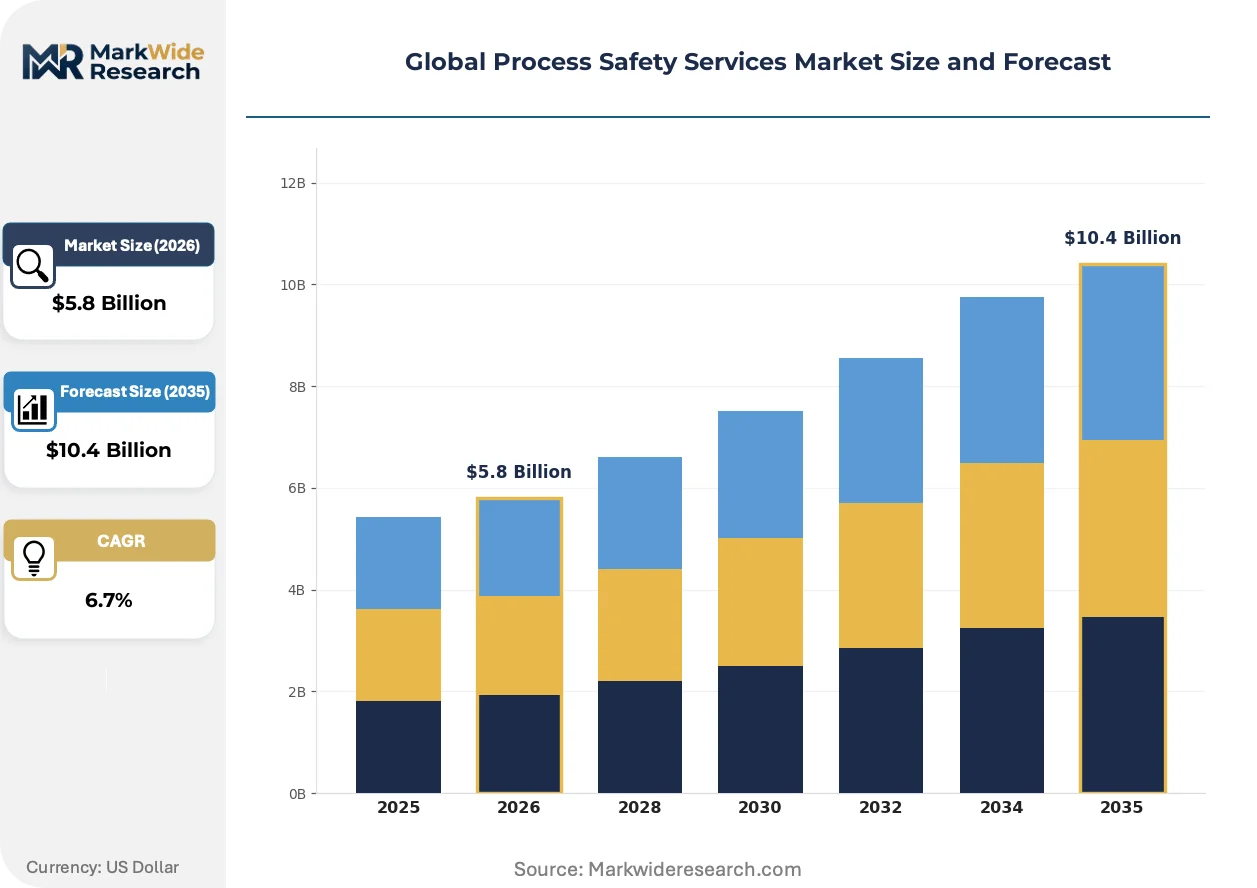
Market Dynamics
Software-defined safety architectures are compressing service delivery timelines while expanding the scope of what process safety providers must deliver beyond traditional compliance audits.
Growth Catalysts
- Seveso III Directive:The EU's tightened major accident hazard controls force facility upgrades across chemical clusters in Germany, Belgium, and the Netherlands.
- Hydrogen infrastructure buildout:Electrolyzer and ammonia synthesis projects introduce novel high-pressure chemistries requiring specialized safety integrity level assessments.
- Carbon capture installations:Post-combustion capture and direct air capture facilities create demand for CO2 handling hazard analysis and compressor safety systems.
Market Restraints
- Specialized engineering talent scarcity:Functional safety certification holders concentrate in Western Europe and North America, limiting service capacity elsewhere.
- Long certification cycles:IEC 61511 compliance verification timelines stretch 12-18 months for complex chemical installations.
- Capital intensity of digital tooling:Real-time safety monitoring platforms require substantial upfront investment in sensor networks and edge computing infrastructure.
Strategic Opportunities
- Saudi Arabia's industrial cities:Jubail and Yanbu petrochemical expansions lack mature local safety consultancy ecosystems.
- Digital twin convergence:Integration of process simulation with safety instrumented system design compresses hazard analysis cycles.
- India's PLI scheme:Specialty chemical manufacturing incentives attract capacity that will require Seveso-equivalent safety frameworks.
Industry Challenges
- Legacy control system integration:Brownfield facilities running 1990s-era distributed control systems resist seamless safety system upgrades.
- Cross-jurisdictional compliance:Multinational operators must reconcile OSHA PSM, Seveso III, and IEC 61511 requirements simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Process Safety Services Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Risk Assessment, Safety Audits, Hazard Analysis, Compliance Management, Emergency Response Planning Industry Vertical: Chemical Manufacturing, Oil & Gas Exploration, Pharmaceutical Production, Power Generation, Food Processing Application: Incident Investigation, Process Design, Equipment Integrity, Training & Development, Regulatory Reporting Client Type: Manufacturers, EPC Contractors, Facility Operators, Regulatory Bodies, Consulting Firms |
| Companies Covered | Bureau Veritas, Honeywell International, ABB, Rockwell Automation, Intertek Group plc, SGS SA, Siemens, Emerson Electric, HIMA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Process Safety Services Market Shifts & Advancements
Real-time risk quantification tools are displacing static documentation-heavy approaches across hazardous facility management. The shift demands new competencies from service providers while opening margin pools in predictive safety analytics.
Machine learning-based process hazard analysis is automating pattern recognition in incident databases and near-miss reporting systems. Major chemical manufacturers in Germany and the US Gulf Coast are deploying these tools for layer of protection analysis validation. The technology is automating previously manual review cycles that consumed engineering hours.
EPA's Risk Management Program amendments tighten accident investigation and root cause analysis requirements for covered processes. Facilities must now document safer technology and alternatives analysis for certain chemical handling. Chemical manufacturers in Texas and Louisiana are expanding internal safety engineering headcount to meet documentation burdens.
Integrated service contracting is consolidating discrete safety audits into multi-year operational partnerships. End-users in pharmaceutical manufacturing increasingly source safety lifecycle management from single providers rather than fragmented specialist boutiques. This pattern is most pronounced in Ireland and Singapore where sterile process containment demands intersect with concentrated biologics production.
Global Process Safety Services Market Segmentation
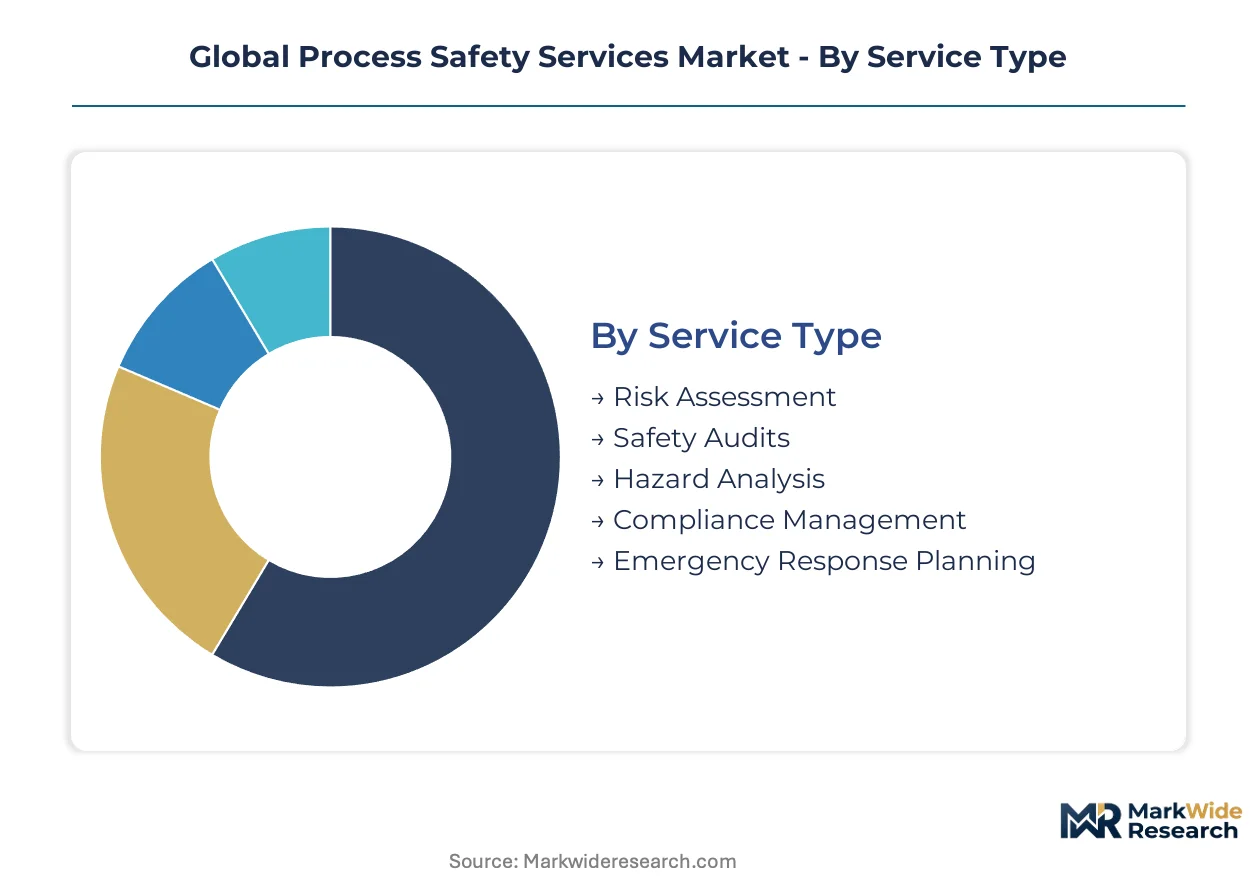
Process safety services fragment across multiple decision axes that shape procurement patterns and margin structures. Buyers prioritize specialized expertise for high-consequence hazard analysis while consolidating routine compliance under integrated service contracts. Understanding these segment boundaries clarifies where technology differentiation commands premium pricing versus where scale economies dominate.
Service Type:
Procurement budgets concentrate where liability exposure and regulatory scrutiny intersect most intensely.
- Risk Assessment:Systematic evaluation of major accident hazards using layer of protection analysis and quantitative risk assessment methodologies. Chemical manufacturers in Germany and the US Gulf Coast sustain premium pricing for these services due to Seveso III and EPA Risk Management Program documentation burdens.
- Safety Audits:Periodic verification of safety management system effectiveness against IEC 61511 and OSHA PSM requirements. Oil and gas operators in Texas and Louisiana drive recurring demand through three-year compliance cycles mandated by regulatory frameworks.
- Hazard Analysis:Process hazard analysis including HAZOP and What-If studies for new and modified facilities. Demand clusters around greenfield petrochemical expansions in Saudi Arabia's industrial cities.
- Compliance Management:Ongoing regulatory documentation, permit maintenance, and inspection coordination. Pharmaceutical manufacturers in Ireland and Singapore source these services through multi-year operational partnerships.
- Emergency Response Planning:Development of site-specific emergency procedures and coordination protocols with local authorities. Required for all Seveso III upper-tier establishments across EU member states.
Volume sits with Safety Audits; growth tilts toward Compliance Management.
Industry Vertical:
Maturity gradients across verticals determine whether buyers seek established providers or tolerate emerging specialists.
- Chemical Manufacturing:The most mature vertical with standardized procurement patterns for safety lifecycle services. Facilities in Belgium, the Netherlands, and Germany sustain the densest consultant ecosystems due to Seveso III implementation history.
- Oil & Gas Exploration:Offshore platforms and onshore processing facilities require specialized high-pressure system expertise. The North Sea and US Gulf Coast concentrate demand for blowout prevention and well control safety systems.
- Pharmaceutical Production:Sterile process containment and FDA process validation guidelines drive expanding margin pools. Biologics manufacturing in Ireland and Singapore commands premium pricing for containment verification services.
- Power Generation:Combined cycle gas turbines and hydrogen-ready plants create emerging demand for combustion hazard analysis. Electrolyzer integration projects in Germany introduce novel safety integrity level assessment requirements.
- Food Processing:Dust explosion hazards in grain handling and spray drying operations sustain specialized niche demand. Facilities in the US Midwest and France's agricultural processing regions require ATEX-compliant equipment assessments.
Revenue concentrates in Chemical Manufacturing; margin expansion favors Pharmaceutical Production.
Application:
Service delivery timelines compress where digital tooling displaces documentation-heavy approaches.
- Incident Investigation:Root cause analysis following process safety incidents or near-miss events. EPA's tightened accident investigation requirements are expanding internal safety engineering headcount at Texas and Louisiana chemical facilities.
- Process Design:Integration of safety instrumented systems during front-end engineering design. Carbon capture installations in the Netherlands and Norway require novel CO2 handling hazard analysis for compressor safety systems.
- Equipment Integrity:Mechanical integrity programs for pressure vessels, piping systems, and relief devices. Oil and gas operators prioritize these services to manage aging infrastructure across the North Sea.
- Training & Development:Competency assurance for functional safety engineers and operations personnel. Scarcity of IEC 61511 certification holders in Western Europe limits service capacity expansion.
- Regulatory Reporting:Preparation and submission of mandated safety documentation to national regulators. Seveso III establishments across Germany, Belgium, and France require periodic safety report updates.
Procurement volume favors Equipment Integrity; digital transformation is accelerating fastest in Process Design.
Client Type:
Contracting structures vary sharply between asset owners seeking operational partnerships and project-phase buyers optimizing for transaction efficiency.
- Manufacturers:Chemical and pharmaceutical producers with captive process safety engineering capabilities. Major German chemical manufacturers are deploying machine learning-based hazard analysis tools for layer of protection analysis validation.
- EPC Contractors:Engineering-procurement-construction firms requiring safety input during project execution. Jubail and Yanbu petrochemical expansions in Saudi Arabia lack mature local safety consultancy ecosystems.
- Facility Operators:Third-party operators managing production assets under long-term agreements. Integrated service contracting is consolidating discrete safety audits into multi-year operational partnerships.
- Regulatory Bodies:National authorities commissioning specialized safety studies or incident investigations. Germany's competent authorities under Seveso III drive demand for independent safety assessment services.
- Consulting Firms:Specialist boutiques and diversified professional services firms subcontracting technical safety expertise. India's specialty chemical manufacturing incentives under PLI scheme will require Seveso-equivalent safety frameworks.
Spend concentrates with Manufacturers; fastest expansion is occurring among EPC Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service consumption concentrates in industrialized economies with dense chemical manufacturing clusters, while emerging markets generate project-phase demand through greenfield petrochemical expansions. Germany and the United States anchor mature procurement patterns. Saudi Arabia and India represent capacity expansion frontiers.
United States
Gulf Coast chemical facilities sustain demand for layer of protection analysis and quantitative risk assessment. EPA's Risk Management Program amendments tighten accident investigation requirements for Texas and Louisiana installations. Houston and Lake Charles industrial corridors expand internal safety engineering headcount to meet documentation burdens.
Germany
Ruhr Valley and Ludwigshafen chemical clusters generate dense consultancy ecosystems for Seveso III compliance. The country's competent authorities mandate periodic safety report updates for upper-tier establishments. Bavarian industrial regions deploy machine learning-based hazard analysis tools for automated pattern recognition.
Saudi Arabia
Jubail and Yanbu petrochemical expansions lack mature local safety consultancy infrastructure. SFDA and national industrial regulators import IEC 61511 verification expertise for high-pressure system assessments. Eastern Province installations create demand for specialized blowout prevention safety systems.
India
PLI scheme incentives attract specialty chemical manufacturing capacity requiring Seveso-equivalent safety frameworks. Maharashtra and Gujarat industrial zones source functional safety certification training for local engineering talent. Dahej and Mundra petrochemical corridors contract international consultants for greenfield hazard analysis.
Netherlands
Rotterdam chemical cluster drives demand for carbon capture installation safety assessments. Port of Rotterdam CO2 handling facilities require novel compressor safety system designs. Eindhoven region hydrogen-ready plants introduce electrolyzer integration safety integrity level requirements.
Global Process Safety Services Market Competitive Landscape
Capital-heavy engineering conglomerates compete with asset-light specialized consultancies for distinct contract types. Tier-one diversified industrials anchor multi-year operational partnerships. Boutique verification specialists capture premium pricing for high-consequence risk assessments. Consolidation accelerates through technology licensing agreements and geographic expansion into underserviced industrial corridors.
Within the diversified engineering tier, Bureau Veritas and Honeywell International exemplify scale-driven positioning. Bureau Veritas leverages its global laboratory network to anchor compliance verification across hazardous installations. Honeywell International occupies a position merging process automation with safety instrumented systems through integrated control platforms. ABB represents the digital transformation archetype, extending simulation capabilities into real-time safety performance optimization.
| Leading Market Players |
|---|
| Bureau Veritas |
| Honeywell International |
| ABB |
| Rockwell Automation |
| Intertek Group plc |
| SGS SA |
| Siemens |
| Emerson Electric |
| HIMA |
| Others |
Supply & Pricing Matrix
Buyers consolidating safety lifecycle management under integrated service contracts are squeezing project-based consultancies and forcing scale investments that reshape margin structures across the value chain.
Pricing Analysis
Margin tightening in risk assessment services reflects IEC 61511 certification scarcity and liability exposure concentration in Western Europe. Project-based pricing dominates hazard analysis and safety audits, while multi-year operational partnerships command premium positioning through embedded compliance management. Certification grade and geographic delivery cost differentiate tiers, with pharmaceutical manufacturers in Ireland and Singapore least price-sensitive due to sterile containment verification demands, whereas EPC contractors in Saudi Arabia's industrial cities exhibit highest sensitivity.
Supply Chain Analysis
Freight costs for specialized sensor networks and edge computing hardware from Germany, Japan, and the United States amplify capital intensity for real-time safety monitoring platforms. Engineering talent supply draws from functional safety certification holders concentrated in Western Europe and North America, creating single-source vulnerability for complex chemical installation verification. Distribution runs through direct engagement with asset owners and EPC contractors, with technology licensing agreements increasingly displacing pure service provision.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around technology-anchored service platforms, with digital twin capabilities and machine learning-based hazard analysis tools forcing boutique verification specialists toward acquisition or niche retreat.
For Market Incumbents: Anticipate margin compression from software-defined safety architectures by deepening captive supply of real-time monitoring hardware and predictive analytics platforms. Acquire IEC 61511 certification training capacity to address engineering talent scarcity in Saudi Arabia and India. Lock multi-year operational partnerships with pharmaceutical manufacturers in Ireland and Singapore before integrated service contracting fully consolidates procurement. For New Entrants and Emerging Players: Capture white-space opportunity in carbon capture installation safety assessments across the Netherlands and Norway, where novel CO2 handling hazard analysis demands outpace established consultancy capacity. Target hydrogen-ready plant electrolyzer integration projects in Germany's Eindhoven region, leveraging partnerships with control system vendors for safety integrity level assessment credibility. For Investors and Strategic Acquirers: The window for entry favors mid-scale engineering consultancies with IEC 61511 verification credentials and established regulatory body relationships in Germany or the United States. Watch for inflection when EPA Risk Management Program amendments trigger mandatory safer technology documentation expansions across Texas and Louisiana chemical facilities, accelerating internal safety engineering headcount buildouts that strain service provider capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | ABB extends digital twin capabilities to EPC contractors lacking in-house simulation expertise. |
| Joint Venture | Bureau Veritas partners with Saudi industrial regulators to localize IEC 61511 verification capacity. |
| Acquisition of Specialist Firm | Machine learning hazard analysis boutiques in Bavaria attract Honeywell integration interest. |
| Geographic Expansion | Indian PLI scheme specialty chemical zones draw Seveso-equivalent framework specialists from Belgium. |
| Platform Integration | Rockwell Automation merges safety instrumented systems with process control architectures. |
Research Methodology
Multi-period observation of safety consultancy contract structures, certification training capacity, and regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with plant managers at chemical manufacturing facilities, procurement leads at pharmaceutical OEMs, EPC contractor safety directors, and functional safety certification bodies. Secondary validation drew from IEC 61511 implementation databases, Seveso III safety report filings, EPA Risk Management Program compliance records, and customs data on safety system hardware trade. Bottom-up service provider revenue estimates triangulated against top-down industrial facility count projections.
Segment-weighting across service type, industry vertical, application, and client type dimensions structured the analytical framework across the analysis window. CAGRs derived from facility modernization cycle timing, regulatory amendment implementation schedules, and greenfield petrochemical project pipelines. Hydrogen infrastructure buildout assumptions and carbon capture installation deployment curves informed scenario-variant outputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory enforcement intensity variations across EU member states and EPA regional office interpretation shifts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Outdoor Safety Lock Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Explosion-Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Electronic Siren Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Wearable Airbag Belt Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Monitoring and Dosimeter Badges Market
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
Barricade Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market