
 Sri Lanka Telecom Tower Market | 2026-2036
Sri Lanka Telecom Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Sri Lanka Telecom Tower Market Insights
Open RAN architecture is reconfiguring how telecom infrastructure gets deployed across Sri Lanka's island geography. Dialog Axiata PLC leverages its extensive macro-site portfolio to sustain coverage leadership in rural districts. EDOTCO Services Lanka anchors the independent tower company model through aggressive colocation expansion. SLT-Mobitel competes by integrating its fiber backbone with tower assets for unified backhaul.
Telecom towers are steel or concrete structures engineered to support multiple antenna arrays at heights typically ranging from 30 to 120 meters, designed to withstand tropical cyclone wind loads per local structural codes while providing line-of-sight transmission for wireless networks. Monopole designs dominate urban deployments where land scarcity and aesthetic restrictions limit footprint, while lattice towers retain cost advantages for rural macro coverage requiring heavy multi-tenant loading. Shared service models now capture the strongest margin pools as mobile network operators outsource passive infrastructure to specialized tower companies.
The Telecommunications Regulatory Commission of Sri Lanka enforces infrastructure sharing mandates that lower barriers to market entry for new mobile virtual network operators, while the Central Environmental Authority reviews tower siting for coastal zone and heritage area compliance. Stakeholders must monitor spectrum auction timelines and tower zoning liberalization as the decisive variables shaping deployment velocity and tenancy ratios.
Market Dynamics
Tower sharing mandates from the Telecommunications Regulatory Commission of Sri Lanka are compressing capital deployment cycles for mobile network operators while elevating tenancy ratios at independent tower company sites.
Growth Catalysts
- Western Province Urban Densification:Colombo's fiber backhaul convergence creates the highest site utilization rates, pulling tower deployment toward metro corridors where multi-tenant loading maximizes asset returns.
- TRC Infrastructure Sharing Guidelines:The regulatory mandate accelerates colocation adoption by lowering barriers to market entry for new mobile virtual network operators seeking network access without greenfield builds.
- Open RAN Architecture:This disaggregated radio access network standard reconfigures deployment economics across Sri Lanka's island geography, enabling multi-vendor interoperability at macro-site portfolios.
Market Restraints
- Steel Input Cost Volatility:Fluctuations in global steel pricing directly impact monopole and lattice tower fabrication costs, squeezing margins for infrastructure providers locked into fixed-lease contracts.
- Coastal Zone Siting Friction:The Central Environmental Authority reviews tower placements for heritage area compliance, adding procedural delays to deployments in high-demand western coastal districts.
- Tropical Cyclone Structural Loading:Local structural codes mandate heavier engineering standards for wind resistance, increasing per-site material costs relative to continental Asian markets with milder meteorological profiles.
Strategic Opportunities
- Central Province Coverage Gaps:Kandy and surrounding hill country districts remain underpenetrated by high-capacity macro sites, presenting first-mover tenancy buildout potential as data traffic migrates inland.
- Fiber-Tower Convergence:Unified backhaul integration creates service differentiation for operators controlling both asset classes, compressing latency for enterprise and residential broadband.
- 5G Spectrum Auction Timing:Anticipated mid-band allocations will trigger densification requirements, positioning shared infrastructure providers to capture incremental colocation demand without bearing radio equipment capex.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized skills for interference management and antenna pattern optimization remain concentrated among legacy operator engineering teams, constraining independent tower company technical staffing.
- Legacy Lease Renegotiation Complexity:Existing ground lease contracts with religious institutions and private landowners often lack colocation assignment clauses, forcing expensive renegotiation for multi-tenant upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sri Lanka Telecom Tower Market |
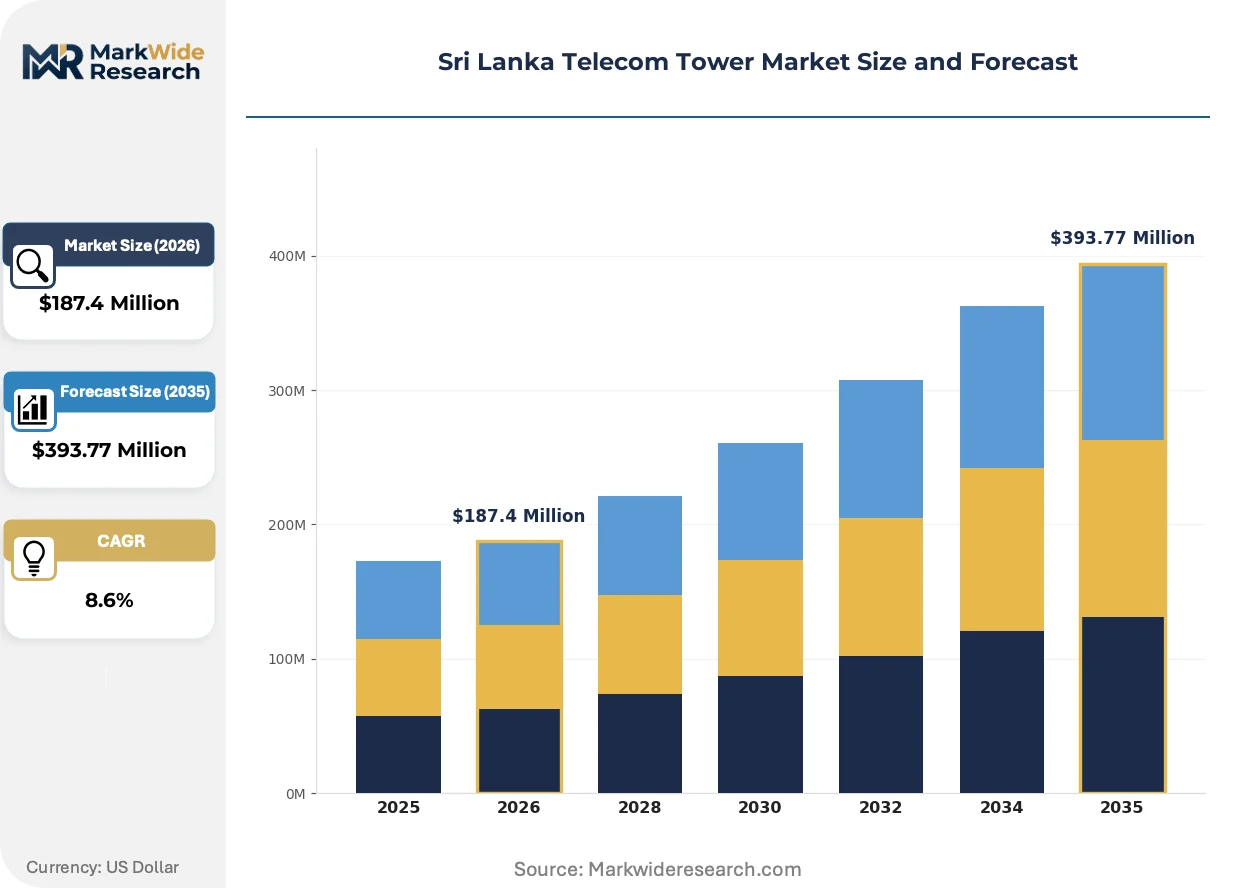
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: 5G, 4G, 3G, Microwave Tower Type: Monopole, Lattice, Stealth, Rooftop Service Type: Shared, Dedicated, Managed, Hybrid Customer Type: MNO, MVNO, Enterprises, Government |
| Companies Covered | Dialog Axiata PLC, SLT-Mobitel, Hutchison Telecommunications Lanka (Pvt) Ltd, Bharti Airtel Lanka (Pvt) Ltd, Sri Lanka Telecom PLC, EDOTCO Services Lanka (Private) Limited, Lanka Bell Ltd, Dialog Broadband Networks, Synopsys Networks (Pvt) Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sri Lanka Telecom Tower Market Trends and Innovations
Passive infrastructure is undergoing operational transformation as remote monitoring systems and predictive maintenance protocols replace manual site inspection regimes across Sri Lanka's dispersed tower footprint.
AI-powered energy management systems are digitizing diesel generator runtime optimization at off-grid tower locations. Rural macro sites across the North Central and Eastern Provinces deploy these systems to reduce fuel logistics costs. The technology is digitizing operational expenditure structures for independent tower companies managing geographically distributed portfolios.
The Central Environmental Authority's revised coastal zone notification requirements now mandate biodiversity impact assessments for new tower siting within 500 meters of sensitive marine ecosystems. This procedural expansion adds 60-90 days to permitting timelines for western coastal deployments. Tower companies are responding by pre-qualifying inland alternative sites to maintain deployment velocity.
Mobile network operators are unbundling passive infrastructure ownership from radio access network operations, converting historical capex-heavy balance sheets into opex-based tenancy models. This procurement transformation concentrates negotiating leverage with specialized tower companies. The shift is most visible in the Western Province, where Dialog Axiata and SLT-Mobitel have transferred substantial site portfolios to EDOTCO Services Lanka under long-term leaseback arrangements.
Sri Lanka Telecom Tower Market Segmentation
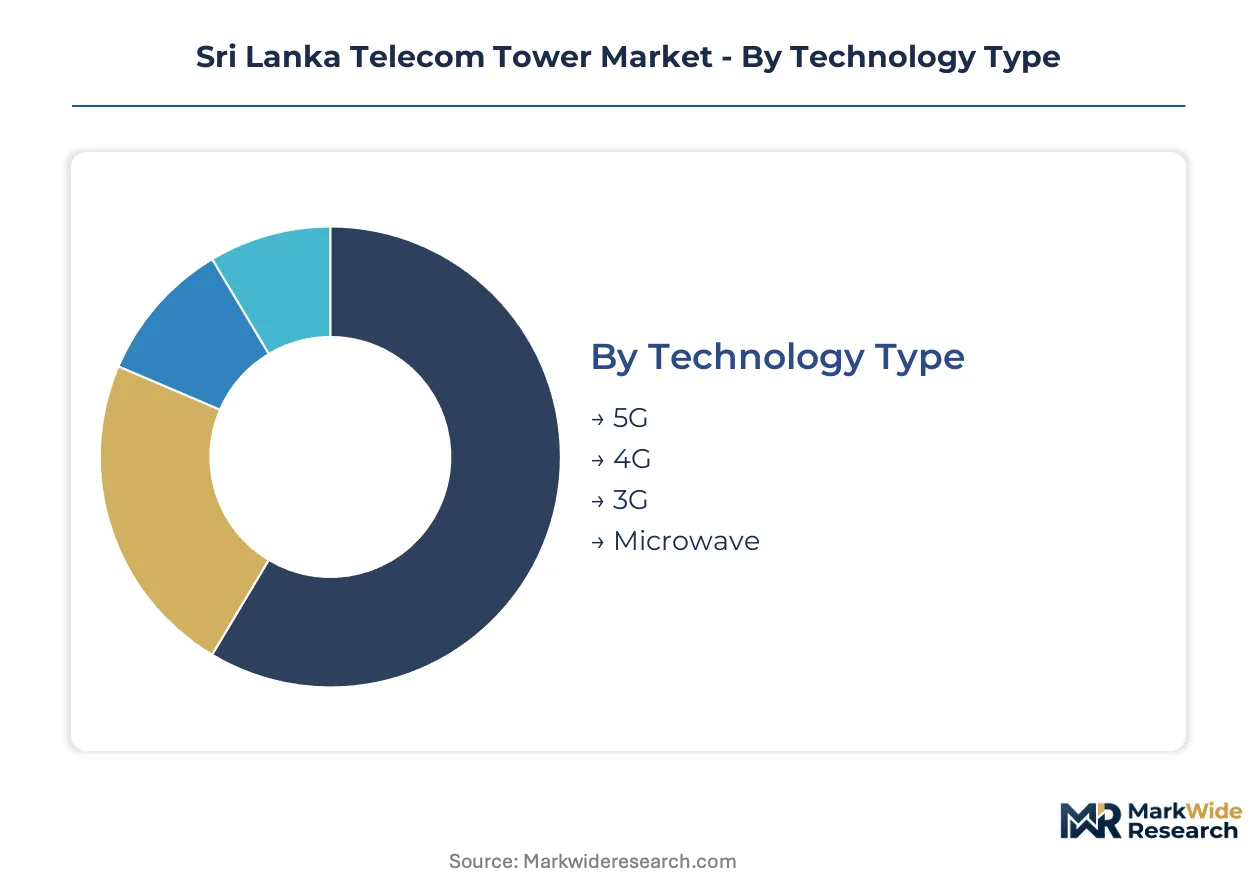
Segmentation of Sri Lanka's telecom tower market reveals how infrastructure deployment adapts to island geography, regulatory mandates, and operator business models. Each dimension—technology, structure, service delivery, and customer type—creates distinct margin profiles and tenancy economics that shape competitive positioning across the Western Province and beyond.
Technology Type:
Technology type segments reflect the use-case spectrum spanning high-capacity urban networks to legacy rural coverage and backhaul relay systems.
- 5G:Mid-band spectrum deployments concentrate in Colombo and Gampaha districts, where fiber backhaul availability supports ultra-low latency requirements for enterprise and residential broadband densification. The Telecommunications Regulatory Commission of Sri Lanka's anticipated spectrum auction timeline is compressing deployment windows for this segment.
- 4G:Macro-site portfolios from Dialog Axiata and SLT-Mobitel anchor nationwide coverage, with carrier aggregation enabling 100+ Mbps throughput across the Western Province's highest-traffic corridors. Rural districts in the Central Province still present first-mover buildout potential as data traffic migrates inland from saturated metro markets.
- 3G:Legacy voice and basic data services persist in remote Eastern Province districts where equipment refresh cycles lag behind national averages.
- Microwave:Point-to-point backhaul links bridge fiber gaps across Sri Lanka's hill country terrain, serving as critical redundancy for coastal corridor routes vulnerable to tropical cyclone disruption.
The dominant share belongs to 4G, while 5G is closing the gap fastest as spectrum allocation clarity emerges from regulatory consultations.
Tower Type:
Structural design selection pivots on land availability, aesthetic constraints, and multi-tenant loading requirements across Sri Lanka's varied topography.
- Monopole:Single-stem steel structures with minimal footprint dominate Colombo's dense urban corridors where municipal zoning restricts ground coverage. These designs command premium lease rates but face fabrication cost pressure from global steel input volatility.
- Lattice:Triangular or square-section steel frameworks retain cost advantages for rural macro coverage in the North Central Province, where heavy wind loading from tropical cyclones demands robust structural engineering per local building codes.
- Stealth:Camouflaged structures disguised as palm trees or architectural elements satisfy Central Environmental Authority requirements for heritage-sensitive districts along the western coastal zone.
- Rooftop:Building-mounted installations exploit existing vertical assets in Gampaha and Kalutara municipal limits, reducing ground lease complexity while limiting antenna height and coverage radius.
Lattice towers hold the dominant share in tenancy count, though monopole deployments are expanding most quickly as urban densification accelerates.
Service Type:
Commercial arrangements segment by infrastructure ownership and operational responsibility allocation between tower companies and network operators.
- Shared:Multi-tenant colocation models capture the strongest margin pools as EDOTCO Services Lanka aggregates demand from multiple mobile network operators at single sites. The Telecommunications Regulatory Commission of Sri Lanka's infrastructure sharing mandates accelerate adoption by lowering barriers for new market entrants.
- Dedicated:Single-tenant arrangements persist where legacy operators retain strategic control of high-traffic locations or where technical specifications preclude multi-vendor interoperability.
- Managed:Outsourced operational responsibility including power, security, and maintenance converts operator capex to predictable opex, particularly attractive for MVNOs lacking field engineering scale.
- Hybrid:Blended structures combining shared passive infrastructure with dedicated active equipment accommodate operator-specific radio configurations while capturing tenancy economics.
Shared service models command the dominant revenue share, with managed services climbing the fastest as operator unbundling of passive infrastructure deepens.
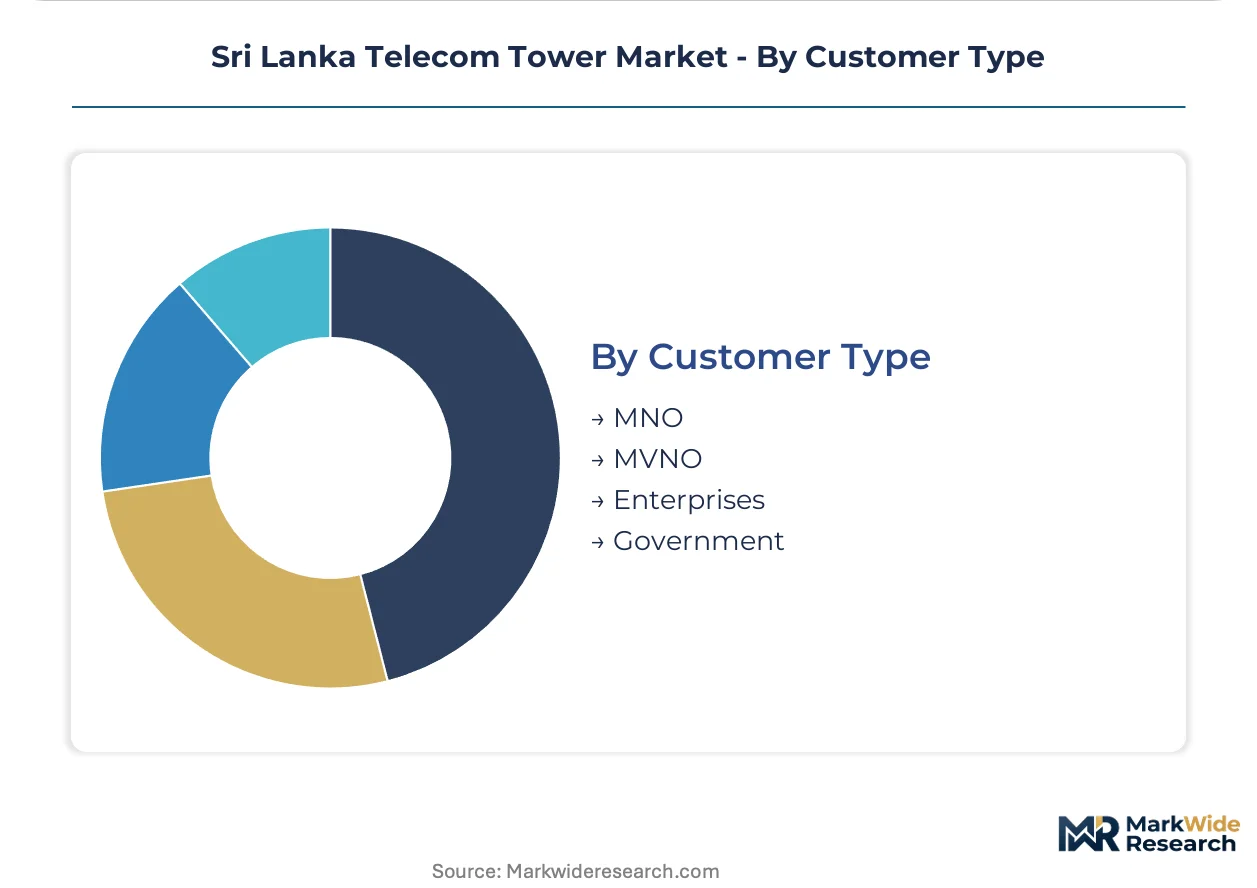
Customer Type:
End-user categories reflect divergent procurement authority, technical sophistication, and contract scale across Sri Lanka's telecommunications ecosystem.
- MNO:Dialog Axiata PLC and SLT-Mobitel drive bulk tenancy demand, with long-term leaseback arrangements transferring historical site portfolios to independent tower companies while retaining network operational control.
- MVNO:Mobile virtual network operators leverage infrastructure sharing guidelines to enter without greenfield capital deployment, concentrating demand in the Western Province where colocation vacancy rates remain highest.
- Enterprises:Private network deployments for logistics, mining, and plantation sectors in the Central Province create specialized tenancy demand outside consumer mobile coverage mandates.
- Government:Public safety and rural connectivity programs channel procurement through the Telecommunications Regulatory Commission of Sri Lanka's universal service obligations, with site selection prioritizing coverage over commercial return metrics.
MNOs retain the dominant share of contracted tenancies, though enterprise demand is gaining share fastest as Industry 4.0 applications proliferate beyond traditional telecom boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian telecom tower manufacturers supply steel lattice structures and monopole assemblies to Sri Lankan operators, with freight corridors running through Tamil Nadu ports to Colombo. This trade relationship shapes equipment sourcing patterns across Sri Lanka's provincial tower deployment programs.
Western Province
Colombo and Gampaha districts concentrate the highest tower tenancy ratios as fiber backhaul convergence enables multi-tenant loading at urban macro sites. The Telecommunications Regulatory Commission of Sri Lanka's infrastructure sharing guidelines accelerate colocation adoption here. Kotte and Dehiwala-Mount Lavinia municipal clusters host the densest stealth tower deployments to satisfy Central Environmental Authority aesthetic restrictions.
Central Province
Kandy and Nuwara Eliya districts present coverage gaps for high-capacity macro sites as data traffic migrates inland from saturated Western Province markets. Hill country terrain complicates line-of-sight transmission engineering. Peradeniya and Gampola industrial zones attract tower fabrication workshops serving the regional buildout.
Northern Province
Jaffna and Kilinochchi districts undergo network restoration with 4G densification following conflict-era infrastructure deficits. The Telecommunications Regulatory Commission of Sri Lanka channels universal service obligation funding toward coverage expansion here. Jaffna Peninsula coastal corridors face Central Environmental Authority marine ecosystem review for new tower siting.
Eastern Province
Trincomalee and Batticaloa districts retain 3G legacy equipment cycles lagging national refresh rates, creating upgrade demand as operators unify network architectures. Off-grid tower locations here deploy AI-powered diesel generator management systems to reduce fuel logistics costs. Kalmunai and Ampara municipal clusters concentrate rooftop installations on existing vertical assets.
Southern Province
Galle and Matara districts balance tourism corridor coverage requirements with heritage zone siting restrictions. The Central Environmental Authority reviews tower placements for coastal compliance along the Galle Fort UNESCO buffer zone. Weligama and Mirissa beach clusters drive stealth tower demand to preserve scenic vistas.
Sri Lanka Telecom Tower Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Sri Lanka's tower procurement landscape. The market structure consolidates around three mobile network operators outsourcing passive infrastructure to a single independent tower company. Strategic archetypes include integrated operator-tower hybrids, pure-play infrastructure specialists, and equipment-agnostic managed service providers. Dominant competitive moves encompass long-term leaseback arrangements converting operator capex to opex, and geographic pre-qualification of alternative sites to bypass permitting delays.
Among operator-affiliated entities, Dialog Axiata PLC and SLT-Mobitel occupy positions as legacy site portfolio holders transitioning assets through leaseback structures. EDOTCO Services Lanka anchors the independent tower company archetype through colocation aggregation. These three entities exemplify the market's shift from vertically integrated network ownership toward specialized infrastructure tenancy models mandated by regulatory sharing guidelines.
| Leading Market Players |
|---|
| Dialog Axiata PLC |
| SLT-Mobitel |
| Hutchison Telecommunications Lanka (Pvt) Ltd |
| Bharti Airtel Lanka (Pvt) Ltd |
| Sri Lanka Telecom PLC |
| EDOTCO Services Lanka (Private) Limited |
| Lanka Bell Ltd |
| Dialog Broadband Networks |
| Synopsys Networks (Pvt) Ltd |
| Others |
Pricing and Supply Chain Analysis
Indian steel lattice fabricators anchor upstream supply for Sri Lankan tower procurement, concentrating margin capture with fabricators in Tamil Nadu while downstream tenancy economics hinge on colocation density at Western Province macro sites.
Pricing Analysis
Cost-plus contracts with steel indexation clauses dominate procurement between tower companies and mobile network operators, insulating EDOTCO Services Lanka from raw material volatility while locking Dialog Axiata into pass-through escalation. Price differentiation rests on structural load certification tier and fiber backhaul proximity, with monopole deployments in Colombo commanding premiums over rural lattice configurations. Cost compression in shared service tiers is intensifying because TRC infrastructure sharing mandates compress tenancy pricing power. Mobile virtual network operators exhibit highest price sensitivity, while government universal service obligation contracts show least elasticity due to coverage mandates overriding commercial metrics.
Supply Chain Analysis
Export-control restrictions on high-grade structural steel alloys limit supply flexibility from Chinese mills, forcing Sri Lankan tower companies toward Indian and Southeast Asian sourcing corridors. Geographic supply concentration centers on India, Vietnam, and South Korea for fabricated steel assemblies and precision antenna mounting hardware. Raw material dependencies span hot-rolled steel sections, zinc-aluminum coating substrates, and marine-grade anchor bolts. Single-source vulnerability from Tamil Nadu port congestion poses structural risk during monsoon shipping windows. Distribution runs through Colombo-based logistics hubs with last-mile deployment via regional fabricator workshops in Kandy and Gampaha.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sri Lanka's telecom tower market sits in early-cycle expansion as 5G spectrum allocation clarity accelerates infrastructure densification beyond legacy 4G coverage buildouts.
For Market Incumbents: Build regulatory relationship moats through pre-qualified site portfolios that bypass Central Environmental Authority permitting delays. EDOTCO Services Lanka should deepen fiber-tower convergence capabilities to defend against SLT-Mobitel's integrated backhaul advantage. Capacity addition in Central Province hill country districts captures inland data traffic migration before competitors establish tenancy relationships. For New Entrants and Emerging Players: Establish a beachhead in enterprise private network deployments for plantation and logistics sectors in Kandy and Nuwara Eliya districts where consumer mobile coverage mandates do not dominate procurement. The Central Province presents most penetrable geography given coverage gaps and lower incumbent site density. Go-to-market positioning should emphasize managed service opex conversion for mid-sized operators lacking field engineering scale. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play infrastructure specialists with established colocation tenancy ratios and long-term leaseback contracts with tier-one mobile network operators. Five-to-ten year viability hinges on regulatory permanence of infrastructure sharing mandates. The signal to watch is 5G spectrum auction timing as inflection trigger for densification capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Colocation Tenancy Expansion | EDOTCO Services Lanka aggregates multiple operators at single sites to maximize asset utilization under TRC sharing guidelines. |
| Fiber-Tower Convergence Investment | Unified backhaul integration compresses latency for Dialog Axiata enterprise customers in Colombo financial district. |
| Stealth Tower Pre-Qualification | Alternative site portfolios bypass Central Environmental Authority delays in Galle Fort UNESCO buffer zones. |
| AI-Powered Energy Management Deployment | Diesel generator optimization reduces opex at off-grid Eastern Province towers managed by independent operators. |
| Central Province Coverage Buildout | First-mover macro site deployment captures inland data traffic migration from saturated Western Province corridors. |
Research Methodology
Cross-validation between tower company tenancy records and Telecommunications Regulatory Commission of Sri Lanka infrastructure sharing filings anchors the qualitative findings. Primary interviews with network planning executives at mobile network operators, procurement leads at independent tower companies, and regulatory affairs specialists at the TRC combined with secondary validation from tower zoning permits, environmental impact assessments, and customs import records for steel structural components. Bottom-up site-level tenancy modeling and top-down market sizing from operator capex disclosures triangulate volume estimates.
Calibration against historical deployment velocity in Western Province districts and anticipated spectrum allocation timelines shapes the projection framework. Segmentation dimensions span technology generation, tower structural type, service delivery model, and customer archetype across the modeling period. CAGRs derive from tenancy ratio buildout curves and per-site revenue trajectories. Forecast inputs incorporate tropical cyclone structural loading requirements and fiber backhaul convergence penetration rates.
Sensitivities concentrate around 5G spectrum auction timing, steel input cost volatility, and coastal zone siting regulatory expansion. Forecasts reflect documented assumptions regarding infrastructure sharing mandate permanence and mobile network operator unbundling velocity. Material shifts in TRC regulatory posture or Central Environmental Authority permitting scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
C-RAN Market
Telecommunications
Fixed LTE Market
Telecommunications
South Africa Telecom Market
Telecommunications
Austria Telecom Market
Telecommunications
Satcom Terminal Market
Telecommunications
Global Small Cell 5G Network Market
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
5G Connections Market
Telecommunications
5G Monetization Market
Telecommunications
Medical 5G Market
Telecommunications
TD-LTE Ecosystem Market
Telecommunications
Global LTE Market
Telecommunications
Norway Telecom Market
Telecommunications
A2P Messaging Market
Telecommunications
Global B2B Telecommunication Market