
 Europe Telecom Expense Management Market | 2026-2036
Europe Telecom Expense Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Telecom Expense Management Market Foresight
Subscription-based software-defined analytics is pivoting how European enterprises procure telecom expense capabilities, shifting capital expenditure into recurring operational models. Accenture PLC leverages its consulting footprint to embed expense management into broader digital transformation contracts. CGI, Inc. anchors its position through deep public sector relationships across France and the United Kingdom. Calero-MDSL Ltd specializes in inventory management modules that integrate with existing ERP systems.
Europe Telecom Expense Management encompasses platforms that automate invoice validation, contract compliance monitoring, and usage optimization across fixed and mobile telecom estates, typically processing call detail records and service tariff databases against contractual rate decks. These systems primarily reduce operational leakage and enforce procurement discipline across multi-vendor telecom environments. Cloud-based deployment leads solution uptake among mid-market enterprises seeking faster implementation cycles, while invoice management captures the largest share of current platform spending due to persistent billing complexity across European carrier markets. On-premises installations persist in banking and finance verticals where data residency requirements dominate infrastructure decisions.
The EU AI Act and GDPR impose strict governance requirements on automated processing of telecom usage data, compelling vendors to embed audit trails and consent management into platform architectures. ECHA chemical disclosure rules indirectly affect hardware asset tracking modules within inventory management solutions. REACH compliance obligations extend to end-of-life device disposal workflows that integrated TEM platforms must document. Stakeholders should monitor how the EU Green Deal's digital reporting standards will merge carbon accounting with telecom asset lifecycle management.
Market Dynamics
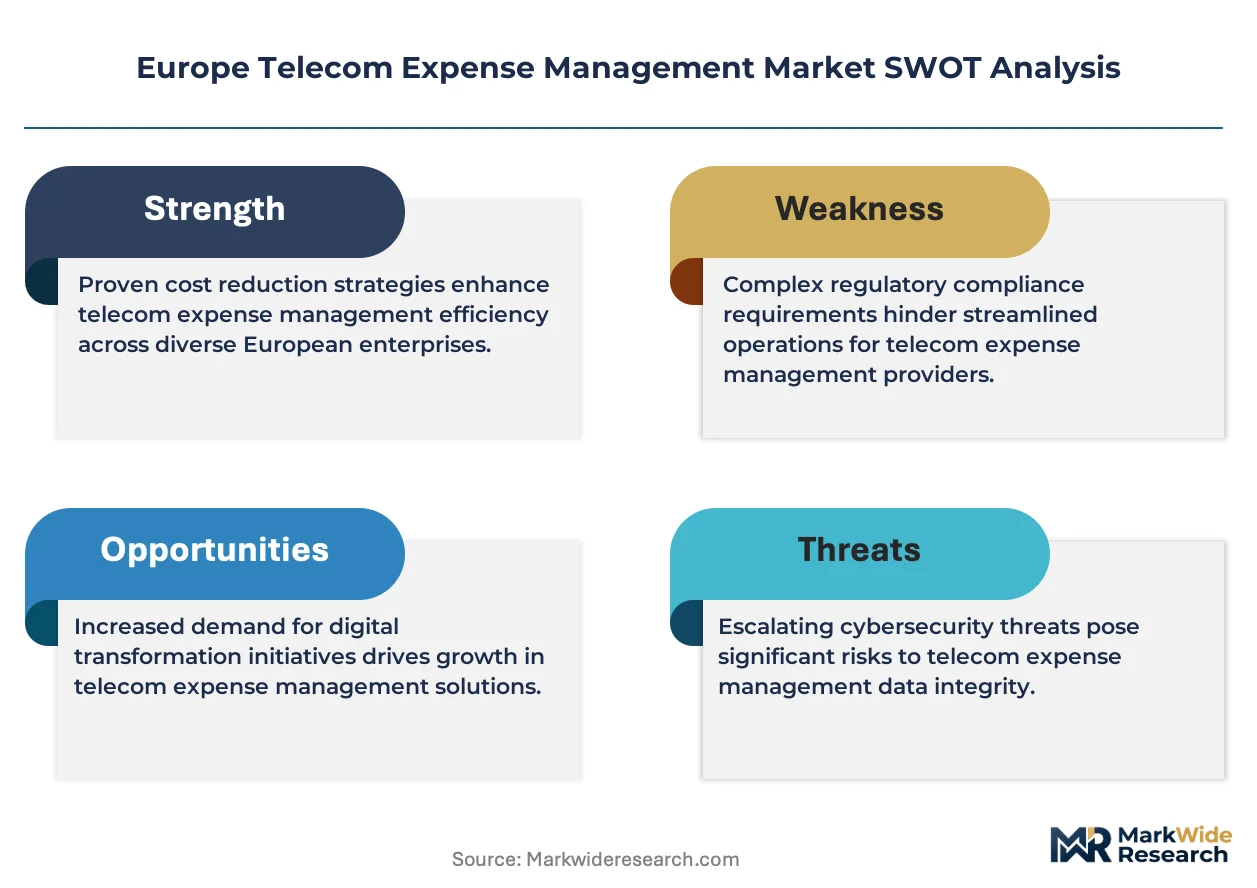
The EU AI Act and GDPR compliance requirements are forcing TEM vendors to rebuild platform architectures around audit trails, consent management, and data residency controls. Large European banking groups now demand automated invoice validation that satisfies both operational efficiency mandates and strict supervisory scrutiny.
Growth Catalysts
- GDPR Article 32 security obligations:Financial services firms in Germany and France must demonstrate technical and organizational measures for telecom data processing, creating mandatory procurement of compliant TEM platforms.
- 5G estate expansion:Mobile device and IoT endpoint proliferation across European manufacturing and logistics verticals generates unmanaged spend requiring centralized visibility tools.
- Cloud migration acceleration:Mid-market enterprises in the United Kingdom are abandoning spreadsheet-based tracking for subscription analytics with faster deployment cycles.
Market Restraints
- Carrier billing fragmentation:European telecom markets maintain heterogeneous invoice formats and tariff structures across national operators, increasing platform integration costs.
- Data residency infrastructure:Banking and defense verticals require on-premises or sovereign cloud deployments that extend implementation timelines and raise total cost of ownership.
- Legacy ERP entrenchment:Deep integration with SAP and Oracle systems in German industrial conglomerates creates switching friction that slows platform replacement cycles.
Strategic Opportunities
- Eastern European underpenetration:Poland, Czech Republic, and Romania show low TEM adoption despite accelerating digital transformation programs in their banking sectors.
- EU Green Deal convergence:Carbon accounting mandates for Scope 3 emissions create demand for TEM platforms that track device lifecycle and e-waste disposal documentation.
- AI-powered anomaly detection:Machine learning modules that flag usage pattern deviations are integrating with existing expense platforms to prevent bill shock before invoice generation.
Industry Challenges
- Multi-vendor data normalization:Engineering teams struggle to harmonize call detail records from disparate European carriers into unified analytics schemas.
- Cross-border compliance staffing:Shortages of legal-technical hybrid talent familiar with both telecom regulations and data protection frameworks constrain vendor expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Telecom Expense Management Market |
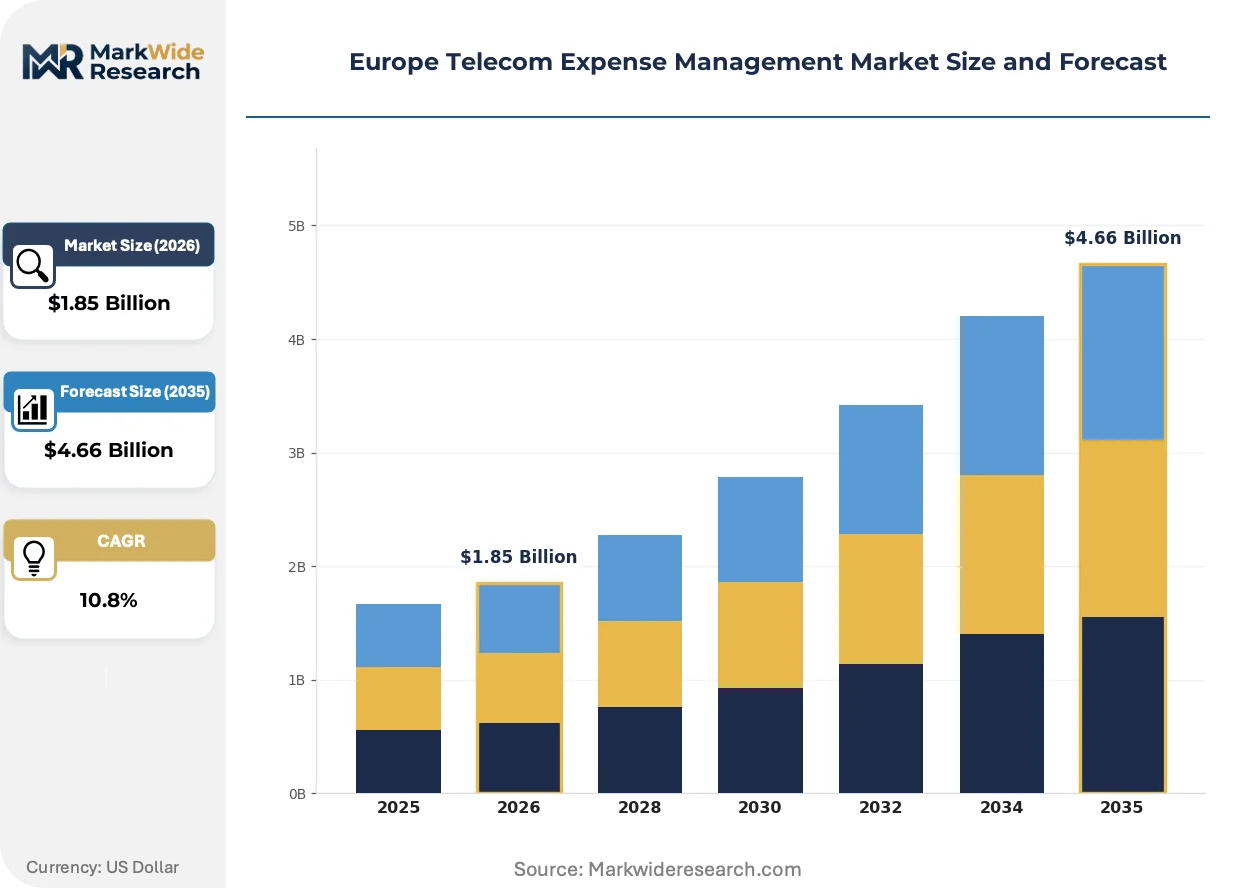
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.66 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution/Offering: Invoice Management, Contract Management, Inventory Management, Usage Analysis, Dispute Management Deployment: On-Premises, Cloud-Based, Hybrid, Hosted Industry Vertical: Telecommunications, Manufacturing, Banking & Finance, Public Sector, Education End User: Enterprises, Managed Service Providers, Value-Added Resellers, System Integrators |
| Companies Covered | Accenture PLC, CGI, Inc., Calero-MDSL Ltd, Tangoe, Inc., Sakon, Inc., Avotus Corporation, Brightfin, NTT Data Corporation, Vodafone Group Plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Telecom Expense Management Market Shifts & Advancements
Telecom expense management is pivoting from retrospective invoice processing toward predictive spend orchestration. Three developments are compressing implementation timelines and reshaping buyer expectations across European enterprise segments.
Embedded analytics engines are integrating directly with carrier APIs to enable real-time rate deck comparisons and instant contract compliance alerts. German automotive manufacturers and French pharmaceutical groups are deploying these modules to catch tariff misalignments before monthly close. The technology is integrating procurement and finance workflows into unified control towers that compress dispute resolution cycles from weeks to hours.
The EU AI Act's risk classification framework is mandating human oversight for automated decision-making in high-stakes financial contexts. TEM platforms processing usage data for banking clients must now embed explainable AI features and documentation trails. Vendors serving the United Kingdom and German banking sectors are rebuilding algorithmic modules to satisfy these governance requirements ahead of enforcement deadlines.
Subscription-based commercial models are displacing perpetual license structures across mid-market procurement. French and Dutch enterprises now expect consumption-aligned pricing with embedded implementation support rather than upfront capital deployment. This shift is visible most acutely among technology and professional services firms with distributed workforces requiring rapid mobile estate scaling.
Europe Telecom Expense Management Market Segmentation
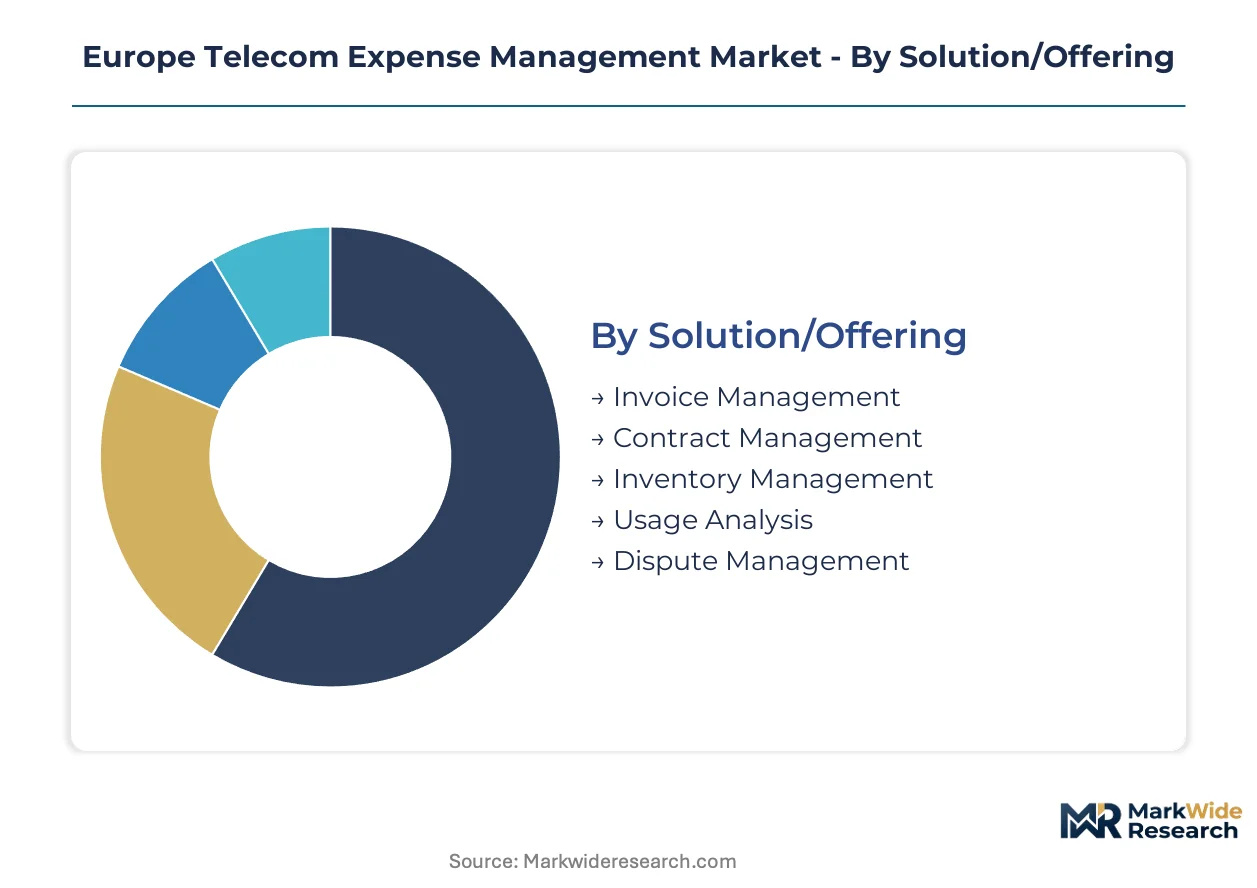
Segmentation in the Europe Telecom Expense Management Market reveals how procurement priorities diverge across infrastructure choices, regulatory exposure, and buyer sophistication. Understanding these divides helps vendors calibrate platform architectures and pricing models to specific buyer readiness levels.
Solution/Offering:
Capital intensity varies sharply across solution modules, with integration-heavy platforms demanding substantially higher upfront engineering investment than standalone analytics tools.
- Invoice Management:Platforms automate validation of carrier bills against contractual rate decks and service inventory databases. German banking groups and French public sector agencies drive demand as they seek to eliminate manual reconciliation workflows and reduce payment leakage across multi-vendor telecom estates.
- Inventory Management:Modules track physical and virtual asset lifecycles, from mobile device procurement through end-of-life disposal documentation. Manufacturing conglomerates in the United Kingdom prioritize these capabilities to satisfy REACH compliance obligations and align with EU Green Deal reporting requirements for Scope 3 emissions.
- Contract Management:Repositories centralize tariff agreements, amendment history, and compliance milestones. Mid-market enterprises favor lightweight implementations.
- Usage Analysis:Analytics engines process call detail records to identify optimization opportunities. Cloud-native vendors dominate this segment.
- Dispute Management:Workflow tools automate carrier billing dispute initiation, documentation, and resolution tracking. Adoption concentrates among enterprises with >500 mobile lines.
Invoice Management absorbs the bulk of installed capacity; Inventory Management is expanding most quickly as sustainability compliance tightens.
Deployment:
Deployment choice hinges on data residency mandates and internal IT maturity, with sovereign requirements pushing banking clients toward controlled infrastructure.
- On-Premises:Installations within client data centers satisfy strict data localization requirements. German and French banking regulators mandate these configurations for processing sensitive usage records.
- Cloud-Based:Multi-tenant SaaS platforms deliver rapid implementation and consumption-aligned pricing. United Kingdom mid-market enterprises and Dutch professional services firms favor this model for distributed workforce scaling.
- Hybrid:Architectures split sensitive processing on-premises while leveraging cloud analytics for non-critical workloads. Automotive manufacturers in Germany deploy hybrid models to protect proprietary mobility data.
- Hosted:Single-tenant managed deployments in vendor-controlled facilities. Public sector buyers in France prefer hosted arrangements for audit trail separation.
Cloud-Based deployments command the largest share of new bookings; Hybrid configurations are climbing the fastest as regulated industries seek architectural compromise.
Industry Vertical:
Vertical differentiation reflects varying tolerance for operational risk and procurement complexity, with financial services imposing the most stringent governance requirements.
- Banking & Finance:Institutions demand audit trails, consent management, and explainable AI to satisfy EU AI Act risk classifications. German Landesbanken and French mutual banks lead platform procurement.
- Telecommunications:Carriers deploy TEM tools internally to manage wholesale interconnect costs and roaming settlement complexity. BT Group and Deutsche Telekom maintain sophisticated in-house platforms.
- Manufacturing:IoT endpoint proliferation across production facilities drives unmanaged spend. German automotive suppliers and Italian industrial equipment makers seek centralized visibility.
- Public Sector:Government bodies prioritize contract compliance and spend transparency. CGI and Sopra Steria anchor relationships across French and United Kingdom agencies.
- Education:Universities manage distributed campus networks and research collaboration tools. Procurement concentrates through consortium frameworks.
Banking & Finance absorbs the bulk of premium platform investment; Manufacturing is gaining share fastest as 5G-enabled IoT estates expand.
End User:
Buyer type determines implementation approach, with direct enterprises demanding customization while intermediaries seek repeatable deployment playbooks.
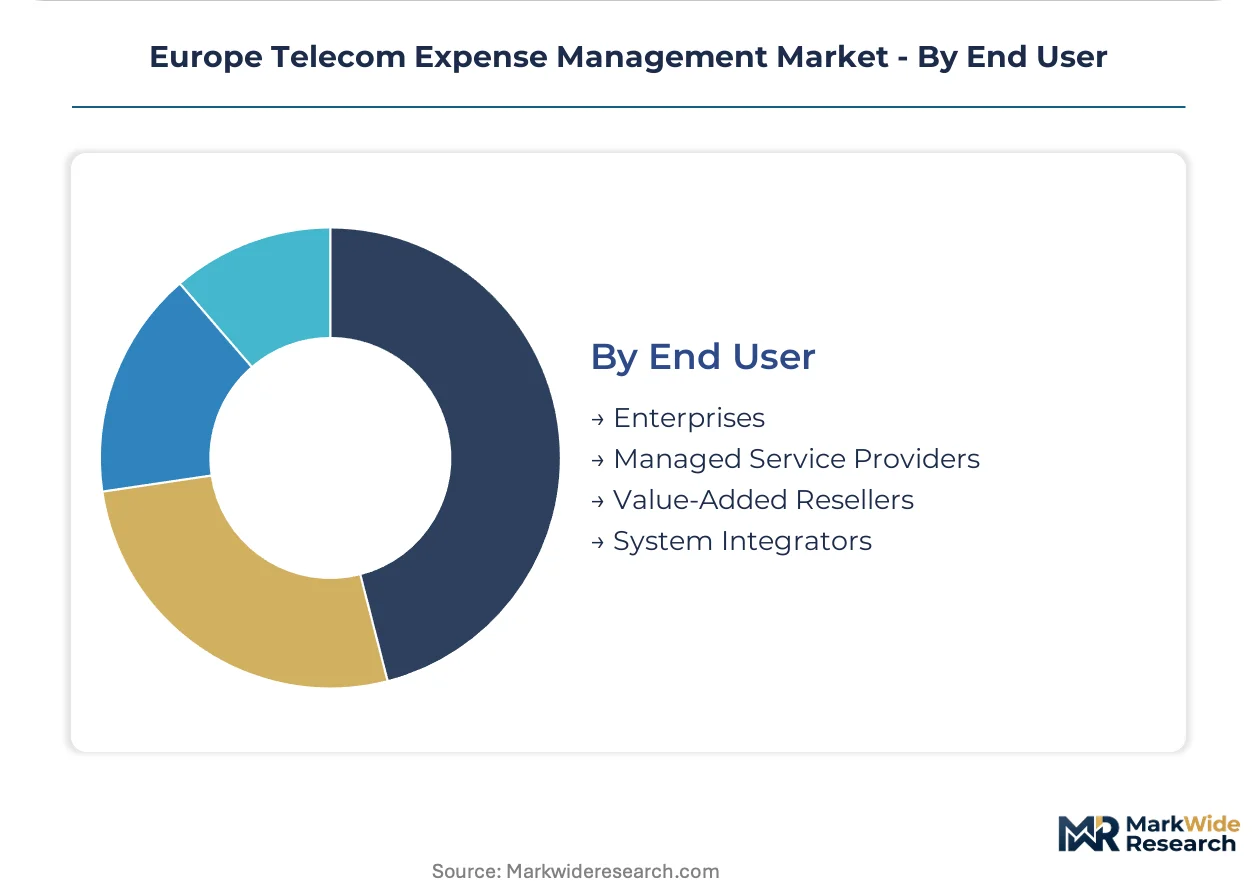
- Enterprises:Direct purchasers with dedicated procurement and IT teams. Large European banking groups and industrial conglomerates in Germany negotiate bespoke platform configurations.
- Managed Service Providers:Third-party operators delivering TEM as a bundled service. United Kingdom and Netherlands markets show strong MSP penetration among mid-market clients.
- Value-Added Resellers:Channel partners embedding TEM within broader telecom procurement relationships. French and Italian markets maintain active reseller ecosystems.
- System Integrators:Consulting firms integrating TEM into digital transformation programs. Accenture and Deloitte leverage existing ERP implementation relationships.
Enterprises retain the dominant share of direct platform licensing; Managed Service Providers are expanding most quickly as subscription models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform consumption concentrates in Western European financial centers while implementation services cluster near client headquarters. Germany, France, and the United Kingdom absorb the majority of enterprise license value, though Eastern European banking sectors now drive fastest adoption velocity.
Germany
Landesbanken and automotive suppliers anchor demand for on-premises invoice validation platforms. GDPR Article 32 technical measures and BaFin supervisory requirements mandate audit-trail documentation for all telecom data processing. Munich and Frankfurt banking clusters deploy hybrid cloud architectures to satisfy data residency while accessing real-time analytics.
France
Mutual banks and public sector agencies prioritize contract compliance modules with embedded consent management. CNIL guidance on automated decision-making shapes platform procurement specifications for high-volume expense processing. Paris-based pharmaceutical groups and Lyon manufacturing clusters adopt subscription analytics for distributed workforce scaling.
United Kingdom
Mid-market professional services firms and fintech operators drive cloud-native TEM adoption. Post-Brexit data adequacy arrangements complicate cross-border processing for multinational banking groups. London financial services and Manchester technology corridors favor rapid-deployment SaaS models over legacy system integration.
Netherlands
Dutch professional services and logistics enterprises seek consumption-aligned pricing for mobile estate expansion. The Authority for Personal Data enforces strict purpose limitation on telecom usage analytics. Amsterdam and Rotterdam corporate headquarters integrate TEM platforms with existing SAP environments for procurement workflow automation.
Poland
Banking sector digital transformation programs generate underpenetrated demand for automated expense validation. The national data protection authority applies GDPR implementation standards with limited local precedent for telecom-specific compliance. Warsaw financial district and Krakow shared service centers represent emerging procurement opportunities for platform vendors.
Europe Telecom Expense Management Market Competitive Landscape
Capital-heavy system integrators compete with asset-light software specialists for platform deployment contracts. The vendor base organizes around consulting-led transformation programs, standalone SaaS analytics, and carrier-embedded managed services. Three archetypes dominate: global consultancies bundling TEM into ERP modernization, pure-play vendors offering rapid-implementation cloud tools, and telecom operators white-labeling expense capabilities. Competitive positioning hinges on geographic compliance expertise and pre-built carrier integrations rather than proprietary technology differentiation.
Within the consulting-led tier, Accenture PLC and CGI, Inc. anchor positions through existing digital transformation relationships and public sector contracting authority. Calero-MDSL Ltd exemplifies the specialized software archetype with modular inventory management approaches. These three entities represent distinct go-to-market strategies: Accenture leverages cross-selling into enterprise resource planning implementations, CGI maintains deep French and United Kingdom government relationships, and Calero-MDSL targets ERP integration scenarios for mid-market manufacturing clients.
| Leading Market Players |
|---|
| Accenture PLC |
| CGI, Inc. |
| Calero-MDSL Ltd |
| Tangoe, Inc. |
| Sakon, Inc. |
| Avotus Corporation |
| Brightfin |
| NTT Data Corporation |
| Vodafone Group Plc |
| Others |
Supply & Pricing Matrix
Backward integration into carrier API infrastructure anchors both supply position and pricing power for European TEM vendors serving German and French banking clients. Platform providers that control direct data pipelines from Deutsche Telekom and Orange command premium subscription rates while reducing third-party integration costs.
Pricing Analysis
Margin tightening in cloud-native tiers reflects hyperscaler compute cost pass-through and aggressive SaaS competition from pure-play vendors. Subscription pricing stratifies across enterprise, mid-market, and SMB tiers with differentiation anchored in GDPR audit-trail depth and pre-built carrier integration counts. Banking verticals show lowest price sensitivity due to BaFin and ACPR compliance mandates, while UK professional services firms drive hardest on consumption-aligned terms.
Supply Chain Analysis
Single-source vulnerability sits with Ireland-based hyperscaler regions hosting multi-tenant analytics workloads for mid-market European clients. Platform engineering draws from Indian development centers, German cloud infrastructure, and US algorithmic licensing for AI modules. Tariff exposure runs through transatlantic data routing dependencies. Distribution runs through direct enterprise sales teams in Frankfurt and Paris, MSP channels in London and Amsterdam, and systems integrator partnerships with Accenture and CGI.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained compliance engineering talent props pricing for GDPR-certified platforms, with certified solution architects commanding 40% implementation premiums over uncertified competitors.
For Market Incumbents: Cement data residency architecture leadership through sovereign cloud certifications in Germany and France ahead of EU AI Act enforcement waves. Acquire specialized inventory management modules to block Calero-MDSL's ERP integration path. Deepen carrier API exclusivity to raise switching costs for banking clients evaluating platform replacement. For New Entrants and Emerging Players: Enter via Polish and Czech banking sectors where TEM penetration lags digital transformation program acceleration. Target manufacturing IoT visibility gaps in Italian industrial corridors underserved by legacy invoice-focused platforms. Lead with carbon accounting integration to capture EU Green Deal reporting budgets. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to consulting-led transformation platforms seeking telecom expense capabilities. Five-to-ten year viability favors vendors with embedded carrier relationships and modular ERP integration architecture. Watch for GDPR enforcement intensity in German Landesbanken as inflection signal for compliance-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier API Direct Integration | Eliminates third-party data normalization costs for Deutsche Telekom and Orange billing feeds. |
| GDPR Certification Investment | Unlocks BaFin-mandated procurement pathways in German banking clusters. |
| Inventory Management Module Acquisition | Captures REACH compliance documentation workflows in UK manufacturing verticals. |
| Polish Banking Sector Expansion | Exploits underpenetrated demand from Warsaw digital transformation programs. |
| Carbon Accounting Platform Integration | Aligns with EU Green Deal Scope 3 reporting requirements for device lifecycle tracking. |
Research Methodology
EU regulatory filings, carrier tariff disclosure databases, and enterprise software procurement records formed the secondary backbone for market sizing. Primary interviews with TEM platform engineers, banking compliance officers, carrier wholesale pricing managers, and ERP integration specialists validated segment assumptions. Bottom-up deployment counts triangulated against top-down enterprise IT spending estimates across the analysis window.
Historical trendline analysis of invoice processing automation adoption informed projection trajectories across deployment model, organization size, industry vertical, and geographic regulatory cluster dimensions. CAGRs derived from segmented growth rate reconciliation against aggregate market boundary conditions. Forecast inputs incorporated GDPR enforcement timeline uncertainty and 5G estate expansion velocity in manufacturing IoT segments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU AI Act enforcement acceleration or carrier consolidation reducing API access competition. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Canada Hosted PBX Market
Telecommunications
Diameter Signaling Control Market
Telecommunications
Global 5G Enterprise Market
Telecommunications
5G Technology Market
Telecommunications
Smart Feature Phone Market
Telecommunications
Indonesia ICT Market
Telecommunications
Mobile Voice Market
Telecommunications
Global Hosted PBX Market
Telecommunications
Turkey Telecom Market
Telecommunications
Egypt ICT Market
Telecommunications
Land Professional Mobile Radio Market
Telecommunications
Telecom Managed Services Market
Telecommunications
Tetra Terminals Market
Telecommunications
5G in Defense Market
Telecommunications
Global Underwater Acoustic Communication Market
Telecommunications
Global 5G in Healthcare Market