
 Japan Contract Logistics Market | 2026-2036
Japan Contract Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Contract Logistics Market Foresight
JIS Z 7252 hazardous material handling certification is rotating the competitive set, disqualifying smaller operators from pharmaceutical and chemical contracts. Kintetsu World Express leverages its Osaka-Kobe port dominance to anchor automotive parts distribution for Toyota suppliers. Nippon Express Holdings sustains nationwide coverage through rail-linked regional depots that competitors cannot replicate. Daifuku Co. Ltd. specializes in automated warehouse robotics, differentiating on labor cost absorption rather than transport scale.
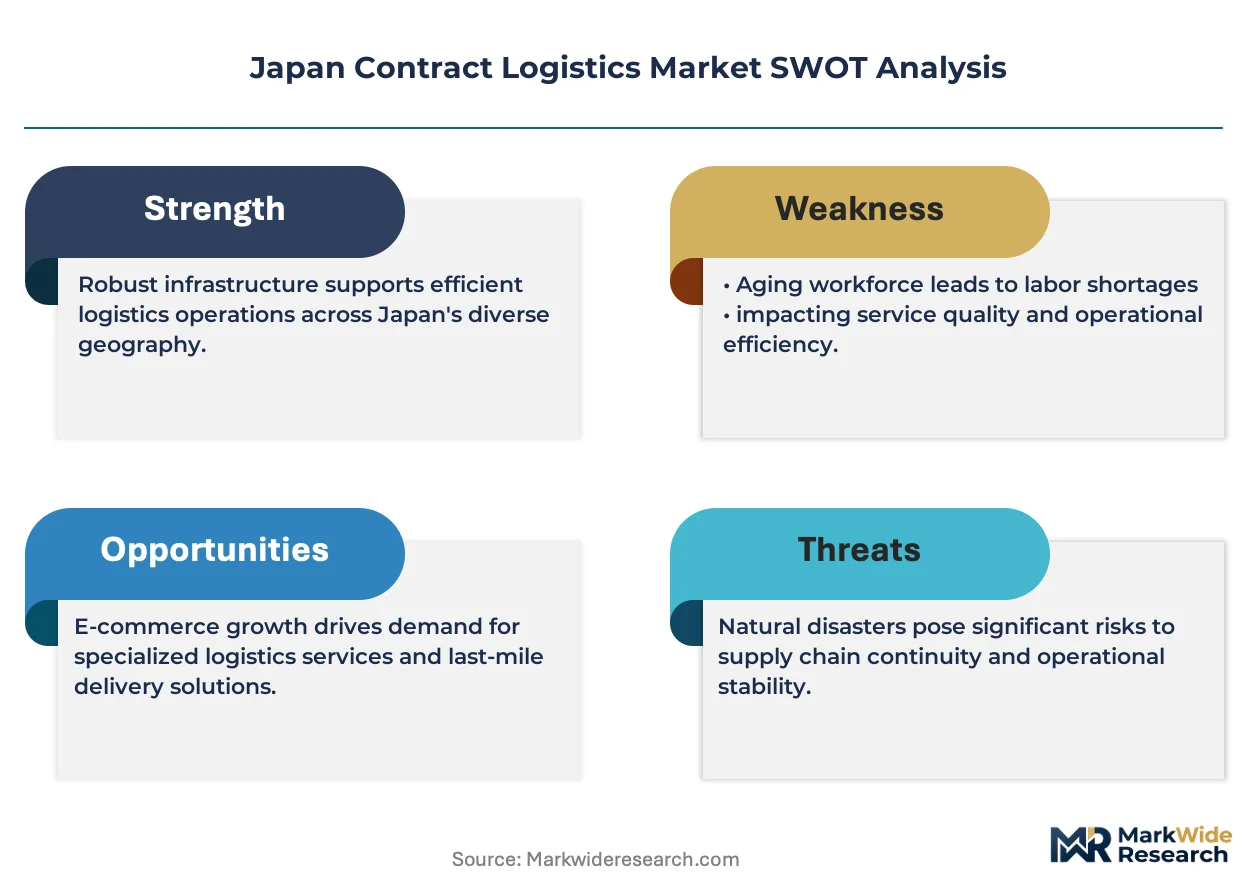
Contract logistics encompasses the outsourced management of transportation, warehousing, and distribution activities governed by multi-year service agreements with measurable KPIs including inventory accuracy thresholds and order cycle times. The primary purpose is to convert fixed logistics infrastructure into variable costs while injecting technology-driven visibility. Warehousing claims the deepest margin pools as automated facilities command premium pricing against conventional stockholding. E-commerce end users represent the fastest-expanding demand channel, pressuring operators to compress last-mile delivery windows. Transportation retains the largest revenue base but faces structural pressure from driver shortages and fuel cost pass-through limits.
METI enforces supply chain resilience standards under the Economic Security Promotion Act, compelling logistics providers to document contingency routing and dual-source critical lanes. PMDA mandates GDP-compliant cold chain documentation for pharmaceutical distribution, elevating compliance costs for temperature-controlled segments. JIS standards for warehouse automation interoperability further segment the technology tier between robotic-enabled operators and manual facilities. Stakeholders must weigh capital deployment toward automation against the risk of regulatory compliance costs outpacing contract pricing power.
Market Dynamics
METI's supply chain digitalization mandates are compressing operator margins while forcing capital redeployment toward IoT-enabled visibility infrastructure. The Kanto corridor's freight density premium is accelerating warehouse automation investments as labor shortages bite deeper.
Growth Catalysts
- Biologics cold chain expansion:Temperature-sensitive pharmaceutical volumes are pulling specialized logistics demand as PMDA GDP compliance requirements tighten documentation standards.
- METI IoT interoperability mandates:Government pressure for supply chain transparency is creating contract opportunities for technology-integrated operators.
- Automotive just-in-sequence demands:Toyota supplier networks require synchronized parts delivery that only dedicated contract logistics infrastructure can sustain.
Market Restraints
- Diesel cost pass-through limits:Fuel price volatility cannot be fully recovered through contract pricing clauses, squeezing transportation margins.
- Driver workforce contraction:Japan's aging logistics labor pool is restricting fleet expansion capacity regardless of equipment availability.
- JIS Z 7252 certification barriers:Hazardous material handling requirements are disqualifying smaller operators from pharmaceutical and chemical contract pools.
Strategic Opportunities
- Kansai port automation:Osaka-Kobe container throughput growth is creating demand for robotic warehouse capacity that domestic operators underprovide.
- E-commerce same-day compression:Last-mile delivery window tightening is opening premium pricing tiers for micro-fulfillment networks in Greater Tokyo.
- Rail-linked regional depots:Underutilized JR Freight infrastructure offers intermodal cost advantages for operators with capital to secure siding access.
Industry Challenges
- WMS-ERP integration complexity:Legacy enterprise systems at Japanese manufacturers resist API connectivity with modern logistics platforms.
- Automation capex recovery timelines:Five-to-seven-year payback periods on robotic warehouse systems exceed typical contract durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Contract Logistics Market |
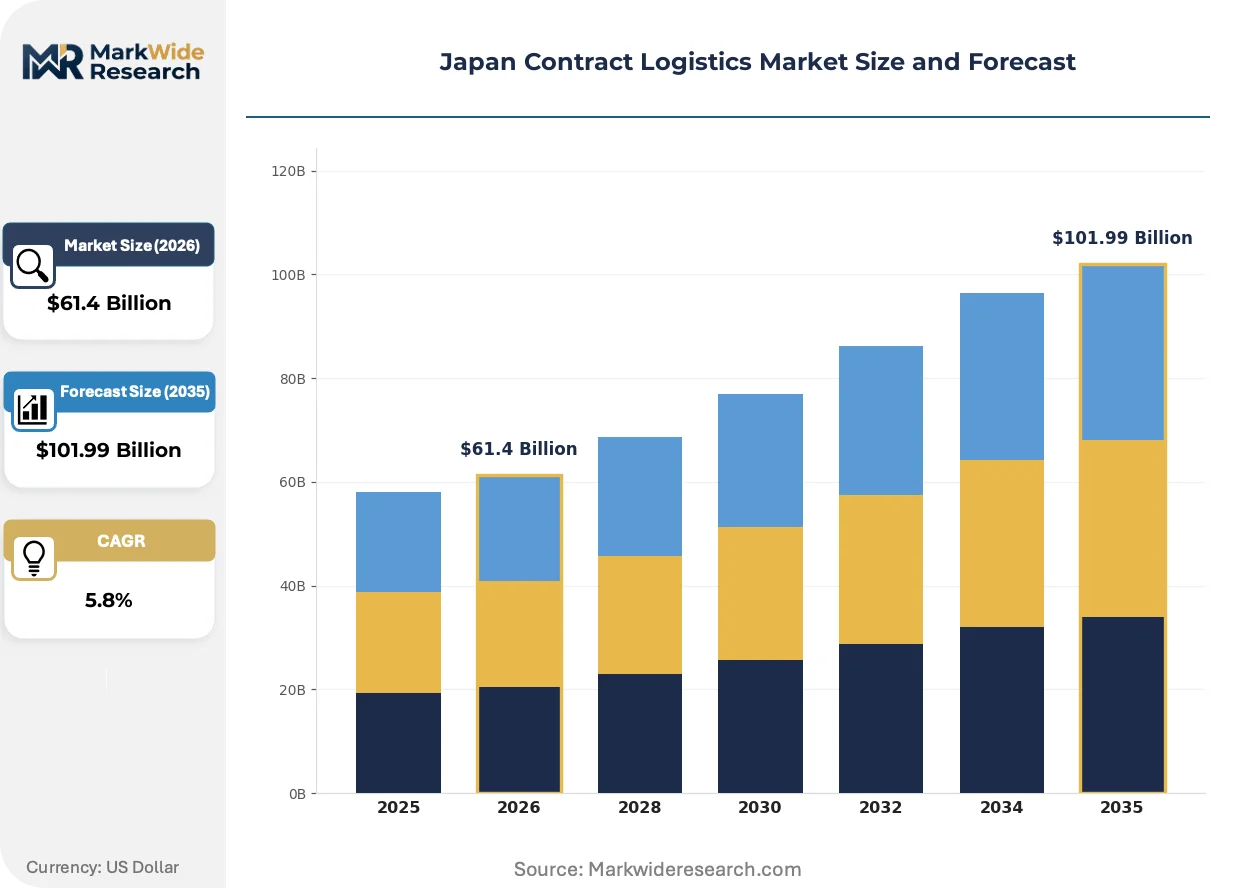
| Market Size in 2026 | $61.4 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
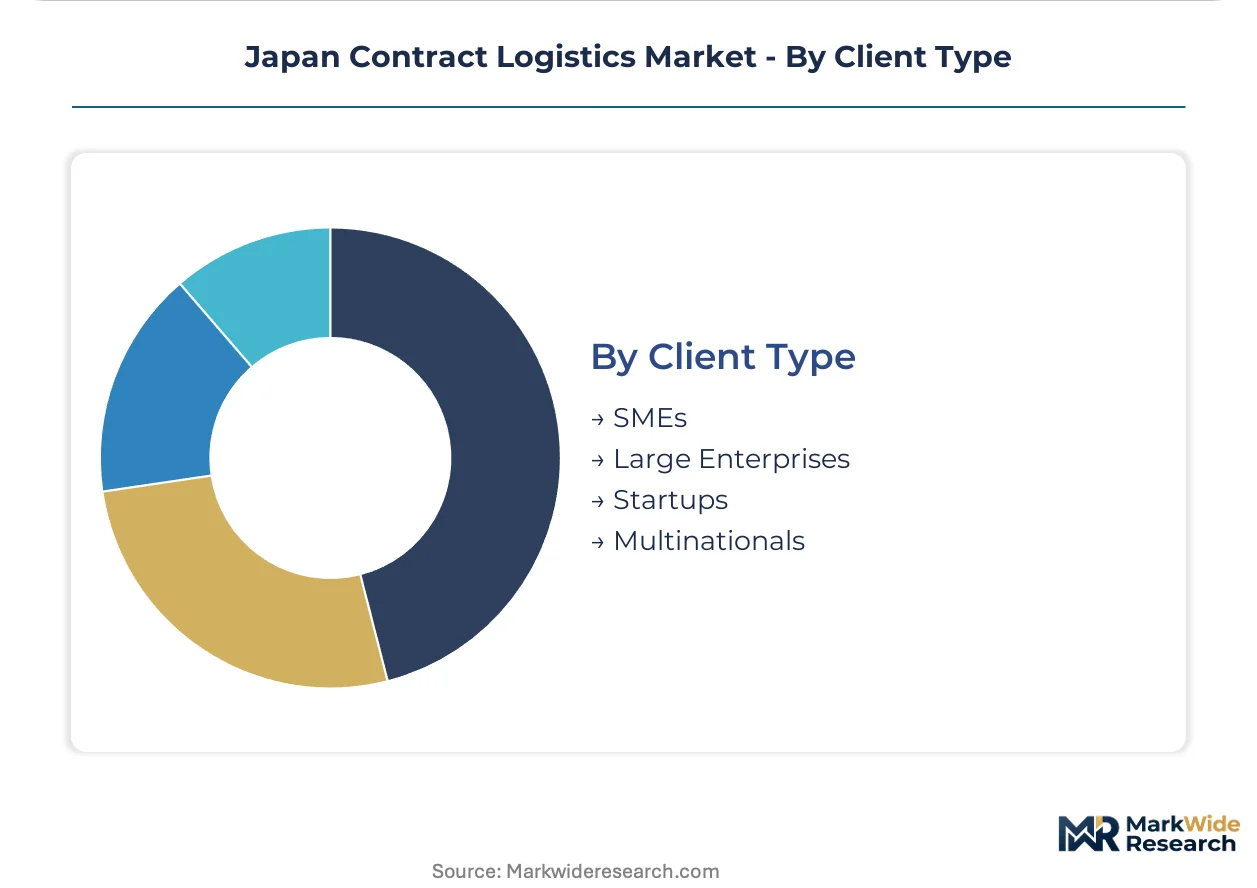
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Distribution End User: Retail, E-commerce, Automotive, Pharmaceuticals Technology: WMS, TMS, RFID, IoT Solutions Client Type: SMEs, Large Enterprises, Startups, Multinationals |
| Companies Covered | Kuehne + Nagel, Kintetsu World Express, Nippon Express Holdings Inc., SBS Holdings, Yamato Transport, Yusen Logistics, CEVA Logistics, Daifuku Co. Ltd., Hitachi Transport System, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Contract Logistics Market Shifts & Advancements
Warehouse robotics and predictive freight matching are compressing operational slack across Japan's logistics networks. These shifts are redrawing competitive boundaries between asset-heavy incumbents and technology-native challengers.
Automated storage and retrieval systems are displacing conventional forklift operations in ambient and chilled facilities. Pharmaceutical distributors and automotive parts suppliers are adopting these systems fastest, driven by JIS standards for warehouse automation interoperability. Labor cost absorption is becoming the primary competitive differentiator as wage pressures intensify.
PMDA's GDP-compliant cold chain documentation mandates are elevating compliance costs across pharmaceutical distribution. Operators must now maintain continuous temperature monitoring with audit trails that satisfy regulatory inspection. Biologics shippers are consolidating vendor relationships toward certified specialists with proven documentation systems.
Outcome-based logistics contracts are replacing rate-per-pallet pricing in high-value manufacturing verticals. Automotive and electronics producers now tie provider compensation to inventory accuracy thresholds and order cycle time performance. This procurement evolution concentrates volume with operators capable of real-time KPI visibility.
Japan Contract Logistics Market Segmentation

Segmentation in Japan's contract logistics market reveals where capital deployment and regulatory compliance create divergent margin structures. Service type and end-user verticals determine pricing power, while technology tier and client scale dictate contract duration and automation requirements.
Service Type:
Warehousing commands the deepest margin pools through automated facilities, while transportation retains volume leadership despite structural cost pressures.
- Warehousing:Automated storage and retrieval systems in ambient and chilled facilities absorb labor cost inflation. Pharmaceutical distributors and automotive parts suppliers in the Kanto corridor adopt these systems fastest under JIS automation interoperability standards.
- Transportation:Fleet operations face diesel cost pass-through limits and driver workforce contraction. METI supply chain resilience standards under the Economic Security Promotion Act compel contingency routing documentation that elevates compliance overhead.
- Freight Forwarding:Osaka-Kobe port throughput growth drives demand for customs brokerage and documentation services.
- Distribution:Last-mile networks in Greater Tokyo compress delivery windows for e-commerce same-day requirements.
The dominant share belongs to Transportation, while Warehousing is closing the gap fastest through premium pricing on robotic capacity.
End User:
Vertical specialization separates certified operators from commodity competitors through regulatory barriers and performance KPIs.
- Pharmaceuticals:Temperature-sensitive biologics expansion pulls specialized cold chain demand. PMDA GDP-compliant documentation mandates elevate compliance costs and consolidate vendor relationships toward certified specialists.
- E-commerce:Same-day delivery compression in Greater Tokyo opens premium pricing tiers for micro-fulfillment networks. METI IoT interoperability mandates create contract opportunities for technology-integrated operators serving this channel.
- Automotive:Toyota supplier networks require synchronized just-in-sequence parts delivery.
- Retail:Conventional stockholding faces margin pressure from inventory accuracy thresholds.
Pharmaceuticals captures the steepest expansion trajectory on biologics growth, though E-commerce claims the largest incremental volume gains.
Technology:
Technology tier determines contract win rates as Japanese manufacturers modernize legacy enterprise systems.
- WMS:Warehouse management systems anchor automated facility operations with real-time inventory visibility.
- TMS:Transportation management platforms optimize routing against driver shortage constraints.
- IoT Solutions:Continuous temperature monitoring with audit trails satisfies PMDA pharmaceutical inspection requirements.
- RFID:Item-level tracking supports outcome-based logistics contracts tied to inventory accuracy thresholds.
IoT Solutions holds the narrowest installed base but the strongest regulatory tailwind, while WMS maintains the broadest penetration.
Client Type:
Scale concentration shapes automation capex recovery timelines and contract duration negotiations.
- Large Enterprises:Multi-year agreements with measurable KPIs including order cycle times and inventory accuracy thresholds. Five-to-seven-year automation payback periods align with contract durations.
- Multinationals:Global supply chain visibility requirements drive WMS-ERP integration complexity against legacy Japanese manufacturer systems.
- SMEs:Price-sensitive demand for variable-cost logistics conversion without capital deployment.
- Startups:Flexible contract terms for volume-scaling e-commerce operations.
Large Enterprises command the dominant contract value share, while Multinationals are expanding their vendor consolidation pace fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's supply chain digitalization mandates under the Economic Security Promotion Act are accelerating infrastructure investment across Japan's major industrial corridors. Regional logistics demand concentrates where automotive, pharmaceutical, and e-commerce clusters intersect with port and rail access.
Kanto/Tokyo
Greater Tokyo's e-commerce same-day delivery compression is pulling micro-fulfillment network expansion. METI IoT interoperability mandates create contract opportunities for technology-integrated operators serving this channel. The Keihin industrial belt anchors pharmaceutical cold chain demand as PMDA GDP compliance requirements tighten.
Kansai/Osaka
Osaka-Kobe port throughput growth drives demand for customs brokerage and robotic warehouse capacity. Automotive just-in-sequence demands from Toyota supplier networks require synchronized parts delivery infrastructure. JIS Z 7252 hazardous material certification requirements rotate the competitive set for chemical and pharmaceutical contracts.
Chubu/Nagoya
Automotive parts distribution dominates regional contract logistics demand through Toyota's supplier ecosystem. Rail-linked regional depots offer intermodal cost advantages for operators securing JR Freight siding access. METI supply chain resilience standards compel contingency routing documentation that elevates compliance overhead.
Kyushu
Semiconductor and electronics manufacturing clusters in Fukuoka and Kumamoto generate specialized warehousing demand. Underutilized port infrastructure creates opportunities for operators building pharmaceutical cold chain capacity. Regional depots face automation capex recovery challenges against shorter contract durations.
Hokkaido
Agricultural and food processing logistics dominate regional demand with seasonal volume spikes. Temperature-controlled distribution requirements align with PMDA cold chain documentation mandates for pharmaceutical transit. Limited rail connectivity constrains intermodal cost advantages available elsewhere.
Japan Contract Logistics Market Competitive Landscape
Listed leaders compete with private specialists across asset ownership and technology integration dimensions. The market structure shows moderate consolidation around integrated transport-warehousing operators with fragmented competition in specialized cold chain segments. Three archetypes dominate: nationwide rail-linked network operators, port-centric automotive logistics specialists, and automation-focused warehouse robotics providers. Competitive moves concentrate on securing hazardous material certifications and deploying IoT-enabled visibility infrastructure to satisfy METI mandates.
Within the nationwide network tier, Nippon Express Holdings Inc. and Kintetsu World Express exemplify scale-driven operators with rail-linked regional depot coverage. Daifuku Co. Ltd. occupies a distinct position as an automation specialist differentiating on labor cost absorption through robotic warehouse systems rather than transport scale. These three companies represent the strategic spectrum from asset-heavy infrastructure to technology-led differentiation that defines competitive positioning in Japan's contract logistics market.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| Kintetsu World Express |
| Nippon Express Holdings Inc. |
| SBS Holdings |
| Yamato Transport |
| Yusen Logistics |
| CEVA Logistics |
| Daifuku Co. Ltd. |
| Hitachi Transport System |
| Others |
Supply & Pricing Matrix
Long-term multi-year service agreements with measurable KPIs lock in supply access and price visibility for Japanese manufacturers converting fixed logistics infrastructure into variable costs. These contracts anchor cost predictability while METI's IoT interoperability mandates force operators to embed technology premiums into pricing structures.
Pricing Analysis
Certification level creates the primary spread between commodity and premium contract tiers. JIS Z 7252 hazardous material handling certification and PMDA GDP-compliant cold chain documentation separate certified specialists from price-competitive generalists. Cost compression in transportation tiers is intensifying because diesel cost pass-through limits prevent full fuel price recovery. SMEs exhibit the highest price sensitivity, while pharmaceutical multinationals accept premium pricing for compliance-certain operators.
Supply Chain Analysis
Just-in-sequence inventory strategies dominate automotive parts distribution through Toyota supplier networks, while pharmaceutical cold chain operators maintain strategic stockpiles for temperature-sensitive biologics. Japan's contract logistics sector draws from domestic warehouse automation equipment, imported IoT sensors, and specialized refrigerated transport chassis. Single-source vulnerability concentrates in JR Freight rail-linked regional depots where siding access is capacity-constrained. Distribution runs through port-centric hubs at Osaka-Kobe and Tokyo-Yokohama for international freight, with regional depots feeding last-mile networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's contract logistics market sits in early-cycle expansion as biologics cold chain penetration deepens and METI digitalization mandates accelerate technology adoption across previously manual facilities.
For Market Incumbents: Consolidate rail-linked regional depot networks against emerging automation specialists threatening transport-warehousing integration. Secure JIS Z 7252 certification renewals before PMDA tightens pharmaceutical documentation standards. Prioritize backward integration into warehouse robotics manufacturing to absorb labor cost inflation. For New Entrants and Emerging Players: Micro-fulfillment network gaps in Greater Tokyo's e-commerce same-day corridor offer white-space entry points. Kansai port automation underprovision creates demand for robotic warehouse capacity that domestic incumbents cannot satisfy. Target pharmaceutical cold chain documentation services as the most penetrable vertical, leveraging cloud-native IoT platforms against legacy WMS-ERP integration bottlenecks. For Investors and Strategic Acquirers: Automation-focused warehouse robotics providers with proven labor cost absorption models present acquisition targets with defensive moats. Long-term viability hinges on contract duration alignment with five-to-seven-year automation capex recovery timelines. Watch METI enforcement intensity on Economic Security Promotion Act contingency routing documentation as the inflection signal for compliance-cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Z 7252 Certification Investment | Hazardous material handling credentials unlock pharmaceutical and chemical contract pools against uncertified competitors. |
| IoT-Enabled Visibility Infrastructure Deployment | METI interoperability mandates create contract opportunities for technology-integrated operators serving manufacturing verticals. |
| Rail-Linked Regional Depot Expansion | JR Freight siding access secures intermodal cost advantages that truck-dependent competitors cannot replicate. |
| Automated Storage and Retrieval System Installation | Robotic warehouse systems absorb labor cost inflation while commanding premium pricing against conventional stockholding. |
| Outcome-Based Logistics Contract Structuring | Inventory accuracy and order cycle time KPIs tie provider compensation to measurable performance, concentrating volume with capable operators. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with logistics operations directors, pharmaceutical supply chain managers, automotive procurement leads, and METI policy specialists; and secondary validation through customs trade statistics, METI supply chain resilience reports, PMDA GDP compliance filings, and JR Freight infrastructure disclosures. Bottom-up facility-level capacity assessments and top-down national logistics expenditure estimates were triangulated against operator revenue disclosures.
Across the analysis window, the forecasting framework modeled service type segmentation, end-user vertical specialization, technology tier adoption curves, and client scale concentration. CAGRs were derived from regression analysis of historical logistics outsourcing penetration against manufacturing value-added trends. Pharmaceutical cold chain volume trajectories and e-commerce same-day delivery compression rates served as industry-specific demand inputs.
Underlying assumptions cover stable METI enforcement intensity, continued biologics pipeline expansion, and JR Freight capacity availability, with deviation risk concentrated in regulatory compliance cost acceleration and driver workforce contraction severity. Revision becomes warranted when PMDA GDP documentation requirements cross thresholds that disqualify sub-scale operators from contract eligibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
ASEAN Warehousing and Distribution Logistics Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
ASEAN Chemical Logistics Market
Logistics and Shipping
North America Same Day Delivery Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
Mexico Logistics Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
WAN Connected Returnable Transport Asset Tracking Market
Logistics and Shipping
US FTL Brokerage Market