
 Wool Market | 2026-2036
Wool Market Size, Share, and Industry Trends Forecast 2026-2036
Wool Market Outlook
Commodity wool trading margins is narrowing as branded fiber certification commands premium pricing. Südwolle Group leverages vertical integration from raw scouring to dyed tops, securing supply chain control across Central European spinning operations. Loro Piana anchors ultra-fine Merino sourcing through long-term station partnerships in Australia, sustaining its position in luxury apparel. Marzotto Group competes on worsted weaving scale, operating integrated mills that service tailored clothing brands with consistent batch quality.
Wool consists of keratin-based animal fibers with crimped microstructure, typically 15-40 microns in diameter, shorn from sheep and processed through scouring, carding, and combing into yarns or felts for thermal and moisture-wicking applications. Merino fiber dominates premium apparel channels due to sub-20 micron fineness, while Rambouillet supplies broader micron ranges for performance outerwear and upholstery blends. Application demand concentrates in textiles for fashion and technical knitwear, with insulation emerging as a structural growth pocket as building codes tighten thermal efficiency requirements.
Australian Wool Innovation and New Zealand's Ministry for Primary Industries enforce clip certification and ethical sourcing standards that shape export market access for raw fiber. REACH and the EU Green Deal textile strategy impose chemical disclosure and recyclability benchmarks on wool products entering European markets. Stakeholders must monitor evolving traceability mandates and carbon accounting rules that will determine which supply chains retain preferential positioning with sustainability-focused buyers.
Market Dynamics
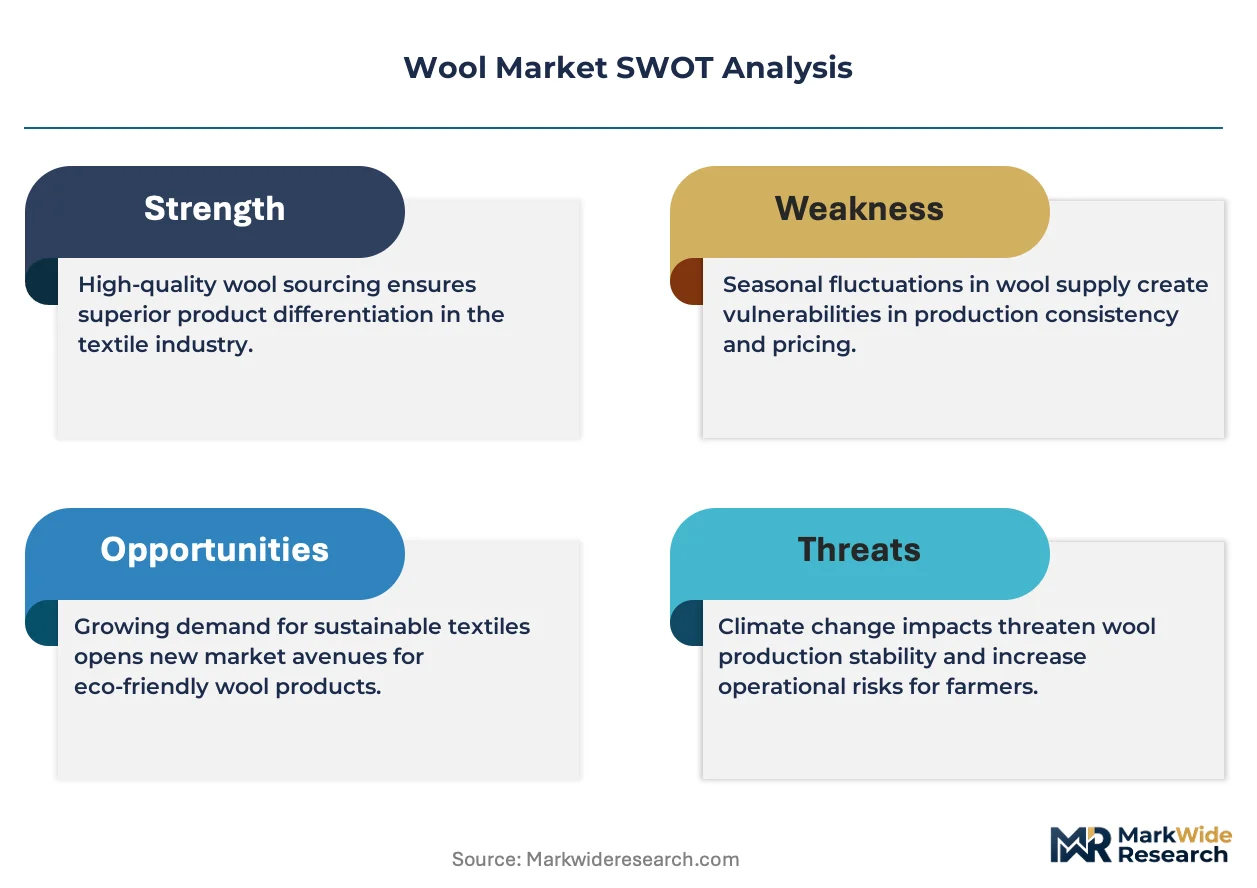
Certified fiber traceability mandates from the EU Green Deal are compressing uncertified wool margins while rerouting procurement toward audited Australian and New Zealand stations with verified carbon accounting.
Growth Catalysts
- EU Green Deal textile strategy:Mandatory chemical disclosure and recyclability benchmarks for wool products entering European markets are accelerating demand for certified fiber with full supply chain documentation.
- Building thermal efficiency codes:Tightened insulation standards across residential and commercial construction are opening structural demand for wool-based natural insulation materials.
- Merino micron fineness:Sub-20 micron fiber from Australian stations commands persistent premium pricing in luxury apparel channels as traceability becomes a purchase prerequisite.
Market Restraints
- Feed price volatility:Drought cycles in Australian pastoral regions create input cost instability that compresses farm-gate margins independent of fiber quality.
- Synthetic fiber substitution:Recycled polyester and bio-based alternatives from chemical manufacturers displace wool in mid-market outerwear and activewear segments.
- Scouring chemical restrictions:REACH limits on wool grease processing chemicals constrain European scouring capacity and raise compliance costs for imported raw fiber.
Strategic Opportunities
- Carbon-negative insulation:Wool's inherent carbon sequestration properties position it for specification in green building projects pursuing net-zero certifications.
- Blockchain traceability platforms:Integration of distributed ledger systems with clip certification enables real-time provenance verification for sustainability-focused luxury buyers.
- India technical knitwear:Underpenetrated demand for performance wool blends in Indian outdoor and athletic apparel presents white space for micron-optimized fiber grades.
Industry Challenges
- Shearing labor shortages:Seasonal workforce gaps in Australian wool-growing regions constrain clip volumes and raise contracting costs for station operators.
- Multi-standard certification complexity:Reconciling Australian Wool Innovation clip protocols with EU Green Deal textile requirements creates administrative overhead for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wool Market |
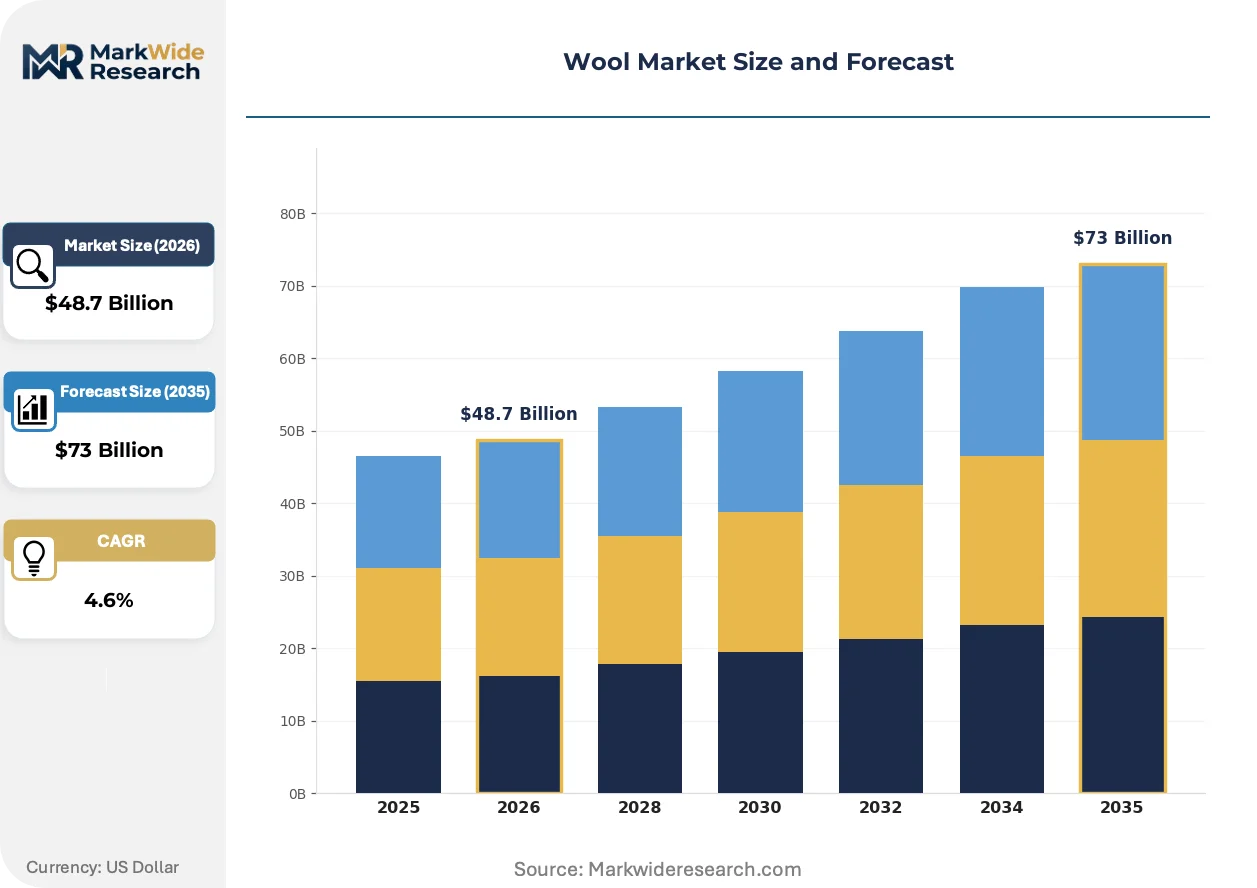
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Merino, Rambouillet, Corriedale, Shetland Application: Textiles, Upholstery, Insulation, Crafts End User: Fashion Industry, Home Furnishing, Automotive, Industrial Distribution Channel: Wholesale, Retail, E-commerce, Direct Sales |
| Companies Covered | Pendleton Woolen Mills, Südwolle Group, Loro Piana, Xinao Textiles Inc., The Woolmark Company, Indorama Ventures Public Company Limited, Marzotto Group, Icebreaker, Zegna Baruffa Lane Borgosesia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wool Market Strategic Shifts
Digital traceability infrastructure and regenerative agriculture verification are reconfiguring how wool fiber quality gets priced and procured across apparel and technical end-uses.
Blockchain-based provenance systems are digitizing supply chain documentation from farm to finished garment. Luxury fashion houses and premium outdoor brands are mandating these platforms for supplier qualification. This technology is digitizing audit costs while compressing time-to-certification for station partnerships.
REACH chemical disclosure requirements are forcing reformulation of wool scouring and dyeing processes across European processing facilities. The regulation is accelerating investment in closed-loop water and solvent recovery systems. Italian and German finishing mills are responding by consolidating supplier bases to audited partners with pre-verified chemical profiles.
Buyers are consolidating procurement around long-term station contracts with embedded sustainability clauses. This model displaces spot-market purchasing for premium micron grades. Australian Merino producers with regenerative agriculture certification are capturing preferential offtake agreements from European luxury spinners.
Wool Market Segmentation
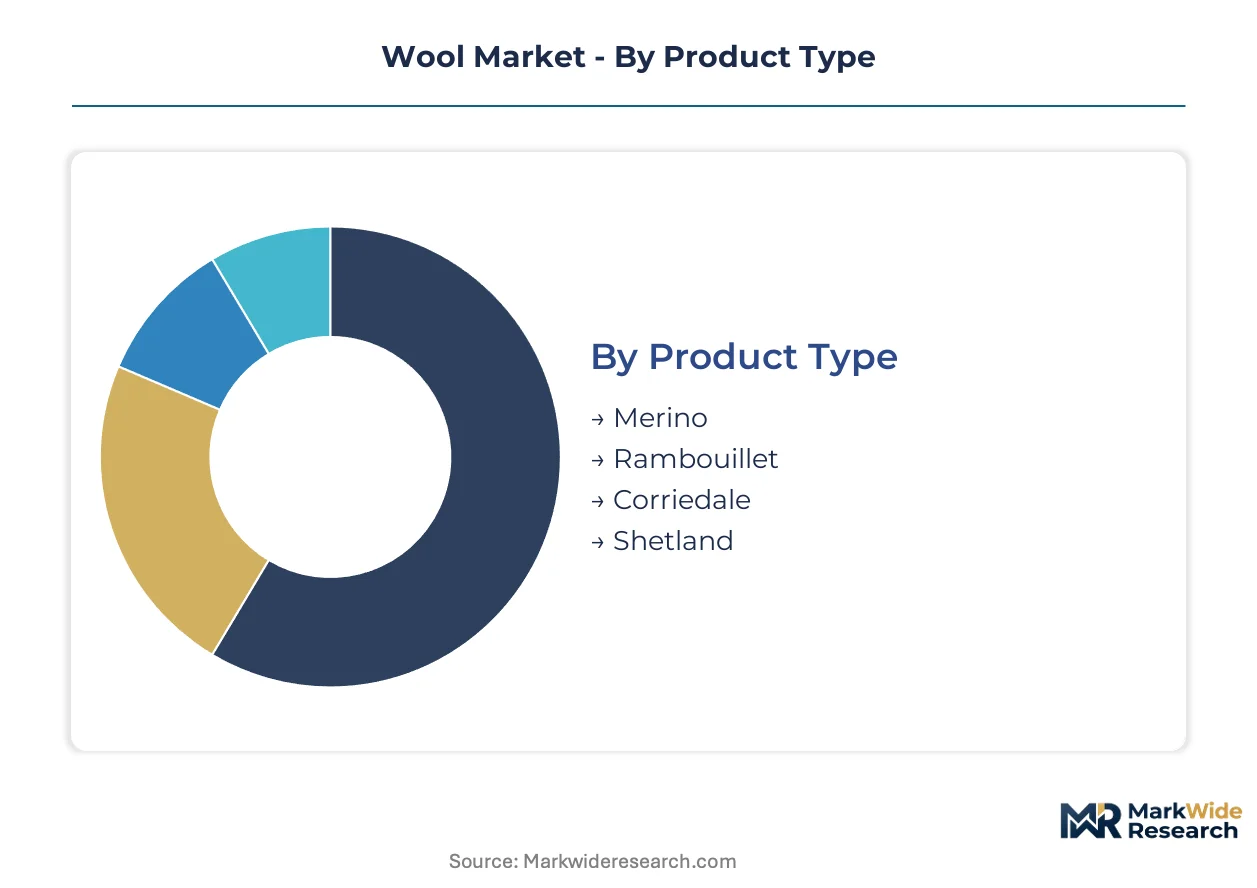
Wool market segmentation reveals how fiber specifications, application requirements, and channel economics create distinct competitive arenas. Each dimension carries different margin profiles and certification burdens that reshape supplier-buyer relationships.
Product Type:
Merino and Rambouillet anchor opposite ends of the fineness spectrum, with Corriedale and Shetland occupying intermediate positions for specific technical and heritage applications.
- Merino:Keratin fibers below 20 microns deliver exceptional softness and moisture management. Australian stations with regenerative agriculture certification supply luxury spinners in Italy and Germany under long-term offtake agreements tied to EU Green Deal traceability mandates.
- Rambouillet:American-raised fine wool typically spans 19-24 microns, combining durability with next-to-skin comfort. Performance outerwear brands in Colorado and Utah specify Rambouillet for mid-layer insulation where loft retention matters more than absolute fineness.
- Corriedale:Dual-purpose fiber from New Zealand crosses Merino fineness with Lincoln length, serving hand-knitting yarn mills and felt manufacturers seeking crimp structure without premium micron pricing.
- Shetland:Heritage breed wool from Scottish islands carries 20-33 micron range with natural color variation, commanding niche premiums in traditional Fair Isle knitting and heritage textile restoration.
Established volume favors Merino; emerging adoption favors Rambouillet as American supply chains shorten lead times for North American performance brands.
Application:
End-use specifications diverge sharply between aesthetic-driven categories and functional performance requirements, with thermal regulation properties opening non-traditional demand channels.
- Textiles:Apparel and accessory manufacturing consumes the majority of scoured and combed tops, with worsted weaving for tailored suiting and woolen spinning for soft handle knitwear representing distinct processing branches.
- Insulation:Loose-fill and batt formats exploit wool's hygroscopic buffering and inherent flame resistance. German and Austrian building codes now recognize sheep wool insulation for passive house certification, creating specification pull from Munich and Vienna architects.
- Upholstery:High-wear furniture applications in commercial hospitality specify wool-rich blends for Martindale abrasion resistance, with British contract furnishing manufacturers sourcing British Wool certified clips for public sector procurement compliance.
- Crafts:Hand-dyed yarn and felting supply chains operate through fragmented distributor networks, with Ravelry-enabled direct-to-consumer sales displacing traditional wholesale for independent dyers in Oregon and Yorkshire.
Textiles retains margin concentration; insulation climbs the fastest as energy retrofit programs accelerate across German-speaking Europe.
End User:
Customer sophistication varies from traceability-obsessed luxury houses to price-sensitive industrial buyers, with certification requirements filtering accessible supply tiers.
- Fashion Industry:LVMH and Kering-affiliated houses mandate ZQ Merino or equivalent ethical certification, with fiber provenance documentation extending to individual station GPS coordinates and shearing date records.
- Home Furnishing:Upholstery fabric mills and carpet manufacturers blend wool with synthetic fibers for cost management, though premium residential collections emphasize natural fiber content for indoor air quality positioning.
- Automotive:Seat trim and interior panel applications specify wool-polyester blends for abrasion and UV resistance, with BMW and Mercedes-Benz design studios specifying traceable natural fibers for concept vehicle sustainability narratives.
- Industrial:Felt manufacturing, polishing wheels, and acoustic dampening applications purchase scoured fleece and noils without fineness grading, competing directly with recycled synthetic alternatives on unit cost.
Fashion Industry commands premium positioning; Industrial faces persistent substitution pressure from engineered fibers.
Distribution Channel:
Channel structure reflects lot size economics and certification verification requirements, with digital infrastructure compressing traditional wholesale hierarchies.
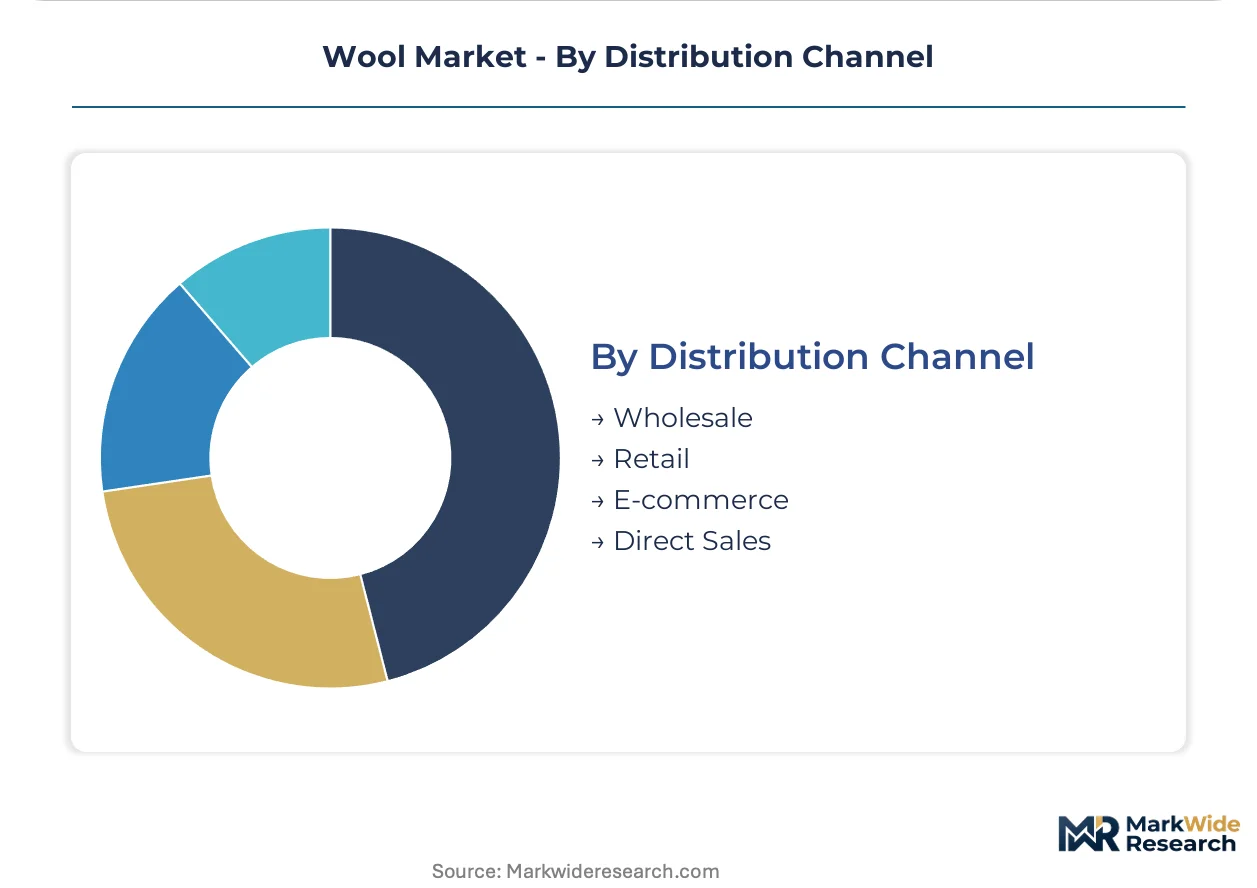
- Wholesale:Scoured wool and greasy fleece trade through auction systems (Australian Wool Exchange) and private treaty, with volume buyers consolidating shipments to achieve container-load efficiencies for European scouring facilities.
- Retail:Finished yarn and craft wool distribute through specialty stores and regional chains, with British Wool and American Wool Council licensing programs providing point-of-sale certification verification.
- E-commerce:Direct-to-station sales platforms and fiber marketplace startups enable small-lot buyers to bypass traditional merchant intermediaries, with blockchain verification increasingly embedded in transaction infrastructure.
- Direct Sales:Long-term supply agreements between Australian stations and Italian spinners eliminate spot market exposure, with embedded sustainability clauses and carbon accounting provisions governing contract renewal.
Wholesale retains volume concentration; e-commerce gains share fastest among artisan and small-batch manufacturing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian spinners absorb micron premiums without volume contraction while Indian knitwear buyers negotiate aggressively on landed cost. Australian stations face divergent elasticity: European luxury houses lock in forward contracts at fixed premiums, whereas Chinese traders bid spot discounts during auction weakness.
Australia
Merino clip volumes from New South Wales and Victoria supply the bulk of sub-20 micron fiber for Italian worsted mills. Australian Wool Innovation enforces clip certification protocols that align with EU Green Deal traceability mandates. Sydney-based exporters consolidate shipments through Port Melbourne to achieve container-load efficiencies for European scouring facilities.
Italy
Biella and Prato spinning clusters process Australian greasy wool into combed tops for luxury apparel weavers. REACH chemical disclosure requirements force reformulation of scouring processes across Piedmont finishing mills. Loro Piana anchors ultra-fine Merino sourcing through long-term station partnerships, sustaining its position in traceable luxury collections.
China
Shandong and Jiangsu provinces operate the world's largest wool scouring and carbonizing capacity for mid-market textile production. The country's national standards regulator enforces GB textile labeling rules that compete with Australian clip certification for market recognition. Ningbo traders arbitrage price spreads between Australian Wool Exchange auctions and domestic yarn mill demand.
Germany
Bavarian and Saxon technical textile manufacturers specify wool insulation batts for passive house construction projects. ECHA restrictions on wool grease processing chemicals constrain regional scouring capacity and raise compliance costs for imported raw fiber. Südwolle Group leverages backward integration from raw scouring to dyed tops, securing supply chain control across Central European spinning operations.
New Zealand
South Island stations supply Corriedale and halfbred clips for carpet yarn and felt manufacturing. The Ministry for Primary Industries enforces ethical sourcing standards that shape export market access for raw fiber. Christchurch-based exporters consolidate procurement around regenerative agriculture verification for European sustainability-focused buyers.
Wool Market Competitive Environment
Capability concentration sits with heritage spinners possessing station relationships and clip certification expertise; scale advantage sits with integrated mills operating multi-fiber platforms. The market structures around three tiers: luxury houses with captive wool sourcing, mid-market spinners with regional brand partnerships, and commodity traders with auction-floor leverage. Two competitive moves dominate: consolidation of scouring-to-top vertical control, and blockchain traceability platform deployment for supplier qualification.
Within the heritage spinner tier, Südwolle Group and Loro Piana exemplify divergent scale-positioning strategies. Südwolle, a German GmbH-structured operation, anchors integrated worsted production across Central European facilities. Loro Piana, now within a larger luxury conglomerate, occupies a position defined by ultra-fine micron exclusivity and Australian station direct-contracting. Marzotto Group, an Italian S.p.A., represents the weaving-scale archetype with integrated mills servicing tailored clothing brands.
| Leading Market Players |
|---|
| Pendleton Woolen Mills |
| Südwolle Group |
| Loro Piana |
| Xinao Textiles Inc. |
| The Woolmark Company |
| Indorama Ventures Public Company Limited |
| Marzotto Group |
| Icebreaker |
| Zegna Baruffa Lane Borgosesia |
| Others |
Value Chain & Pricing Dynamics
Biella's worsted spinning cluster anchors European micron premiums through captive relationships with Australian Merino stations, translating raw fiber scarcity into sustained pricing power for certified clips. This geographic concentration enables Italian spinners to command fixed-premium contracts while spot-market traders absorb auction volatility.
Pricing Analysis
Service revenue from scouring-to-top processing contracts drives lifetime value for integrated European mills. Three-tier pricing structure across certified premium, standard clip, and commodity auction grades separates ZQ Merino from standard Australian Wool Innovation clips from uncertified greasy fleece. Pricing pressure stems from REACH compliance costs compressing scouring margins. Industrial felt buyers exhibit highest price sensitivity; LVMH-affiliated houses show lowest.
Supply Chain Analysis
Tariff exposure between Australia and China dominates supply chain risk calculations for raw fiber traders. Production concentrates in Australia, New Zealand, and China. Raw material flows draw from greasy Merino fleece, scoured tops, and carbonized noils. Single-source vulnerability runs through Australian Wool Exchange auction concentration. Distribution runs through containerized shipment consolidation at Port Melbourne and direct sales agreements with Italian spinners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wool market represents a high-growth disruption as EU Green Deal traceability mandates reconfigure procurement economics and carbon-negative insulation opens non-traditional demand channels.
For Market Incumbents: Entrench station relationships through embedded sustainability clauses and regenerative agriculture certification investments. Backward integration into Australian scouring capacity mitigates REACH chemical restriction risks. Blockchain traceability platform deployment secures supplier qualification status with luxury fashion houses. For New Entrants and Emerging Players: Build out technical knitwear capabilities targeting Indian outdoor and athletic apparel white space. Carbon-negative insulation specification for German passive house projects offers penetrable entry point. Direct-to-station e-commerce platforms with embedded provenance verification provide differentiated go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated processors with clip certification expertise and long-term station contracts. Five-to-ten year viability hinges on traceability infrastructure ownership. Acquisition targets include Australian stations with regenerative agriculture verification. Blockchain platform adoption rates signal inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Certification | Australian stations with verified carbon sequestration capture preferential offtake from European luxury spinners. |
| Blockchain Traceability Platform Deployment | Distributed ledger integration with clip certification enables real-time provenance verification for sustainability-focused buyers. |
| Backward Integration into Scouring | Südwolle Group's captive scouring-to-top control secures supply chain positioning against REACH compliance cost pressures. |
| Carbon-Negative Insulation Specification | Wool's inherent carbon sequestration properties position fiber for German passive house and Austrian building code compliance. |
| Direct-to-Station E-Commerce Platform | Digital marketplace infrastructure with embedded certification verification displaces traditional merchant intermediaries for artisan buyers. |
Study Parameters
The analysis maps Merino micron grades, Rambouillet performance tiers, insulation applications, and craft supply channels, each validated through station operators, Italian spinning mill procurement directors, German technical textile engineers, and Indian knitwear manufacturers. Primary fieldwork combined with secondary validation from Australian Wool Innovation clip reports, EU Green Deal textile strategy documentation, ECHA REACH chemical restriction databases, and customs trade flow records. Bottom-up fiber volume estimates triangulated against top-down apparel and construction demand modeling.
Assumptions held fixed include EU Green Deal traceability mandate enforcement timelines and Australian pastoral region climate stability; varied assumptions included synthetic fiber substitution rates and Indian technical apparel penetration depth. Segmentation modeling spanned product type, application, end user, and distribution channel dimensions across the analysis window. CAGRs derived from regression analysis against historical clip auction data and forward contract pricing. Forecast inputs incorporated building thermal efficiency code adoption curves and regenerative agriculture certification uptake rates.
Stress conditions across Australian drought frequency, EU carbon border adjustment implementation, and Chinese GB standards recognition were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification cost trajectories and luxury brand sustainability commitment durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
Cotton Processing Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Cotton Bags Market
Yarn and Fabric Manufacturing
Italy Textile Manufacturing Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Ring Spinning Frame Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
E-Glass Fiber Yarn and Roving Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Poly Cotton Fabric Market
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
Upholstery Fabric Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market