
 Polyisoprene Rubber Market | 2026-2036
Polyisoprene Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Polyisoprene Rubber Market Analytics
ISO 10993 biocompatibility certification is rotating supplier eligibility in medical-grade polyisoprene, forcing compounders to validate extractables and cytotoxicity profiles before hospital procurement committees approve vendor lists. KURARAY leverages its solution-polymerization expertise to sustain premium positioning in surgical glove feedstock. JSR Corporation anchors Japanese supply security through captive isoprene monomer capacity. ExxonMobil Chemical competes on synthetic polyisoprene consistency for tire sidewall applications where batch-to-batch variance raises curing defects.
Polyisoprene rubber is a synthetic elastomer polymerized from isoprene monomer, chemically analogous to natural rubber but with controlled cis-1,4 content typically exceeding 96 percent, yielding tensile strengths of 20-30 MPa and Shore A hardness of 40-60 depending on formulation. Manufacturers employ Ziegler-Natta or anionic polymerization to achieve the stereoregularity required for tire curing bladder performance and medical device elasticity. Modified Polyisoprene commands widening specification spreads as healthcare OEMs demand halogen-free, low-protein variants for latex-sensitive patients, while Standard Polyisoprene retains volume leadership in automotive anti-vibration mounts where cost efficiency outweighs premium formulation. Liquid Polyisoprene represents the fastest-growing form factor, enabling sprayable sealant applications in industrial maintenance where hot-melt processing proves impractical.
FDA 21 CFR 177.2600 and EU MDR compliance frameworks govern medical-device-grade polyisoprene migration limits, compelling compounders to maintain drug master files and quality management certifications that smaller Asian producers struggle to sustain. REACH SVHC screening and RoHS substance restrictions further constrain plasticizer and accelerator selections across European automotive supply chains. Stakeholders must monitor evolving EPA TSCA Section 5 notification requirements for novel isoprene copolymers, as new chemical entity status triggers pre-manufacture review delays that can freeze formulation pipelines for eighteen months or longer.
Market Dynamics
ISO 10993 biocompatibility certification is rotating supplier eligibility in medical-grade polyisoprene, forcing compounders to validate extractables and cytotoxicity profiles before hospital procurement committees approve vendor lists. KURARAY leverages its solution-polymerization expertise to sustain premium positioning in surgical glove feedstock. JSR Corporation anchors Japanese supply security through captive isoprene monomer capacity. ExxonMobil Chemical competes on synthetic polyisoprene consistency for tire sidewall applications where batch-to-batch variance raises curing defects.
Growth Catalysts
- EU MDR migration limits:Compounded medical-grade polyisoprene faces tightened extractable thresholds under EU MDR Annex I, accelerating hospital procurement committee demand for pre-validated drug master files from certified compounders.
- Liquid polyisoprene sprayability:Low-viscosity grades enable cold-applied industrial sealants where hot-melt processing proves impractical, opening maintenance contracts in offshore energy infrastructure.
- Thai-Indonesian feedstock concentration:Integrated natural rubber processing clusters in Southeast Asia lower isoprene derivative unit costs through captive monomer supply and co-located polymerization assets.
Market Restraints
- Isoprene monomer volatility:Crude C5 stream availability from naphtha crackers fluctuates with ethylene operating rates, compressing margin predictability for non-integrated compounders.
- Natural rubber price arbitrage:Hevea brasiliensis spot markets in Kuala Lumpur and Singapore periodically undercut synthetic polyisoprene tire formulations, displacing volume in cost-sensitive automotive anti-vibration mounts.
- REACH SVHC screening delays:ECHA substance-of-very-high-concern candidate list expansions force 12-18 month reformulation cycles for European automotive supply chains, freezing specification approvals.
Strategic Opportunities
- Halogen-free surgical glove variants:Healthcare OEMs in Germany and Switzerland demand low-protein, accelerator-free formulations for latex-sensitive patients, commanding 40-60% formulation premiums over standard grades.
- Indian PLI scheme localization:Production-linked incentive schemes for medical device manufacturing are drawing compounders to establish domestic polymerization capacity near Mumbai and Chennai industrial corridors.
- Catheter co-extrusion convergence:Multi-layer tubing combining polyisoprene elastomeric cores with thermoplastic polyurethane sheaths enables next-generation minimally invasive cardiovascular devices.
Industry Challenges
- ISO 10993-5 cytotoxicity validation timelines:Contract laboratories require 16-24 weeks for complete extractables profiling, delaying hospital vendor list approvals and freezing new compounder market entry.
- Ziegler-Natta catalyst supply concentration:Titanium-based initiator production concentrates among three specialized chemical manufacturers, creating single-source vulnerability for stereoregular polymerization campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyisoprene Rubber Market |
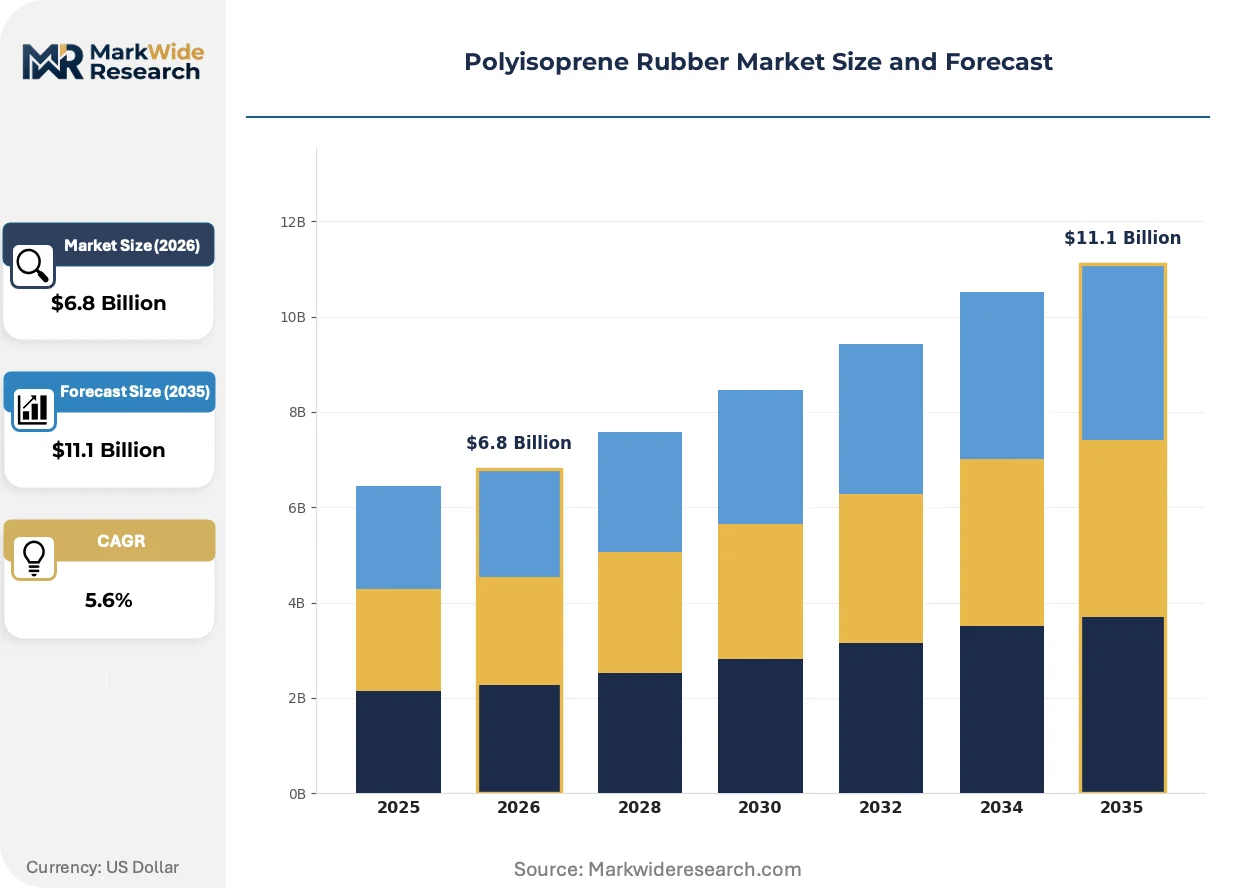
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.1 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Polyisoprene, Modified Polyisoprene, Liquid Polyisoprene, Blend Polyisoprene Application: Tires, Medical Devices, Gaskets, Seals End User: Automotive, Healthcare, Consumer Goods, Industrial Form: Sheet, Liquid, Tube, Granule |
| Companies Covered | Ansell Limited, KURARAY, Cariflex, ExxonMobil Chemical, Mitsui Chemicals, JSR Corporation, Top Glove Corporation Bhd, Arlanxeo, Kraton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyisoprene Rubber Market Evolving Landscape
Liquid polyisoprene grades are compressing application boundaries between conventional hot-melt processing and ambient-cure sealant systems. Three developments are restructuring competitive positioning across medical, automotive, and industrial maintenance verticals.
Reactive liquid polyisoprene formulations with tunable viscosity ranges from 500 to 5000 cP are miniaturizing equipment footprints in industrial maintenance applications. Offshore platform operators in the North Sea and Gulf of Mexico now deploy portable spray systems for gasket replacement without hot-work permits. The technology is compressing traditional two-part silicone and polysulfide sealant market share in confined-space repair contracts.
REACH Annex XIV authorization requirements for phthalate plasticizers are forcing compounders to validate citrate and polyester alternatives in medical tubing formulations. ECHA sunset date pressures are accelerating reformulation investments among German and French medical device suppliers ahead of 2026 deadlines. Tire sidewall compounders face parallel RoHS substance restrictions across European automotive OEM supply chains.
Hospital procurement committees now mandate pre-submitted drug master files and ISO 13485 quality certifications before vendor list inclusion. Medical device OEMs in the United States are consolidating supplier panels from 12-15 qualified compounders to 4-6 strategic partners with validated cytotoxicity profiles. The concentration is most visible in cardiovascular catheter supply chains where FDA 21 CFR 177.2600 compliance documentation requires 18-month qualification cycles.
Polyisoprene Rubber Market Segmentation
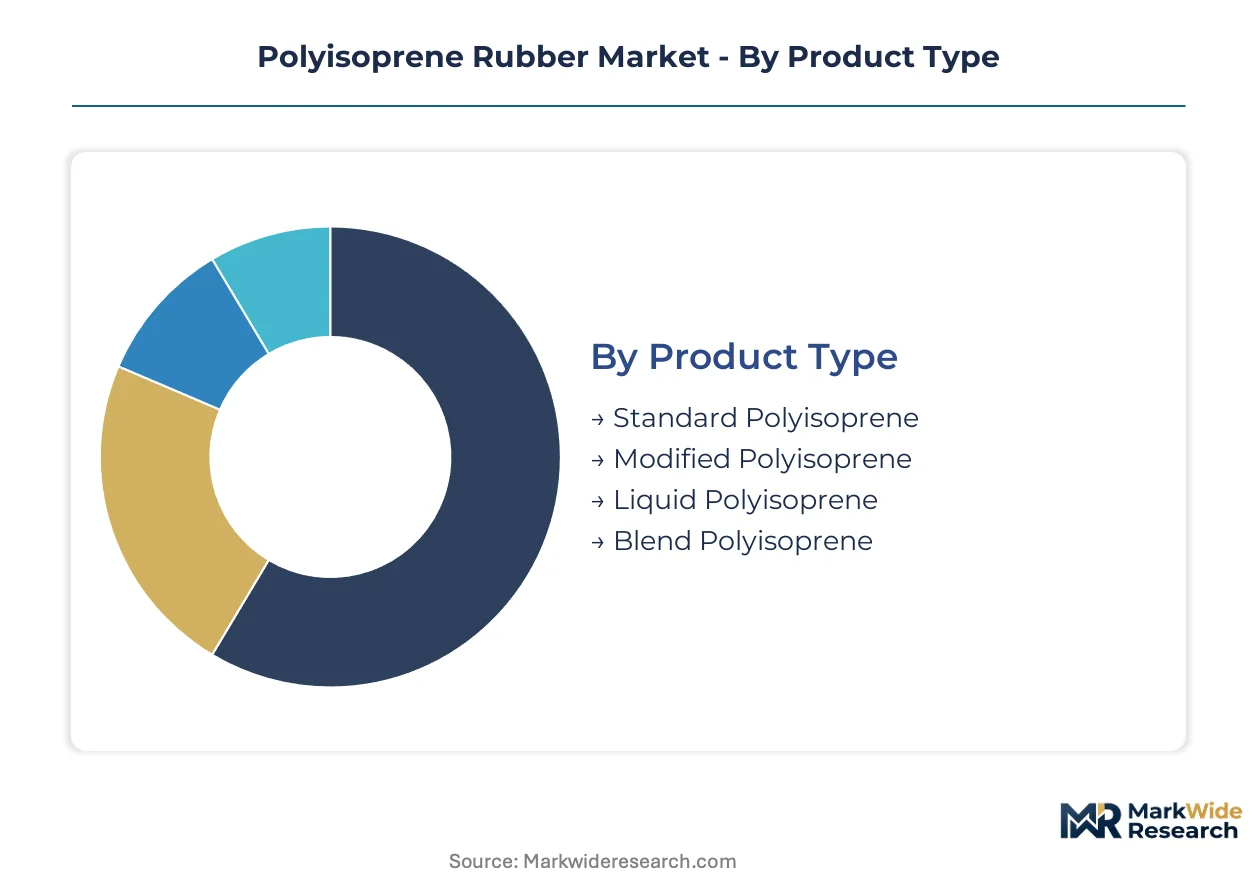
Polyisoprene rubber procurement channels diverge sharply between commodity tire compounders seeking volume contracts and medical device OEMs demanding validated drug master files. Specification-grade segmentation determines which suppliers qualify for hospital vendor lists versus automotive spot purchasing.
Product Type:
Standard grades flow through distributor networks to tire manufacturers, while medical-certified variants require direct technical service relationships with compounders.
- Standard Polyisoprene:Cis-1,4 content exceeding 96 percent delivers tensile strengths of 20-30 MPa for tire curing bladders and automotive anti-vibration mounts. Procurement concentrates among Thai and Indonesian integrated producers where captive isoprene monomer supply compresses unit costs for high-volume tire sidewall formulations.
- Modified Polyisoprene:Halogen-free, low-protein variants command formulation premiums for latex-sensitive patients in German and Swiss surgical glove applications. REACH SVHC screening and EU MDR migration limits are accelerating hospital procurement committee demand for pre-validated compounders with ISO 10993-5 cytotoxicity documentation.
- Liquid Polyisoprene:Low-viscosity grades from 500 to 5000 cP enable sprayable sealant deployment in offshore energy maintenance without hot-work permits.
- Blend Polyisoprene:Co-extrusion formulations with thermoplastic polyurethane sheath layers serve multi-layer cardiovascular catheter tubing.
Standard Polyisoprene dominates installed base. Modified Polyisoprene is where expansion concentrates.
Application:
Medical applications extract margin through regulatory qualification barriers, while tire and industrial segments compete on monomer cost efficiency.
- Tires:Synthetic polyisoprene consistency requirements for sidewall curing raise batch-to-batch variance penalties. Natural rubber spot markets in Kuala Lumpur and Singapore periodically undercut synthetic formulations in cost-sensitive automotive anti-vibration mounts.
- Medical Devices:FDA 21 CFR 177.2600 and EU MDR compliance frameworks govern migration limits, compelling compounders to maintain drug master files. Hospital procurement committees now mandate pre-submitted ISO 13485 certifications before vendor list inclusion.
- Gaskets:Industrial maintenance contracts in North Sea and Gulf of Mexico platforms favor cold-applied liquid formulations.
- Seals:REACH Annex XIV phthalate authorization deadlines are forcing citrate and polyester plasticizer validation ahead of 2026 sunset dates.
Tires anchor volume throughput. Medical Devices capture the steepest expansion trajectory.
End User:
Automotive procurement consolidates around integrated Thai-Indonesian supply clusters, while healthcare demands geographic proximity to FDA and EU MDR regulatory expertise.
- Automotive:Tire manufacturers remain the largest procurement segment, with sidewall compounders facing parallel RoHS substance restrictions across European OEM supply chains.
- Healthcare:Medical device producers are expanding purchases for surgical gloves and catheters, with cardiovascular OEMs consolidating supplier panels from 12-15 qualified compounders to 4-6 strategic partners.
- Consumer Goods:Latex-sensitive patient demand drives accelerator-free formulation premiums in personal protective equipment.
- Industrial:Offshore platform operators deploy portable spray systems for gasket replacement without hot-work permits.
Automotive commands raw tonnage. Healthcare is expanding most quickly.
Form:
Physical form determines processing equipment requirements, with liquid grades miniaturizing industrial maintenance footprints.
- Sheet:Conventional calendering output for tire curing bladder manufacturing.
- Liquid:Reactive formulations with tunable viscosity ranges enable ambient-cure sealant systems in confined-space repair contracts.
- Tube:Extruded profiles for catheter co-extrusion convergence combining elastomeric cores with thermoplastic polyurethane sheaths.
- Granule:Bulk handling format for compounder batch mixing operations.
Sheet dominates legacy processing infrastructure. Liquid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes and REACH SVHC screening deadlines are redirecting capital toward integrated Southeast Asian clusters and European medical-grade certification hubs. Feedstock proximity and regulatory compliance velocity now determine regional competitiveness more than labor arbitrage.
Thailand
Captive natural rubber processing infrastructure in Hat Yai and Surat Thani provinces generates isoprene monomer at unit costs below naphtha cracker alternatives. The country's Board of Investment grants eight-year tax holidays for polymerization capacity expansions. Rayong's Eastern Economic Corridor hosts KURARAY's solution-polymerization complex serving surgical glove compounders.
Indonesia
Sumatran Hevea brasiliensis plantations supply feedstock to Medan and Palembang derivative plants at spot prices that periodically undercut synthetic formulations. The national industrial ministry prioritizes downstream rubber processing through import substitution mandates. Batam's free trade zone enables duty-free export of medical-grade polyisoprene to FDA-registered US compounders.
Germany
ECHA's 2026 sunset dates for phthalate plasticizers are forcing compounders in Leverkusen and Ludwigshafen to validate citrate alternatives ahead of REACH Annex XIV deadlines. The country's medical device OEMs command 40-60% formulation premiums for halogen-free surgical glove variants. Bavarian catheter manufacturers consolidate supplier panels to partners with pre-submitted drug master files.
United States
FDA 21 CFR 177.2600 compliance documentation requires 18-month qualification cycles that freeze new compounder entry into cardiovascular catheter supply chains. Gulf Coast petrochemical corridors in Texas and Louisiana offer integrated isoprene monomer from steam crackers. Hospital procurement committees in Boston and Minneapolis now mandate ISO 13485 certifications before vendor list inclusion.
India
PLI scheme disbursements for medical device manufacturing are drawing compounders to establish polymerization capacity near Mumbai and Chennai industrial corridors. CDSCO's tightening purity benchmarks for surgical gloves mirror FDA medical-grade standards. Gujarat's Dahej petroleum complex offers feedstock integration for domestic tire sidewall compounders.
Polyisoprene Rubber Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and feedstock integration dimensions. The market structures around three tiers: integrated petrochemical majors with captive monomer supply, solution-polymerization specialists commanding medical-grade premiums, and regional compounders competing on spot pricing for automotive applications. Strategic moves concentrate on backward integration into isoprene monomer production and pre-validation of ISO 10993 cytotoxicity profiles to secure hospital vendor list positions.
Within the medical-grade specialization tier, KURARAY and JSR Corporation exemplify solution-polymerization expertise that sustains premium positioning. ExxonMobil Chemical anchors the consistency-driven segment for tire applications where batch variance raises curing defects. Among integrated petrochemical players, Mitsui Chemicals and Arlanxeo occupy positions shaped by captive feedstock access and regional distribution density.
| Leading Market Players |
|---|
| Ansell Limited |
| KURARAY |
| Cariflex |
| ExxonMobil Chemical |
| Mitsui Chemicals |
| JSR Corporation |
| Top Glove Corporation Bhd |
| Arlanxeo |
| Kraton Corporation |
| Others |
Value Network & Pricing Analysis
Natural rubber spot market arbitrage against synthetic polyisoprene simultaneously redraws supply geography toward Southeast Asian plantations and compresses pricing power for naphtha-crackers in Europe and North America. Tire manufacturers exploit this substitution window to force contract renegotiations, while medical-grade compounders defend premiums through certification moats that spot markets cannot breach.
Pricing Analysis
Certification level creates the primary spread between medical-grade and industrial-grade polyisoprene, with ISO 10993-validated variants commanding substantial premiums over standard tire formulations. Three-tier pricing structure across premium medical, standard automotive, and economy industrial levels reflects divergent purity benchmarks and documentation burdens. Pricing pressure stems from Kuala Lumpur and Singapore spot markets periodically undercutting synthetic alternatives in cost-sensitive anti-vibration mounts. Tire manufacturers exhibit acute price sensitivity, while hospital procurement committees prioritize pre-validated drug master files over unit cost.
Supply Chain Analysis
Strategic stockpiling of isoprene monomer distinguishes integrated Thai and Indonesian producers from European and North American compounders exposed to C5 stream volatility. Supply concentrates in Thailand, Indonesia, and Japan, where captive natural rubber processing or naphtha cracking secures feedstock autonomy. Raw material dependencies encompass crude C5 streams, titanium-based Ziegler-Natta catalysts, and phthalate or citrate plasticizers. Single-source vulnerability concentrates in catalyst manufacturing among three specialized chemical producers. Distribution runs through direct technical service relationships for medical grades and distributor networks for commodity tire formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical device OEM consolidation from twelve to six qualified compounders signals early-cycle expansion in cardiovascular catheter and surgical glove applications, with liquid polyisoprene sprayability opening industrial maintenance white space.
For Market Incumbents: Fortify hospital vendor list positions by accelerating ISO 10993-5 cytotoxicity validation timelines and securing backward integration into isoprene monomer production. Natural rubber price arbitrage threatens margin stability in tire sidewall formulations, demanding captive feedstock control in Thai or Indonesian production clusters. For New Entrants and Emerging Players: Anchor in Indian medical device manufacturing corridors where PLI scheme disbursements subsidize domestic polymerization capacity establishment. Liquid polyisoprene industrial maintenance contracts in offshore energy infrastructure represent the most penetrable segment, with cold-applied sealant technology bypassing entrenched silicone and polysulfide incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed solution-polymerization specialists holding pre-validated EU MDR drug master files. Five-to-ten year viability hinges on regulatory compliance velocity outpacing commodity spot market erosion. The signal to watch is ECHA REACH Annex XIV sunset date adherence among European compounders, with authorization failures triggering forced divestitures of medical-grade capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isoprene Monomer | Captive C5 stream supply from Thai naphtha crackers insulates margin predictability against ethylene operating rate volatility. |
| ISO 10993-5 Cytotoxicity Pre-Validation | Accelerated extractables profiling compresses sixteen-week laboratory timelines to secure hospital procurement committee approval. |
| Liquid Polyisoprene Capacity Expansion | Low-viscosity reactive grades capture offshore platform maintenance contracts without hot-work permit requirements. |
| Halogen-Free Formulation Development | Accelerator-free variants command Swiss and German surgical glove premiums for latex-sensitive patient populations. |
| Indian PLI Scheme Localization | Mumbai and Chennai corridor proximity aligns with CDSCO tightening purity benchmarks mirroring FDA medical-grade standards. |
Research Methodology
Desk research of customs trade databases, ECHA REACH substance screening records, and FDA 21 CFR 177.2600 compliance filings preceded structured interviews with tire compounder procurement directors, medical device OEM regulatory affairs leads, hospital purchasing committee managers, and Southeast Asian petrochemical plant operators. Primary fieldwork with JSR Corporation and KURARAY technical service teams validated solution-polymerization process economics. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Variance decomposition across product type, application vertical, end-user industry, and geographic production hub shaped the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating natural rubber spot price correlation coefficients and medical-grade certification penetration rates. Modeled inputs encompassed ethylene cracker operating rates, EU MDR Annex I migration limit enforcement timelines, and Indian PLI scheme disbursement trajectories.
Underlying assumptions cover sustained REACH SVHC screening stringency and FDA medical-grade standard evolution, with deviation risk concentrated in isoprene monomer supply disruptions and natural rubber price collapse scenarios. Revision becomes warranted when Kuala Lumpur spot market discounts to synthetic polyisoprene exceed historical volatility bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Seal Plugs Market
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Tire Reinforcement Materials Market
Rubber
FKM Elastomers Market
Rubber
Neoprene Rubber Market
Rubber
Rubber Roller Cleaner Market
Rubber
Rubber Foam Market
Rubber
Rubber Choppers Market
Rubber
Rubber Bulb Seals Market
Rubber
Chloroprene Rubber Tape Market
Rubber
Rubber Masterbatch Market
Rubber
Isobutylene Market
Rubber
Rubber Coatings Market
Rubber
Global Cast Elastomers Market
Rubber
Rubber Accelerators Market
Rubber
Tire Chemicals Market