
 Neoprene Rubber Market | 2026-2036
Neoprene Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Neoprene Rubber Market Outlook
REACH is realigning the cost-of-entry calculus for European neoprene suppliers by mandating stricter disclosure of chlorinated byproducts in polymerization. ARLANXEO leverages its integrated butadiene-to-chloroprene pipeline to sustain feedstock cost advantages across German and Dutch production hubs. Denka Company Limited anchors its competitive position through captive acetylene sourcing and specialized electrical-grade neoprene formulations for Asian cable sheathing markets.
Neoprene rubber is a synthetic elastomer polymerized from chloroprene monomer, exhibiting density ranges of 1.23–1.25 g/cm³ and operational temperature stability from -40°C to 120°C, which makes it indispensable for oil-resistant gaskets, weatherproof seals, and protective equipment requiring flex fatigue resistance. Solid neoprene commands the dominant volume share in industrial gasket and hose applications where compression set specifications are non-negotiable, while neoprene foam is expanding fastest in marine buoyancy and HVAC insulation as building energy codes tighten. Cellular neoprene occupies a specialized niche in wetsuit and medical brace fabrication where closed-cell water resistance justifies premium pricing over competing elastomers.
The EPA enforces VOC emission thresholds at U.S. adhesive manufacturing facilities that consume neoprene-based contact cements, while China's MEE imposes wastewater discharge limits on chloroprene production clusters in Shandong and Sichuan provinces. ISO 1629 nomenclature standards and JIS K 6380 physical testing protocols create divergent compliance burdens for exporters serving multiple regulatory jurisdictions simultaneously. Stakeholders must monitor how the EU F-Gas Regulation's extension toward high-GWP blowing agents used in neoprene foam production will reshape formulation chemistry and regional cost competitiveness.
Market Dynamics
REACH compliance deadlines are compressing European neoprene supply chains as producers absorb reformulation costs for reduced chloroprene residuals, while Chinese capacity expansion absorbs displaced volume from shuttered Western lines.
Growth Catalysts
- Automotive sealing mandates:OEM specifications for under-hood gaskets now require oil resistance thresholds that only chloroprene-based elastomers reliably meet, pulling volume from nitrile alternatives.
- EU F-Gas Regulation phase-down:The restriction on high-GWP blowing agents is accelerating adoption of water-blown neoprene foam chemistries in HVAC insulation applications.
- Marine buoyancy standards:SOLAS life-raft certification requirements for closed-cell buoyancy materials are expanding specification-grade neoprene foam orders in Korean and Chinese shipyards.
Market Restraints
- Chloroprene monomer supply concentration:Over 60% of global monomer capacity resides in Shandong and Sichuan provinces, creating single-geography exposure to MEE wastewater enforcement actions.
- Acetylene feedstock volatility:Captive carbide-based acetylene production faces electricity cost inflation and carbon intensity scrutiny under China's dual carbon goals.
- EPDM substitution in weatherstripping:Automotive exterior seals are migrating to EPDM for cost and color-matching flexibility, compressing neoprene's addressable share in non-oil-contact applications.
Strategic Opportunities
- Medical brace fabrication:Closed-cell neoprene's biocompatibility profile and moisture-wicking laminates are penetrating orthopedic support markets previously served by latex and thermoplastic elastomers.
- India PLI scheme for specialty chemicals:Domestic chloroprene capacity investments under production-linked incentives could reduce import dependence for cable sheathing compounds serving power transmission expansion.
- Recyclate integration:Devulcanization technologies for post-industrial neoprene scrap are enabling circular feedstock claims in premium athletic equipment channels.
Industry Challenges
- Polymerization catalyst expertise:Cleaner initiator systems for reduced residual chloroprene require process engineering talent scarce outside legacy DuPont/Showa Denko technical lineages.
- Multi-jurisdiction certification stacking:Simultaneous compliance with ISO 1629 nomenclature, JIS K 6380 testing, and REACH SVHC disclosure creates documentation overhead for export-focused compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neoprene Rubber Market |
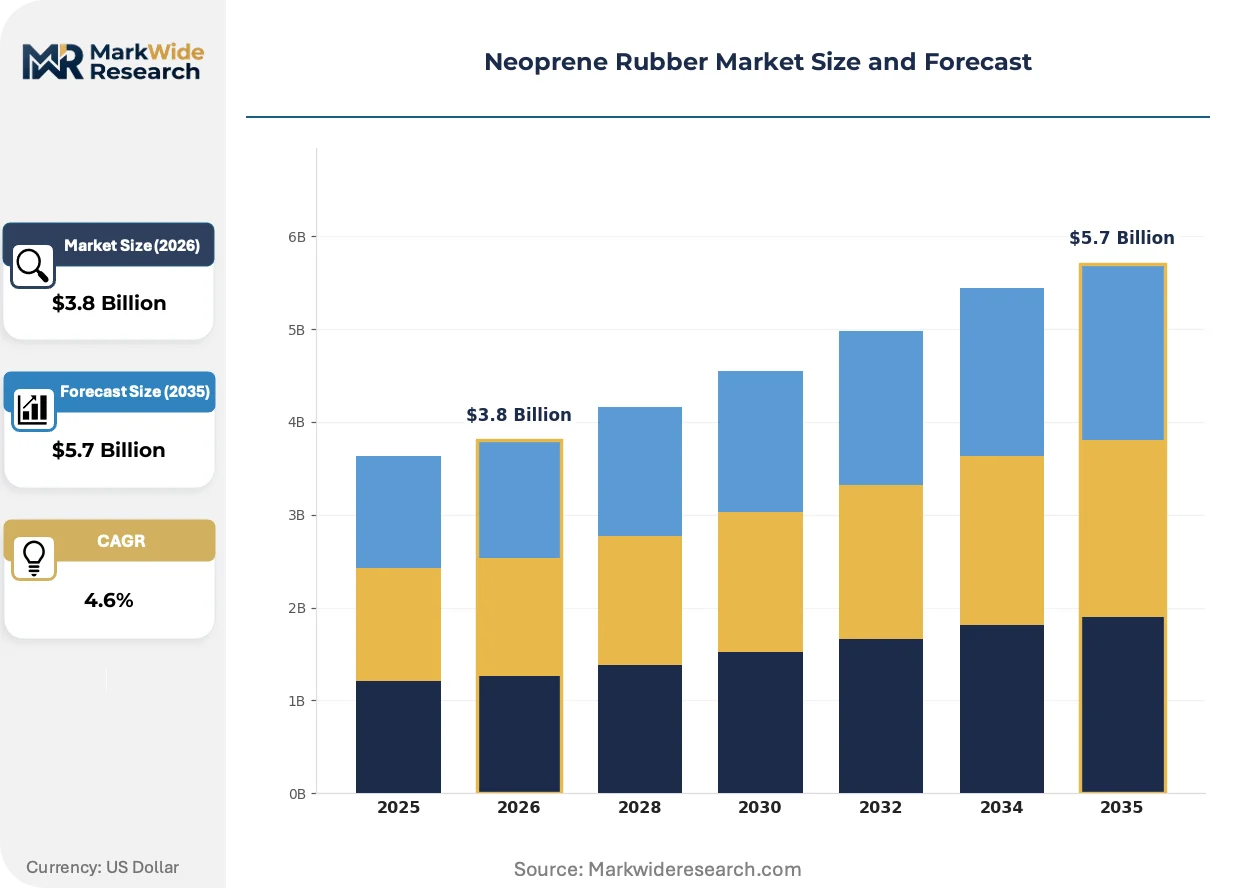
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellular Neoprene, Solid Neoprene, Neoprene Blends, Neoprene Foam Application: Automotive Seals, Adhesives, Gaskets, Protective Gear Form: Sheets, Rolls, Extrusions, Molds End User: Industrial, Consumer Goods, Automotive, Medical |
| Companies Covered | China National Bluestar (Group) Co. Ltd., BRP Manufacturing, ARLANXEO, SEDO Chemicals Neoprene GmbH, Resonac Holdings Corporation, Denka Company Limited, Shanxi Huojia Changhua Synthetic Rubber Co., Ltd., Eastex Products, Inc., Tosoh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neoprene Rubber Market Strategic Shifts
Formulation chemistry and manufacturing process control are converging to address regulatory tightening while opening performance tiers previously unattainable with conventional neoprene grades.
Advanced peroxide-cured neoprene compounds are consolidating specification control in automotive powertrain sealing. Tier-1 gasket suppliers in Germany and Michigan are qualifying these grades for 150°C continuous service, displacing some fluorocarbon elastomer use in transmission applications. The technology is consolidating material substitution decisions around total system cost rather than per-kilogram pricing.
REACH SVHC candidate list expansion is forcing disclosure of chlorinated byproducts across polymerization batches. European compounders are investing in closed-loop solvent recovery and real-time residual monitoring to maintain market access. German producers face the steepest compliance gradient as the country's chemical sector self-regulation through VCI guidelines anticipates formal ECHA restrictions.
Specification-driven procurement is compressing supplier qualification cycles in industrial distribution. Large MRO buyers in the US Gulf Coast petrochemical corridor now demand lot-traceable neoprene sheet with pre-certified compression set data, bypassing traditional distributor stocking models. This pattern is most pronounced in Texas and Louisiana, where turnaround maintenance schedules tolerate no material variance.
Neoprene Rubber Market Segmentation
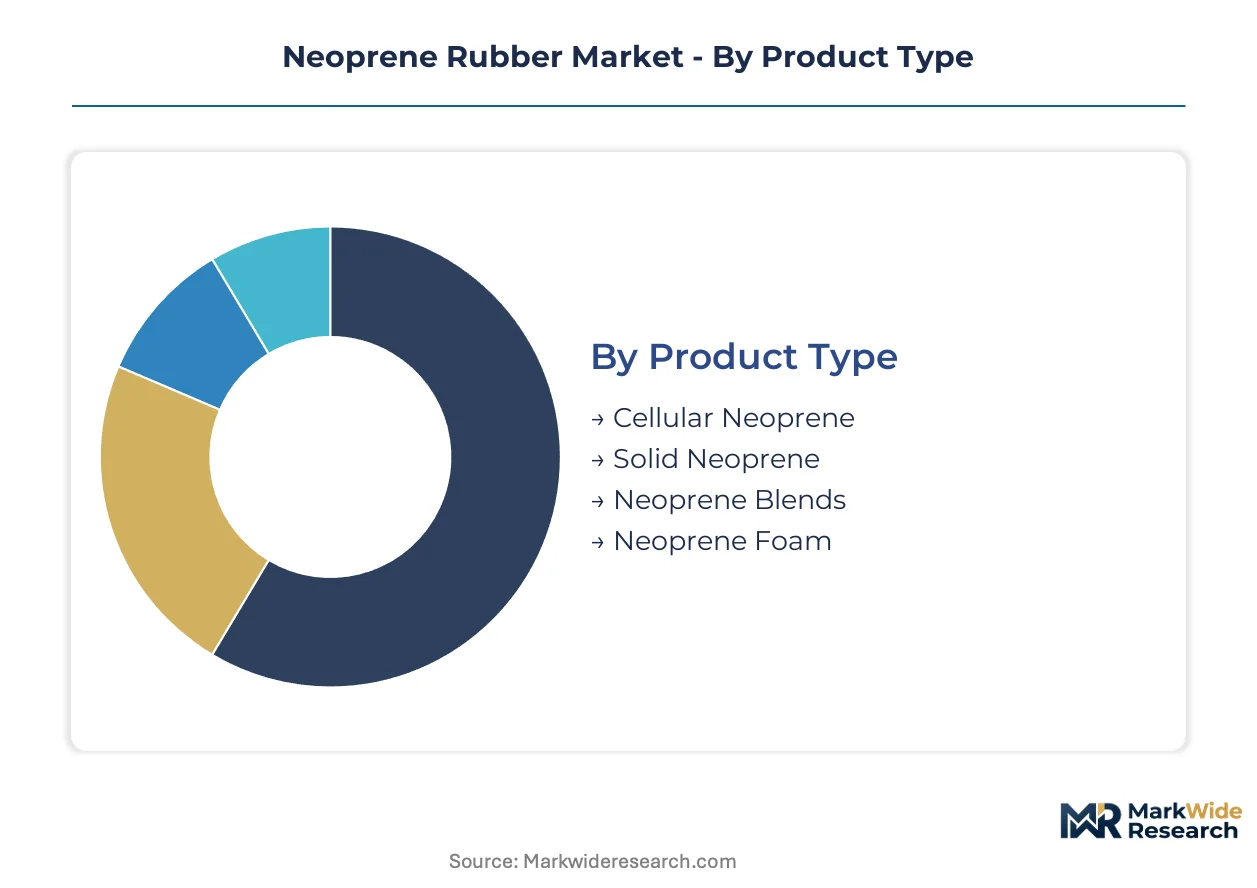
Neoprene rubber segmentation reflects divergent performance requirements across oil-resistant industrial applications versus consumer-facing flexibility demands. Product form and end-use specifications dictate polymerization chemistry, curing systems, and certification burdens that fragment supplier capabilities.
Product Type:
Standardization dominates commodity grades while cellular and foam variants command formulation secrecy and closed-cell process control.
- Solid Neoprene:Dense vulcanized sheets and rolls deliver compression set resistance below 25% after 70 hours at 100°C. Automotive under-hood gasket specifications in Michigan and Stuttgart pull volume toward peroxide-cured grades certified for continuous 120°C service.
- Neoprene Foam:Closed-cell expanded structures achieve water absorption below 5% by volume, qualifying for SOLAS marine buoyancy applications in Korean shipyards. The EU F-Gas Regulation's phase-down of HFC blowing agents is accelerating water-blown chemistry adoption in HVAC duct insulation.
- Cellular Neoprene:Biocompatible closed-cell grades with moisture-wicking fabric laminates penetrate orthopedic brace markets in Germany and Japan.
- Neoprene Blends:Compounded with EPDM or SBR to balance oil resistance against cost in industrial hose covers.
Leading the category by volume: Solid Neoprene. Growing fastest: Neoprene Foam.
Application:
Functional performance thresholds separate specification-grade procurement from commodity spot purchasing.
- Automotive Seals:Powertrain gaskets require ASTM D2000 BC specifications for aromatic fluid resistance. Tier-1 suppliers in Stuttgart and Detroit qualify lots against OEM compression set and tensile retention protocols before line release.
- Gaskets:Industrial flange seals in Texas petrochemical facilities demand lot-traceable sheet with pre-certified compression set data, bypassing distributor stocking models.
- Adhesives:Solvent-based contact cements face EPA VOC thresholds at U.S. manufacturing facilities.
- Protective Gear:Wetsuit fabrication in Thailand and Vietnam sources ultra-stretch laminates with nylon jersey facing.
Dominant by specification intensity: Automotive Seals. Expanding most quickly: Gaskets for process industry maintenance cycles.
Form:
Processing method determines surface finish precision and dimensional tolerance capabilities.
- Sheets:Calendered slabs serve die-cutting operations for gasket fabrication with thickness tolerance ±0.25mm.
- Rolls:Continuous lengths optimize automated cutting systems in high-volume automotive trim operations.
- Extrusions:Profiled seals with coextruded rigid locking beads anchor window and door systems.
- Molds:Compression-molded complex geometries deliver orthopedic brace components with fabric encapsulation.
Highest volume throughput: Rolls. Steepest specification climb: Molds for medical device integration.
End User:
Certification burden and procurement scale separate enterprise buyers from fragmented consumer channels.
- Automotive:OEM direct sourcing mandates IATF 16949 traceability and PPAP qualification for every compound revision.
- Industrial:MRO buyers in Louisiana and Texas petrochemical corridors demand pre-certified material data sheets to compress turnaround maintenance schedules.
- Medical:Brace fabricators in Germany and Japan require ISO 10993 biocompatibility testing for skin-contact applications.
- Consumer Goods:Athletic equipment brands specify devulcanized recyclate content for circularity claims in premium channels.
Procurement concentration peaks with Automotive. Fastest qualification cycles: Medical for orthopedic support expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest share of neoprene rubber consumption, with domestic automotive OEMs and export-oriented fabricators driving procurement concentration. Regional supply chains diverge sharply between REACH-regulated European production and capacity expansion in East Asian chemical clusters.
China
Shandong and Sichuan provinces host over 60% of global chloroprene monomer capacity, serving domestic automotive gasket manufacturers and marine foam exporters. The Ministry of Ecology and Environment enforces wastewater discharge limits on production clusters, tightening compliance costs for Shandong-based polymerization facilities. Qingdao shipyards specification-grade neoprene foam orders for SOLAS-certified life-raft buoyancy systems.
Germany
ARLANXEO's integrated butadiene-to-chloroprene pipeline sustains feedstock cost advantages across German and Dutch production hubs supplying automotive Tier-1 suppliers. REACH SVHC disclosure mandates for chlorinated byproducts force closed-loop solvent recovery investments at compounders in Leverkusen and Marl. Stuttgart-based gasket suppliers qualify peroxide-cured grades for 150°C continuous powertrain service.
United States
EPA VOC emission thresholds at adhesive manufacturing facilities in Ohio and Texas constrain solvent-based contact cement consumption. Michigan automotive OEMs specify ASTM D2000 BC grades for under-hood sealing systems, pulling volume from nitrile alternatives. Louisiana and Texas petrochemical corridor MRO buyers demand lot-traceable sheet with pre-certified compression set data.
Japan
Denka Company Limited anchors competitive positioning through captive acetylene sourcing and specialized electrical-grade formulations for cable sheathing markets. METI industrial standards and JIS K 6380 physical testing protocols create compliance burdens for exporters serving multiple jurisdictions. Osaka-based compounders supply orthopedic brace fabricators requiring ISO 10993 biocompatibility certification.
India
Power transmission expansion drives cable sheathing compound demand previously met through imports from Chinese and Japanese suppliers. The Production-Linked Incentive scheme for specialty chemicals incentivizes domestic chloroprene capacity investments in Gujarat and Maharashtra. Mumbai electrical equipment manufacturers qualify local compounders for grid infrastructure projects.
Neoprene Rubber Market Competitive Environment
German producers anchor one tier; Japanese specialists hold formulation differentiation in electrical-grade segments. The vendor base spans integrated petrochemical conglomerates with captive feedstock control and regional compounders serving specification-intensive MRO channels. Three archetypes dominate: integrated monomer-to-polymer operators, electrical-grade formulation specialists, and regional sheet-calendering compounders. Competitive intensity concentrates around backward integration into acetylene feedstock and qualification speed for automotive OEM direct sourcing.
Within the integrated operator tier, ARLANXEO and Denka Company Limited exemplify divergent feedstock strategies—ARLANXEO leveraging butadiene integration in European hubs, Denka deploying carbide-based acetylene in Asian production. Among regional specialists, SEDO Chemicals Neoprene GmbH and BRP Manufacturing occupy positions calibrated to specification-grade procurement in REACH-regulated and North American industrial distribution channels respectively. Shanxi Huojia Changhua Synthetic Rubber Co., Ltd. represents the capacity-expansion archetype serving domestic Chinese demand and export-oriented foam fabricators.
| Leading Market Players |
|---|
| China National Bluestar (Group) Co. Ltd. |
| BRP Manufacturing |
| ARLANXEO |
| SEDO Chemicals Neoprene GmbH |
| Resonac Holdings Corporation |
| Denka Company Limited |
| Shanxi Huojia Changhua Synthetic Rubber Co., Ltd. |
| Eastex Products, Inc. |
| Tosoh Corporation |
| Others |
Value Chain & Pricing Dynamics
Tier-1 automotive OEM procurement teams in Stuttgart and Detroit command contract-based long-term offtake agreements that compress spot market liquidity for specification-grade neoprene. This buyer concentration forces compounders to absorb reformulation costs for REACH compliance while maintaining price stability on multi-year supply agreements.
Pricing Analysis
Short lead-time premiums for SOLAS-certified neoprene foam in Korean shipyards run 15-25% above standard contract pricing for equivalent density grades. Three-tier pricing structure across premium, standard, and economy levels segments the market by certification intensity, with ASTM D2000 BC grades commanding sustained premiums over industrial commodity sheet. Pricing pressure stems from EPDM substitution in non-oil-contact automotive seals, with commodity neoprene sheet buyers exhibiting highest price sensitivity while medical brace fabricators show inelastic demand for biocompatible cellular grades.
Supply Chain Analysis
Chloroprene monomer supply rests on carbide-based acetylene production in Shandong and Sichuan provinces, with secondary dependence on butadiene feedstock at ARLANXEO's German and Dutch hubs. Key inputs span acetylene from captive carbide operations, butadiene from naphtha cracking, and peroxide curing agents from Japanese specialty chemical producers. Single-geography concentration in China's chemical clusters exposes the chain to MEE wastewater enforcement actions. Distribution runs through regional compounders serving MRO channels in the US Gulf Coast and direct OEM supply agreements in European automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive acetylene supply to insulate margins from electricity cost inflation and carbon intensity scrutiny under China's dual carbon goals.
For Market Incumbents: Hedge against EPDM substitution in automotive weatherstripping by accelerating peroxide-cured grade qualification for 150°C powertrain applications. Secure backward integration into acetylene feedstock through carbide facility investments or long-term tolling agreements in Sichuan. Counter Shanxi Huojia Changhua's capacity expansion by locking multi-year supply agreements with Qingdao shipyards for SOLAS-certified foam. For New Entrants and Emerging Players: The price-point gap between premium peroxide-cured automotive grades and economy sheet for industrial gaskets offers entry space for mid-tier compounders. Target India's PLI-backed specialty chemicals sector for chloroprene capacity investments serving Mumbai electrical equipment manufacturers. Penetrate through devulcanization technology partnerships that enable circular feedstock claims in athletic equipment channels. For Investors and Strategic Acquirers: The window for entry favors compounders with ISO 10993 biocompatibility certification and established orthopedic brace fabricator relationships. Long-term viability hinges on qualification speed for automotive OEM direct sourcing as distributor models erode. Watch for REACH SVHC list expansion triggering forced asset sales among European compounders lacking closed-loop solvent recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetylene | Captive carbide production insulates Denka and Shanxi Huojia Changhua from electricity cost volatility. |
| Water-Blown Foam Chemistry Transition | EU F-Gas Regulation compliance opens HVAC insulation share for early movers abandoning HFC blowing agents. |
| Devulcanization Technology Deployment | Post-industrial scrap recovery enables circularity claims in premium wetsuit and athletic equipment channels. |
| Peroxide-Cured Grade Qualification | 150°C continuous service certification displaces fluorocarbon elastomers in German transmission applications. |
| Closed-Loop Solvent Recovery Investment | REACH SVHC disclosure mandates force Leverkusen compounders to real-time residual monitoring systems. |
Study Parameters
Trade databases, ECHA regulatory filings, and automotive OEM procurement disclosures formed the secondary backbone of this analysis. Primary interviews with chloroprene plant managers, Tier-1 gasket supplier procurement leads, and marine foam distribution channel partners validated demand assumptions. Bottom-up and top-down triangulation cross-checked volume estimates against customs data and downstream consumption surveys.
Bottom-up modeling built from grade-level production capacity, utilization rates, and end-use consumption patterns across the projection horizon. Segmentation dimensions spanned product form, curing system, certification tier, and regional production hub. CAGRs derived from regression analysis against automotive production forecasts and building energy code adoption curves, with chloroprene monomer capacity expansion schedules and REACH compliance cost absorption as key sensitivity inputs.
Inputs from Chinese MEE enforcement records and Korean shipyard order books were available through the study window; gaps in real-time automotive OEM compound qualification timelines introduce uncertainty bands around near-term volume allocations. Forecasts reflect documented assumptions on feedstock cost trajectories and regulatory phase-in schedules. A small set of triggers—REACH SVHC list expansion, Shandong wastewater enforcement intensity, and India PLI disbursement pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Reclaimed Rubber Market
Rubber
Performance Elastomers Market
Rubber
Rubber Chemicals Market
Rubber
Rubber Foam Materials Market
Rubber
Rubber Coatings Market
Rubber
Global Medical Rubber and Balloon Products Consumption Market
Rubber
Rubber Rollers Market
Rubber
Synthetic Rubber Market
Rubber
EPDM Market
Rubber
Rubber Plated Hose Market
Rubber
Co-Extruded Rubber Profiles Market
Rubber
Rubber Conveyor Belt Market
Rubber
Global Rubber Process Oil Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
Global Rubber Additives Market
Rubber
Industrial Rubber Market