
 FKM Elastomers Market | 2026-2036
FKM Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
FKM Elastomers Market Foresight
Aftermarket service revenue is narrowing as a margin pool for compounders relative to virgin polymer sales. Daikin Industries leverages captive fluorine chemistry to sustain integrated feedstock control from ore to finished elastomer. Solvay S.A. anchors its position through specialty grades targeting perfluoroelastomer applications in semiconductor fabrication. Gujarat Fluorochemicals Limited competes on cost-optimized copolymer FKM for automotive gasket programs across South Asian supply chains.
FKM elastomers are fluorocarbon-based synthetic rubbers containing vinylidene fluoride and hexafluoropropylene repeat units, delivering continuous service temperatures above 200°C alongside resistance to aromatic hydrocarbons and strong acids. Manufacturers produce these materials through free-radical emulsion polymerization followed by bisphenol or peroxide curing to achieve compression set performance required in dynamic sealing. Copolymer FKM retains the largest volume share for general automotive and industrial applications where cost-performance balance governs specification. Perfluoroelastomer segments command premium positioning in semiconductor etch equipment and aerospace fuel systems where near-universal chemical resistance justifies material cost multiples over standard grades.
The EPA enforces emissions standards that elevate fluoropolymer durability requirements in automotive and chemical processing equipment. REACH and RoHS frameworks in Europe restrict certain curing system chemistries, redirecting formulation development toward peroxide-curable architectures. The EU F-Gas Regulation phases down hydrofluorocarbon production, pressuring raw material pathways for conventional FKM synthesis. Stakeholders must monitor regulatory divergence between EPA tailpipe rules and European chemical restrictions when allocating R&D across regional product lines.
Market Dynamics
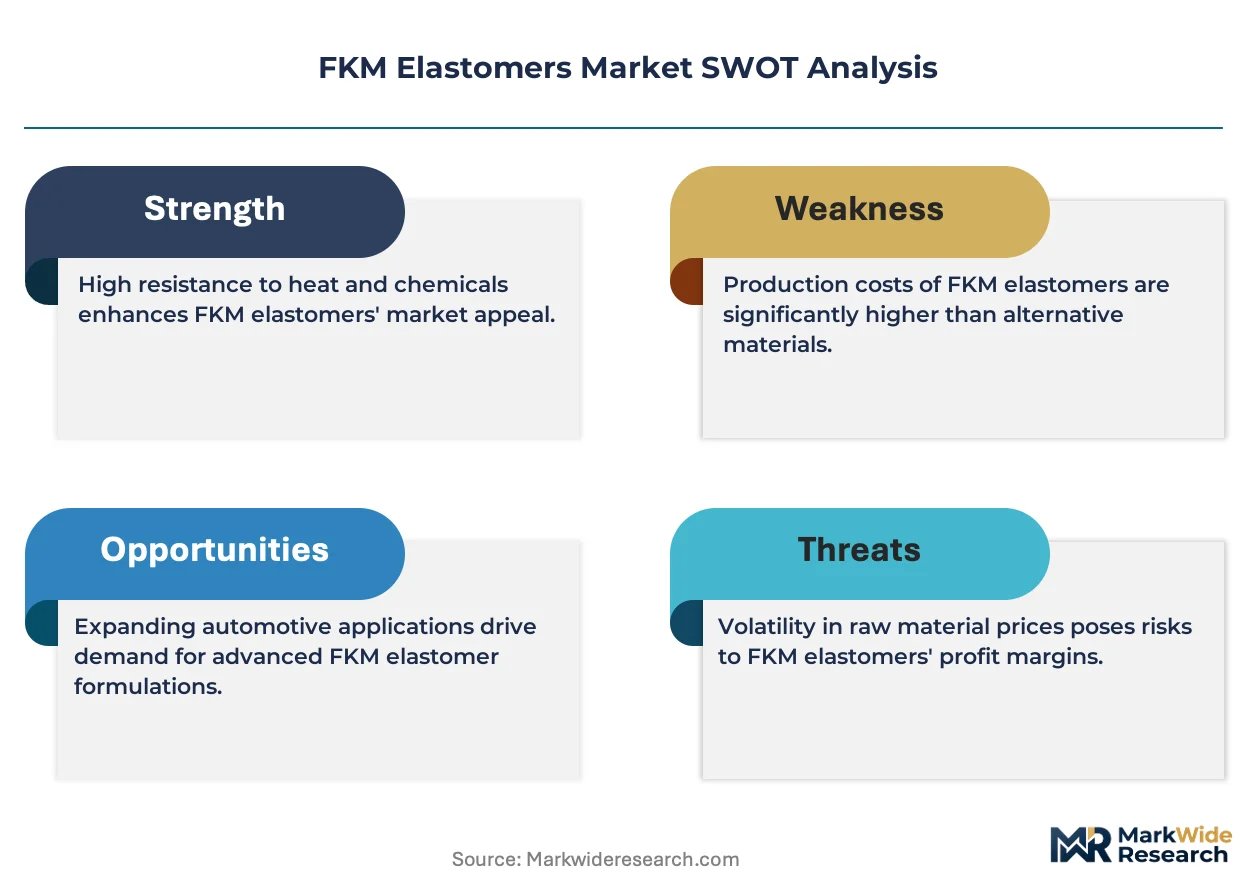
The EU F-Gas Regulation is forcing a fundamental recalibration of fluoropolymer feedstock pathways, compressing conventional vinylidene fluoride supply chains while redirecting capital toward alternative synthesis routes and peroxide-curable architectures.
Growth Catalysts
- Aerospace fleet modernization:Aircraft OEM procurement of high-performance seals is accelerating as narrow-body and wide-body production rates recover, concentrating demand in fuel system and engine sealing applications.
- REACH and RoHS frameworks:European chemical restrictions on bisphenol curing systems are redirecting formulation development toward peroxide-curable FKM architectures with superior compression set performance.
- Semiconductor fabrication expansion:Perfluoroelastomer demand for etch chamber sealing is rising alongside wafer fab capacity additions in East Asia and North America.
Market Restraints
- Fluorinated feedstock concentration:Captive fluorspar-to-VDF integration at major chemical conglomerates limits independent compounder access to cost-competitive monomer supply.
- Hydrofluorocarbon phase-down mechanics:The EU F-Gas Regulation's staged production quotas are tightening raw material availability for conventional emulsion polymerization routes.
- Thermoplastic elastomer substitution:High-performance TPVs are capturing select automotive coolant hose applications where service temperature requirements have moderated.
Strategic Opportunities
- India automotive gasket programs:Cost-optimized copolymer FKM specifications are penetrating South Asian supply chains as domestic OEM localization mandates intensify.
- Hydrogen infrastructure sealing:Emerging demand for permeation-resistant elastomers in fuel cell systems and high-pressure storage vessels is opening specification windows beyond traditional fuel resistance metrics.
- EPA tailpipe durability standards:Extended emissions system warranty requirements are elevating material specifications for turbocharger hoses and fuel injector seals in US passenger vehicle platforms.
Industry Challenges
- Fluoropolymer compounding expertise scarcity:The specialized knowledge required for peroxide cure system optimization and metal adhesion promotion is concentrating at a shrinking pool of technical specialists.
- Multi-jurisdiction certification timelines:Parallel qualification protocols under EPA, ECHA, and OEM-specific material approval systems are extending new grade introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FKM Elastomers Market |
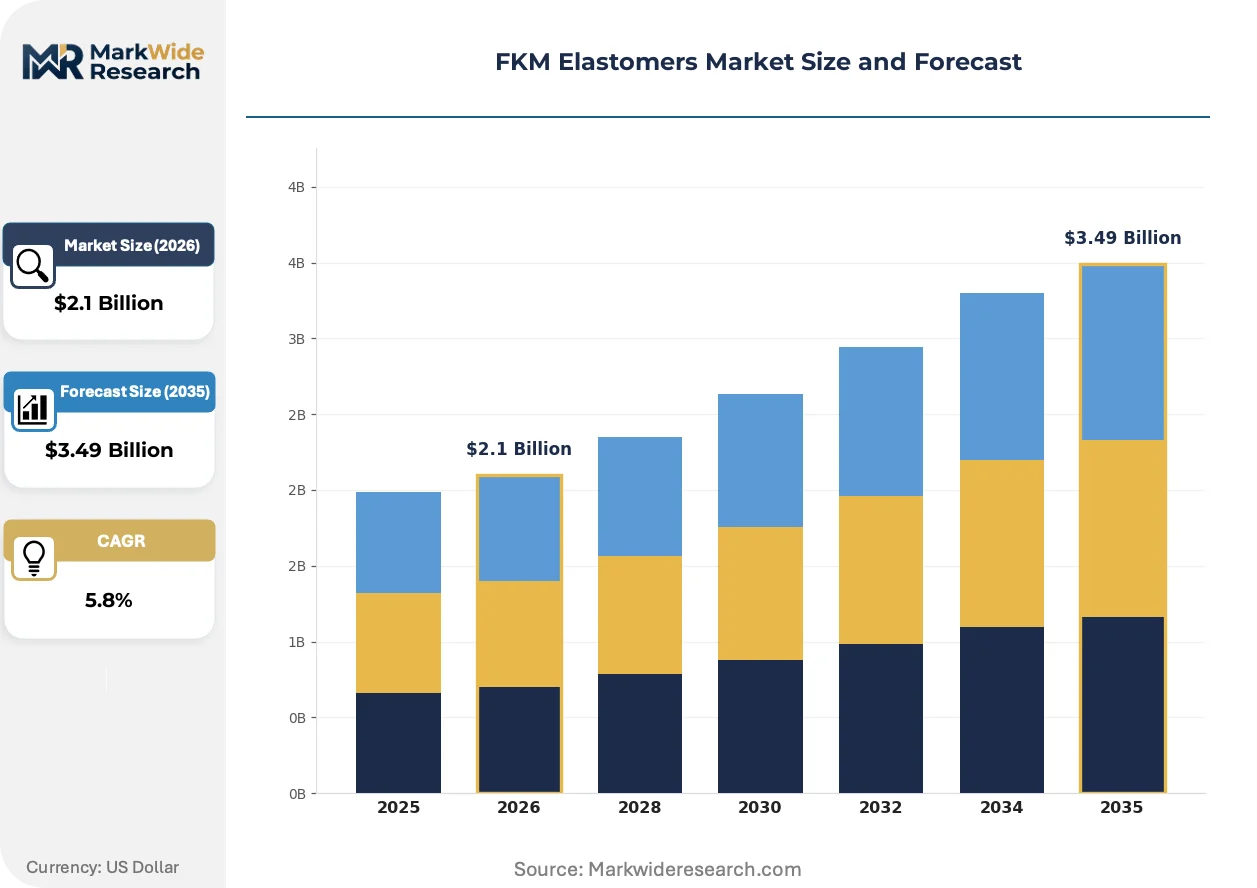
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
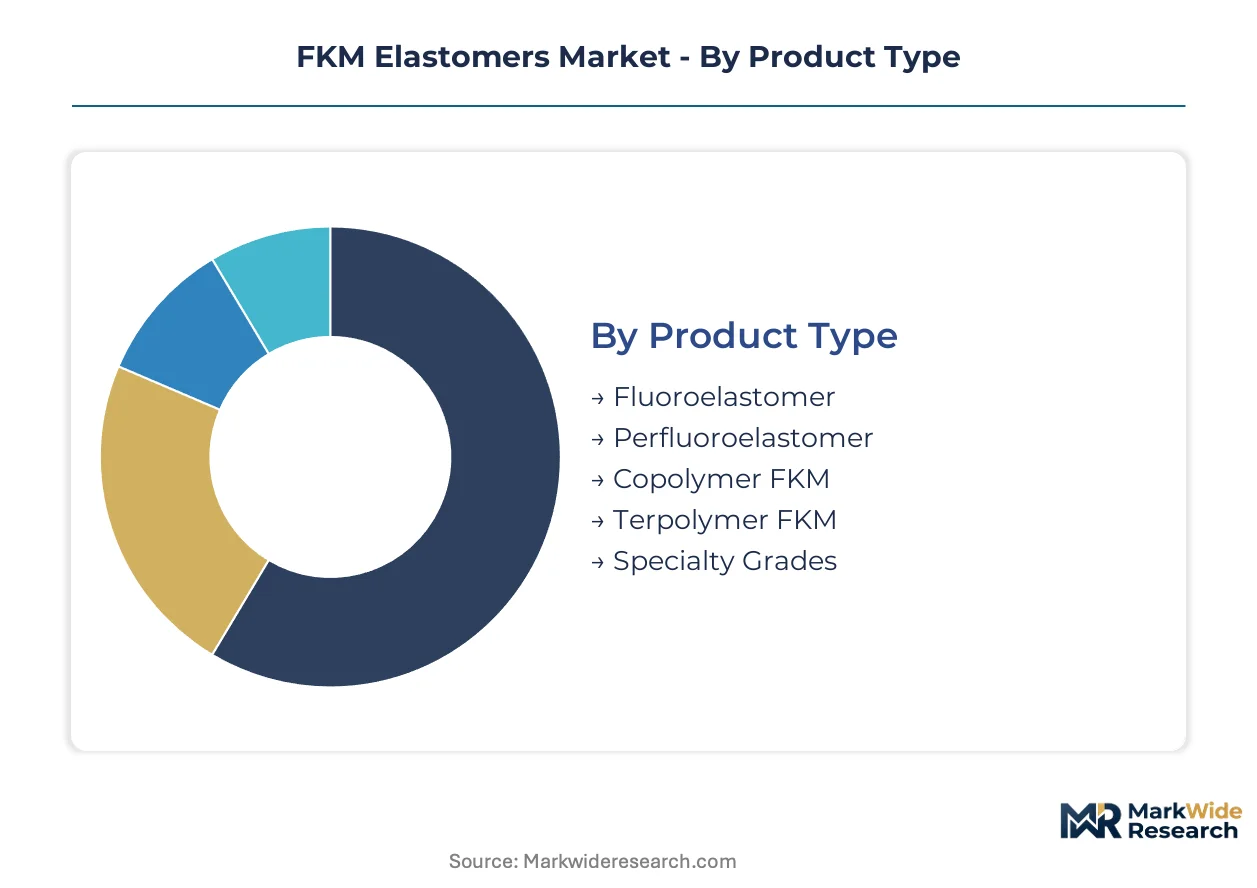
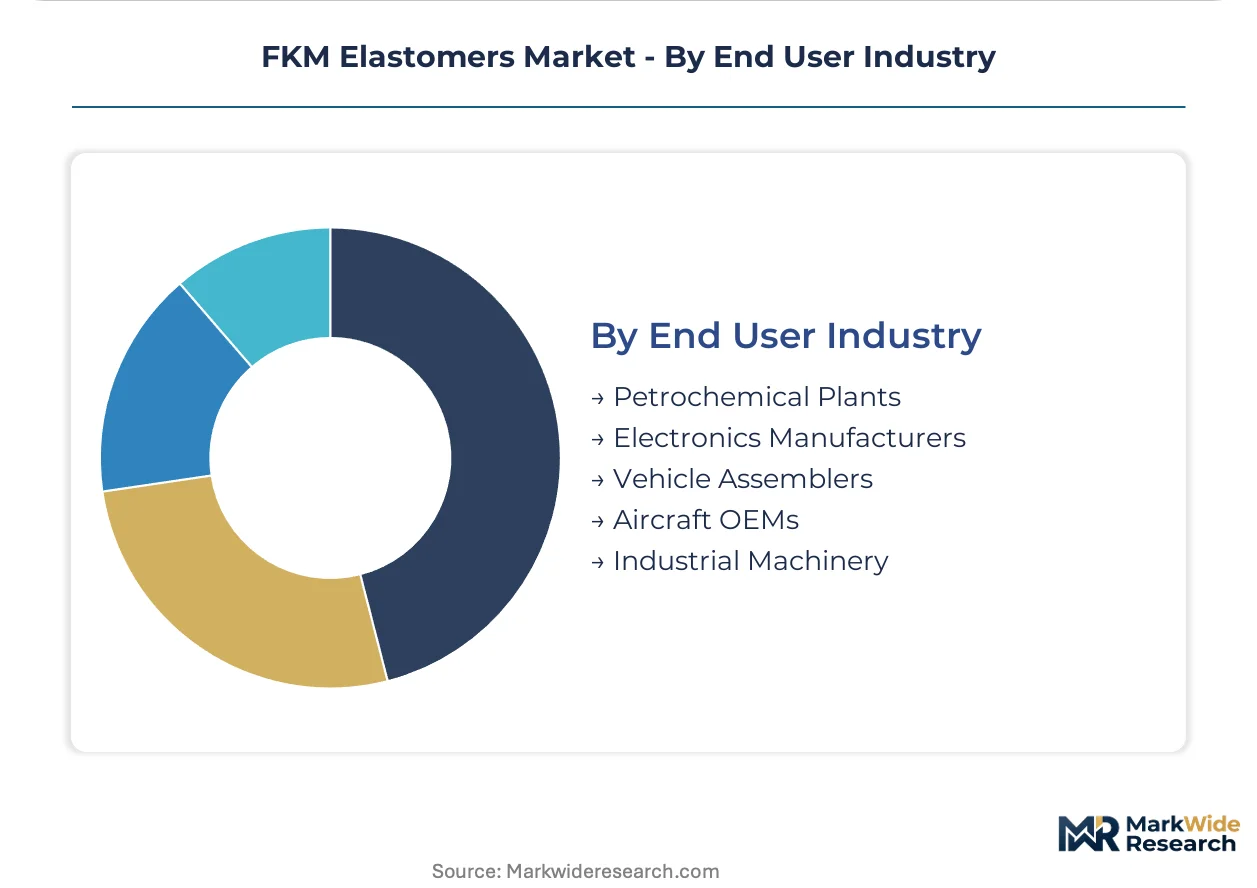
| Segmentation | Product Type: Fluoroelastomer, Perfluoroelastomer, Copolymer FKM, Terpolymer FKM, Specialty Grades Technology: Injection Molding, Compression Molding, Transfer Molding, Extrusion, Reaction Injection Molding Application: Aerospace Seals, Chemical Processing Components, Automotive Gaskets, Electrical Insulation, Oil & Gas Components End User Industry: Petrochemical Plants, Electronics Manufacturers, Vehicle Assemblers, Aircraft OEMs, Industrial Machinery |
| Companies Covered | 3M, AGC Inc., The Chemours Company, DuPont, Shin-Etsu Chemical Co., Ltd., Daikin Industries, Ltd., Gujarat Fluorochemicals Limited, Zeon Corporation, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FKM Elastomers Market Shifts & Advancements
Peroxide-curable FKM architectures are displacing legacy bisphenol systems across multiple end-use verticals, while regulatory pressure on fluorinated feedstocks is accelerating process chemistry innovation and supply chain reconfiguration.
Advanced peroxide cure systems incorporating improved radical scavenger packages are rendering obsolete conventional bisphenol-crosslinked grades in dynamic sealing applications. Automotive OEMs in Germany and Japan are specifying these architectures for turbocharger intercooler hoses and transmission seals. The shift is compressing compounder R&D cycles and elevating technical service requirements for cure kinetic optimization.
The EU F-Gas Regulation's hydrofluorocarbon production phase-down is tightening vinylidene fluoride monomer availability across European manufacturing corridors. Chemical processors are responding by qualifying alternative feedstock routes and accelerating in-house fluorine recovery investments. Semiconductor equipment manufacturers face the most acute material security pressures given perfluoroelastomer dependence on constrained HFC-134a pyrolysis pathways.
Specification consolidation among tier-one automotive suppliers is compressing approved vendor lists and elevating compounder qualification barriers. Buyers are unbundling compound supply from technical service contracts, forcing mid-scale producers to compete on formulation expertise rather than volume scale. This pattern is most pronounced in Germany's industrial corridor, where Volkswagen Group and BMW procurement frameworks are consolidating elastomer supply base.
FKM Elastomers Market Segmentation
FKM elastomer procurement cycles vary dramatically by segment—automotive gasket programs refresh annually while aerospace fuel system seals carry decade-long qualification timelines. Understanding these velocity differentials shapes inventory strategy and R&D allocation across the value chain.
Product Type:
Inventory turnover correlates inversely with fluorine content—standard copolymers move through supply chains fastest while perfluoroelastomers sit in strategic stockpiles awaiting semiconductor tool builds.
- Copolymer FKM:Vinylidene fluoride-hexafluoropropylene copolymers deliver the cost-performance balance that dominates automotive transmission seals and coolant hoses. German vehicle assemblers specify these grades for high-volume turbocharger plumbing where 200°C continuous service suffices. The segment turns inventory fastest due to standardized OEM approval lists and predictable replacement schedules.
- Perfluoroelastomer:Fully fluorinated backbone structures achieve near-universal chemical resistance for semiconductor etch chamber sealing and aerospace fuel systems. Wafer fab equipment manufacturers in Japan and the United States qualify these materials for 300°C plasma environments where parts-per-billion contamination tolerance governs yield. Lead times extend to 26 weeks given monomer scarcity and cleanroom packaging requirements.
- Fluoroelastomer:Base FKM grades serve general industrial sealing where aromatic hydrocarbon resistance takes priority over temperature extremes.
- Terpolymer FKM:Tetrafluoroethylene incorporation elevates base resistance for chemical processing valve seals in Germany's industrial corridor.
- Specialty Grades:Metal-adhesive modified formulations target bonded composite seals for aircraft engine applications.
Copolymer FKM anchors the volume base while perfluoroelastomer gains share at the steepest rate.
Technology:
Tooling amortization schedules separate high-volume automotive programs from low-mix aerospace work—compression molding dominates where cavity counts justify steel investment while transfer molding persists for prototype-to-production transitions.
- Injection Molding:Automated cavity filling with precise shot control enables automotive O-ring production at cycle times under 90 seconds. Volkswagen Group suppliers in Wolfsburg operate 128-cavity tools for fuel injector seals where flash tolerance below 0.05mm eliminates secondary trimming.
- Compression Molding:Open cavity pressing accommodates oversized aerospace seals where charge weight variability exceeds injection unit capacity. Suppliers to Boeing and Airbus in Toulouse maintain hydraulic presses to 1000-ton capacity for engine mount gaskets requiring post-cure oven cycles.
- Transfer Molding:Intermediate complexity tooling bridges prototype validation and production scale-up for chemical processing diaphragms.
- Extrusion:Continuous profile generation supplies turbocharger hose tubing to tier-one automotive suppliers in Stuttgart.
- Reaction Injection Molding:Liquid component mixing enables complex geometries for electrical connector seals in electronics manufacturing.
Injection molding commands the largest installed equipment base while reaction injection molding expands most quickly in electronics applications.
Application:
Specification intensity stratifies sharply—aerospace fuel seals require FAA certification trails while automotive coolant hoses operate under self-certified compounder specifications.
- Automotive Gaskets:Cylinder head and transmission pan seals represent the highest volume outlet where EPA emissions durability standards extend warranty periods to 150,000 miles. Ford and General Motors procurement frameworks consolidate approved vendor lists around peroxide-curable architectures.
- Aerospace Seals:Fuel system and engine sealing applications demand AMS-R-83485 qualification with traceable batch records. Safran and Collins Aerospace buyers in France and Iowa enforce lot-specific rheology data for flight-critical components.
- Chemical Processing Components:Valve seats and pump diaphragms in Germany's Ludwigshafen chemical cluster prioritize permeation resistance.
- Oil & Gas Components:Downhole packer elements for North Sea platforms require sour gas compatibility testing.
- Electrical Insulation:Wire jacketing for high-temperature motor leads in industrial machinery tolerates broader specification windows.
Automotive gaskets generate the highest absolute volume while aerospace seals command the steepest pricing premiums.
End User Industry:
Consolidation patterns diverge—vehicle assemblers reduce supply bases aggressively while petrochemical plants maintain multi-source strategies for operational continuity.
- Vehicle Assemblers:Platform-commonality programs at Toyota and Hyundai Motor Group compress compounder counts to three approved suppliers per seal category. Just-in-sequence delivery mandates force regional compounding investments in Indiana, Kentucky, and Alabama.
- Aircraft OEMs:Boeing and Airbus long-term agreements specify minimum five-year compound supply security with audited secondary source qualification. Wichita and Hamburg aerostructures suppliers carry 180 days strategic inventory given qualification timelines.
- Petrochemical Plants:BASF and Dow maintenance schedules drive spot purchasing for turnaround rebuild kits.
- Electronics Manufacturers:Taiwan Semiconductor and Intel fab expansion programs concentrate perfluoroelastomer demand.
- Industrial Machinery:Distributed OEM base sustains fragmented demand across pump, valve, and compressor rebuild markets.
Vehicle assemblers concentrate procurement fastest while electronics manufacturers expand specification intake most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Asia exhibit acute price sensitivity for standard copolymer grades, while semiconductor equipment manufacturers in Japan and the United States accept steep premiums for perfluoroelastomer supply security. This demand-elasticity contrast shapes regional procurement strategies and inventory positioning across the value chain.
United States
Aerospace seal demand from Boeing and Collins Aerospace concentrates in Wichita and Seattle, where AMS-R-83485 qualification timelines extend to 18 months. The EPA enforces tailpipe durability standards that elevate FKM specifications for turbocharger hoses. Semiconductor equipment manufacturers in Hillsboro, Oregon carry strategic perfluoroelastomer inventories given constrained HFC-134a pyrolysis feedstock.
Germany
Volkswagen Group and BMW procurement frameworks in Wolfsburg and Munich consolidate approved compounder lists to three suppliers per seal category. The EU F-Gas Regulation phases down hydrofluorocarbon production, pressuring VDF monomer availability. BASF and Covestro maintenance schedules in Ludwigshafen drive spot purchasing for chemical processing valve rebuild kits.
China
Wafer fab capacity expansion in Shanghai and Hefei concentrates perfluoroelastomer demand for etch chamber sealing. The country's dual carbon goals redirect fluoropolymer investment toward alternative synthesis routes. Domestic automotive OEMs in Guangdong province localize gasket supply chains under government-mandated component sourcing programs.
Japan
Tokyo Electron and Shin-Etsu procurement networks qualify FKM grades for 300°C plasma environments where contamination tolerance governs semiconductor yield. METI industrial standards govern fluorspar-to-elastomer supply chain traceability. Nagoya-based tier-one suppliers operate just-in-sequence delivery systems for Toyota platform-commonality programs.
India
Maruti Suzuki and Hyundai Motor India localization mandates intensify cost-optimized copolymer FKM penetration for cylinder head gaskets. The PLI scheme for automotive components attracts compounding investment to Gujarat and Tamil Nadu. Fluorochemical production clusters in Vadodara supply feedstock to domestic elastomer manufacturers serving South Asian aftermarket channels.
FKM Elastomers Market Competitive Landscape
Capability concentration sits with integrated fluorine chemistry specialists; scale advantage sits with diversified polymer conglomerates. The market structures around three tiers: captive fluorspar-to-VDF producers, independent compounders with formulation expertise, and regional fabricators serving aftermarket rebuild markets. Strategic moves center on backward integration into monomer supply and qualification consolidation with tier-one automotive OEMs.
Within the integrated chemistry tier, Daikin Industries and Gujarat Fluorochemicals Limited exemplify divergent geographic and cost-positioning strategies. Among specialty-grade specialists, Solvay S.A. occupies a position defined by perfluoroelastomer focus for semiconductor fabrication equipment. These three companies represent the archetype spectrum from captive feedstock control through cost-optimized copolymer supply to premium perfluoroelastomer positioning.
| Leading Market Players |
|---|
| 3M |
| AGC Inc. |
| The Chemours Company |
| DuPont |
| Shin-Etsu Chemical Co., Ltd. |
| Daikin Industries, Ltd. |
| Gujarat Fluorochemicals Limited |
| Zeon Corporation |
| Solvay S.A. |
| Others |
Supply & Pricing Matrix
Single-source dependency on HFC-134a pyrolysis feedstock for perfluoroelastomer synthesis determines both the extreme pricing tier spreads between semiconductor-grade and automotive copolymer grades and the geographic concentration of strategic inventory buffers. Buyers facing EU F-Gas Regulation phase-down quotas accept material cost multiples while downstream compounders absorb margin compression from captive VDF producers.
Pricing Analysis
Aftermarket service contracts and extended technical support agreements drive lifetime value capture for integrated fluorine chemistry specialists. Three-tier pricing structure across perfluoroelastomer, terpolymer FKM, and standard copolymer grades reflects fluorine content and certification burden. Price differentiation hinges on AMS-R-83485 aerospace qualification and EPA emissions durability certification. Cost compression in automotive copolymer tiers intensifies as tier-one OEMs consolidate approved vendor lists. South Asian vehicle assemblers exhibit acute price sensitivity while semiconductor equipment manufacturers in Japan accept steep premiums for supply security.
Supply Chain Analysis
Vinylidene fluoride monomer production concentrates in China, Japan, and the United States where integrated fluorspar-to-elastomer operations anchor supply. Raw material pathways draw from fluorspar ore concentrates, hydrofluorocarbon intermediates, and peroxide cure system additives. Single-source vulnerability pervades HFC-134a pyrolysis routes for perfluoroelastomer feedstock. Distribution runs through tier-one automotive supplier hubs in Germany, regional compounding facilities in India, and semiconductor equipment clusters in East Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as hydrogen infrastructure sealing applications open specification windows beyond traditional fuel resistance metrics. Aerospace fleet modernization and semiconductor fabrication capacity additions provide durable demand tailwinds.
For Market Incumbents: Build captive feedstock moats through backward integration into fluorspar mining and VDF monomer production. Daikin Industries exemplifies this architecture from ore to finished elastomer. Defend against thermoplastic elastomer substitution by accelerating peroxide-curable grade qualification with Volkswagen Group and BMW procurement frameworks. Prioritize certification investment for EPA tailpipe durability standards.
For New Entrants and Emerging Players: Cost-optimized copolymer specifications for Maruti Suzuki and Hyundai Motor India localization programs represent the most penetrable entry point. Gujarat Fluorochemicals Limited demonstrates viable positioning through South Asian supply chain penetration. Chemical processing valve rebuild kits for BASF and Covestro maintenance schedules offer secondary white-space. Go-to-market through regional compounding joint ventures bypasses captive feedstock barriers.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors integrated chemistry specialists with monomer control. Long-term viability over the next decade rests on regulatory navigation capability between EPA tailpipe rules and EU F-Gas Regulation phase-down mechanics. Acquisition target archetype: mid-scale compounders with peroxide cure system expertise and existing tier-one automotive qualifications. Monitor EU hydrofluorocarbon production quota announcements as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive VDF monomer supply insulates Daikin Industries from EU F-Gas Regulation quota pressures. |
| Peroxide Cure System Qualification | REACH-compliant architectures displace legacy bisphenol systems at Volkswagen Group suppliers. |
| Regional Compounding Investment | Gujarat and Tamil Nadu facilities serve Maruti Suzuki just-in-sequence delivery mandates. |
| Long-term Supply Agreement | Boeing and Airbus frameworks specify minimum five-year compound security with audited secondary sources. |
| Alternative Feedstock Route Development | Fluorine recovery investments respond to HFC-134a pyrolysis pathway constraints. |
Research Methodology
The analysis maps copolymer FKM, perfluoroelastomer, terpolymer, and specialty grade segments, each validated through procurement managers at tier-one automotive suppliers, aerospace seal qualification engineers, semiconductor equipment material scientists, and chemical processing maintenance directors. Primary fieldwork combined with secondary validation from SEC 10-K filings, customs and trade data, ACC and Cefic industry reports, and EPA emissions certification databases. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Assumptions held fixed include current EU F-Gas Regulation phase-down trajectories, EPA tailpipe durability warranty periods, and semiconductor fabrication capacity expansion plans across East Asia and North America. Variables stress-tested encompass hydrofluorocarbon production quota revisions, REACH curing system restriction amendments, and thermoplastic elastomer substitution rates in automotive coolant applications. The projection horizon spans product type, technology platform, application intensity, and end-user industry consolidation patterns. CAGRs derived from segment-level volume elasticity models and value-per-kilogram progression curves.
Stress conditions across fluorspar ore price volatility, HFC-134a availability constraints, and automotive OEM vendor consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory acceleration or feedstock pathway disruption. Cross-checking against IHS Markit vehicle production databases and SEMI wafer fab equipment forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Rubber Wear Liners Market
Rubber
Rubber Accelerators Market
Rubber
Acrylic Rubber Market
Rubber
Rubber Tapes Market
Rubber
Rubber Sheets Market
Rubber
Global Rubber Market
Rubber
Silicone Rubber Market
Rubber
Tire Reinforcement Materials Market
Rubber
Natural Rubber Market
Rubber
Polybutadiene Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Global Rubber Process Oil Market
Rubber
Butyl Rubber Market
Rubber
Corrosion Protection Rubber Linings and Coatings Market
Rubber
Rubber Foam Market