
 Global Vinyl Sulfone Market | 2026-2036
Global Vinyl Sulfone Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vinyl Sulfone Market Foresight
The capability gap between integrated dye manufacturers and commodity traders is rotating competitive advantage toward firms with captive sulfonation capacity. Bodal Chemicals Ltd. leverages backward integration into vinyl sulfone intermediates to secure margin pools across the textile dye value chain. Kiri Industries Limited anchors its position through dedicated manufacturing scale at its Gujarat facilities. Atul Ltd. differentiates via technology leadership in specialty vinyl sulfone derivatives for export markets.
Vinyl sulfone denotes a class of reactive organic compounds containing the vinyl sulfonyl functional group (CH2=CH-SO2-), synthesized through sulfonation of ethylene or oxidation of thioethers, primarily serving as coupling agents in reactive dye chemistry for cellulose fiber coloration. Di vinyl sulfone dominates volume consumption due to its established role in navy and black reactive dye formulations, while vinyl sulfone resin commands premium pricing in adhesive crosslinking applications where thermal stability requirements exceed standard textile grades. The powder form segment sustains higher logistics costs but occupies irreplaceable positions in water treatment chemical blending operations.
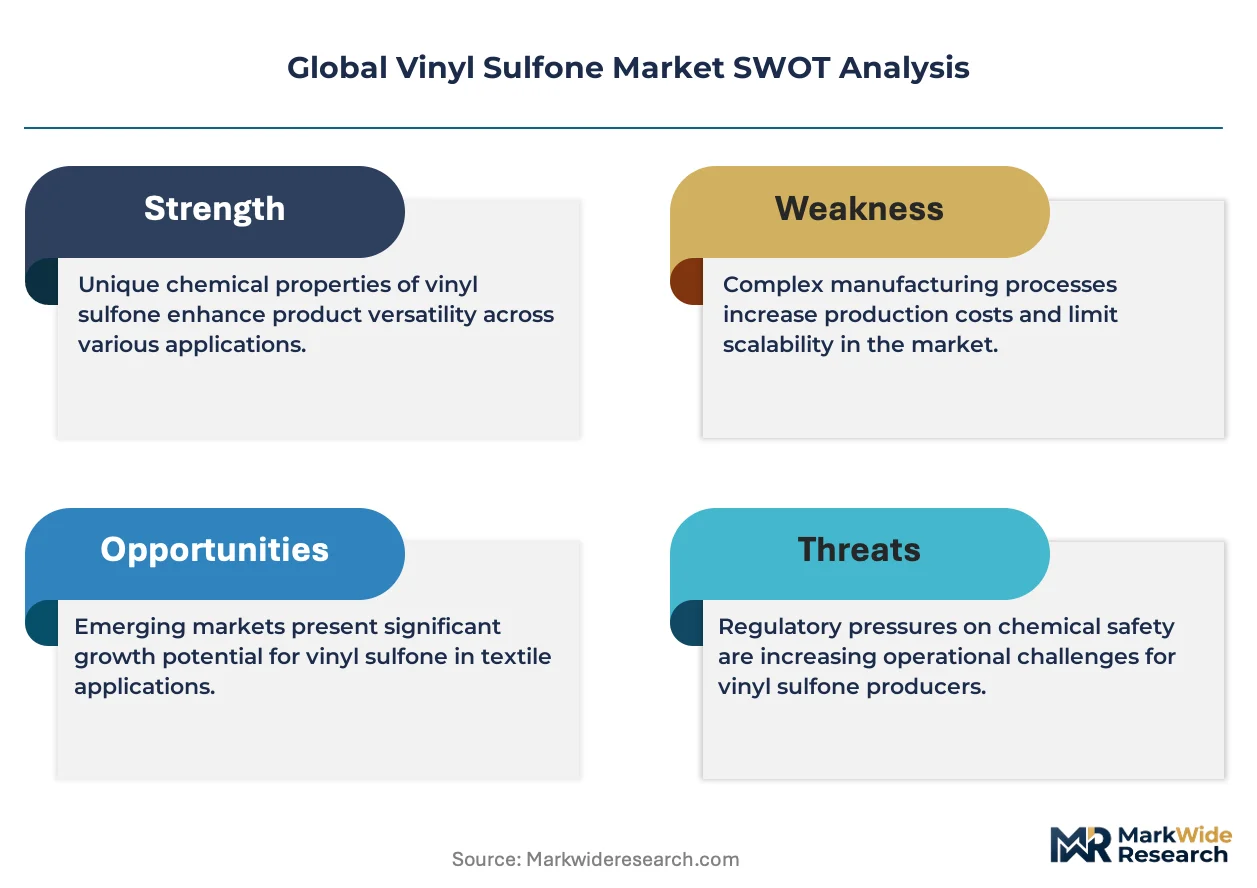
REACH registration requirements in Europe, EPA discharge standards for textile effluents in the United States, and China's MEE emission controls for chemical parks collectively elevate compliance costs for non-integrated producers. India's Central Pollution Control Board mandates zero liquid discharge at bulk chemical clusters, forcing capacity consolidation among smaller vinyl sulfone manufacturers. Stakeholders must monitor regulatory divergence between OECD chemical safety frameworks and emerging economy enforcement capacity gaps to anticipate supply chain relocation decisions.
Market Dynamics
REACH azo compound limits in Europe are compressing legacy dye intermediate supply chains while simultaneously redirecting volume toward vinyl sulfone chemistry, forcing textile chemical manufacturers to revalidate entire formulation portfolios around sulfone-based coupling agents.
Growth Catalysts
- Cellulose fiber demand surge:Global apparel brands are expanding cotton and viscose sourcing commitments, directly amplifying consumption of reactive dyes requiring vinyl sulfone coupling chemistry for color fastness.
- India's ZLD mandates:The Central Pollution Control Board's zero liquid discharge requirements at bulk chemical clusters are accelerating consolidation among compliant integrated manufacturers with captive sulfonation assets.
- Water treatment chemical expansion:Municipal utilities in the United States and Germany are scaling vinyl sulfone resin procurement for membrane crosslinking applications in advanced filtration systems.
Market Restraints
- Ethylene feedstock volatility:Vinyl sulfone synthesis depends on ethylene sulfonation pathways exposed to naphtha-cracking economics and regional olefin supply imbalances.
- Gujarat corridor concentration:Over half of India's merchant vinyl sulfone capacity sits within a 200-kilometer radius of Ankleshwar and Vapi, creating single-point geographic vulnerability.
- Epoxy silane substitution:Adhesive formulators in automotive assembly applications are piloting alternative crosslinkers with comparable thermal stability profiles at lower curing temperatures.
Strategic Opportunities
- Vietnam textile manufacturing:Fabric dyeing capacity relocation from China is creating virgin demand for reactive dye intermediates among Ho Chi Minh City corridor processors lacking established sulfone supplier relationships.
- EU Green Deal chemistry:The European Commission's sustainable textile strategy is incentivizing bio-based vinyl sulfone derivative development through Horizon Europe innovation funding.
- Digital inventory platforms:Specialty chemical distributors are launching just-in-time procurement portals that reduce working capital requirements for mid-scale dye houses.
Industry Challenges
- Sulfonation process engineering expertise:The specialized knowledge required for controlled vinyl sulfone synthesis with minimal byproduct formation has concentrated among a shrinking cohort of veteran chemical engineers.
- REACH registration timelines:New derivative commercialization in Europe faces 18-24 month dossier preparation periods that compress product launch windows against faster-moving Asian competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vinyl Sulfone Market |
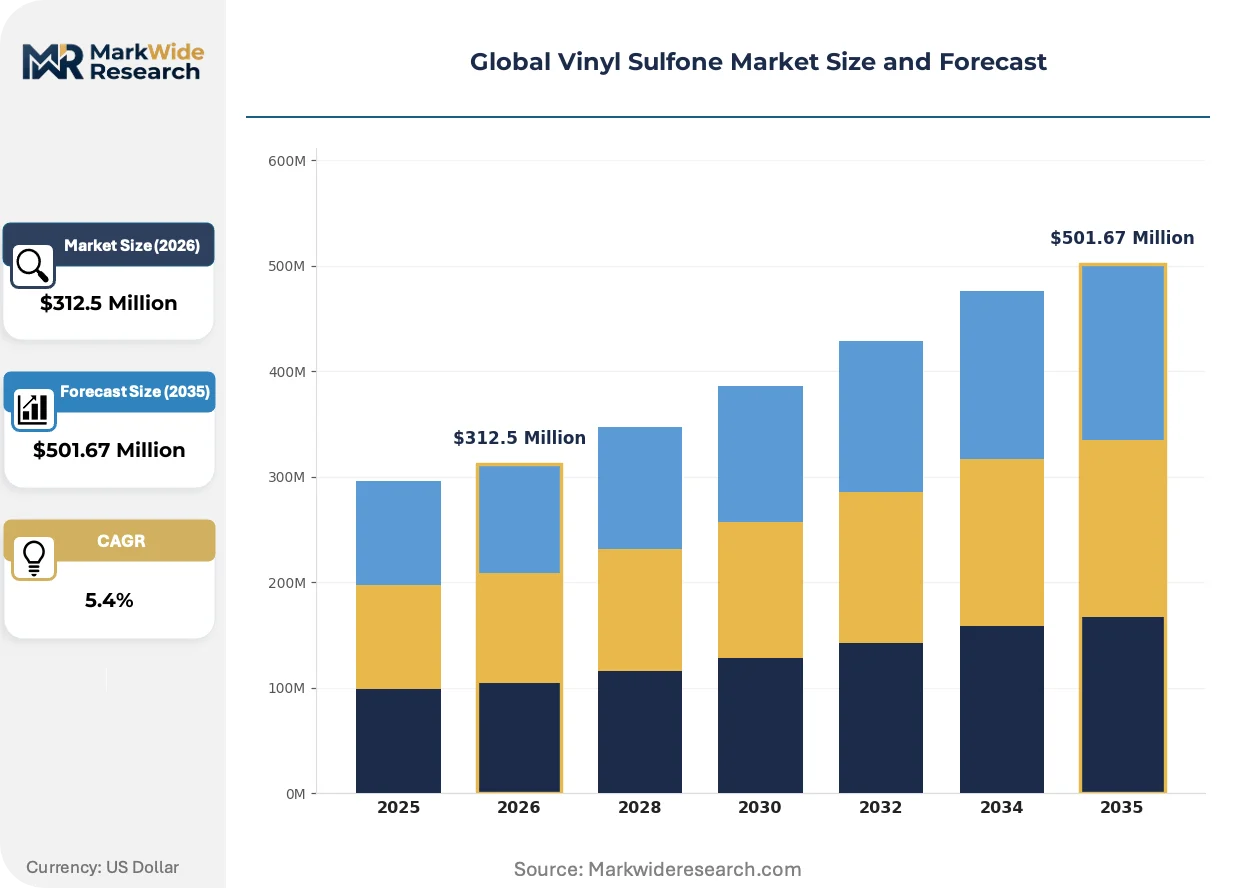
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono Vinyl Sulfone, Di Vinyl Sulfone, Divinyl Sulfone Derivatives, Vinyl Sulfone Resin Application: Dye Intermediates, Textile Printing, Water Treatment, Chemical Crosslinking Agents End User Industry: Textile Manufacturers, Paper Processing Companies, Leather Manufacturers, Adhesive Producers Form: Liquid, Powder, Granules, Emulsion |
| Companies Covered | Bodal Chemicals Ltd., Kiri Industries Limited, Shree Pushkar Chemicals and Fertilisers Ltd., Bhageria Industries Limited, Atul Ltd., Sigma-Aldrich (Merck KGaA), AksharChemIndia, Ambuja Intermediates Pvt. Ltd., Mayur Dye-chem Intermediates LLP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vinyl Sulfone Market Shifts & Advancements
Continuous processing technology is displacing batch sulfonation across vinyl sulfone manufacturing, while regulatory chemistry mandates in Europe and effluent enforcement in Asia are rewriting formulation specifications throughout the textile dye value chain.
Membrane-based sulfonation systems are bifurcating competitive positioning between integrated manufacturers with capital-intensive continuous assets and commodity traders dependent on legacy batch operations. Specialty dye houses in Italy and Turkey are prioritizing suppliers with membrane-verified batch consistency for navy and black reactive formulations. The technology is compressing margin pools for non-integrated intermediaries while rewarding firms with in-house sulfonation engineering capabilities.
ECHA's 2023 update to REACH restriction entries for aromatic amines is forcing reformulation of legacy reactive dye portfolios across European textile finishers. The regulation's tightened migration limits for specific amine cleavage products is accelerating technical service investments by vinyl sulfone manufacturers to support customer requalification programs. German and Benelux dye houses are responding by consolidating supplier relationships toward partners with documented sulfonation traceability systems.
Specification-driven procurement is consolidating buyer power among tier-one apparel brands with mandated chemical management protocols. Mid-scale dye houses in Bangladesh and Pakistan are losing direct supplier access as purchasing decisions migrate to centralized sustainability compliance teams at headquarters level. The shift is most visible in denim processing clusters where ZDHC MRSL conformance has become a non-negotiable supplier qualification threshold.
Global Vinyl Sulfone Market Segmentation
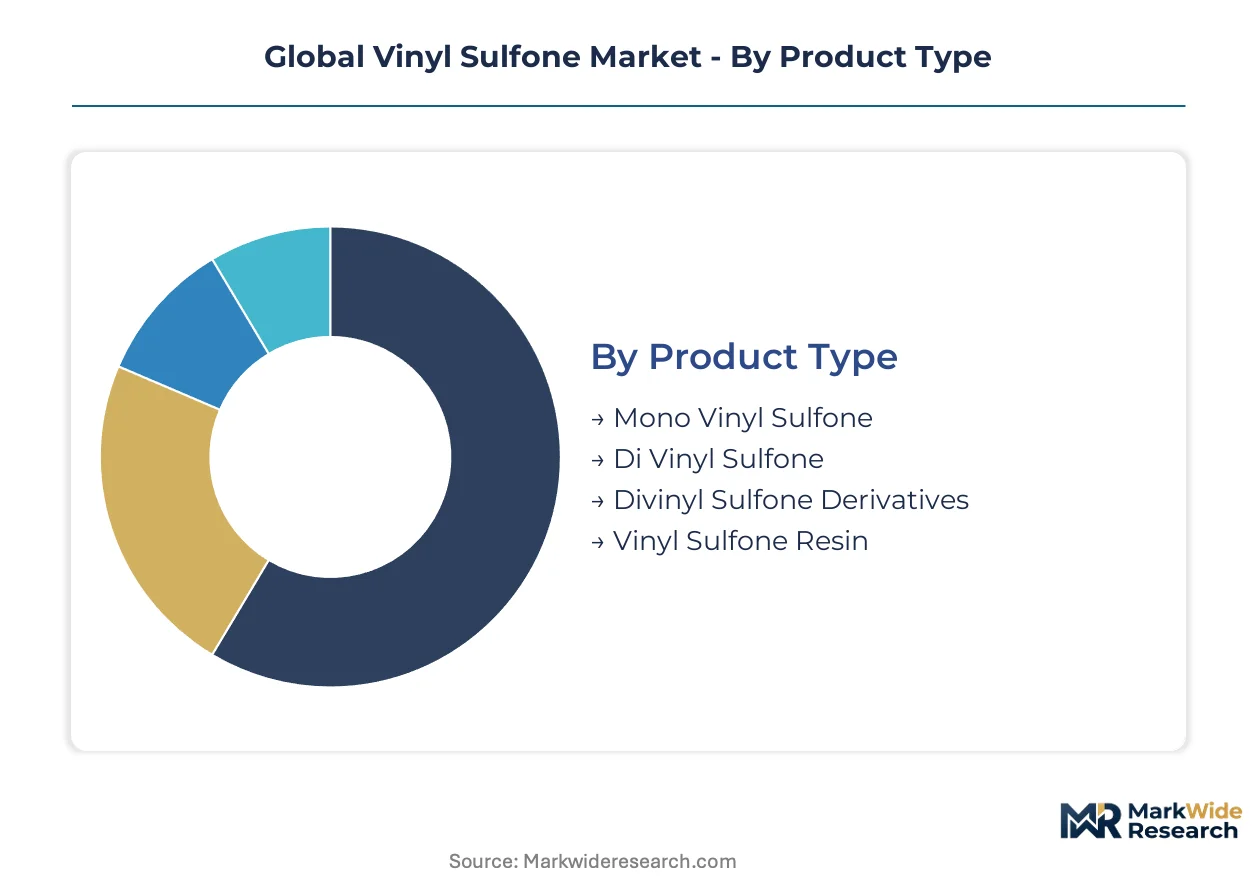
Segmentation in vinyl sulfone markets exposes divergent vulnerability profiles to substitute chemistries and regulatory displacement. Each dimension reveals distinct margin architectures and competitive moats that reshape procurement patterns across textile, water treatment, and adhesive end-uses.
Product Type:
Substitution pressure from epoxy silanes and alternative crosslinkers intensifies competition most acutely in commodity vinyl sulfone grades, while specialty derivatives retain defensive positioning through formulation lock-in.
- Mono Vinyl Sulfone:This single-vinyl functional compound serves as a controlled-reactivity intermediate in light-shade reactive dye synthesis. Textile chemical manufacturers in Gujarat's Ankleshwar cluster specify mono vinyl sulfone for pale turquoise and yellow formulations where hydrolysis stability requirements exceed standard di vinyl sulfone performance.
- Di Vinyl Sulfone:The bifunctional workhorse dominates navy and black reactive dye chemistry through dual anchor points to cellulose fibers. Demand concentrates at integrated dye manufacturers in India's Vapi corridor and China's Yangtze River Delta, where REACH-compliant azo dye substitution has amplified procurement volumes.
- Divinyl Sulfone Derivatives:Modified structures with substituted vinyl groups command specialty pricing in high-fastness applications.
- Vinyl Sulfone Resin:Polymeric variants serve membrane crosslinking in German and US municipal water treatment systems.
Di vinyl sulfone anchors the volume base while vinyl sulfone resin gains share at the steepest rate.
Application:
Cost tier stratification separates commodity dye intermediate consumption from premium water treatment and specialty adhesive applications, with margin compression most severe in standardized textile printing formulations.
- Dye Intermediates:Coupling chemistry for reactive dyes on cotton and viscose fibers constitutes the dominant value pool. Procurement from Bangladeshi and Pakistani dye houses is consolidating toward integrated suppliers with ZDHC MRSL conformance documentation.
- Textile Printing:Paste formulations for rotary and flat-screen printing require controlled viscosity vinyl sulfone grades. Italian and Turkish specialty printers are narrowing supplier panels to partners with membrane-verified batch consistency.
- Water Treatment:Membrane crosslinking applications in US and German municipal utilities utilize resin-grade materials with thermal stability specifications exceeding textile grades.
- Chemical Crosslinking Agents:Adhesive formulators in automotive assembly pilot alternatives but retain vinyl sulfone chemistry where curing temperature tolerance is non-negotiable.
Dye intermediates command the dominant revenue share while water treatment applications expand most quickly.
End User Industry:
Customer type concentration drives specification divergence, with tier-one apparel brands imposing chemical management protocols that exclude mid-scale leather and paper processors from direct supplier relationships.
- Textile Manufacturers:Fabric dyeing operations across Vietnam's Ho Chi Minh City corridor and South India's Tiruppur cluster constitute the primary demand anchor. ZDHC conformance requirements have centralized purchasing decisions at brand headquarters level.
- Leather Manufacturers:Tanning and finishing operations in Italy's Arzignano district utilize vinyl sulfone derivatives for wet-white leather crosslinking.
- Paper Processing Companies:Wet-strength resin applications in specialty packaging grades represent a stable but slower-expanding consumption segment.
- Adhesive Producers:Automotive and construction formulators specify thermal-cure grades where epoxy silane alternatives face performance gaps.
Textile manufacturers anchor the volume base while adhesive producers generate the highest per-kilogram margins.
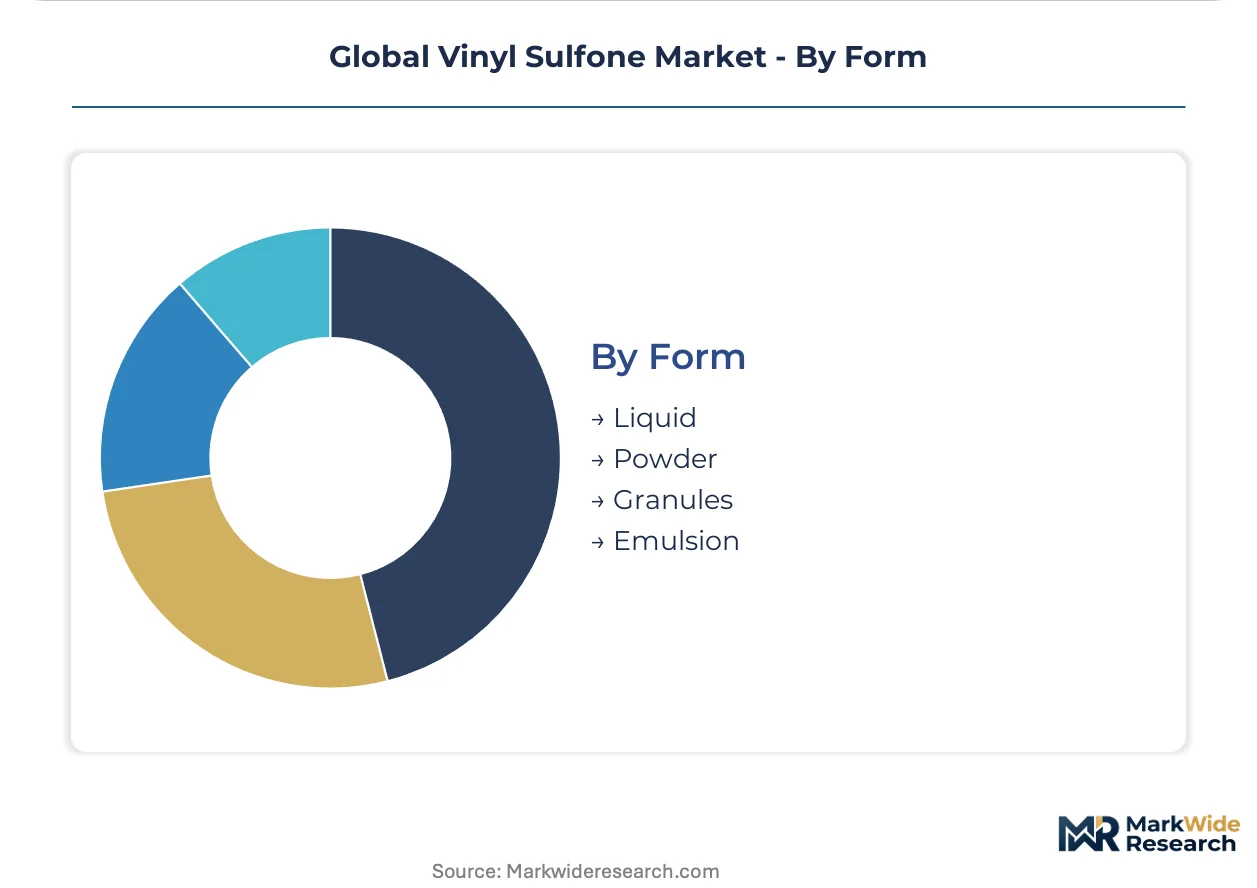
Form:
Supply concentration in powder processing capabilities creates geographic moats, with liquid and emulsion formulations more exposed to regional blending competition.
- Powder:Spray-dried solid forms sustain irreplaceable positions in water treatment chemical blending and long-haul logistics to inland dye houses. India's Central Pollution Control Board zero liquid discharge mandates favor powder handling at compliant bulk chemical clusters.
- Liquid:Aqueous solutions serve just-in-time textile printing operations with limited on-site dilution capacity.
- Granules:Free-flowing solid forms reduce dust exposure in automated handling systems at large-scale dye manufacturers.
- Emulsion:Dispersed-phase products address specialized leather finishing and adhesive formulation requirements.
Powder form sustains the volume foundation while emulsion formats climb the fastest in specialty adhesive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in vinyl sulfone chemistry tilt toward Asian manufacturing centers with captive sulfonation assets, while European and North American markets rely increasingly on imported intermediates for REACH-compliant dye reformulation.
China
Yangtze River Delta petrochemical processors consume di vinyl sulfone at scale for navy and black reactive dye export production. MEE emission controls at designated chemical parks are forcing capacity consolidation toward integrated producers with zero liquid discharge compliance. Zhejiang and Jiangsu province facilities are expanding membrane-based sulfonation systems to serve Italian and Turkish specialty dye house specifications.
India
Gujarat's Ankleshwar-Vapi corridor hosts over half of domestic merchant vinyl sulfone capacity serving Bangladeshi and Pakistani textile finishers. Central Pollution Control Board zero liquid discharge mandates at bulk chemical clusters are accelerating exits among non-compliant batch operators. Bodal Chemicals and Kiri Industries leverage backward integration into sulfone intermediates to capture margin pools across the reactive dye value chain.
Germany
Benelux and domestic textile finishers source vinyl sulfone derivatives for ECHA-compliant reactive dye portfolios amid tightened aromatic amine migration limits. REACH registration timelines of 18-24 months compress product launch windows against Asian competitors. Specialty chemical distributors in the Rhine-Ruhr region are consolidating supplier panels toward partners with documented sulfonation traceability systems.
United States
Municipal utilities in Texas and California are scaling vinyl sulfone resin procurement for membrane crosslinking in advanced filtration infrastructure. EPA discharge standards for textile effluents elevate compliance costs for downstream dye house operations. The Gulf Coast petrochemical corridor provides ethylene feedstock access for domestic sulfonation capacity serving water treatment chemical blenders.
Vietnam
Ho Chi Minh City corridor fabric dyeing operations are generating virgin demand for reactive dye intermediates as capacity relocates from China. Local processors lack established sulfone supplier relationships, creating procurement fragmentation. European and Indian intermediate exporters are establishing technical service presences to support customer requalification programs for ZDHC MRSL conformance.
Global Vinyl Sulfone Market Competitive Landscape
Concentration sits with integrated dye manufacturers possessing captive sulfonation assets, while commodity traders face margin compression from membrane-based continuous processing technology. The vendor base stratifies across three tiers: multinational chemical conglomerates with diversified intermediate portfolios, regional integrated specialists with backward control over sulfone production, and merchant traders dependent on legacy batch operations. Dominant competitive moves include capacity expansion at Gujarat chemical clusters and strategic partnerships between Indian sulfone producers and European specialty dye houses seeking REACH-compliant supply security.
Among India-based integrated manufacturers, Bodal Chemicals Ltd., Kiri Industries Limited, and Atul Ltd. occupy positions representing distinct strategic archetypes. Bodal Chemicals exemplifies backward integration into vinyl sulfone intermediates to secure margin capture across textile dye value chains. Kiri Industries anchors the scale-driven tier through dedicated manufacturing assets in Gujarat's chemical corridor. Atul Ltd. sits within the specialty derivative segment, serving export markets with technology leadership in modified vinyl sulfone structures. Sigma-Aldrich (Merck KGaA) represents the multinational laboratory and specialty chemical distribution archetype with global sourcing networks for high-purity grades.
| Leading Market Players |
|---|
| Bodal Chemicals Ltd. |
| Kiri Industries Limited |
| Shree Pushkar Chemicals and Fertilisers Ltd. |
| Bhageria Industries Limited |
| Atul Ltd. |
| Sigma-Aldrich (Merck KGaA) |
| AksharChemIndia |
| Ambuja Intermediates Pvt. Ltd. |
| Mayur Dye-chem Intermediates LLP |
| Others |
Supply & Pricing Matrix
ZDHC MRSL conformance documentation gates supplier qualification and price differentiation simultaneously, compressing margin pools for non-certified batch operators while rewarding integrated manufacturers with documented sulfonation traceability. Buyers in Bangladesh and Pakistan now face bifurcated procurement panels where certification status overrides volume discounts.
Pricing Analysis
The customization-premium spread separates commodity di vinyl sulfone from specialty vinyl sulfone resin grades, with membrane-verified batch consistency commanding substantial markups from Italian and Turkish dye houses. Pricing stratifies across REACH-registered, ZDHC-conforming, and standard merchant tiers, with ethylene feedstock volatility transmitting cost compression into commodity grades. Brand headquarters procurement teams exhibit lowest price sensitivity, while mid-scale Ho Chi Minh City dye houses negotiate aggressively on standard intermediates.
Supply Chain Analysis
Container availability on the Nhava Sheva-Chittagong trade lane shapes inbound logistics costs for Indian sulfone exporters serving Bangladeshi textile finishers. Manufacturing concentrates in India, China, and Germany, with ethylene sulfonation pathways drawing from naphtha-cracking economics and regional olefin balances. Single-source vulnerability concentrates in Gujarat's Ankleshwar-Vapi corridor, where over half of India's merchant capacity sits within a 200-kilometer radius. Distribution runs through specialty chemical distributors consolidating supplier panels toward integrated producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epoxy silane substitution in automotive adhesive applications threatens vinyl sulfone resin premiums, forcing incumbents to defend formulation lock-in through technical service investments and specification engineering.
For Market Incumbents: Secure captive sulfonation capacity in Gujarat's compliant chemical clusters to defend margin pools against membrane-based continuous processing entrants. Deepen technical service presences in Vietnam's Ho Chi Minh City corridor to support customer requalification programs before European exporters establish beachheads. For New Entrants and Emerging Players: Differentiate on bio-based vinyl sulfone derivative development targeting EU Green Deal chemistry funding through Horizon Europe innovation windows. Penetrate Vietnam's fabric dyeing sector via just-in-time procurement portals that reduce working capital burdens for mid-scale processors lacking established supplier relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across membrane-based sulfonation systems, favoring acquisition targets with veteran chemical engineering teams and documented batch consistency protocols. Watch for REACH registration timeline compression as the inflection signal indicating European specialty dye house supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfone Intermediates | Bodal Chemicals and Kiri Industries capture margin pools across reactive dye value chains through captive production. |
| Membrane-Based Continuous Processing Adoption | Integrated manufacturers displace legacy batch operators with capital-intensive sulfonation assets in Gujarat and Zhejiang. |
| REACH-Compliant Derivative Development | Specialty producers serve German and Benelux dye houses facing ECHA aromatic amine migration limit tightening. |
| Technical Service Presence in Vietnam | Indian and European exporters support ZDHC MRSL conformance for Ho Chi Minh City processors relocating from China. |
| Long-Term Supply Agreements with Tier-One Apparel Brands | Centralized sustainability compliance teams at headquarters level consolidate procurement toward documented sulfonation traceability. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed dye manufacturers, and European Chemicals Agency registration dossiers. Plant managers at Gujarat sulfonation facilities, procurement leads at Bangladeshi textile finishers, and technical directors at Italian specialty dye houses provided operational validation. Bottom-up volume estimates from individual production facilities triangulate against top-down demand assessments from end-use consumption patterns.
Segmentation dimensions modeled span product type, application, end-user industry, and form across the projection horizon. CAGRs derive from ethylene feedstock cost trajectories, REACH regulatory compliance cost absorption rates, and textile manufacturing capacity relocation patterns. Forecast inputs incorporate ZDHC MRSL adoption curves and membrane crosslinking demand from German and US municipal utilities.
Material uncertainties — ethylene price volatility, REACH restriction entry updates, and MEE enforcement intensity at Chinese chemical parks — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory divergence persistence and sulfonation process engineering talent availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
Glutathione Market
Specialty Chemicals
Dehazer Market
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Polyphosphate Market
Specialty Chemicals
Fixing Agent Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Polyglycerol Sebacate (PGS) Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Lignin Products Market
Specialty Chemicals
Global Aerosol Market
Specialty Chemicals
Global Blowing Agent Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Polyglycolic Acid (PGA) Market
Specialty Chemicals
Europe Optical Brighteners Market