
 Ethylene-Vinyl Alcohol Copolymer (EVOH) Market | 2026-2036
Ethylene-Vinyl Alcohol Copolymer (EVOH) Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene-Vinyl Alcohol Copolymer (EVOH) Market Analysis
Japanese resin producers is restructuring global EVOH supply chains through selective capacity rationalization and technology licensing. Kuraray Co., Ltd. leverages its proprietary melt-phase polymerization platform to sustain premium-grade output for pharmaceutical barrier films. Kureha Corporation anchors North American oxygen-barrier packaging through its integrated resin-to-film operations in the United States. Mitsubishi Chemical Corporation competes on multi-layer coextrusion know-how, extending its technical service reach across European automotive fuel-system customers.
Ethylene-vinyl alcohol copolymer is a semi-crystalline thermoplastic synthesized through copolymerization of ethylene and vinyl alcohol monomers, with ethylene content typically ranging from 27 to 48 mole percent to balance processability against gas-barrier performance. Its dense hydrogen-bonded molecular structure yields oxygen transmission rates below 0.5 cc·mm/m²·day·atm, making it indispensable for shelf-life extension in sensitive packaged goods. Extrusion dominates processing-method value capture due to its centrality in multi-layer film and sheet architectures, while blown film commands growth momentum from downgauging trends in retail food packaging. Barrier films represent the deepest margin pool within applications, though pharmaceutical-grade bottles are gaining share as serialization and track-and-trace regulations multiply.
The U.S. FDA maintains exacting extractables-and-leachables standards for EVOH contacting food and drug products, while the EU REACH framework governs monomer residual thresholds and substance-of-very-high-concern declarations across imported resin lots. Japan's METI enforces JIS standards on plastic food-contact materials that effectively filter non-compliant Asian suppliers from premium-tier procurement lists. Stakeholders must monitor evolving extended producer responsibility mandates in the EU and California, as mechanical recycling of EVOH-containing multi-layer structures remains technically immature and economically unproven at commercial scale.
Market Dynamics
Multi-layer coextrusion technology is compressing oxygen transmission rates below legacy thresholds, forcing resin suppliers to synchronize R&D roadmaps with film converter specifications or surrender premium-tier positioning.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates are intensifying demand for passive barrier materials that extend shelf life without mechanical cooling, pulling EVOH into modified-atmosphere packaging for fresh proteins across Central European retail chains.
- Track-and-trace serialization:Pharmaceutical packaging lines are integrating oxygen-scavenging barrier layers to protect biologics through distribution networks subject to temperature excursion risks and regulatory audit trails.
- Downgauging in flexible retail formats:Blown film converters are specifying ultra-thin EVOH core layers to reduce material intensity while maintaining barrier performance, absorbing resin volumes previously allocated to thicker cast film structures.
Market Restraints
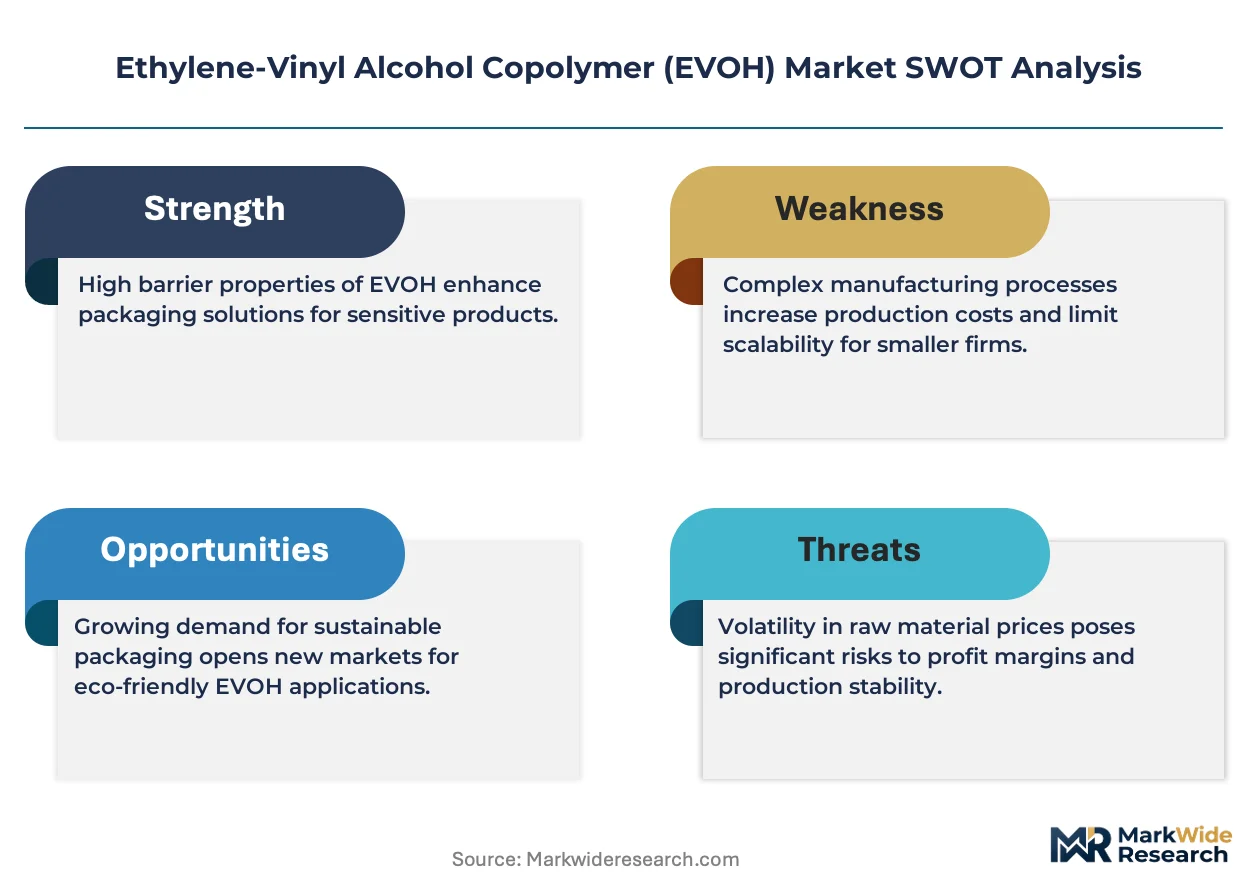
- Ethylene feedstock volatility:Naphtha-cracking economics tie EVOH resin pricing to regional olefin spreads, compressing converter margins during upstream petrochemical tightness.
- Mechanical recycling immaturity:EVOH's presence in multi-layer laminates blocks conventional reprocessing streams, exposing brand owners to extended producer responsibility penalties under EU packaging waste directives.
- Polyamide substitution in automotive:Fuel-system manufacturers are qualifying aliphatic polyamides for certain barrier applications, displacing EVOH in select non-critical vapor-management components.
Strategic Opportunities
- India cold-chain buildout:FSSAI-mandated food safety modernization is creating first-time specification of high-barrier packaging for temperature-sensitive dairy and prepared meals in metropolitan distribution networks.
- Biodegradable barrier hybrids:Convergence of EVOH with polylactic acid outer layers is opening compostable packaging segments previously closed to petroleum-derived barrier resins.
- Pharmaceutical serialization mandates:FDA DSCSA compliance deadlines are accelerating qualification of barrier bottles with integrated authentication features for generic drug distribution.
Industry Challenges
- Coextrusion die engineering scarcity:Fewer than a dozen equipment builders globally maintain expertise in nine-layer and above configurations, creating bottlenecked capacity expansion timelines for converters.
- Extractables validation timelines:USP Class VI and FDA extractables-and-leachables protocols for pharmaceutical-grade EVOH extend qualification cycles to 18-24 months, freezing supplier-switching decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene-Vinyl Alcohol Copolymer (EVOH) Market |
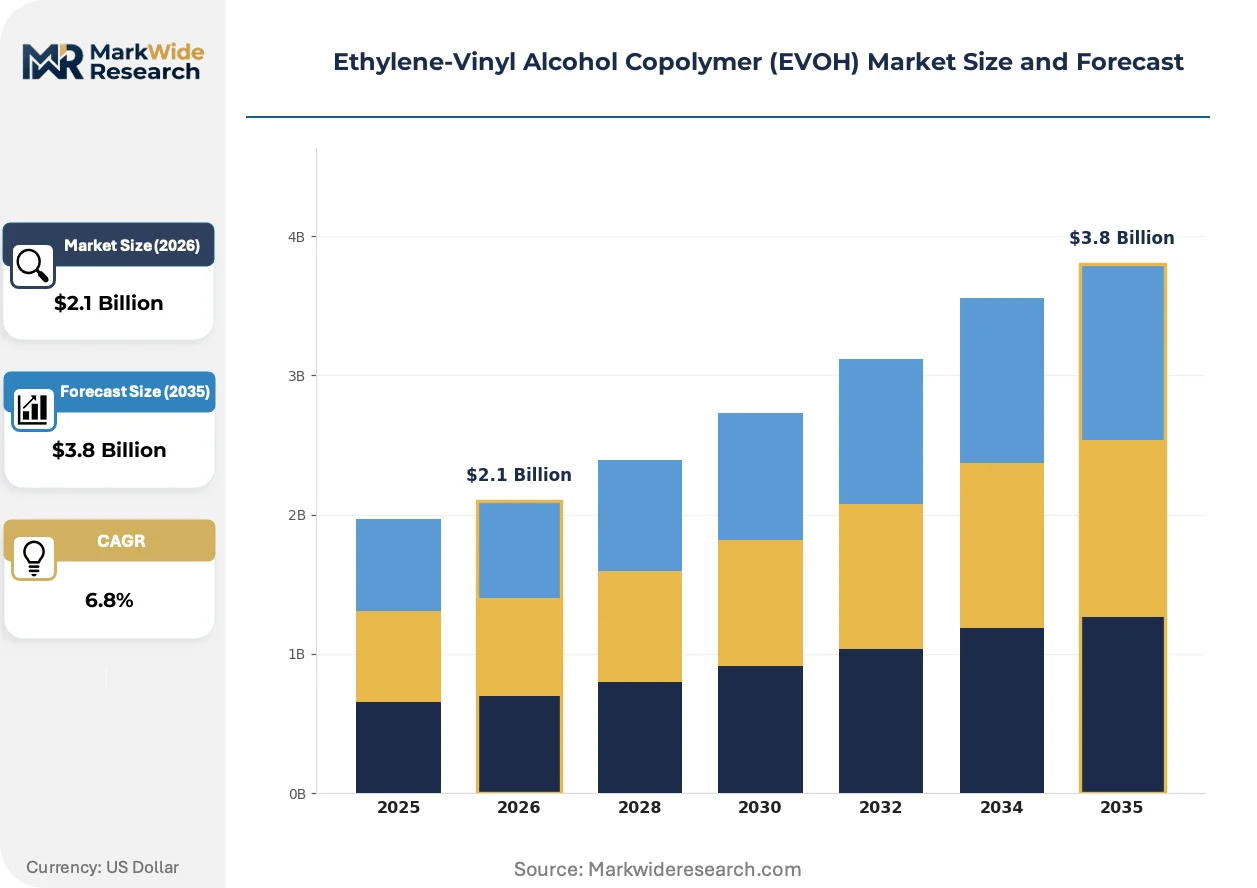
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Extrusion, Blown Film, Coating End User: Food Packaging, Pharmaceutical, Automotive, Consumer Goods Application: Barrier Films, Bottles, Adhesives, Fibers Form: Granules, Pellets, Sheets, Films |
| Companies Covered | SK Functional Polymer, Kureha Corporation, Kuraray Co., Ltd., Schur Flexibles Holding GesmbH, Arkema, Mitsubishi Chemical Corporation, Elephchem, Coveris, Chang Chun Petrochemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene-Vinyl Alcohol Copolymer (EVOH) Market Emerging Trajectories
Active barrier technologies and circular-economy compliance requirements are restructuring how resin specifications propagate through converter and brand-owner value chains.
Reactive oxygen-scavenging EVOH grades are absorbing transition-metal catalysts into the polymer matrix to neutralize ingress rather than merely resist it. Pharmaceutical blister pack manufacturers are qualifying these materials for oxygen-sensitive oncology APIs. The technology is absorbing technical service resources from legacy passive-barrier resin portfolios as converters revalidate stability data.
REACH SVHC disclosure thresholds are tightening to 0.1% weight-by-weight for monomer residuals in imported EVOH lots. European compounders are demanding certified analytical packages from Asian resin sources to avoid customs detention. Automotive fuel-system suppliers are most exposed, as tank coextrusion lines cannot absorb formulation changes without full permeation requalification.
Brand-owner specification consolidation is compressing approved supplier lists to resin producers with integrated analytical laboratories and regional technical service presence. Retail grocery chains in Germany are mandating single-source accountability for barrier performance failures. Converter procurement teams are responding by qualifying dual-source resin strategies that sacrifice volume discounts for supply security.
Ethylene-Vinyl Alcohol Copolymer (EVOH) Market Segmentation
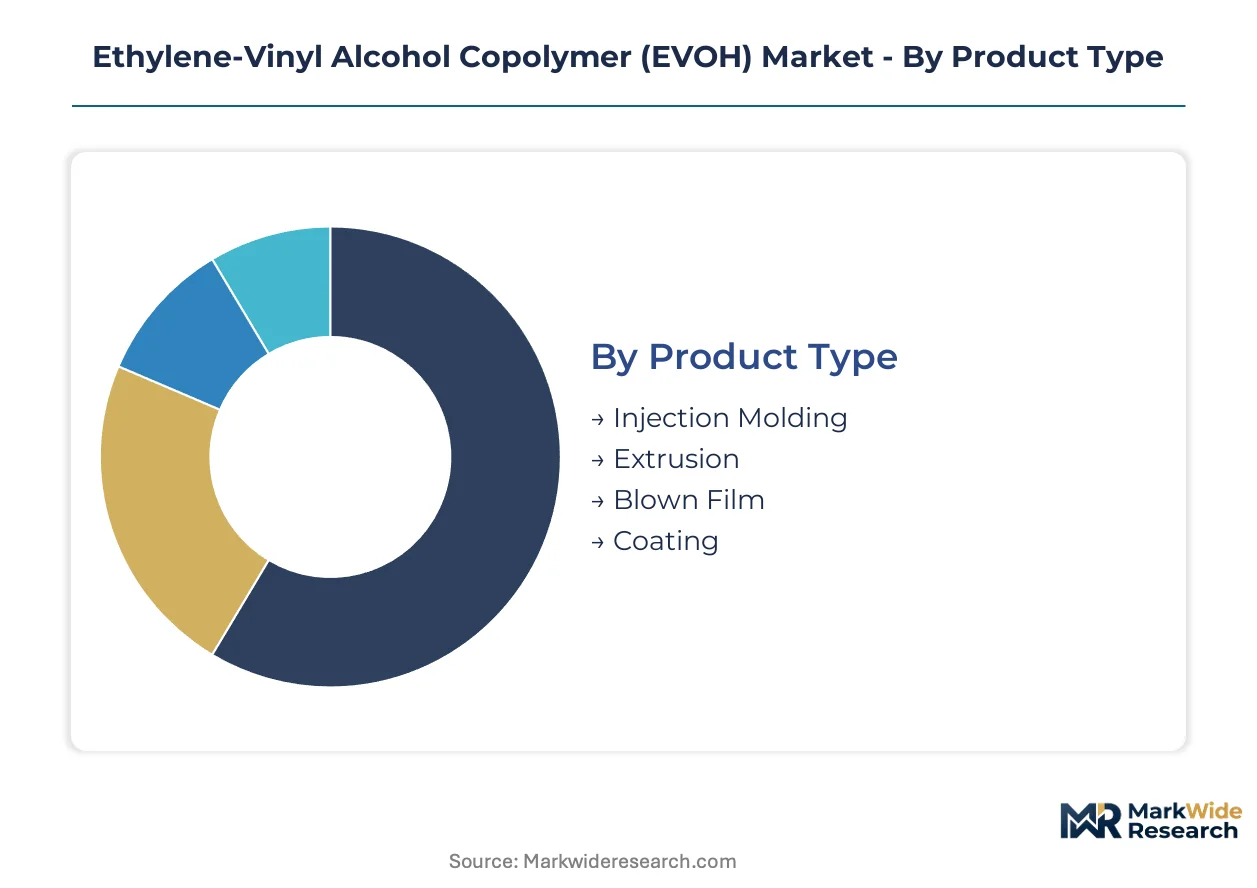
EVOH resin specifications fragment across processing methods and barrier-performance tiers, with converter capital commitments determining which segments capture premium pricing. Procurement teams align supplier qualification with end-use regulatory exposure rather than commodity resin availability.
Product Type:
Capital intensity varies sharply across processing technologies, with multi-layer coextrusion lines demanding the heaviest upfront equipment investment while coating operations require minimal dedicated infrastructure.
- Extrusion:Multi-layer sheet and film coextrusion systems dominate value capture in EVOH processing, requiring precision die engineering and layer-thickness control to achieve oxygen transmission rates below 0.5 cc·mm/m²·day·atm. German packaging converters serving Central European retail chains absorb the majority of extrusion-grade resin volumes as brands pursue extended shelf-life solutions under EU Green Deal specifications.
- Blown Film:Downgauging trends in flexible retail formats are compressing EVOH core layers to sub-micron thicknesses while maintaining barrier integrity, pulling resin demand from cast film structures into blown film configurations. This segment is expanding most quickly as converters reduce material intensity per packaging unit.
- Injection Molding:Pharmaceutical-grade barrier bottles and automotive fuel-system components require tight dimensional tolerance and extractables validation cycles extending 18-24 months under USP Class VI protocols.
- Coating:Solvent and aqueous coating applications for paperboard and flexible substrates involve lower capital barriers but constrained resin specification flexibility.
Extrusion absorbs the bulk of installed capacity; blown film is expanding most quickly.
End User:
Regulatory exposure and shelf-life requirements create tiered demand patterns, with pharmaceutical and food packaging commanding premium resin grades while automotive applications face substitution pressure.
- Food Packaging:Modified-atmosphere packaging for fresh proteins across Central European retail chains is intensifying demand for passive barrier materials as EU F-Gas Regulation phases down mechanical cooling dependence. Japanese resin producers supply premium grades through selective capacity rationalization and technology licensing arrangements.
- Pharmaceutical:Oxygen-scavenging barrier layers protect biologics through distribution networks subject to temperature excursion risks and FDA DSCSA track-and-trace serialization mandates, with oncology API blister packs absorbing reactive EVOH grades containing transition-metal catalysts.
- Automotive:Fuel-system manufacturers are qualifying aliphatic polyamides for certain vapor-management components, displacing EVOH in select non-critical applications.
- Consumer Goods:Cosmetic and household product packaging specifies standard-grade barrier performance with less stringent extractables documentation.
Food packaging commands the deepest volume base; pharmaceutical is climbing the fastest as serialization mandates multiply.
Application:
Margin structure inverts across application types, with barrier films capturing the steepest premiums and fiber applications remaining largely developmental.
- Barrier Films:Multi-layer coextrusion architectures for sensitive packaged goods represent the deepest margin pool within EVOH applications, with oxygen transmission rate specifications tightening below legacy thresholds as coextrusion die engineering advances.
- Bottles:Pharmaceutical-grade barrier bottles with integrated authentication features are gaining share as FDA DSCSA compliance deadlines accelerate qualification timelines for generic drug distribution.
- Adhesives:Tie-layer formulations bonding EVOH to polyolefin substrates in multi-layer structures require specialized compatibilizer chemistry and represent a captive demand segment.
- Fibers:Technical textile and filtration applications remain niche, with limited commercial scale and fragmented end-use specification.
Barrier films absorb the bulk of installed capacity; bottles are expanding most quickly.
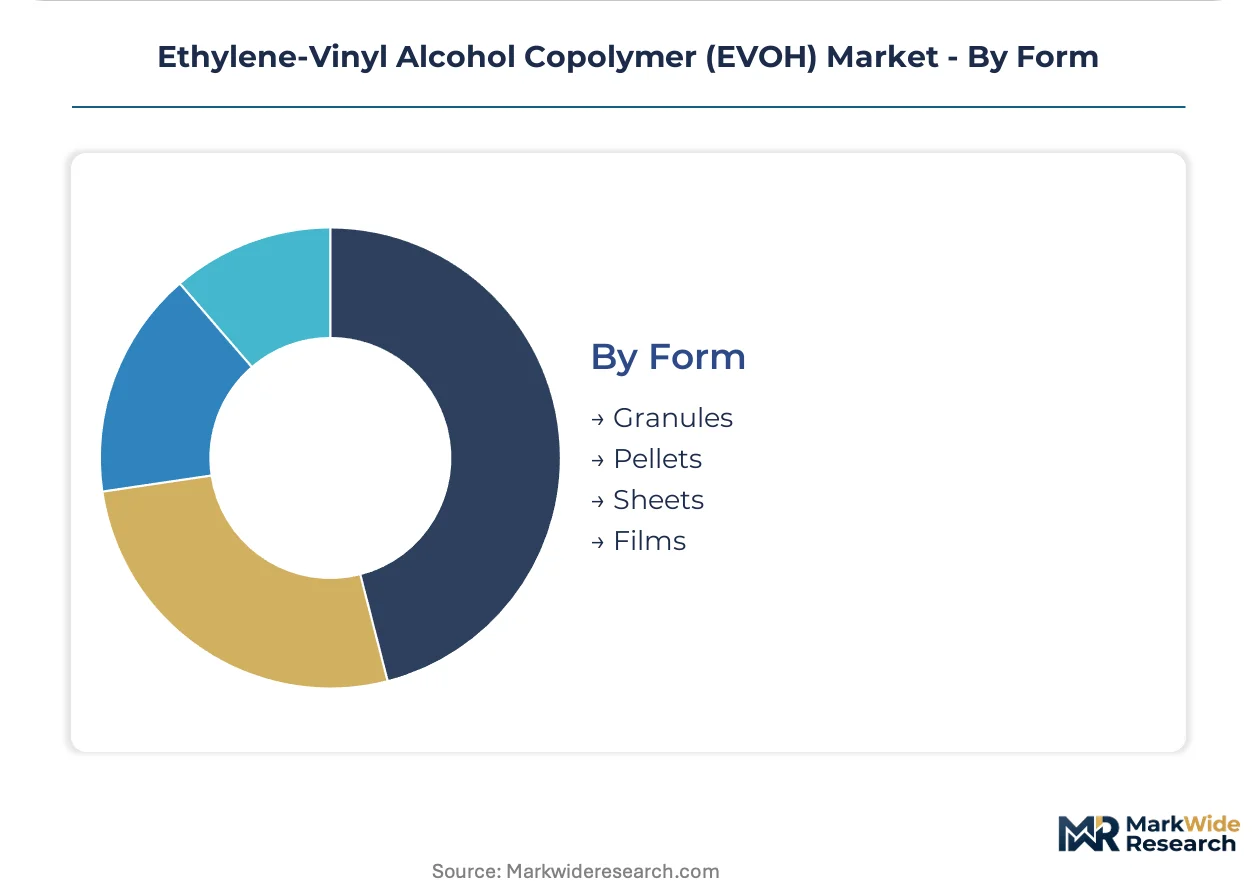
Form:
Supply chain configuration determines form factor availability, with pellet and granule formats dominating resin distribution while sheet and film forms reflect captive converter integration.
- Pellets:Standardized pellet form enables bulk handling and automated feeding across extrusion and injection molding operations, with REACH SVHC disclosure thresholds at 0.1% weight-by-weight governing monomer residual certification for European compounders.
- Granules:Larger particle size suits specific compounding and masterbatch applications where melt homogeneity requirements differ from pellet-fed systems.
- Sheets:Pre-extruded multi-layer sheet stock serves thermoforming operations for rigid food trays and pharmaceutical blister packs, with integrated EVOH barrier layers locked into converter supply agreements.
- Films:Cast and oriented film products reflect downstream integration by major resin producers into film manufacturing rather than merchant resin sales.
Pellets absorb the bulk of installed capacity; sheets are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naphtha-cracking economics in East Asia and the Middle East anchor ethylene feedstock availability for EVOH resin production. Regional demand patterns diverge sharply between mature packaging markets with strict circular-economy mandates and emerging cold-chain economies specifying barrier materials for the first time.
Germany
Modified-atmosphere packaging for fresh proteins absorbs premium EVOH grades as retailers phase out mechanical cooling under EU F-Gas Regulation phase-down timelines. The country's national packaging regulator enforces extended producer responsibility mandates that penalize multi-layer structures lacking recyclability pathways. Packaging converters in the Rhine-Ruhr cluster serve Central European retail chains with oxygen transmission specifications below 0.5 cc·mm/m²·day·atm.
United States
Pharmaceutical serialization mandates under FDA DSCSA deadlines accelerate qualification of barrier bottles with integrated authentication features for generic drug distribution. The national pharmaceutical regulator maintains exacting extractables-and-leachables standards for EVOH contacting drug products. Fuel-system manufacturers in the Detroit automotive cluster qualify aliphatic polyamides for select vapor-management components, displacing EVOH in non-critical applications.
Japan
Resin producers leverage proprietary melt-phase polymerization platforms to sustain premium-grade output for pharmaceutical barrier films. METI enforces JIS standards on plastic food-contact materials that filter non-compliant Asian suppliers from premium-tier procurement lists. Technical service operations in the Osaka-Kobe industrial zone extend support reach across European automotive fuel-system customers.
India
FSSAI-mandated food safety modernization creates first-time specification of high-barrier packaging for temperature-sensitive dairy and prepared meals in metropolitan distribution networks. The national food safety authority mandates cold-chain compliance for perishable goods that pulls EVOH into modified-atmosphere formats. Packaging converters in the Mumbai-Pune corridor serve quick-service restaurant chains expanding prepared meal delivery.
China
Domestic resin producers scale copolymerization capacity to reduce import dependence for extrusion-grade EVOH serving flexible retail packaging. The Ministry of Ecology and Environment enforces dual carbon goals that tighten specifications for barrier materials in perishable goods distribution. Film manufacturing clusters in the Yangtze River Delta integrate captive resin production with multi-layer coextrusion lines for export-oriented food packaging.
Ethylene-Vinyl Alcohol Copolymer (EVOH) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable barrier hybrids and regional technical service presence. The vendor base concentrates around integrated resin-to-film operators and specialty compounders with analytical certification capabilities. Three archetypes dominate: Japanese multinationals with proprietary polymerization platforms, European flexible packaging converters with captive resin sourcing, and Asian chemical conglomerants scaling commodity-grade capacity. Competitive moves center on selective capacity rationalization in mature markets and technology licensing arrangements to secure premium-tier positioning.
Within the integrated resin-to-film tier, Kuraray Co., Ltd. and Kureha Corporation exemplify Japanese producers leveraging proprietary platforms for pharmaceutical and North American oxygen-barrier applications respectively. Mitsubishi Chemical Corporation anchors the multi-layer coextrusion specialist position. Chang Chun Petrochemical Co., Ltd. represents the scale-driven Asian chemical conglomerant archetype expanding commodity-grade capacity. SK Functional Polymer occupies a position between premium and standard tiers with regional technical service reach. These named entities illustrate how competitive positioning stratifies across technology licensing, captive integration, and volume-scale vectors rather than converging on a single dominant model.
| Leading Market Players |
|---|
| SK Functional Polymer |
| Kureha Corporation |
| Kuraray Co., Ltd. |
| Schur Flexibles Holding GesmbH |
| Arkema |
| Mitsubishi Chemical Corporation |
| Elephchem |
| Coveris |
| Chang Chun Petrochemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Family-owned Japanese resin specialists anchor premium-tier supply, translating proprietary polymerization platforms into pricing discipline that resists commoditization pressure from Asian volume players. Their selective capacity rationalization tightens availability for pharmaceutical-grade certifications, forcing converters to absorb technical service premiums or surrender barrier-performance guarantees.
Pricing Analysis
Warranty-backed technical service bundles separate pharmaceutical-grade EVOH from unbundled commodity resin transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with USP Class VI validation commanding steep premiums over food-contact grades. Cost compression in standard-tier extrusion resin is intensifying because Chinese producers are scaling commodity copolymerization capacity. Small-scale pharmaceutical converters exhibit the sharpest price sensitivity, while automotive fuel-system OEMs prioritize permeation requalification security over unit cost.
Supply Chain Analysis
Ocean freight rate volatility from East Asian resin hubs to European compounders compresses converter margins during petrochemical shipping tightness. Manufacturing gravity centers on Japan, South Korea, and China, with ethylene feedstock drawing from regional naphtha-cracking economics. Vinyl acetate monomer and ethylene dependencies expose producers to olefin spread fluctuations. Single-source vulnerability concentrates in nine-layer coextrusion die engineering, where fewer than a dozen equipment builders globally control capacity expansion timelines. Distribution runs through integrated resin-to-film operators and merchant compounders with certified analytical laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from REACH SVHC disclosure tightening and extended producer responsibility penalties will force non-compliant Asian suppliers from premium-tier procurement lists. Surviving players must absorb qualification costs or exit pharmaceutical and Central European food packaging segments.
For Market Incumbents: Deploy proprietary melt-phase polymerization know-how to sustain pharmaceutical barrier film positioning against emerging biodegradable hybrid competitors. Absorb backward integration into captive film manufacturing to secure converter supply agreements. Accelerate regional technical service presence in India to capture FSSAI-mandated cold-chain buildout before commodity entrants qualify. For New Entrants and Emerging Players: Reactive oxygen-scavenging EVOH grades containing transition-metal catalysts offer the most penetrable wedge for oncology API blister pack qualification. Target Indian metropolitan distribution networks for first-time high-barrier packaging specification in temperature-sensitive dairy. Pursue technology licensing arrangements with established Japanese producers rather than greenfield polymerization investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor European flexible packaging converters with captive resin sourcing and integrated analytical laboratories in Germany. Five-to-ten year viability hinges on circular-economy compliance infrastructure and mechanical recycling pathway development. Monitor EU packaging waste directive enforcement intensity as the inflection signal for premium-tier supplier list compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Acetate Monomer Supply | Reduces ethylene feedstock volatility exposure for Japanese resin producers. |
| Pharmaceutical-Grade Certification Investment | Extends USP Class VI qualification timelines to 18-24 months, freezing supplier-switching decisions. |
| Regional Technical Service Expansion | Captures FSSAI-mandated cold-chain specification in Mumbai-Pune corridor for prepared meal delivery. |
| Biodegradable Barrier Hybrid Development | Opens compostable packaging segments through PLA-EVOH convergence for EU Green Deal compliance. |
| Long-Term Supply Agreement with Central European Retail Chains | Locks in oxygen-barrier film volumes under EU F-Gas Regulation phase-down timelines. |
Methodological Framework
Multi-period observation of resin capacity rationalization patterns and regulatory disclosure thresholds anchored the trend analysis, supplemented by interviews with technical R&D directors at Japanese resin producers, procurement leads at German packaging converters, and plant managers at multi-layer coextrusion facilities. Secondary validation drew from customs and trade data tracking EVOH import flows, SEC filings of listed chemical conglomerates, and ECHA REACH SVHC registration databases. Bottom-up resin volume estimates triangulated against top-down pharmaceutical packaging demand projections.
Segment-weighting across processing method, end-use industry, and regional regulatory cluster determined value distribution in the analytical framework. CAGRs derived from ethylene feedstock spread modeling and converter capacity utilization trajectories across the projection horizon. Industry-specific inputs included oxygen transmission rate specification tightening timelines and pharmaceutical serialization mandate compliance deadlines.
Several conditions sit outside the modeled scope, including breakthrough mechanical recycling technologies for multi-layer laminates and abrupt ethylene feedstock price shocks from geopolitical supply disruptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and converter qualification cycle durations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Global Polymeric Adsorbents Market
Polymers & Resins
Construction Polymer Market
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
UV Stabilized Thermoplastic Elastomer for Automotive Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Global Furan Resins Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
Vinyl Acetate Monomer (VAM) Market