
 Non-Hodgkin Lymphoma Treatment Market | 2026-2036
Non-Hodgkin Lymphoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Hodgkin Lymphoma Treatment Market Intelligence
Hospital formulary access channels is reshaping how novel agents reach patients. Roche leverages its diagnostic-therapeutic bundling to control institutional procurement decisions. Bristol Myers Squibb sustains broad hematology center penetration through its cell therapy infrastructure. Janssen Pharmaceuticals anchors community oncology access with differentiated oral agent distribution.
Non-Hodgkin lymphoma treatment encompasses therapeutic interventions targeting malignant proliferation of B-cell, T-cell, and natural killer cell lineages, with regimens selected based on immunophenotyping, fluorescence in situ hybridization for chromosomal translocations, and positron emission tomography staging to determine metabolic tumor burden and treatment response. Immunotherapy commands the deepest margin pools as checkpoint inhibitors and bispecific antibodies displace salvage chemotherapy in relapsed settings. Targeted therapy segments, including Bruton tyrosine kinase and BCL-2 inhibitors, represent the fastest-growing category driven by oral bioavailability and outpatient administration economics.
FDA breakthrough therapy designation and EMA priority medicines frameworks compress regulatory review timelines, directly shaping manufacturer pipeline prioritization and launch sequencing decisions. NMPA conditional approval pathways in China and Japan's PMDA sakigake designation create parallel market access tracks that influence global clinical trial placement. Stakeholders must monitor evolving CMS coverage determination methodologies for cellular therapies, as these precedents will dictate reimbursement architecture for next-generation modalities.
Market Dynamics
FDA breakthrough therapy designations are compressing clinical development timelines for bispecific antibodies and CAR-T constructs, forcing manufacturers to front-load manufacturing capacity before confirmatory data readouts.
Growth Catalysts
- Accelerated Approval Pathways:FDA's breakthrough therapy and EMA's priority medicines frameworks truncate regulatory review periods. Manufacturers redirect pipeline resources toward agents qualifying for these expedited tracks.
- Outpatient Administration Economics:Oral BTK and BCL-2 inhibitors shift treatment delivery from infusion centers to community oncology practices. Payer reimbursement for oral oncolytics under Medicare Part D drives site-of-care migration.
- Companion Diagnostic Integration:Fluorescence in situ hybridization and next-generation sequencing panels enable precision patient selection. Hematology centers bundle molecular profiling with therapeutic decision-making.
Market Restraints
- Cellular Therapy Manufacturing Bottlenecks:Autologous CAR-T production requires dedicated cleanroom facilities and vector supply. Viral vector scarcity constrains batch yields across CD19 and BCMA programs.
- Reimbursement Compression for Salvage Regimens:CMS national coverage determinations for chimeric antigen receptor T-cell therapy impose outcome-based payment conditions. Community oncologists face prior authorization burdens for novel agents.
- Clinical Trial Competition for Relapsed Populations:Multiple sponsors target the same rituximab-refractory patient pools. Recruitment saturation extends enrollment timelines and inflates per-patient costs.
Strategic Opportunities
- Allogeneic Off-the-Shelf Platforms:Allogeneic CAR-T and natural killer cell therapies eliminate patient-specific manufacturing. Academic medical centers in Germany and the United Kingdom pilot donor-derived construct protocols.
- T-Cell Engager Expansion:Bispecific antibodies redirecting T-cells against CD20 and CD19 targets penetrate community settings. Subcutaneous administration formats reduce infusion chair time and nursing overhead.
- Real-World Evidence Submissions:FDA's Project Confirm and EMA's adaptive pathways accept post-marketing registry data. Sponsors leverage electronic health record networks to satisfy confirmatory trial requirements.
Industry Challenges
- Vector Manufacturing Scale-Up:Lentiviral and gamma-retroviral vector production requires specialized transfection expertise. Contract development and manufacturing organizations face capacity allocation conflicts across multiple CAR-T sponsors.
- Toxicity Management Standardization:Cytokine release syndrome and neurotoxicity grading systems vary across academic centers. Community hospitals lack standardized protocols for bispecific antibody adverse event triage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Hodgkin Lymphoma Treatment Market |
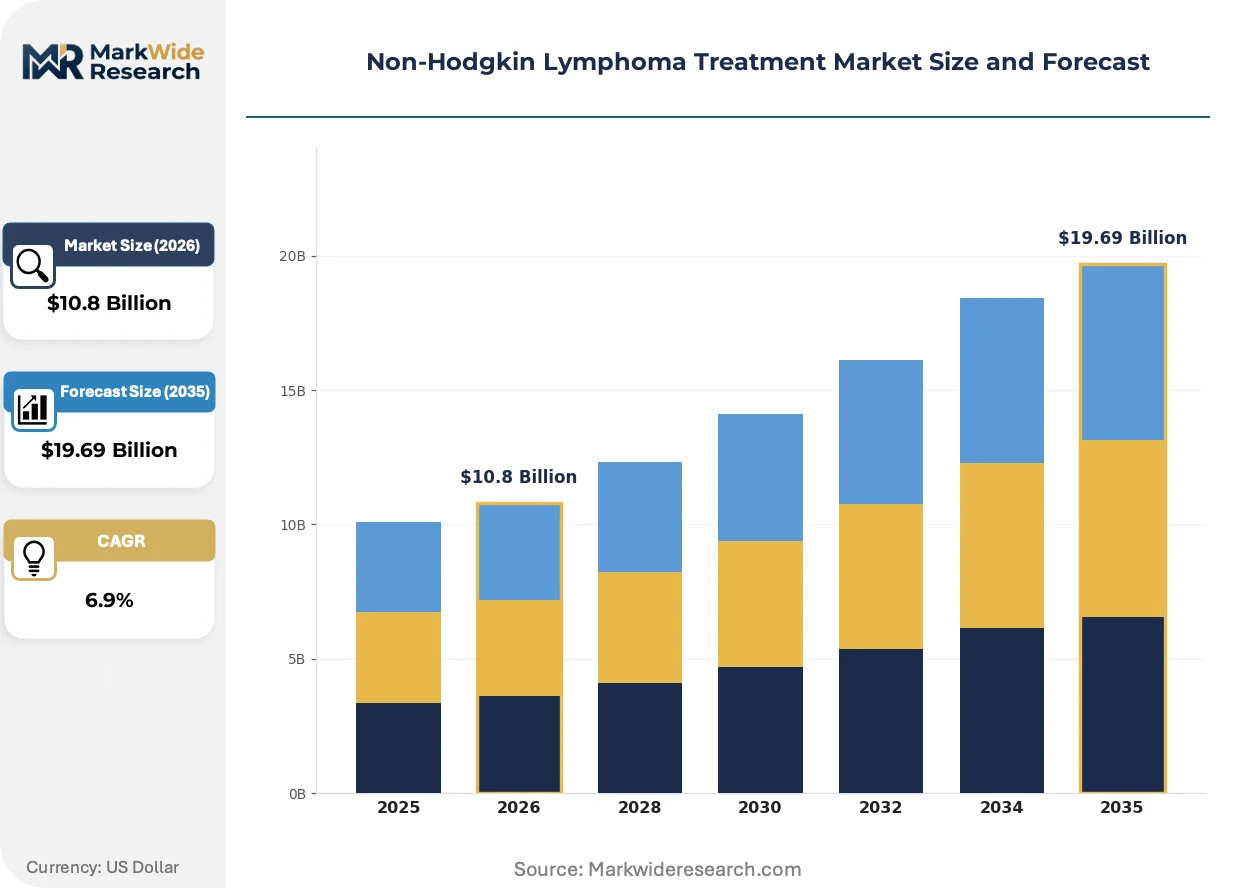
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $19.69 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy, Stem Cell Transplant Application: Indolent Lymphoma, Aggressive Lymphoma, Mantle Cell Lymphoma, Burkitt Lymphoma, T-cell Lymphoma End User: Oncology Clinics, Hematology Centers, Research Institutes, Specialized Hospitals, Ambulatory Surgery Centers Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular, Topical |
| Companies Covered | Roche, Novartis AG, Gilead Sciences, Bristol Myers Squibb, Takeda Pharmaceutical Company Limited, AstraZeneca, Janssen Pharmaceuticals, Bayer AG, Seagen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Hodgkin Lymphoma Treatment Market Strategic Shifts & Innovations
Next-generation modalities are collapsing the boundary between hematology and solid tumor therapeutic development, with platform technologies originally validated in lymphoma now migrating into autoimmune and infectious disease applications.
Bispecific T-cell engagers with extended half-life engineering are rendering obsolete the requirement for continuous intravenous infusion infrastructure. Community oncology practices adopt these agents for relapsed diffuse large B-cell lymphoma, eliminating the need for referral center admission. This shift compresses the addressable market for salvage chemotherapy regimens previously administered in hospital settings.
EMA's adaptive pathway and priority medicines frameworks compress conditional approval timelines for agents demonstrating early progression-free survival signals. Manufacturers front-load manufacturing investments to supply European markets within six months of positive phase II readouts. Hematology centers in France and Germany restructure pharmacy budgets to accommodate these compressed launch sequences.
Site-of-care migration toward oral oncolytics disrupts traditional infusion center revenue models. Community oncology practices in the United States capture margin pools previously retained by hospital outpatient departments through in-house dispensing of BTK inhibitors. Payer pharmacy benefit managers respond with exclusive formulary placement contracts that consolidate distribution through limited specialty pharmacy networks.
Non-Hodgkin Lymphoma Treatment Market Segmentation
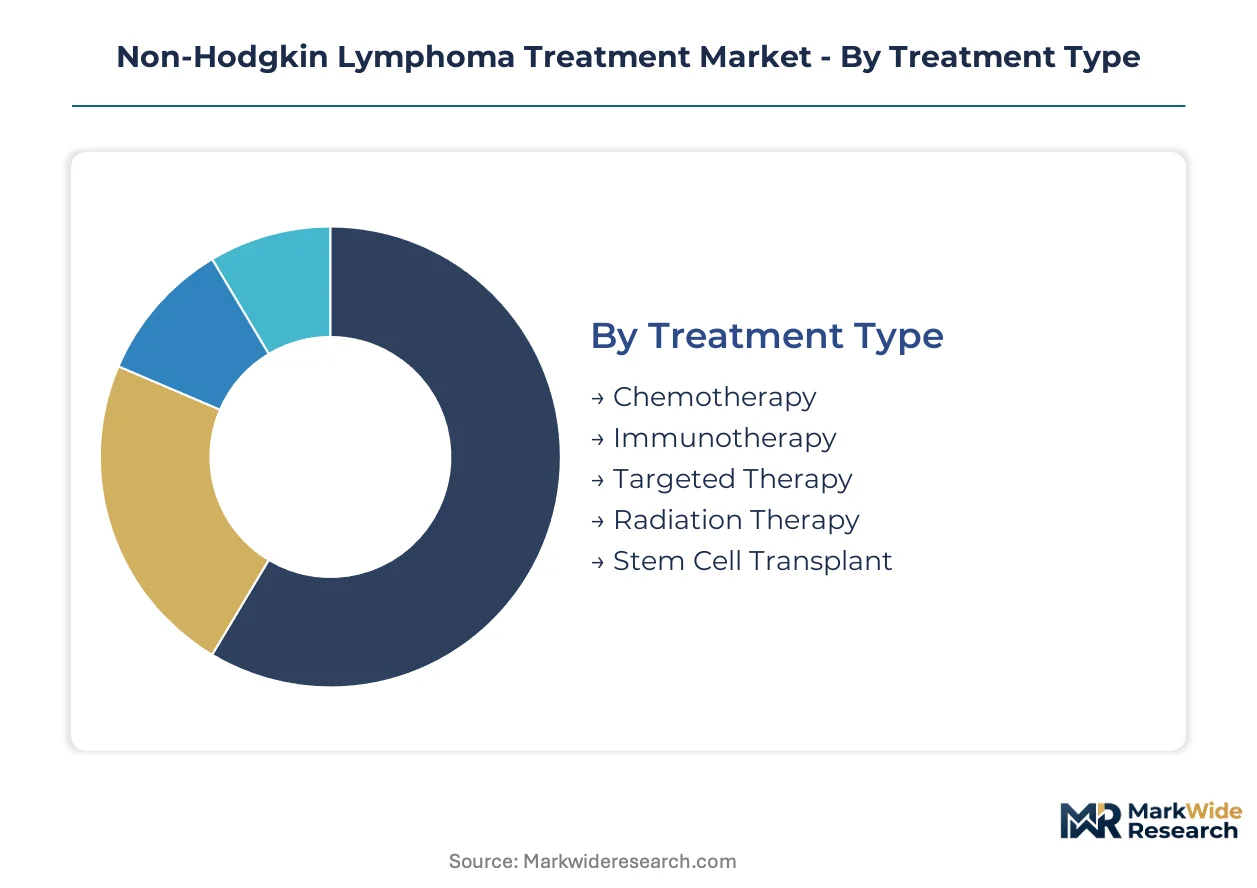
Segmentation in non-Hodgkin lymphoma treatment reveals how therapeutic innovation, site-of-care economics, and patient acuity reshape procurement patterns across institutional buyers. Manufacturers align pipeline investments with modality-specific margin structures and administration infrastructure requirements.
Treatment Type:
Cost tier differentiation separates legacy cytotoxic platforms from premium biologics and cellular therapies, with reimbursement bandwidth determining formulary placement across hospital systems.
- Immunotherapy:Checkpoint inhibitors and bispecific antibodies redirect immune surveillance against malignant clones. Demand concentrates in United States academic medical centers where prior authorization infrastructure supports CAR-T and monoclonal antibody access. FDA breakthrough therapy designations compress development timelines for CD19-directed programs.
- Targeted Therapy:Small-molecule inhibitors of Bruton tyrosine kinase and BCL-2 proteins enable outpatient oral administration. Community oncology practices in Germany and the United Kingdom capture margin pools through in-house dispensing, shifting volume from hospital infusion centers.
- Chemotherapy:Anthracycline and alkylator regimens retain first-line utility in resource-constrained settings.
- Radiation Therapy:Consolidation dosing for localized disease and palliative symptom management.
- Stem Cell Transplant:Autologous and allogeneic protocols for high-risk relapsed populations.
Immunotherapy commands the established base. The steepest expansion runs through targeted therapy.
Application:
Patient acuity and disease biology dictate treatment intensity, with aggressive histologies requiring immediate combination protocols while indolent variants permit watchful waiting or delayed intervention.
- Aggressive Lymphoma:Diffuse large B-cell lymphoma and related subtypes demand rapid chemoimmunotherapy induction. Hematology centers in France and Italy prioritize R-CHOP capacity and CAR-T referral pathways for refractory cases. EMA adaptive pathways accelerate bispecific antibody access.
- Mantle Cell Lymphoma:BTK inhibitor sensitivity and TP53 mutation status stratify treatment selection. Academic consortia in the United States and Germany integrate molecular profiling into frontline decision algorithms.
- Indolent Lymphoma:Follicular and marginal zone subtypes managed with observation or rituximab monotherapy.
- Burkitt Lymphoma:High-intensity short-cycle chemotherapy for pediatric and adult populations.
- T-cell Lymphoma:Peripheral and cutaneous subtypes with limited targeted therapy options.
Aggressive lymphoma absorbs the largest therapeutic investment. Mantle cell lymphoma shows the most rapid protocol evolution.
End User:
Site-of-care migration redistributes patient volume between hospital-based infusion infrastructure and community-accessible administration settings.
- Hematology Centers:Academic medical centers with integrated pathology, flow cytometry, and cellular therapy manufacturing. Germany's university hospitals and United States NCI-designated cancer centers anchor CAR-T and bispecific antibody administration. EMA priority medicines frameworks compress launch-to-treatment intervals.
- Oncology Clinics:Community-based practices capturing oral oncolytic dispensing and subcutaneous injection protocols. Medicare Part D reimbursement structures in the United States incentivize site-of-care migration away from hospital outpatient departments.
- Specialized Hospitals:General oncology units with limited cellular therapy capability.
- Research Institutes:Phase I-II trial sites and correlative science programs.
- Ambulatory Surgery Centers:Diagnostic biopsy and port placement procedures.
Hematology centers retain complex cellular therapy concentration. Oncology clinics gain share fastest through oral agent migration.
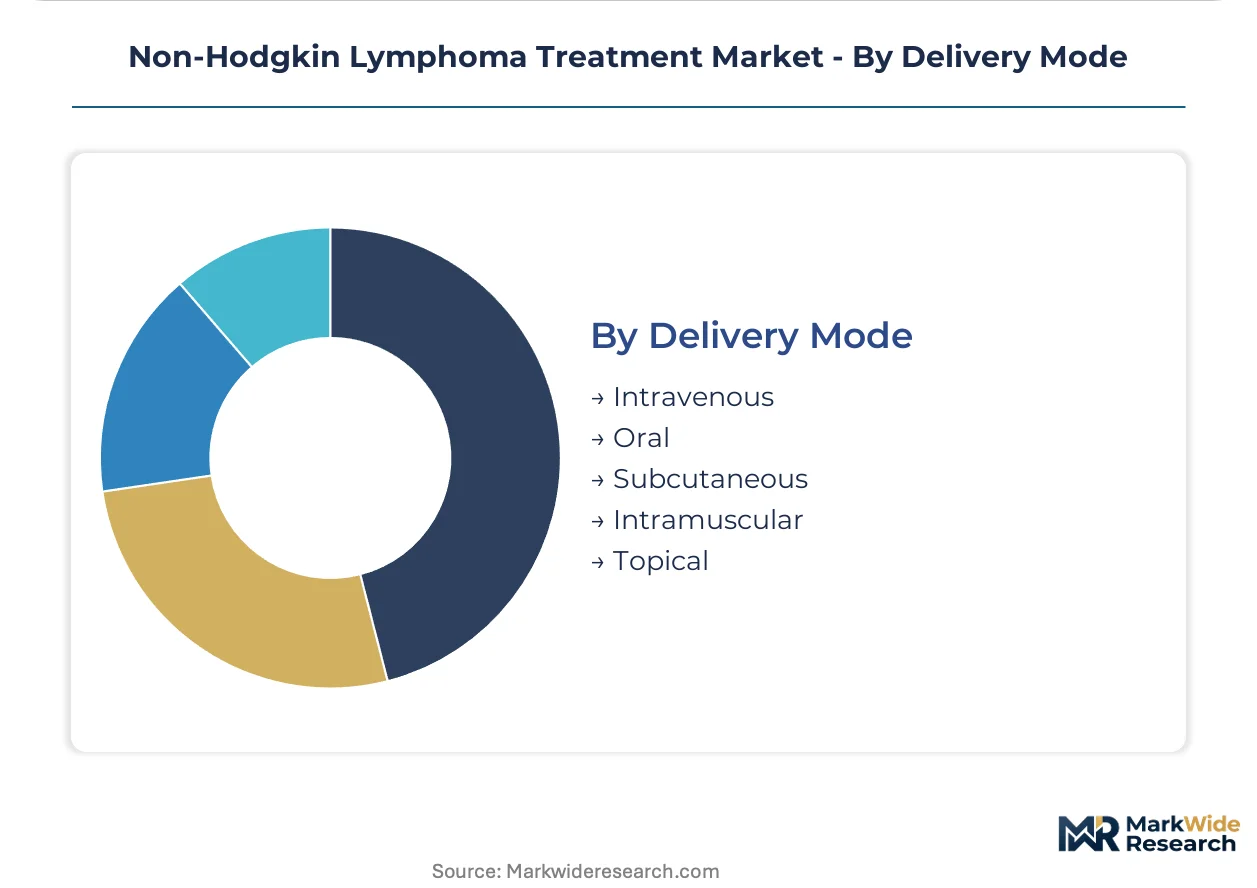
Delivery Mode:
Administration route determines nursing overhead, facility requirements, and patient convenience trade-offs across treatment settings.
- Intravenous:Infusion center infrastructure for monoclonal antibodies, chemotherapy, and cellular products. Hospital outpatient departments in the United States defend revenue through facility fee structures tied to chair time.
- Oral:BTK and BCL-2 inhibitors enable home administration with pharmacy benefit manager oversight. Specialty pharmacy networks consolidate distribution through limited distribution agreements.
- Subcutaneous:Extended half-life bispecific antibodies reduce administration frequency.
- Intramuscular:Limited applications in supportive care and premedication.
- Topical:Cutaneous T-cell lymphoma localized therapy.
Intravenous delivery maintains volume leadership. Subcutaneous formulations are climbing the fastest as engineering advances reduce dosing frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Johns Hopkins Hospital and Mayo Clinic referral networks anchor United States therapeutic access, channeling complex lymphoma cases through NCI-designated cancer centers with integrated CAR-T manufacturing partnerships.
United States
FDA breakthrough therapy designations compress bispecific antibody launch timelines, with academic medical centers in Boston and Houston restructuring pharmacy budgets to accommodate accelerated access. Medicare national coverage determinations for cellular therapies impose outcome-based payment conditions that reshape site-of-care economics. The Dana-Farber Cancer Institute and MD Anderson Cancer Center anchor CAR-T administration networks across the Northeast and Southwest corridors.
Germany
EMA priority medicines frameworks truncate conditional approval timelines, with university hospitals in Munich and Heidelberg piloting allogeneic donor-derived construct protocols. The German Federal Joint Committee (G-BA) early benefit assessments determine reimbursement rates for novel agents within six months of EMA authorization. The Rhine-Ruhr and Bavarian clusters concentrate hematology center capacity and molecular profiling infrastructure.
China
NMPA conditional approval pathways create parallel market access tracks for domestic bispecific antibody developers, with Shanghai and Beijing academic medical centers integrating next-generation sequencing panels into frontline decision algorithms. The National Reimbursement Drug List (NRDL) annual negotiation cycles determine patient access to premium therapeutics. The Yangtze River Delta anchors cellular therapy clinical trial density and contract manufacturing organization concentration.
Japan
PMDA sakigake designation accelerates priority review for lymphoma therapeutics demonstrating early efficacy signals, with Tokyo and Osaka hematology centers adopting subcutaneous bispecific antibody formats to reduce infusion chair requirements. The Central Social Insurance Medical Council (Chuikyo) pricing negotiations establish reimbursement ceilings that influence manufacturer launch sequencing. The Kanto and Kansai regions concentrate academic medical center capacity and companion diagnostic integration.
United Kingdom
NICE technology appraisals and the Cancer Drugs Fund create tiered access pathways, with London and Manchester hematology networks leveraging real-world evidence submissions to satisfy conditional approval requirements. The NHS England specialized commissioning framework concentrates CAR-T administration in designated supra-regional centers. The Greater London and Greater Manchester clusters anchor molecular profiling and cellular therapy referral infrastructure.
Non-Hodgkin Lymphoma Treatment Market Key Industry Players
On the supply side, the industry is consolidating around integrated diagnostic-therapeutic platforms, with manufacturers bundling companion diagnostics to control institutional procurement decisions. Large-cap pharmaceutical conglomerates and specialized biotechnology firms occupy distinct competitive tiers, with the former leveraging cell therapy infrastructure and the latter pursuing bispecific antibody engineering. Dominant competitive moves include strategic partnerships for vector manufacturing capacity and geographic expansion through regional licensing arrangements.
Within the integrated platform tier, Roche and Novartis AG exemplify diagnostic-therapeutic bundling strategies, while Bristol Myers Squibb anchors cell therapy infrastructure penetration across academic medical centers. These three entities represent contrasting archetypes: Swiss-based conglomerate with diagnostic dominance, Swiss-based pharmaceutical with gene therapy manufacturing scale, and US-based biopharmaceutical with hematology center network density.
| Leading Market Players |
|---|
| Roche |
| Novartis AG |
| Gilead Sciences |
| Bristol Myers Squibb |
| Takeda Pharmaceutical Company Limited |
| AstraZeneca |
| Janssen Pharmaceuticals |
| Bayer AG |
| Seagen Inc. |
| Others |
Cost & Logistics Intelligence
Vector manufacturing undercapacity across North American and European contract development organizations is compressing batch yields for lentiviral and gamma-retroviral constructs, forcing CAR-T sponsors to accept premium pricing for viral vector supply while locking in multi-year offtake agreements to secure manufacturing slots.
Pricing Analysis
Volume-discount tiering structures separate academic medical center consortia purchasing cellular therapies at scale from community oncology practices procuring oral oncolytics through specialty pharmacy networks. Price differentiation hinges on FDA breakthrough therapy designation status and companion diagnostic bundling. Cost compression in salvage chemotherapy regimens is intensifying because bispecific antibodies displace infusion-based protocols. Community oncology practices exhibit highest price sensitivity due to Medicare Part D reimbursement constraints, while academic centers with NCI designation absorb premium pricing for CAR-T access.
Supply Chain Analysis
Export-control regimes limiting flows of gene therapy manufacturing equipment and viral vector production technology constrain capacity expansion in jurisdictions outside the United States, Germany, and Switzerland. Supply concentrates in these three countries for clinical-grade plasmid DNA, specialized transfection reagents, and closed-system bioreactors. Raw material dependencies include fetal bovine serum, synthetic lipid nanoparticles, and cryopreservation media. Single-source vulnerability permeates lentiviral vector master cell bank supply. Distribution runs through limited specialty pharmacy networks for oral agents and hospital-based pharmacy procurement for cellular therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
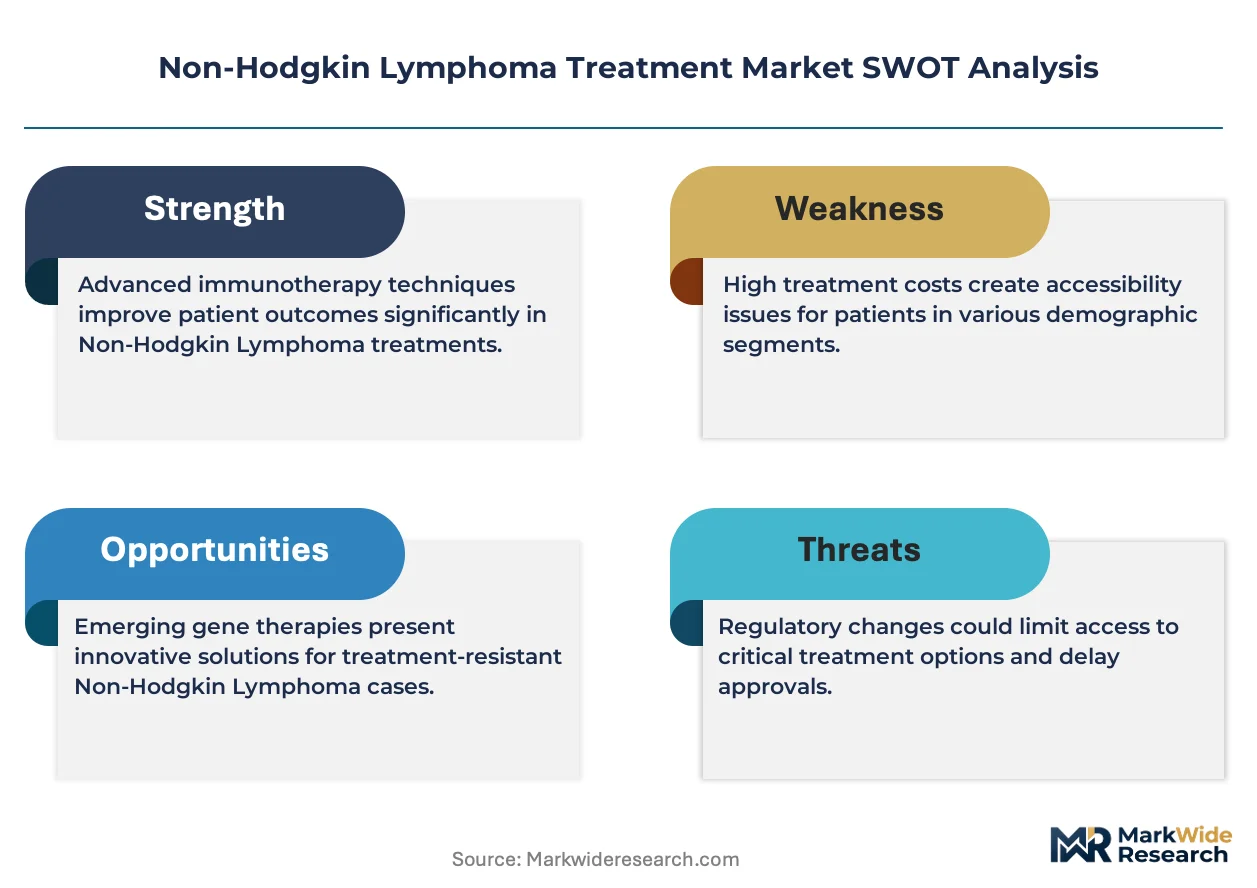
This market demands substitution defense as oral BTK and BCL-2 inhibitors displace hospital-based infusion revenue models, threatening incumbent positioning anchored in infusion center infrastructure.
For Market Incumbents: Insulate cellular therapy franchises through backward integration into viral vector manufacturing capacity in Germany and the United States, securing captive supply chains against CDMO allocation conflicts. Deepen formulary control via diagnostic-therapeutic bundling to defend against bispecific antibody entrants penetrating community settings. For New Entrants and Emerging Players: Establish a beachhead in allogeneic off-the-shelf platforms where autologous manufacturing bottlenecks create white-space opportunity. Target mantle cell lymphoma protocols in Germany and the United Kingdom where TP53 stratification demands novel therapeutic options. Pursue subcutaneous administration formats to reduce site-of-care barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bispecific antibody developers with extended half-life engineering and community oncology distribution partnerships. Long-term viability centers on platform technologies migrating beyond oncology into autoimmune applications. Monitor EMA adaptive pathway approval velocity as inflection indicator for European market access traction.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Viral vector capacity expansion in Germany and the United States secures supply for CD19-directed programs. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for bispecific antibody candidates. |
| Licensing Agreement | Companion diagnostic partnerships with Roche or Foundation Medicine control institutional procurement decisions. |
| Pipeline Diversification | T-cell engager expansion into mantle cell and follicular lymphoma segments broadens addressable populations. |
| Clinical Trial Advancement | Real-world evidence submissions through FDA Project Confirm satisfy post-marketing confirmatory requirements. |
Research Approach
A standing panel of drug development executives, formulary directors at NCI-designated cancer centers, payer access specialists, and hospital procurement managers provided ongoing calibration against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS national coverage determinations. Bottom-up patient-flow modeling triangulated with top-down pharmaceutical revenue segmentation.
Scenario-bracketing framed demand projections across treatment line, administration route, and regional regulatory cluster dimensions over the projection horizon. CAGRs derived from fitted growth curves anchored to approved therapy launch dates and reimbursement authorization timelines. Forecast inputs incorporated site-of-care migration rates and companion diagnostic adoption curves.
Sensitivities concentrate around CMS coverage determination reversals for cellular therapies and viral vector supply disruptions. Forecasts reflect assumptions regarding accelerated approval pathway continuity and manufacturing scale-up feasibility. Material shifts in FDA breakthrough therapy designation criteria or EMA adaptive pathway scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Hematopoietic Agents Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Blood Plasma Market
Hematology
Aplastic Anemia Treatment Market
Hematology
Hemoglobin Testing Systems Market
Hematology
Multiple Myeloma Therapeutics Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Sickle Cell Anemia Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Marginal Zone Lymphoma Treatment Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Hematologic Malignancies Market
Hematology
Langerhans Cell Histiocytosis Management Market
Hematology
Mantle Cell Lymphoma Treatment Market
Hematology
Multiple Myeloma Market