
 Polyamide 12 Powder for High-Performance 3D Printing Market | 2026-2036
Polyamide 12 Powder for High-Performance 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Polyamide 12 Powder for High-Performance 3D Printing Market Insights
Multi-source procurement for polyamide 12 powder is expanding as aerospace tier suppliers derisk supply chains. Evonik Industries leverages its backward integration into laurolactam monomer production to sustain cost advantages across European and North American markets. Arkema anchors its position through specialty polyamide chemistry expertise, while EOS GmbH dominates equipment-powder bundling strategies that lock in recurring material demand.
Polyamide 12 powder for high-performance 3D printing is a semi-crystalline thermoplastic with a melting point near 178°C, low moisture absorption, and excellent chemical resistance, engineered primarily for additive manufacturing processes requiring dimensional stability and mechanical durability in end-use parts. The standard grade segment leads volume due to its broad compatibility across selective laser sintering and multi jet fusion platforms, while glass bead reinforced formulations command premium positioning in aerospace components where stiffness-to-weight ratios determine qualification. Filled grades are gaining fastest in medical devices as biocompatibility certifications and sterilization tolerance become decisive procurement filters.
FDA material master files and EU MDR technical documentation requirements shape market access by mandating batch-level traceability and toxicological risk assessments for implant-contact applications. EPA air emissions standards for nylon production facilities influence capital allocation decisions for new powder manufacturing capacity. Stakeholders must monitor evolving ISO/ASTM additive manufacturing material standards and national aviation authority qualification pathways to anticipate which powder grades achieve production part approval.
Market Dynamics
Aerospace qualification pathways for flight-critical components are compressing development timelines while simultaneously tightening material traceability requirements, forcing powder suppliers to restructure batch documentation systems ahead of regulatory enforcement.
Growth Catalysts
- EU MDR Technical Documentation Mandates:Implant-contact applications now require toxicological risk assessments that only certified PA12 grades satisfy, filtering procurement toward qualified suppliers.
- Selective Laser Sintering Platform Expansion:Equipment installations in Germany, China, and the United States are creating captive demand for compatible powder formulations.
- Aerospace Lightweighting Imperatives:Stiffness-to-weight optimization in unmanned aerial systems and satellite structures is displacing machined aluminum in bracket and housing applications.
Market Restraints
- Laurolactam Monomer Concentration:European and Asian producers control upstream feedstock, exposing compounders to price volatility and supply interruption risks.
- FDA Master File Approval Timelines:Medical device manufacturers face 18-24 month certification delays that freeze procurement decisions and inventory planning.
- Recycled Powder Performance Degradation:Reused PA12 exhibits reduced elongation at break, limiting closed-loop economics and waste disposal cost recovery.
Strategic Opportunities
- India Medical Device Manufacturing:CDSCO regulatory harmonization with ISO 13485 standards is opening import pathways for biocompatible PA12 grades in orthopedic tooling.
- Glass Bead Reinforced Formulations:Aerospace structural applications requiring CTE matching with carbon fiber composites represent unmet specification demand.
- Multi Jet Fusion Platform Proliferation:HP's equipment licensing model is expanding addressable machine bases beyond laser-based systems into polymer powder bed fusion.
Industry Challenges
- Additive Manufacturing Process Engineering Talent:Powder bed fusion parameter optimization requires specialized expertise that outpaces university program output.
- Batch-to-Batch Consistency Verification:Melt flow rate and particle size distribution testing protocols lack harmonization across equipment OEM specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyamide 12 Powder for High-Performance 3D Printing Market |
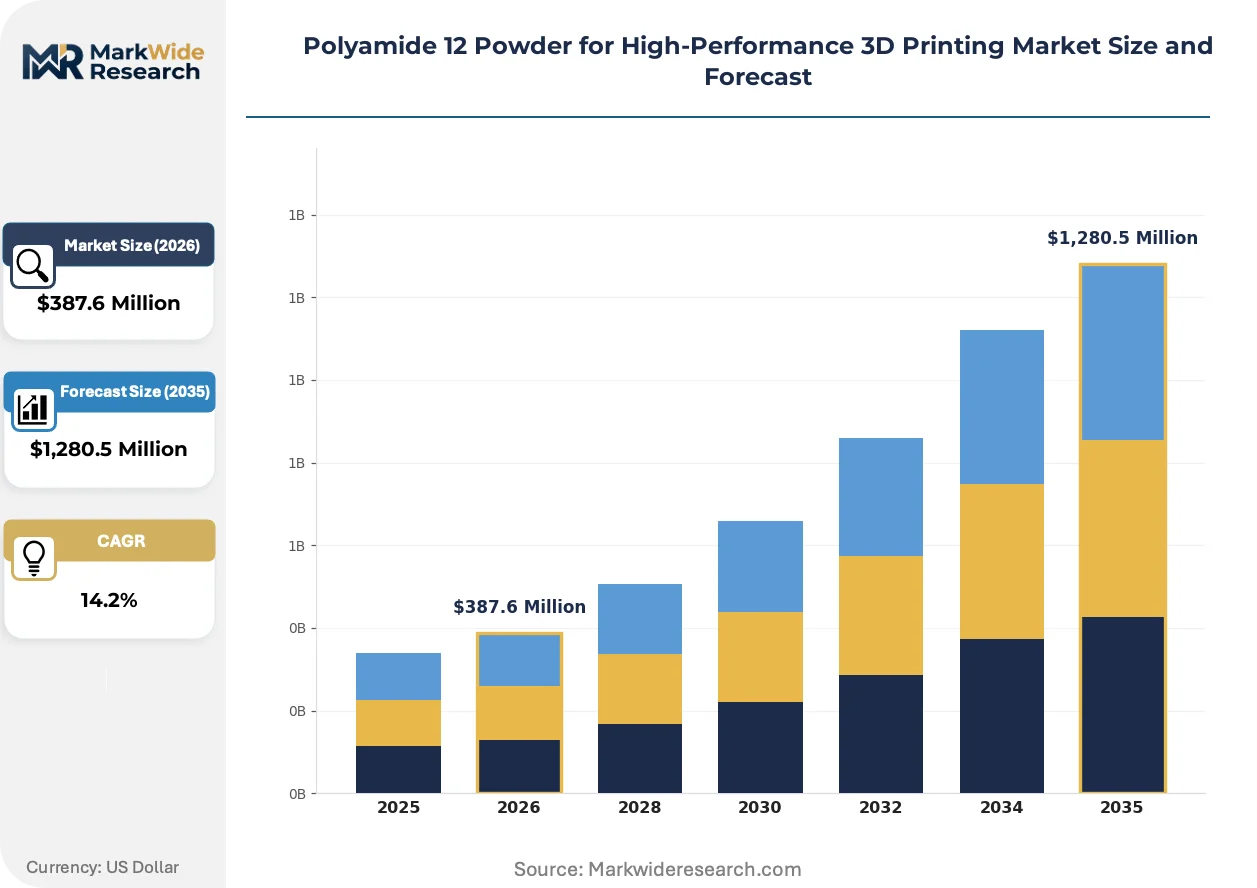
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, Filled Grade, Glass Bead Reinforced, Elastomer Modified, UV Stabilized Application: Aerospace Components, Consumer Goods, Industrial Prototyping, Medical Devices, Electronics Housings Technology: Selective Laser Sintering, Multi Jet Fusion, Binder Jetting, Electron Beam Melting, Digital Light Processing End User Industry: Aerospace Manufacturers, Consumer Product Developers, Industrial Fabricators, Medical Equipment Firms, Electronics Assemblers |
| Companies Covered | Evonik Industries, Arkema, EOS GmbH, HP, 3D Systems, Stratasys, Toray Industries, BASF, EMS-Chemie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyamide 12 Powder for High-Performance 3D Printing Market Trends and Innovations
Material qualification workflows and regulatory documentation systems are converging with production software platforms, compressing the gap between R&D formulation and manufacturing release.
Next-generation PA12 powder grades with embedded traceability markers are unifying quality assurance and supply chain authentication into single-scan verification systems. Aerospace tier suppliers in Germany and France are adopting these formulations to satisfy EASA production part approval requirements. This unification is eliminating redundant laboratory testing and accelerating lot release timelines from weeks to days.
REACH substance restriction proposals targeting nylon-12 precursor chemicals are forcing reformulation investments among European compounders. The ECHA regulatory trajectory threatens existing supply chains while creating first-mover advantages for bio-based laurolactam alternatives. Medical device exporters to the European Union are pre-emptively auditing material certificates to avoid customs detention.
Consolidated procurement contracts spanning powder, equipment, and post-processing services are displacing spot-market purchasing among high-volume aerospace manufacturers. Tier 1 suppliers in the United States and Germany are negotiating multi-year agreements that bundle material supply with machine utilization guarantees. This behavioral shift is concentrating demand among vertically integrated service bureaus and marginalizing independent powder distributors.
Polyamide 12 Powder for High-Performance 3D Printing Market Segmentation
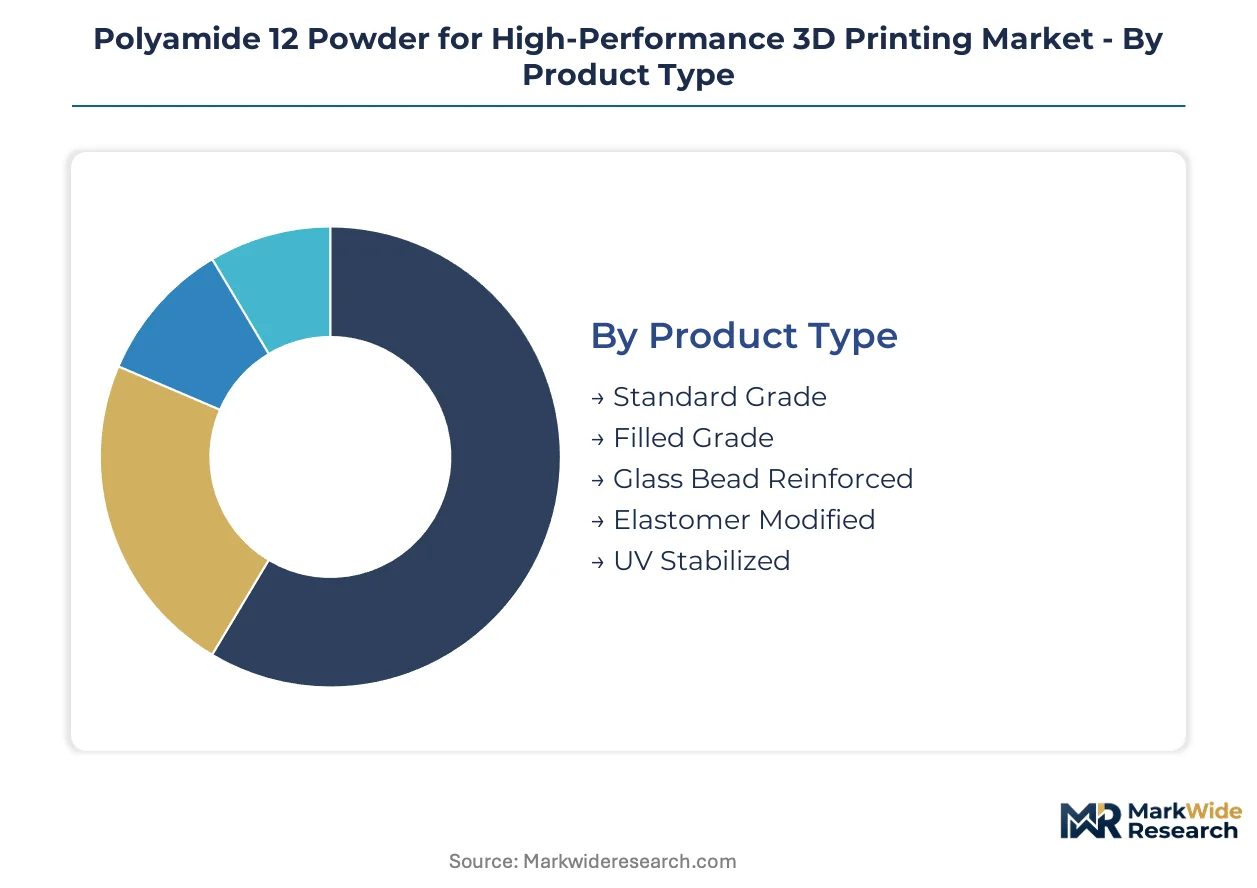
PA12 powder formulations diverge sharply between commodity prototyping runs and qualification-intensive production environments. Segment boundaries increasingly reflect certification thresholds rather than base chemistry alone.
Product Type:
Material integration depth separates standalone powder grades from those engineered for embedded traceability systems and regulatory documentation workflows.
- Standard Grade:Virgin polyamide 12 with controlled particle size distribution serves the bulk of selective laser sintering and multi jet fusion installations. Aerospace tier suppliers in Germany and the United States consume this grade for non-structural brackets and ducting where batch consistency outweighs mechanical enhancement.
- Glass Bead Reinforced:30-40% glass bead loading elevates stiffness-to-weight ratios and reduces coefficient of thermal expansion. Satellite manufacturers and unmanned aerial system producers specify this grade for carbon fiber composite mating surfaces where dimensional stability across temperature cycling determines qualification.
- Filled Grade:Mineral or carbon-based fillers target medical device tooling and surgical guides requiring sterilization tolerance.
- Elastomer Modified:Polyether block amide copolymerization delivers Shore D hardness flexibility for snap-fit enclosures and vibration-damping mounts.
- UV Stabilized:Hindered amine light stabilizer packages extend outdoor service life for drone housings and agricultural sensor enclosures.
Volume placements concentrate in Standard Grade; the faster expansion belongs to Glass Bead Reinforced.
Application:
Application tiering tracks the distance from functional prototype to flight-critical or implant-contact production part approval.
- Aerospace Components:Bracketry, ducting, and satellite structural elements demand EASA and FAA production part approval pathways. Powder suppliers must maintain batch-level traceability systems that satisfy NADCAP audit requirements for flight-critical hardware.
- Medical Devices:Surgical guides, orthopedic tooling, and implant-contact fixtures require FDA material master files and EU MDR technical documentation. CDSCO regulatory harmonization in India is opening import pathways for biocompatible grades in spinal fusion and joint replacement tooling.
- Consumer Goods:Eyewear frames, sporting equipment, and personalized accessories prioritize surface finish and colorability over mechanical certification.
- Industrial Prototyping:Functional validation models and assembly fixtures emphasize rapid turnaround and dimensional accuracy.
- Electronics Housings:EMI shielding integration and thermal management properties drive specification in 5G infrastructure and autonomous vehicle sensor enclosures.
Procurement volume clusters in Aerospace Components; Medical Devices are climbing the fastest.
Technology:
Technology segmentation reflects equipment OEM bundling strategies and parameter lock-in effects that shape powder formulation compatibility.
- Selective Laser Sintering:CO2 laser-based powder bed fusion dominates installed base in Germany, China, and the United States. EOS GmbH equipment-powder bundling creates captive demand for compatible formulations with tuned refresh ratios and thermal profiles.
- Multi Jet Fusion:HP's thermal inkjet-based system expands addressable machine bases through licensing models that lower capital barriers. Fusing agent chemistry requires powder surface energy matching distinct from laser-based systems.
- Binder Jetting:Liquid binder deposition enables higher build speeds for sand cores and metal infiltration precursors.
- Electron Beam Melting:Vacuum-based electron beam processing targets titanium and refractory metal applications with limited PA12 relevance.
- Digital Light Processing:Photopolymer vat polymerization sits outside powder bed fusion entirely.
Equipment concentration favors Selective Laser Sintering; Multi Jet Fusion is gaining share fastest.
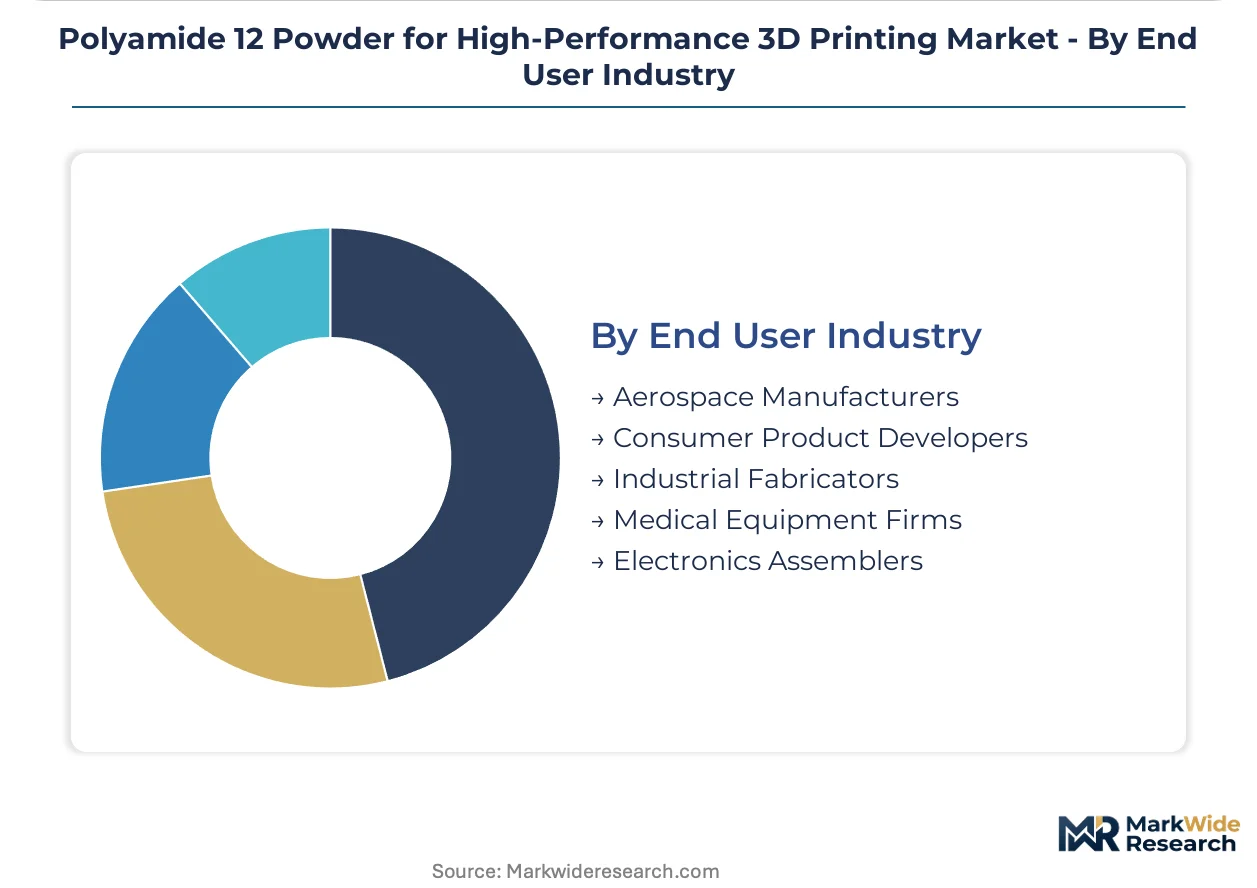
End User Industry:
Customer type segmentation distinguishes vertically integrated manufacturers from service bureau intermediaries and their respective procurement behaviors.
- Aerospace Manufacturers:Tier 1 suppliers in France, Germany, and the United States negotiate multi-year powder supply agreements bundled with machine utilization guarantees. Consolidated procurement contracts displace spot-market purchasing and marginalize independent distributors.
- Medical Equipment Firms:Orthopedic implant makers and surgical instrument producers demand toxicological risk assessments and sterilization validation data that filter procurement toward qualified suppliers with FDA master file holdings.
- Consumer Product Developers:Eyewear and sporting goods brands prioritize design iteration speed and surface aesthetics.
- Industrial Fabricators:Tooling and fixturing shops balance material cost against build success rates.
- Electronics Assemblers:5G infrastructure and automotive sensor producers specify dielectric properties and thermal conductivity.
Contract value concentrates in Aerospace Manufacturers; Medical Equipment Firms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Laurolactam monomer production clusters in Germany and China anchor geographic supply chains for polyamide 12 powder. Equipment density and regulatory stringency shape regional demand patterns.
United States
FAA production part approval pathways for flight-critical hardware drive aerospace procurement. EPA air emissions standards for nylon production facilities influence capital allocation for new powder manufacturing capacity. Tier 1 suppliers in Texas and California negotiate multi-year supply agreements bundling material with machine utilization guarantees.
Germany
EOS GmbH equipment-powder bundling creates captive demand for compatible formulations across selective laser sintering installations. REACH substance restriction proposals targeting nylon-12 precursor chemicals force reformulation investments among European compounders. The Bavarian cluster of powder bed fusion equipment makers and material compounders concentrates technical talent and batch documentation expertise.
China
MIIT industrial additive manufacturing development plans accelerate domestic equipment installations requiring compatible powder supply. GB standards for polymer materials shape certification requirements for medical and aerospace applications. The Yangtze River Delta hosts expanding service bureau capacity serving consumer goods and electronics prototyping demand.
India
CDSCO regulatory harmonization with ISO 13485 standards opens import pathways for biocompatible grades in orthopedic tooling. PLI scheme incentives for medical device manufacturing attract contract manufacturers establishing captive 3D printing operations. Maharashtra and Gujarat house emerging clusters of surgical instrument producers qualifying PA12 for sterilization-tolerant tooling.
France
EASA qualification requirements for satellite structural elements filter procurement toward batch-traceable powder grades. ANSM medical device regulations enforce toxicological risk assessment documentation for implant-contact applications. The aerospace tier supply chain around Toulouse adopts embedded traceability markers to satisfy production part approval timelines.
Polyamide 12 Powder for High-Performance 3D Printing Market Competitive Landscape
Capacity expansion dominates the current landscape as compounders add powder manufacturing lines ahead of regulatory enforcement deadlines. The vendor base separates into three tiers: integrated chemical conglomerates with monomer backward integration, equipment OEMs with captive material strategies, and independent specialty compounders. Strategic archetypes include upstream-integrated producers leveraging feedstock control, platform-locked suppliers bundling powder with machine sales, and certification-focused specialists serving medical and aerospace qualification pathways. M&A activity and strategic partnerships concentrate among equipment-powder bundling arrangements.
Within the upstream-integrated tier, Evonik Industries and Arkema exemplify producers with captive laurolactam supply chains. EOS GmbH anchors the equipment-powder bundling archetype through selective laser sintering platform lock-in. HP occupies a position bridging equipment licensing with material specification influence across multi jet fusion system proliferation.
| Leading Market Players |
|---|
| Evonik Industries |
| Arkema |
| EOS GmbH |
| HP |
| 3D Systems |
| Stratasys |
| Toray Industries |
| BASF |
| EMS-Chemie |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap compounders in Germany and Switzerland anchor powder supply networks, translating laurolactam cost volatility into disciplined pricing tiers that reward multi-year contract commitments from aerospace tier suppliers.
Pricing Analysis
Warranty and batch-traceability documentation are bundled into premium PA12 grades serving EASA and FAA qualification pathways, while standard formulations ship unbundled for prototyping applications. Three-tier pricing structure across aerospace-certified, medical-grade, and industrial-standard levels reflects certification investment recovery and toxicological assessment costs. Pricing pressure stems from REACH substance restriction proposals threatening existing feedstock chemistry, compressing margins for non-integrated compounders. Medical device manufacturers exhibit lowest price sensitivity due to FDA master file lock-in effects, whereas consumer goods prototypers drive spot-market discounting.
Supply Chain Analysis
Regional distribution centers in Ludwigshafen, Lyon, and Shanghai coordinate hub-and-spoke powder logistics to service selective laser sintering and multi jet fusion installations. Upstream supply draws from laurolactam monomer production concentrated in Germany, China, and Japan, with compounding capacity clustered around equipment OEM headquarters. Single-source vulnerability in bio-based feedstock alternatives threatens reformulation timelines as ECHA regulatory trajectories tighten. Distribution runs through vertically integrated service bureaus that bundle material with machine utilization guarantees, displacing independent powder traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance capabilities, with REACH enforcement and EU MDR documentation requirements forcing sub-scale compounders toward exit or acquisition.
For Market Incumbents: Lock in aerospace tier suppliers through multi-year powder-equipment bundling agreements that embed traceability markers satisfying NADCAP audit requirements. Expand backward integration into bio-based laurolactam alternatives ahead of ECHA substance restriction enforcement, securing first-mover positioning as European precursor chemistry faces reformulation mandates.
For New Entrants and Emerging Players: Begin with CDSCO-harmonized medical device tooling opportunities in Maharashtra and Gujarat, where PLI scheme incentives attract contract manufacturers lacking captive powder supply. Target orthopedic implant producers requiring sterilization-tolerant grades but underserved by incumbent certification backlogs, offering accelerated technical documentation support as differentiation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap compounders with FDA master file holdings and EASA qualification relationships in Southern Germany, where family ownership transitions create acquisition windows. Monitor ECHA regulatory publication timelines as inflection signals for bio-based feedstock substitution economics and stranded asset risk in conventional nylon-12 chemistry.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Laurolactam | Secures feedstock positioning ahead of REACH substance restrictions targeting conventional nylon-12 precursors. |
| Multi-Year Powder-Equipment Bundling Agreements | Locks in recurring demand from aerospace tier suppliers consolidating procurement around EOS GmbH platform ecosystems. |
| EU MDR Technical Documentation Investment | Opens implant-contact medical device pathways requiring toxicological risk assessments that filter procurement toward qualified suppliers. |
| Regional Distribution Center Expansion | Reduces logistics friction for multi jet fusion proliferation across HP licensing networks in Asia-Pacific manufacturing clusters. |
| Embedded Traceability Marker Development | Unifies quality assurance and supply chain authentication into single-scan verification systems satisfying EASA production part approval. |
Research Methodology
Multi-period observation of laurolactam contract pricing, equipment installation rates, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with powder compounding plant managers, aerospace tier supplier procurement leads, medical device regulatory affairs directors, and selective laser sintering platform engineers. Secondary validation drew from ECHA substance restriction proposals, FDA material master file databases, SEC filings of integrated chemical conglomerates, and customs trade data tracking PA12 powder shipments. Bottom-up segment sizing triangulated against top-down chemical industry capacity assessments.
Segment-weighting across product type, application tier, technology platform, and end-user industry shaped volume and value projections across the analysis window. Aerospace qualification pathways and medical certification timelines supplied industry-specific forecast inputs, with CAGRs derived from equipment installation forecasts and refresh ratio economics. Modeling incorporated powder bed fusion parameter lock-in effects and regulatory enforcement probability weightings.
Underlying measurement precision varies by segment; aerospace-certified and medical-grade categories carry tighter precision than industrial prototyping tiers due to visible contract documentation. Forecasts reflect assumptions around ECHA regulatory trajectory timing and equipment OEM bundling strategy continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
Rapid Prototyping Materials Market
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
3D Printing Polymers Market
3D Printing Materials
3D Printing Consumables Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
3D Printing Applications Polymers Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
Middle East 3D Printing Materials Market
3D Printing Materials
Graphene in 3D Printing Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
Global Metal Additive Manufacturing Market