
 Graphene in 3D Printing Market | 2026-2036
Graphene in 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Graphene in 3D Printing Market Analysis
High-purity monolayer graphene specification tiers is collapsing the cost barrier between laboratory prototyping and production-scale additive manufacturing. Graphene 3D Lab Inc. leverages proprietary filament extrusion methods to anchor North American supply chains for conductive printing materials. Nano Dimension Ltd. competes in printed electronics by integrating graphene inks into multi-material deposition systems. Haydale Graphene Industries PLC differentiates through plasma-functionalized graphene dispersions that sustain batch-to-batch conductivity consistency.
Graphene in 3D printing denotes the incorporation of atomically thin carbon allotropes—typically 1-10 layer thickness, 0.335 nm interlayer spacing—into thermoplastic binders, photopolymer resins, or metal powder matrices to enhance tensile strength, thermal conductivity, and electrical properties in additively manufactured parts. The primary commercial purpose centers on producing functional prototypes and end-use components that exceed baseline polymer performance without the weight penalty of traditional metal or continuous fiber reinforcement. Filament formulations currently lead volume shipments due to compatibility with existing Fused Deposition Modeling hardware installed across prototyping firms and educational entities. Aerospace and healthcare applications are expanding fastest as OEMs qualify graphene composites for non-critical flight hardware and biocompatible surgical guides respectively, while automotive consumer goods segments remain margin-constrained by certification timelines.
FDA device manufacturing standards and EPA chemical substance reporting requirements shape graphene loading thresholds and biocompatibility testing protocols for healthcare applications in the United States. REACH registration obligations and ECHA nanomaterial guidance in Europe impose pre-market toxicity documentation that filters out uncertified raw material suppliers. ISO/ASTM additive manufacturing quality frameworks provide the baseline process validation language that most industrial buyers require before qualifying new material vendors. Stakeholders must monitor evolving nanomaterial classification decisions by OECD member regulators, as reclassification would trigger additional safety data obligations across multiple jurisdictions simultaneously.
Market Dynamics
Aerospace OEMs are compressing qualification cycles for graphene-reinforced flight hardware, forcing filament suppliers to batch-certify conductivity consistency under FAA airworthiness protocols rather than prototype-grade tolerances.
Growth Catalysts
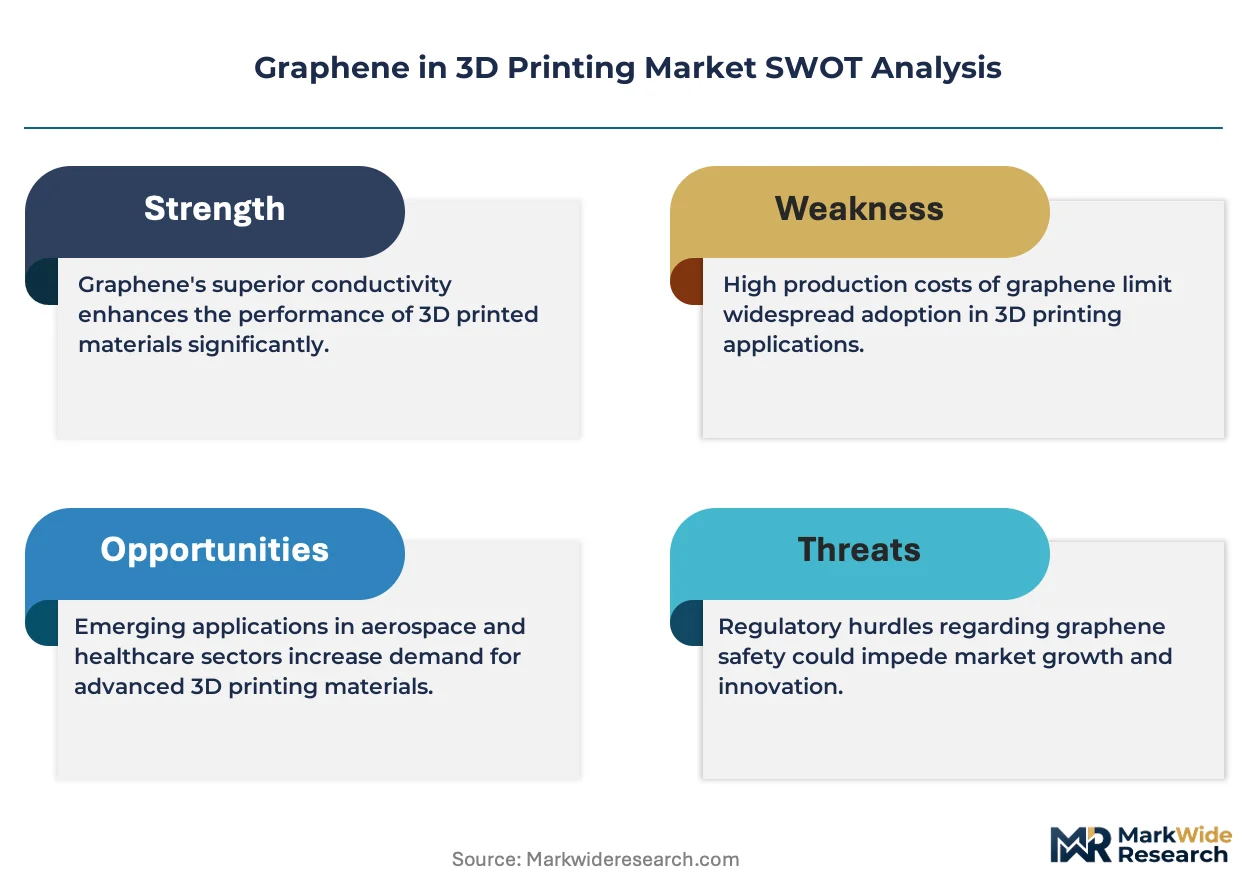
- REACH nanomaterial registration:ECHA pre-market toxicity documentation in Europe filters out uncertified raw material suppliers, creating captive demand for registered graphene dispersions among German industrial OEMs.
- Biocompatible surgical guide demand:Healthcare additive manufacturing is pulling plasma-functionalized graphene into photopolymer resins for patient-specific orthopedic tooling.
- Conductive tooling integration:Fused Deposition Modeling hardware installed across prototyping firms enables immediate filament adoption without capital equipment swaps.
Market Restraints
- Monolayer graphene input cost volatility:High-purity feedstock prices fluctuate with graphite electrode supply from Chinese mining concentrators.
- Batch-to-batch conductivity variance:Unfunctionalized graphene dispersion methods produce inconsistent electrical performance in multi-material deposition systems.
- Continuous fiber substitution threat:Carbon fiber-reinforced thermoplastics retain cost advantage in non-conductive structural lightweighting applications.
Strategic Opportunities
- Underpenetrated automotive certification:German Tier-1 suppliers lag aerospace in qualifying graphene composites for crash-critical components.
- CSRD material traceability mandates:EU corporate sustainability reporting requirements create premium pricing for supply-chain-documented graphene filament.
- Photopolymer-graphene convergence:Multi-material deposition systems integrating conductive inks with ceramic binders open ceramic matrix composite applications.
Industry Challenges
- Plasma functionalization technician scarcity:Specialized surface chemistry expertise required for dispersion stability sits concentrated in UK and German research clusters.
- ISO/ASTM process validation timelines:Industrial buyers demand 18-24 month qualification cycles before vendor approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphene in 3D Printing Market |
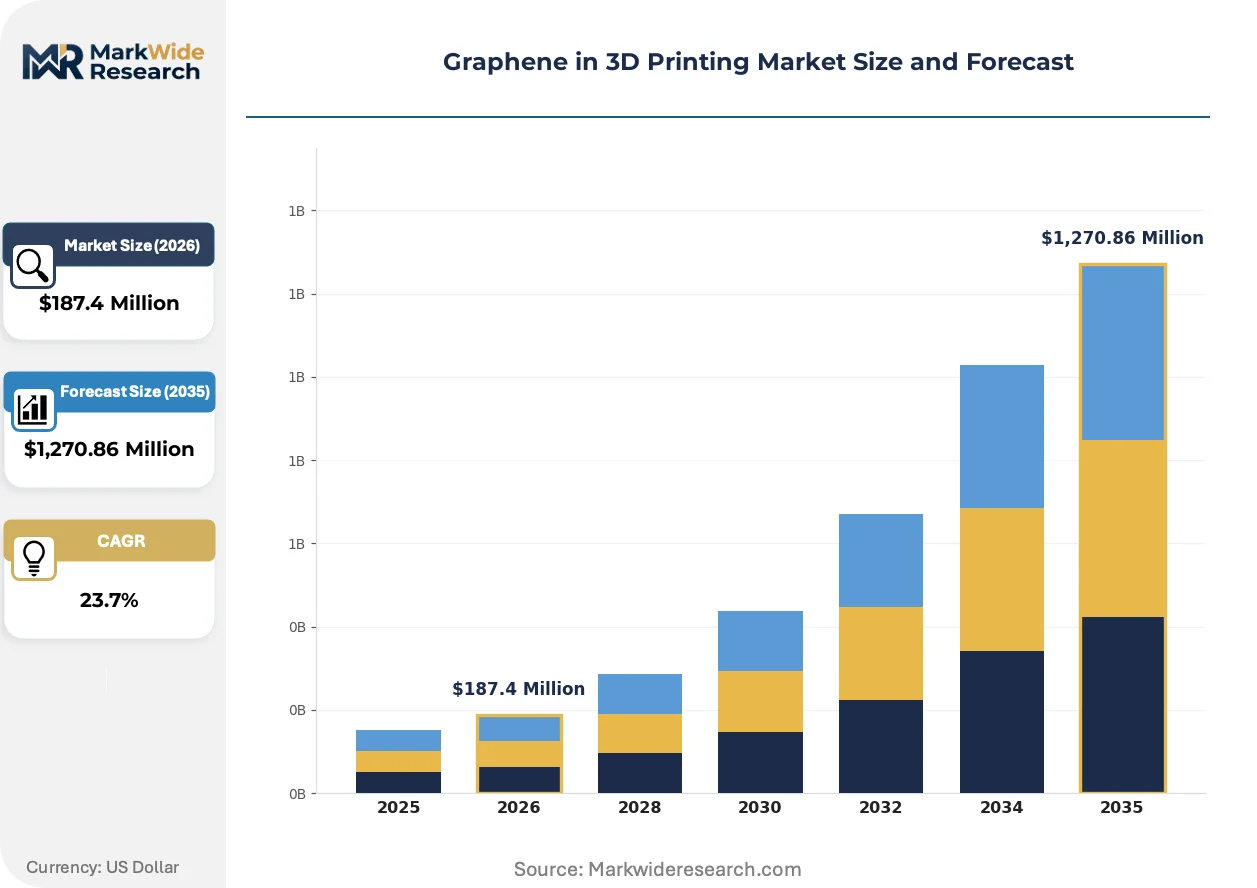
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filaments, Powders, Composites, Coatings Application: Aerospace, Automotive, Healthcare, Consumer Goods End User: OEMs, Prototyping Firms, Research Institutions, Educational Entities Technology: Fused Deposition Modeling, Selective Laser Sintering, Stereo Lithography, Binder Jetting |
| Companies Covered | 3D Graphene Lab, Graphene 3D Lab Inc., Nano Dimension Ltd., XG Sciences, Inc., Graphmatech AB, Haydale Graphene Industries PLC, Versarien plc, Applied Graphene Materials plc, PMG 3D Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphene in 3D Printing Market Emerging Trajectories
Plasma surface modification and in-situ exfoliation methods are collapsing the performance gap between laboratory-grade graphene and production-scale additive manufacturing feedstock.
Multi-material deposition hardware is supplanting single-extruder FDM systems in aerospace prototyping facilities. Boeing and Airbus tier suppliers are trialing graphene-ink integration for embedded sensor pathways in non-critical flight hardware. This capability compression is eliminating the separate post-print electronics assembly step.
REACH registration obligations are reshaping raw material procurement patterns across European filament manufacturers. ECHA nanomaterial guidance forces pre-market toxicity documentation that disqualifies uncertified Asian feedstock suppliers. German industrial OEMs are consolidating purchases around ECHA-registered dispersion providers.
Certification-driven vendor consolidation is concentrating procurement authority among aerospace quality departments. Tier-1 suppliers are bypassing distributor channels for direct filament contracts with plasma-functionalization specialists. This channel compression is most visible in southern Germany's automotive-aerospace supplier corridor.
Graphene in 3D Printing Market Segmentation
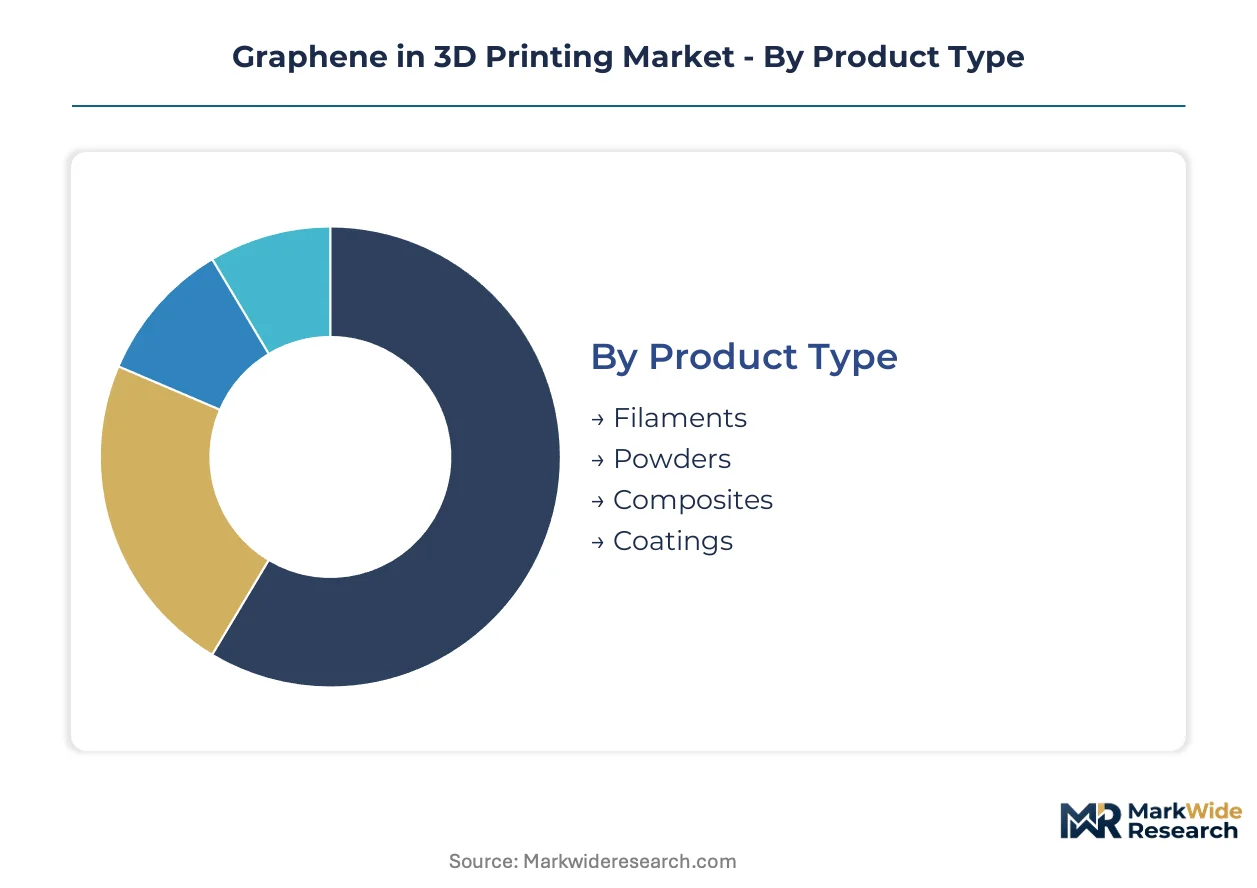
Segmentation in graphene 3D printing reflects divergent regulatory burdens and hardware compatibility constraints across material formats and deposition technologies. Buyers select product types based on existing capital equipment and end-use certification requirements rather than performance optimization alone.
Product Type:
REACH registration thresholds in Europe differentiate certified filaments from uncertified powders and dispersions, creating procurement friction for cross-border supply chains.
- Filaments:Thermoplastic binders loaded with 1-5 wt% graphene content extrude through standard FDM hardware without equipment modification. German automotive OEMs and prototyping firms in Stuttgart and Munich drive volume demand for conductive PLA and ABS formulations qualified under ISO/ASTM additive manufacturing frameworks.
- Powders:Graphene-coated metal and polymer powders enable selective laser sintering of electrically conductive structural components. Aerospace tier suppliers in Toulouse and Hamburg trial nickel-graphene and titanium-graphene matrices for non-critical flight hardware where weight reduction offsets powder handling complexity and ECHA nanomaterial documentation burdens.
- Composites:Pre-mixed graphene-resin systems target photopolymer and ceramic matrix applications requiring dispersion stability.
- Coatings:Post-print surface treatments deposit conductive graphene layers onto non-conductive substrates.
Established volume favors Filaments; emerging adoption favors Powders.
Application:
Margin structures collapse where certification timelines extend beyond 24 months, favoring applications with abbreviated qualification pathways.
- Aerospace:FAA airworthiness protocols and EASA certification requirements compress supplier margins while filtering out uncertified material vendors. Boeing and Airbus tier suppliers in Seattle, Toulouse, and Hamburg integrate graphene-reinforced components into non-critical flight hardware such as interior panels and sensor housings, bypassing crash-critical structural applications pending longer qualification cycles.
- Healthcare:FDA device manufacturing standards and EPA chemical substance reporting requirements impose biocompatibility testing protocols that favor plasma-functionalized graphene dispersions with documented surface chemistry. Patient-specific surgical guides and orthopedic tooling in Boston and Minneapolis medical device clusters pull graphene-loaded photopolymers through abbreviated 510(k) pathways.
- Automotive:Crash-critical component certification lags aerospace, constraining German Tier-1 supplier adoption.
- Consumer Goods:Margin pressure from Asian manufacturing competition limits graphene loading rates in mass-market products.
Revenue concentration sits with Aerospace; steepest expansion trajectory belongs to Healthcare.
End User:
Capital equipment ownership patterns determine addressable market boundaries for each user category.
- OEMs:In-house additive manufacturing departments at Siemens, BMW, and Airbus demand batch-certified conductivity consistency under vendor-managed inventory contracts. Direct filament procurement from plasma-functionalization specialists bypasses distributor markups in southern Germany's automotive-aerospace corridor.
- Prototyping Firms:Service bureaus in London, Chicago, and Singapore leverage existing FDM hardware for immediate graphene filament adoption without capital equipment swaps, though project-based revenue limits long-term material commitments.
- Research Institutions:University labs in Cambridge and Zurich drive specification development for next-generation dispersion methods.
- Educational Entities:Technical schools prioritize cost-minimized standard filaments over functionalized grades.
Procurement authority concentrates among OEMs; volume accessibility favors Prototyping Firms.
Technology:
Hardware installation bases and graphene compatibility constraints segment addressable demand.
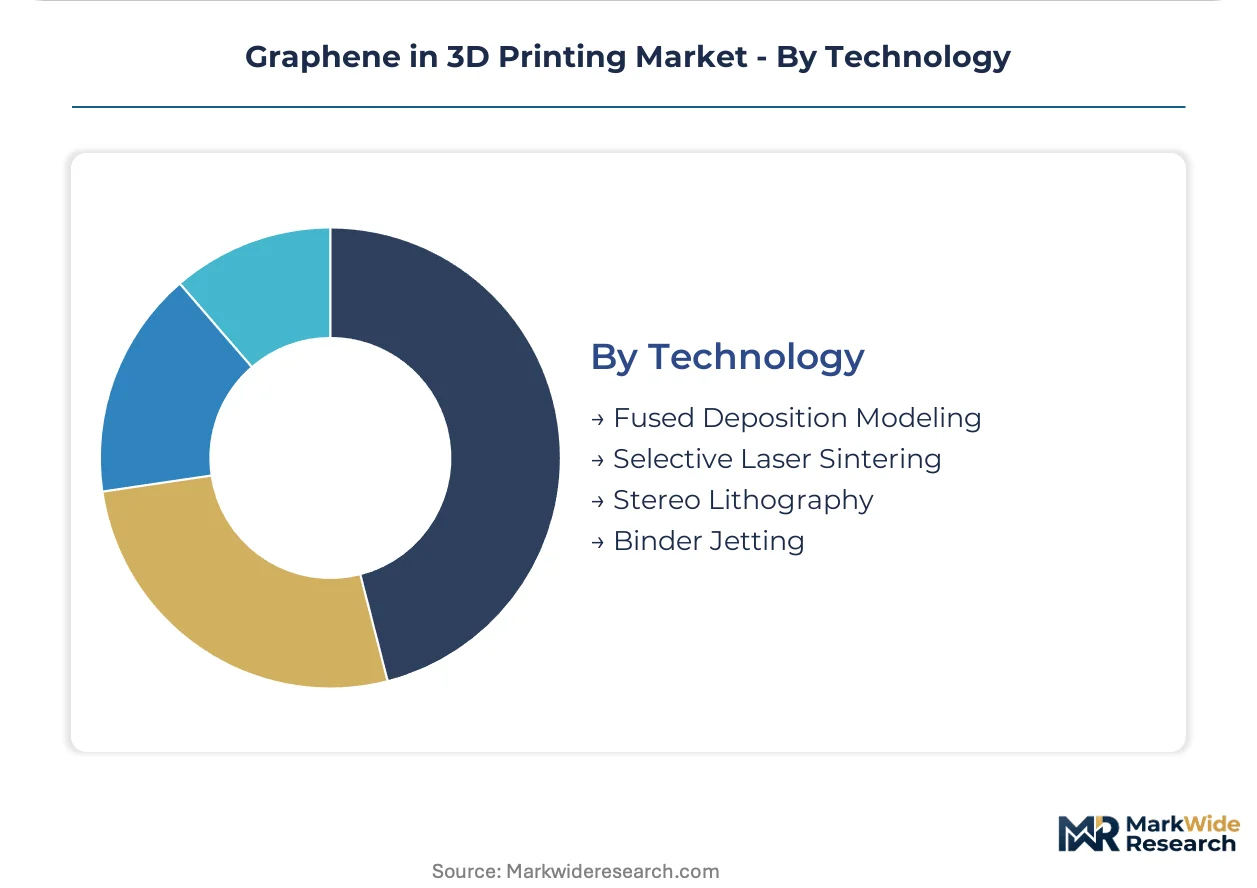
- Fused Deposition Modeling:Existing installed base across prototyping firms and educational entities enables immediate filament adoption. FDM systems dominate low-cost conductive printing despite layer-resolution limitations that exclude fine-pitch electronic applications.
- Selective Laser Sintering:Metal and polymer powder beds accommodate graphene-coated feedstock for structural lightweighting. SLS hardware scarcity and powder handling infrastructure requirements limit adoption to aerospace and automotive OEMs with captive equipment.
- Stereo Lithography:Photopolymer resin vats integrate graphene dispersions for high-resolution biomedical tooling.
- Binder Jetting:Ceramic and metal binder systems trial graphene-loaded binders for multi-material deposition.
Installed base favors Fused Deposition Modeling; capability expansion favors Selective Laser Sintering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Graphene 3D printing feedstock flows from Chinese graphite mining concentrators toward European filament manufacturers and North American prototyping hubs. Import dependency for high-purity monolayer graphene creates pricing volatility that shapes regional manufacturing strategies.
United States
FAA airworthiness protocols compress supplier qualification timelines for aerospace tier suppliers in Seattle and Wichita. EPA chemical substance reporting requirements under TSCA Section 8 impose graphene loading documentation burdens on Boston medical device clusters. Patient-specific surgical guide manufacturers in Minneapolis pull plasma-functionalized dispersions through abbreviated FDA 510(k) pathways.
Germany
REACH nanomaterial registration obligations filter procurement toward ECHA-registered dispersion providers serving Stuttgart automotive OEMs. CSRD material traceability mandates create premium pricing for supply-chain-documented filament. Southern Germany's automotive-aerospace supplier corridor concentrates direct procurement contracts with plasma-functionalization specialists bypassing distributor markups.
United Kingdom
Specialized surface chemistry expertise for dispersion stability concentrates in Cambridge and Oxford research clusters. UK Research and Innovation funding programs accelerate plasma functionalization method development for production-scale feedstock. Haydale Graphene Industries PLC anchors Welsh manufacturing capacity for batch-certified conductivity consistency.
China
Graphite electrode supply from domestic mining concentrators determines monolayer graphene input cost volatility for export markets. GB standards for nanomaterial classification shape pre-market documentation requirements for filament manufacturers in Shenzhen and Dongguan. Yangtze River Delta additive manufacturing clusters trial graphene-coated metal powders for selective laser sintering applications.
Japan
METI technology roadmaps prioritize conductive composite development for electronics miniaturization. JIS standards for additive manufacturing quality frameworks provide baseline process validation language for industrial buyers in Nagoya and Osaka. Kanto region prototyping firms leverage existing FDM hardware for immediate graphene filament adoption without capital equipment swaps.
Graphene in 3D Printing Market Vendor Landscape
Concentration sits with plasma-functionalization specialists that sustain batch-to-batch conductivity consistency under aerospace qualification protocols. The vendor base stratifies across three tiers: research-derived dispersion method holders, filament extrusion specialists with proprietary compounding techniques, and multi-material deposition system integrators. M&A activity targets plasma surface modification expertise concentrated in UK and German research clusters. Strategic partnerships between filament manufacturers and aerospace tier suppliers compress ISO/ASTM process validation timelines.
Within the functionalization-specialist tier, Haydale Graphene Industries PLC and Applied Graphene Materials PLC represent UK-based plasma surface modification expertise. Graphene 3D Lab Inc. exemplifies North American filament extrusion specialists with proprietary compounding methods. These three entities occupy positions across the value chain from raw dispersion stability through finished conductive filament production.
| Leading Market Players |
|---|
| 3D Graphene Lab |
| Graphene 3D Lab Inc. |
| Nano Dimension Ltd. |
| XG Sciences, Inc. |
| Graphmatech AB |
| Haydale Graphene Industries PLC |
| Versarien plc |
| Applied Graphene Materials plc |
| PMG 3D Technologies |
| Others |
Supply Flow & Price Mechanics
REACH nanomaterial registration gates both supply qualification and price differentiation simultaneously, filtering uncertified Asian feedstock out of European procurement while creating captive pricing power for ECHA-registered dispersion providers serving Stuttgart automotive OEMs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with plasma-functionalized graphene filaments commanding spreads over unfunctionalized grades due to batch-certified conductivity consistency under ISO/ASTM frameworks. Price differentiation rests on certification grade and volume scale, with aerospace tier suppliers least sensitive and educational entities most price-responsive. Cost compression in economy-tier standard filaments is intensifying because Asian manufacturing competition limits graphene loading rates in mass-market products.
Supply Chain Analysis
Just-in-time inventory preferences dominate prototyping firms and service bureaus, while aerospace OEMs maintain strategic stockpiles of batch-certified filament to buffer 18-24 month qualification timelines. Geographic supply concentration centers on China for graphite electrode feedstock, the United Kingdom for plasma functionalization expertise, and Germany for filament extrusion and compounding. Raw material dependencies include high-purity monolayer graphene from Chinese mining concentrators, thermoplastic binders from petrochemical suppliers, and proprietary dispersion stabilizers. Single-source vulnerability in Chinese graphite concentrate supply creates tariff exposure and commodity price volatility. Distribution runs through direct procurement contracts between plasma-functionalization specialists and Tier-1 aerospace suppliers, bypassing traditional distributor channels in southern Germany's automotive-aerospace corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by compressed aerospace qualification timelines, with OEMs now accelerating vendor consolidation after pandemic-era supply chain disruptions delayed material certification programs.
For Market Incumbents: Consolidate plasma functionalization capacity through selective acquisition of UK and German research-derived dispersion method holders to defend against continuous fiber-reinforced thermoplastic substitution threats. Deepen backward integration into graphite electrode supply relationships to buffer Chinese mining concentrator price volatility. Prioritize ISO/ASTM process validation investment to compress 18-24 month qualification cycles and lock out uncertified competitors from aerospace tier supplier vendor lists.
For New Entrants and Emerging Players: Differentiate on automotive crash-critical component certification, where German Tier-1 suppliers lag aerospace adoption and present underpenetrated white-space. Target patient-specific surgical guide applications in Boston and Minneapolis medical device clusters, where abbreviated FDA 510(k) pathways reduce barrier-to-entry versus aerospace qualification. Pursue a filament-extrusion-specialist positioning with proprietary compounding methods rather than competing directly against plasma-functionalization incumbents on dispersion chemistry.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with captive graphene dispersion capabilities but non-core additive manufacturing exposure, particularly European industrial materials parents. Five-to-ten year viability hinges on regulatory nanomaterial classification stability across OECD jurisdictions. Watch ECHA nanomaterial guidance evolution as the inflection signal — reclassification would trigger additional safety data obligations and consolidate procurement authority around registered providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Functionalization Capacity Expansion | Secures batch-to-batch conductivity consistency for Boeing and Airbus tier supplier contracts under FAA protocols. |
| REACH Registration Investment | Creates captive demand among German automotive OEMs by filtering uncertified Asian feedstock from procurement. |
| Direct Procurement Channel Development | Eliminates distributor markups in southern Germany's automotive-aerospace supplier corridor. |
| Photopolymer-Graphene Convergence R&D | Opens ceramic matrix composite applications through multi-material deposition system integration. |
| CSRD Material Traceability Compliance | Captures premium pricing from EU corporate sustainability reporting requirements for supply-chain-documented filament. |
Methodological Framework
Operator-level perspectives from filament extrusion specialists, plasma functionalization technicians, aerospace quality department procurement managers, and medical device regulatory affairs leads anchored the qualitative base. Primary interviews combined with secondary validation from ECHA nanomaterial registration databases, FDA 510(k) submission filings, ISO/ASTM additive manufacturing quality framework documentation, and customs trade data for graphite electrode imports. Bottom-up shipment volume analysis triangulated against top-down OEM procurement survey data.
Sensitivity analysis tested forecast robustness across the projection horizon by varying graphene loading rate assumptions, qualification timeline compression scenarios, and regulatory reclassification probabilities. Segmentation dimensions modeled include product format, application vertical, end-user category, and deposition technology, with additional granularity on certification tier and geographic regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns in adjacent advanced materials markets, calibrated against aerospace and healthcare OEM capex cycle indicators.
Material uncertainties — ECHA nanomaterial reclassification decisions, Chinese graphite concentrate export restrictions, and FAA airworthiness protocol amendments — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and supply chain continuity that may require reassessment. Revision becomes warranted when OECD nanomaterial classification harmonization crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
Vat Photopolymerization 3D Printing Technology Market
3D Printing Materials
3D Printing Plastics Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
Patterning Materials Market
3D Printing Materials
3D Printing Applications Polymers Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
3D Printing Polymers Market
3D Printing Materials
Global 3D Printing Filament Market
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Thermoformed Plastics for Printing Market